
 Global Gravure Printing Inks Market | 2026-2036
Global Gravure Printing Inks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gravure Printing Inks Market Foresight
ISO 2846-1 colorimetric compliance is unwinding supplier eligibility across the gravure inks value chain. Sun Chemical leverages captive resin manufacturing across Europe and Asia to sustain formulation consistency at scale. DIC Corporation anchors its position through deep backward integration into organic pigment synthesis. Sakata INX Corporation specializes in high-speed publication inks, occupying a defensible niche where solvent recovery economics favor regional production.
Gravure printing inks are liquid formulations engineered for transfer from an engraved copper or chrome cylinder to film, paper, or foil substrates at speeds exceeding 300 meters per minute, with viscosity typically controlled between 20 and 100 centipoise through solvent or water dilution. The primary commercial purpose centers on high-volume, repeatable decoration of packaging and publications where image fidelity and color density must survive lamination, heat sealing, or outdoor exposure. Solvent-based inks still dominate flexible packaging for snack and confectionery films where adhesion to treated polyolefin substrates remains unmatched, though water-based systems are capturing share in corrugated pre-print and paperboard folding carton applications. UV-curable formulations command premium positioning in security printing and decorative labels where instant drying eliminates set-off and enables inline finishing.
EPA Method 24 VOC testing in the United States, REACH substance restrictions administered by ECHA in Europe, and China's GB standards on packaging pollutant limits are collectively forcing reformulation investment and reshaping raw material sourcing. The EU F-Gas Regulation and state-level air quality rules in California and Gujarat add layered compliance costs that favor suppliers with multi-regional technical service laboratories. Stakeholders must monitor regulatory divergence between jurisdictions to decide whether to standardize formulations globally or tolerate SKU proliferation across regional plants.
Market Dynamics
The gravure inks market is being fundamentally restructured by solvent-to-water formulation migration, as converters in Vietnam, Indonesia, and India face tightening food-contact compliance mandates that render legacy solvent systems operationally stranded.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving SVHC list is forcing European converters to validate alternative chemistries, creating certified-supplier preference windows for compliant ink manufacturers with in-house resin capabilities.
- Flexible packaging investment:Southeast Asian snack and confectionery producers are commissioning new gravure lines at rates exceeding Western replacement cycles, pulling ink demand toward high-volume solvent formulations.
- Energy-curable technology maturation:UV and LED-curable systems are achieving adhesion benchmarks on treated polyolefins previously reserved for solvent inks, enabling instant-drying workflows in security printing and decorative label segments.
Market Restraints
- Nitrocellulose resin concentration:Supply of this critical film-forming polymer concentrates among Chinese and European chemical producers, exposing formulators to input volatility and qualification delays.
- China's GB standards enforcement:MEE inspections of packaging pollutant limits are disrupting regional production schedules and forcing emergency reformulation cycles without guaranteed technical success.
- Digital printing substitution:Inkjet and toner systems are capturing short-run flexible packaging jobs where gravure cylinder costs and lead times prove prohibitive for sub-10,000 meter runs.
Strategic Opportunities
- India's PLI scheme for packaging:Government production-linked incentives for domestic manufacturing are attracting multinational converters seeking tariff-advantaged export platforms to Middle East and African markets.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases used in solvent recovery systems are creating retrofit demand for carbon adsorption and thermal oxidation alternatives that favor specialized ink chemistry partnerships.
- E-commerce corrugated pre-print:Water-based gravure systems are penetrating Amazon and Flipkart supplier networks for high-graphic shipping boxes, displacing flexo in premium unboxing experience segments.
Industry Challenges
- Colorimetric certification timelines:ISO 2846-1 compliance verification for new pigment batches extends supplier qualification cycles by 4-6 months, compressing product launch windows for seasonal packaging programs.
- Legacy cylinder inventory stranding:Converters with extensive engraved copper cylinder libraries face write-down pressure as shorter run lengths and design refresh cycles reduce amortization feasibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gravure Printing Inks Market |
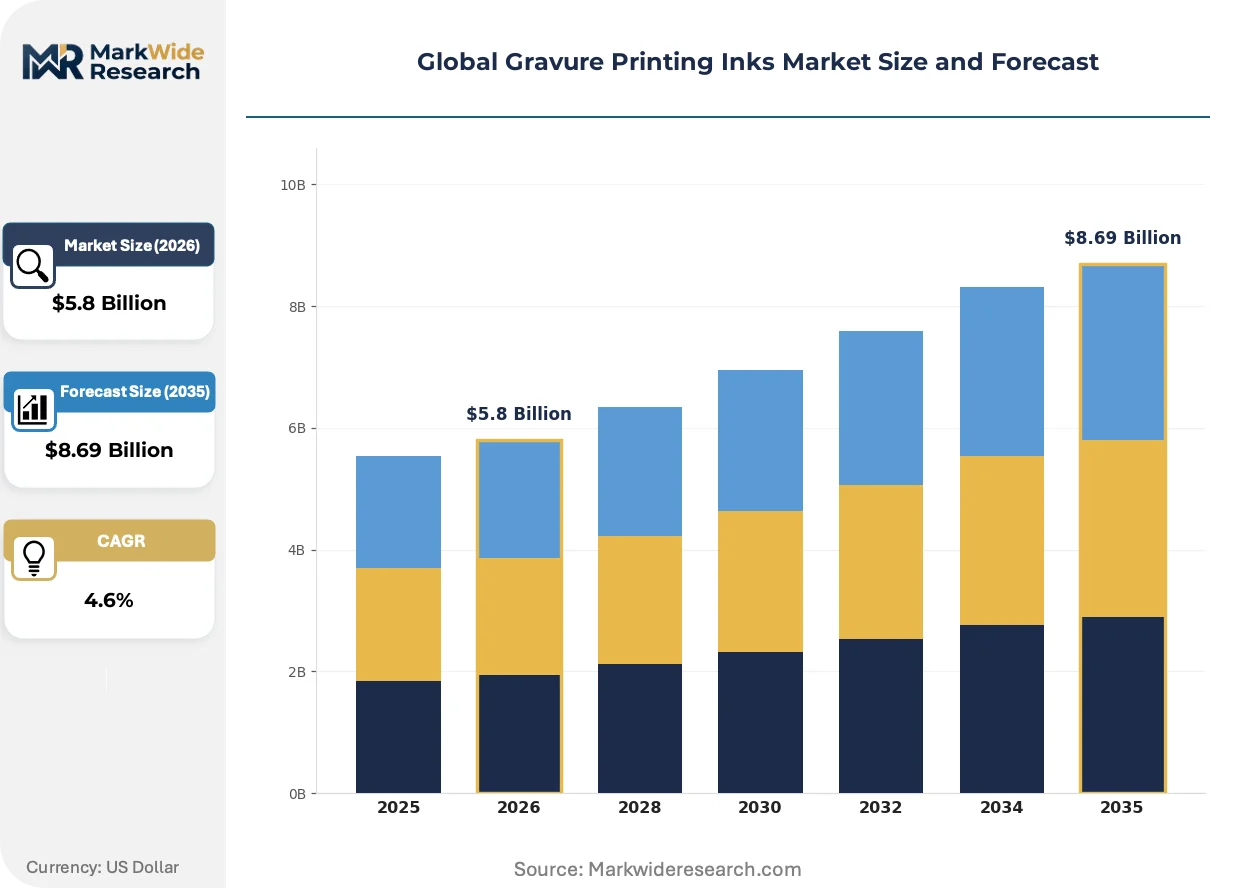
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $8.69 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ink Type: SOLVENT-BASED, WATER-BASED, UV-CURABLE, OIL-BASED, ENERGY CURABLE Printing Material: FILM, PAPER, FOIL, CARDBOARD, TEXTILES Application: PACKAGING, PUBLICATIONS, LABELS, DECORATIVE PRINTING, SECURITY PRINTING End User: PACKAGING MANUFACTURERS, PUBLISHERS, LABEL PRODUCERS, ADVERTISING AGENCIES, TEXTILE CONVERTERS |
| Companies Covered | Sakata INX Corporation, Sun Chemical, DIC Corporation, Dainichiseika Color & Chemicals Mfg. Co., Ltd., Toyo Ink SC Holdings Co., Ltd., Flint Group, hubergroup Deutschland GmbH, Tokyo Printing Ink MFG Co. Ltd., Siegwerk Druckfarben AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gravure Printing Inks Market Shifts & Advancements
Formulation chemistry, regulatory enforcement modalities, and procurement governance are simultaneously evolving, with water-based systems, digital workflow integration, and sustainability verification protocols converging to redefine supplier selection criteria.
Electron beam (EB) curable ink technology is supplanting thermal drying systems in high-end flexible packaging applications where heat-sensitive films and metallic substrates dominate. Italian and German converters serving luxury confectionery brands are adopting EB lines at replacement rates exceeding 15% annually for new capacity. This shift is compressing the addressable market for conventional solvent recovery infrastructure while elevating capital barriers to ink supplier participation.
China's GB standards on packaging pollutants, administered by MEE with provincial-level enforcement intensifying in Guangdong and Zhejiang, are disqualifying legacy solvent formulations from food-contact applications. Domestic ink producers are accelerating water-based and high-solid solvent development to retain converter relationships. The corrugated pre-print and paperboard folding carton segments are experiencing the most acute compliance-driven product switches, with multinational brand owners auditing supplier certificates before contract renewal.
Brand-owner sustainability scorecards are displacing pure unit-cost procurement in flexible packaging converter selection across North American and European markets. Unilever, Nestlé, and PepsiCo are embedding Scope 3 emissions tracking into ink supplier evaluations, favoring regional producers with verified renewable energy certificates and closed-loop solvent management. This behavioral pivot is most visible in California and the Netherlands, where state-level climate disclosure rules and the EU CSRD are mandating supply chain emissions transparency.
Global Gravure Printing Inks Market Segmentation
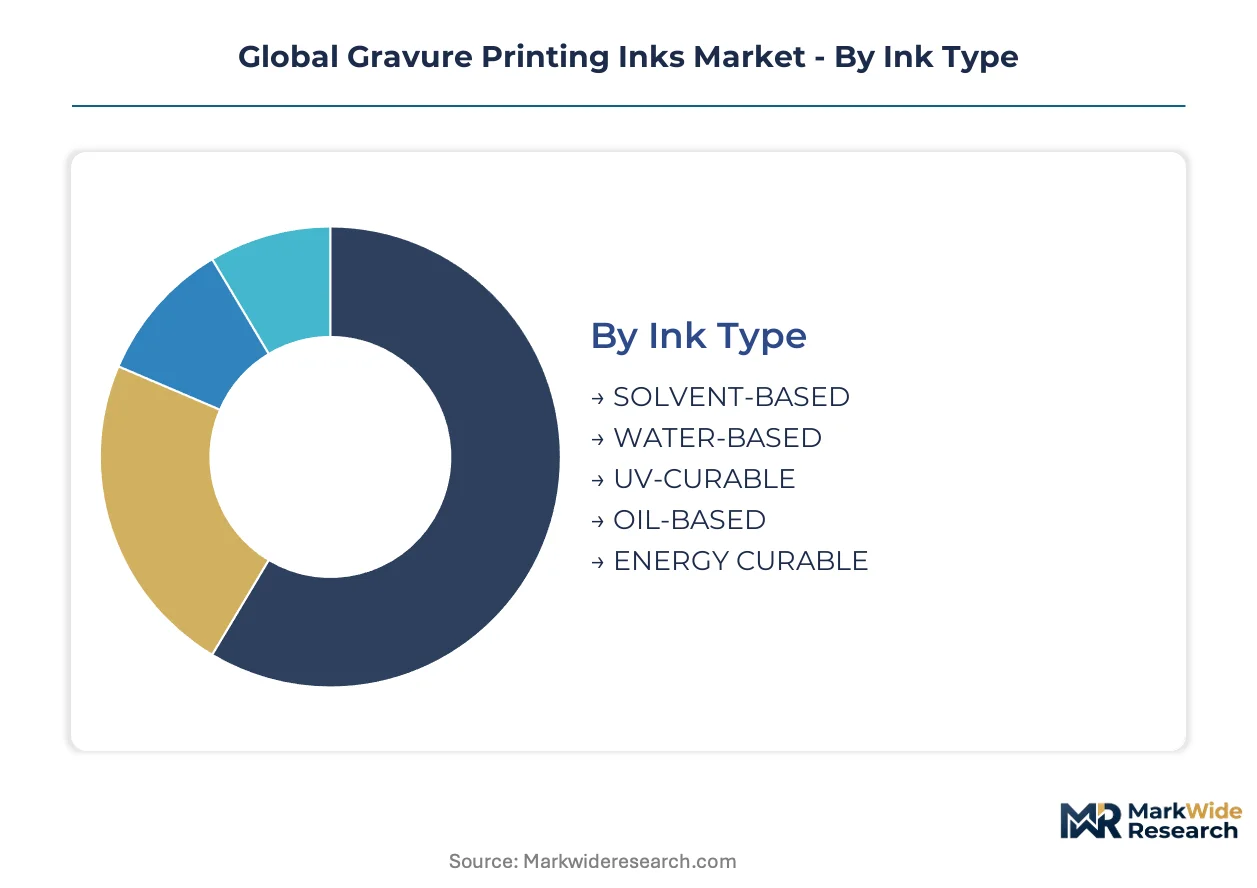
Gravure ink formulation choices directly determine regulatory compliance pathways and capital equipment requirements for converters. Each segmentation dimension carries distinct margin profiles, technical service demands, and geographic concentration patterns that shape supplier strategy.
Ink Type:
REACH substance restrictions, EPA Method 24 VOC thresholds, and China's GB standards on packaging pollutants are fragmenting formulation strategies across regulatory jurisdictions.
- SOLVENT-BASED:Nitrocellulose and polyurethane resin systems deliver unmatched adhesion to treated polyolefin films at speeds exceeding 300 meters per minute. Demand concentrates in Vietnam, Indonesia, and India where snack and confectionery packaging investment outpaces Western replacement cycles, though MEE inspections are forcing emergency reformulation.
- WATER-BASED:Acrylic and polyurethane dispersions eliminate VOC emissions but require longer drying tunnels and infrared heating systems. Corrugated pre-print for Amazon and Flipkart supplier networks in India and China is absorbing capacity as brand owners audit sustainability certificates before contract renewal.
- UV-CURABLE:Photoinitiator-acrylate systems enable instant drying on heat-sensitive films and metallic substrates for security printing and decorative labels.
- OIL-BASED:Mineral oil and vegetable oil vehicles serve publication gravure where odor neutrality and rub resistance dominate specifications.
- ENERGY CURABLE:Electron beam formulations bypass photoinitiator migration concerns for food-contact flexible packaging in luxury confectionery segments.
Solvent-based formulations handle the majority of throughput; water-based systems are gaining share fastest amid regulatory enforcement intensification.
Printing Material:
Substrate selection dictates cylinder engraving depth, doctor blade pressure settings, and drying system configuration for converter capital planning.
- FILM:BOPP, PET, and nylon substrates require surface tension treatment above 38 dynes for solvent ink wetting and lamination bond strength. Flexible packaging converters in Southeast Asia are expanding gravure capacity specifically for multilayer snack films where heat seal integrity must survive distribution chain stress.
- PAPER:Coated and uncoated woodfree stocks absorb water-based systems for publication and corrugated pre-print applications where fiber swelling control determines print fidelity.
- FOIL:Aluminum and metallized substrates demand low-heat curing to prevent oxidation and delamination in pharmaceutical blister packs.
- CARDBOARD:Recycled fiber content in folding cartons creates variable absorbency that challenges ink mileage consistency.
- TEXTILES:Synthetic and natural fabrics require specialized rheology for rotary screen gravure hybrids in transfer printing applications.
Film substrates absorb the highest ink volumes per installed gravure line; cardboard is climbing fastest as e-commerce corrugated pre-print displaces flexo in premium unboxing segments.
Application:
End-use specifications determine whether converters prioritize colorimetric compliance, tamper evidence, or production speed in supplier selection.
- PACKAGING:Food-contact compliance mandates from FDA, EFSA, and China's SAMR dominate formulation validation cycles. Flexible packaging for snacks, confectionery, and ready-to-eat meals commands the largest ink volumes, with ISO 2846-1 colorimetric certification extending supplier qualification timelines.
- PUBLICATIONS:Catalogs, magazines, and inserts prioritize low-grammage paper compatibility and odor neutrality for mail distribution.
- LABELS:Pressure-sensitive and shrink-sleeve applications require instant-drying UV systems to eliminate set-off during inline die-cutting.
- DECORATIVE PRINTING:Wallpaper, flooring, and furniture films demand lightfastness ratings above Blue Wool Scale 6 for residential durability.
- SECURITY PRINTING:Banknotes, passports, and tax stamps require specialized pigments with magnetic, infrared, or ultraviolet authentication features subject to national mint procurement controls.
Packaging commands the dominant share of formulation development resources; security printing maintains the steepest expansion trajectory as government identity document modernization accelerates.
End User:
Procurement governance models diverge sharply between multinational brand owners with sustainability scorecards and regional converters optimizing unit economics.
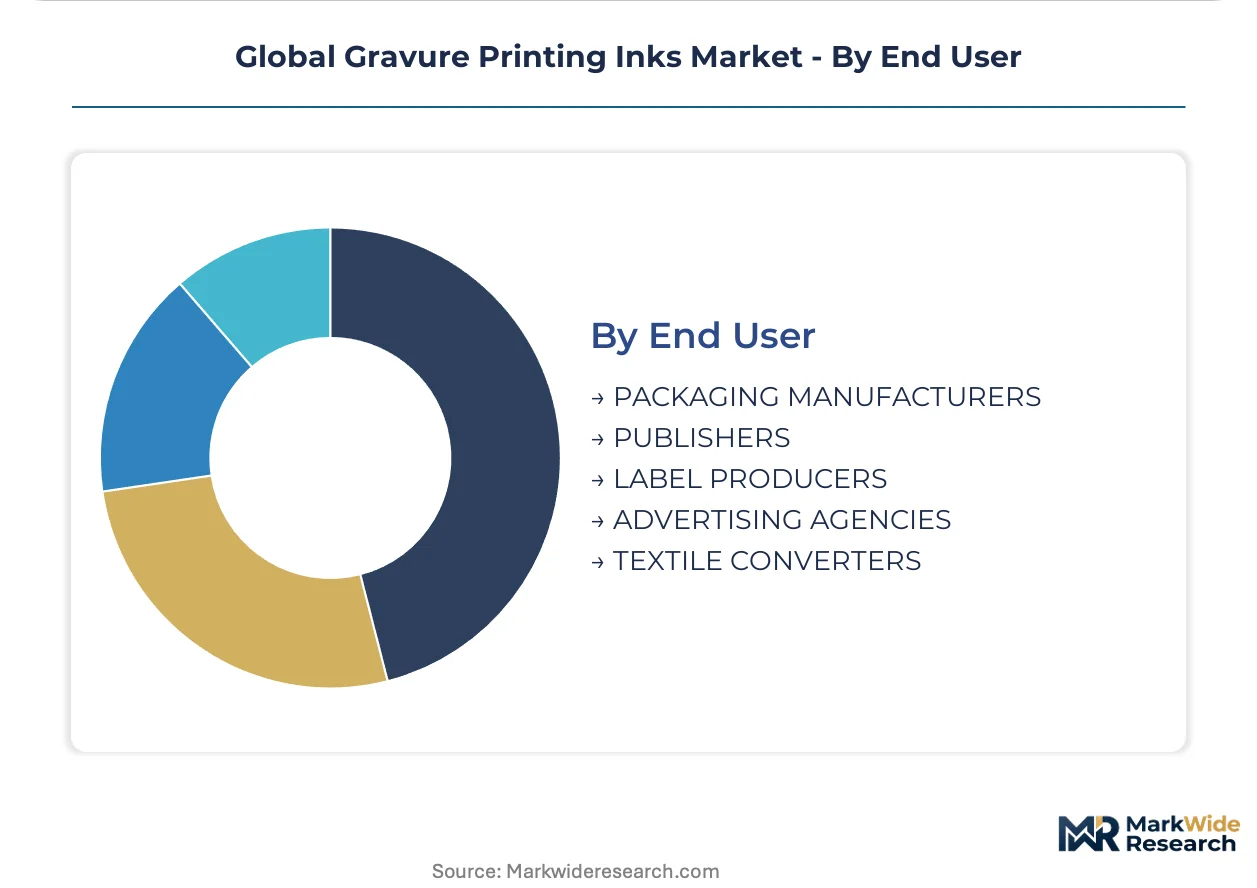
- PACKAGING MANUFACTURERS:Integrated converters serving Unilever, Nestlé, and PepsiCo are embedding Scope 3 emissions tracking into ink supplier evaluations, favoring regional producers with verified renewable energy certificates in California and the Netherlands.
- PUBLISHERS:Magazine and catalog printers face digital substitution pressure, consolidating print volumes among fewer gravure-equipped facilities.
- LABEL PRODUCERS:Narrow-web converters are adopting UV-LED curing to reduce energy consumption and substrate heat exposure.
- ADVERTISING AGENCIES:Point-of-sale and promotional material printers prioritize short-run flexibility where digital systems compete for sub-10,000 meter jobs.
- TEXTILE CONVERTERS:Transfer printing operations in Turkey and Italy are migrating from rotary screen to gravure cylinder systems for finer halftone reproduction.
Packaging manufacturers drive the majority of technical service laboratory investment; label producers are expanding most quickly as beverage and personal care SKU proliferation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government production-linked incentives and tightening food-contact mandates are redirecting packaging investment toward India and Southeast Asia, while European and Chinese environmental enforcement accelerates formulation migration from solvent-based systems.
China
Flexible packaging converters in Guangdong and Zhejiang provinces face intensified MEE inspections under GB standards for packaging pollutants. Domestic ink producers are accelerating water-based and high-solid solvent development to retain converter relationships. The Pearl River Delta industrial cluster is experiencing acute compliance-driven product switches in corrugated pre-print and paperboard folding carton segments.
India
The PLI scheme for packaging manufacturing is attracting multinational converters seeking tariff-advantaged export platforms to Middle East and African markets. Maharashtra and Gujarat host expanding gravure capacity as snack and confectionery producers commission new lines. Water-based gravure systems are penetrating Amazon and Flipkart supplier networks for high-graphic e-commerce shipping boxes.
Vietnam
Snack and confectionery packaging investment is outpacing Western replacement cycles, pulling ink demand toward high-volume solvent formulations. Ho Chi Minh City industrial zones are absorbing new gravure line installations as regional brand owners consolidate Southeast Asian production. FSSAI-equivalent food-contact compliance rules are tightening, rendering legacy solvent systems operationally stranded.
Germany
ECHA's evolving SVHC list under REACH is forcing converters to validate alternative chemistries, creating certified-supplier preference windows for compliant ink manufacturers. Bavarian and North Rhine-Westphalian converters serving luxury confectionery brands are adopting electron beam curable lines at replacement rates exceeding 15 percent annually. EU F-Gas Regulation restrictions on fluorinated greenhouse gases are creating retrofit demand for carbon adsorption alternatives.
United States
EPA Method 24 VOC testing and California state-level air quality rules are adding layered compliance costs that favor suppliers with multi-regional technical service laboratories. Midwest flexible packaging hubs are embedding Scope 3 emissions tracking into ink supplier evaluations under brand-owner sustainability scorecards. Security printing demand for government identity document modernization is accelerating in the Washington D.C. corridor.
Global Gravure Printing Inks Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with captive resin and pigment capabilities, supplemented by specialized ink formulators with regional technical service depth. The vendor base concentrates among Japanese and European chemical groups with backward integration into organic pigment synthesis and nitrocellulose resin supply. Two strategic archetypes dominate: integrated pigment-to-ink manufacturers sustaining formulation consistency at scale, and niche specialists occupying defensible positions in high-speed publication or security printing segments. Competitive moves center on multi-regional laboratory expansion for regulatory compliance support and emergency reformulation partnerships with converters facing inspection-driven disruption.
Within the integrated chemical conglomerate tier, DIC Corporation and Sun Chemical exemplify archetypes with upstream control over critical raw materials. Sakata INX Corporation occupies a position representing specialized publication ink expertise where solvent recovery economics favor regional production. Among European-based formulators, Siegwerk Druckfarben AG & Co. KGaA and hubergroup Deutschland GmbH sit within the mid-scale technical service tier serving brand-owner sustainability audit requirements.
| Leading Market Players |
|---|
| Sakata INX Corporation |
| Sun Chemical |
| DIC Corporation |
| Dainichiseika Color & Chemicals Mfg. Co., Ltd. |
| Toyo Ink SC Holdings Co., Ltd. |
| Flint Group |
| hubergroup Deutschland GmbH |
| Tokyo Printing Ink MFG Co. Ltd. |
| Siegwerk Druckfarben AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
ISO 2846-1 colorimetric compliance gates supplier eligibility and simultaneously stratifies price premiums across formulation tiers, forcing converters to absorb longer qualification timelines or pay expedited certification surcharges. Buyers with cylinder libraries already amortized face steeper effective costs when switching suppliers than greenfield entrants, embedding pricing power with incumbent pigment manufacturers.
Pricing Analysis
Cost-plus contracts with nitrocellulose resin indexation dominate solvent-based formulations, tying ink prices to Chinese and European petrochemical feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels separates energy-curable security inks from water-based corrugated grades and commodity solvent packaging formulations. Pricing pressure stems from digital printing substitution in sub-10,000 meter runs, where cylinder engraving costs render gravure uncompetitive. Regional converters in Vietnam and Indonesia exhibit highest price sensitivity due to thin margin structures, while luxury confectionery brand owners in Germany and Italy tolerate premium EB-curable pricing for food-contact compliance.
Supply Chain Analysis
Inventory cycles for nitrocellulose resin extend qualification timelines, forcing formulators to hold 90-120 day safety stocks against Chinese and European supply disruptions. Raw material sourcing draws from German polyurethane resin specialists, Indian organic pigment intermediates, and Japanese photoinitiator producers, creating multi-currency exposure. Single-source vulnerability concentrates in nitrocellulose film-forming polymers, where three Chinese state-owned enterprises control majority export volumes. Distribution runs through regional technical service laboratories in Maharashtra, Guangdong, and North Rhine-Westphalia, with emergency reformulation support commanding 15-25% logistics premiums.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gravure ink incumbents face a substitution defense against digital inkjet and toner systems capturing short-run flexible packaging, requiring strategic repositioning toward compliance-driven segments where cylinder economics retain advantage.
For Market Incumbents: Shield core flexible packaging relationships by embedding water-based and EB-curable development partnerships with converters facing MEE inspection deadlines in Guangdong and Zhejiang. Accelerate backward integration into organic pigment synthesis to offset nitrocellulose resin volatility and compress ISO 2846-1 certification cycles for seasonal packaging programs.
For New Entrants and Emerging Players: Differentiate on emergency reformulation service capabilities for converters disrupted by China's GB standards enforcement, targeting mid-tier Vietnamese and Indonesian snack packaging producers with stranded solvent inventories. Penetrate India's PLI-subsidized corrugated pre-print segment through Amazon and Flipkart supplier network certifications, leveraging water-based gravure technical gaps left by multinational incumbents.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward carbon adsorption retrofit specialists and EB-curable formulation platforms with food-contact validation. Long-term viability hinges on 5-10 year regulatory divergence between REACH-compliant European markets and enforcement-lagged Southeast Asian jurisdictions. Target acquisition archetype: regional ink formulators with captive resin capabilities and multi-regional laboratory footprints. Signal to watch: MEE inspection intensity in Pearl River Delta industrial clusters as leading indicator of Chinese formulation switching velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | DIC Corporation's captive organic pigment production sustains formulation consistency across ECHA SVHC compliance cycles. |
| Water-Based Formulation Scale-Up | Domestic Chinese producers accelerate acrylic dispersion capacity to retain converter relationships under GB standards enforcement. |
| EB-Curable Line Retrofit Partnerships | German luxury confectionery converters adopt electron beam systems at 15% annual replacement rates for heat-sensitive films. |
| Multi-Regional Laboratory Expansion | Sun Chemical's technical service presence in Maharashtra and Gujarat supports India's PLI-driven packaging investment surge. |
| Digital Workflow Integration | UV-LED curing adoption by narrow-web label producers reduces energy consumption and substrate heat exposure in beverage SKU proliferation. |
Research Methodology
Desk research of customs trade data, ECHA SVHC registry updates, and SEC 10-K chemical segment disclosures preceded structured interviews with gravure ink plant managers, flexible packaging procurement leads at multinational brand owners, and distribution channel partners serving Southeast Asian industrial zones. Primary fieldwork with technical R&D directors at Japanese and European chemical conglomerates validated formulation migration timelines and nitrocellulose resin sourcing patterns. Bottom-up volume estimates triangulated against top-down packaging investment databases from India, Vietnam, and Indonesia.
Variance decomposition across ink type, substrate material, and end-use application segments informed projection modeling throughout the forecast period. Segmentation dimensions included formulation chemistry tier, printing substrate family, packaging versus publication end-use, and regional regulatory compliance cluster. CAGRs derived from converter capacity expansion announcements, cylinder engraving order backlogs, and brand-owner sustainability scorecard implementation trajectories. Key inputs encompassed MEE inspection intensity indices for Guangdong and Zhejiang, and EU F-Gas Regulation phase-down schedules affecting solvent recovery infrastructure.
Material uncertainties — abrupt REACH substance list expansion, nitrocellulose resin export restrictions from Chinese state-owned producers, and digital printing cost parity achievement in mid-run flexible packaging — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and converter capital commitment timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Global Light Changing Packaging Inks Market
Printing Inks
Packaging Inks and Coatings Market
Printing Inks
Lithography Inks Market
Printing Inks
Thermal Inkjet Inks Market
Printing Inks
Inkjet Colorants Market
Printing Inks
Brazil Commercial Printing Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Molecular Ink Market
Printing Inks
Ink Resins Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Food Grade Inks Market
Printing Inks
Flexo-Ink Market
Printing Inks
Global Printing Blanket Market
Printing Inks
North America Ink Market
Printing Inks
Zink Printing Market