
 Global Premium Hair Care Market | 2026-2036
Global Premium Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Global Premium Hair Care Market Foresight
South Korea is tilting toward expanded premium hair care manufacturing capacity as domestic brands scale export-oriented production. L'Oréal S.A. leverages its Seoul-based innovation hub to anchor R&D intensity in fermented ingredient technologies. Kao Corporation sustains competitive positioning through specialized scalp-care formulations targeting professional channels. Shiseido Company, Limited dominates prestige distribution across Japanese and Southeast Asian luxury retail doors.
Premium hair care encompasses scientifically formulated products positioned above mass-market tiers, typically containing higher concentrations of active ingredients such as keratin, ceramides, and plant-derived extracts, designed to deliver measurable hair repair, scalp health, and aesthetic performance outcomes. Shampoo and hair serum segments lead value generation due to repeat purchase frequency and premium pricing power in professional and direct-to-consumer channels. Hair mask and scalp care categories within the hair concern dimension are capturing expanding margin pools as consumers trade up from basic conditioning to targeted treatment protocols.
REACH and the EU Green Deal impose stringent chemical safety and sustainability disclosure obligations on European formulations, while the FDA governs cosmetic ingredient safety and labeling standards in the United States. South Korea's MFDS maintains rigorous functional cosmetic approval pathways that elevate barrier-to-entry for clinical hair treatment claims. Stakeholders must monitor evolving cross-border regulatory divergence on preservative allowances and biodegradability mandates to align portfolio development with compliance timelines.
Market Dynamics
Professional salon channel consolidation is concentrating demand among fewer but larger service providers, forcing formulation suppliers to reconfigure volume commitments and technical service deployment around multi-location operator networks rather than independent stylists.
Growth Catalysts
- Fermented ingredient R&D:Seoul-based innovation clusters are scaling bio-fermentation capacity for scalp microbiome formulations, creating proprietary active pipelines that command professional channel premiums.
- EU Green Deal compliance mandates:REACH chemical disclosure requirements are accelerating reformulation cycles, favoring suppliers with pre-validated sustainable ingredient portfolios and third-party certification infrastructure.
- South Korea export manufacturing:Domestic brands are expanding dedicated production lines for Southeast Asian and North American distribution, capturing margin pools previously served by European incumbents.
Market Restraints
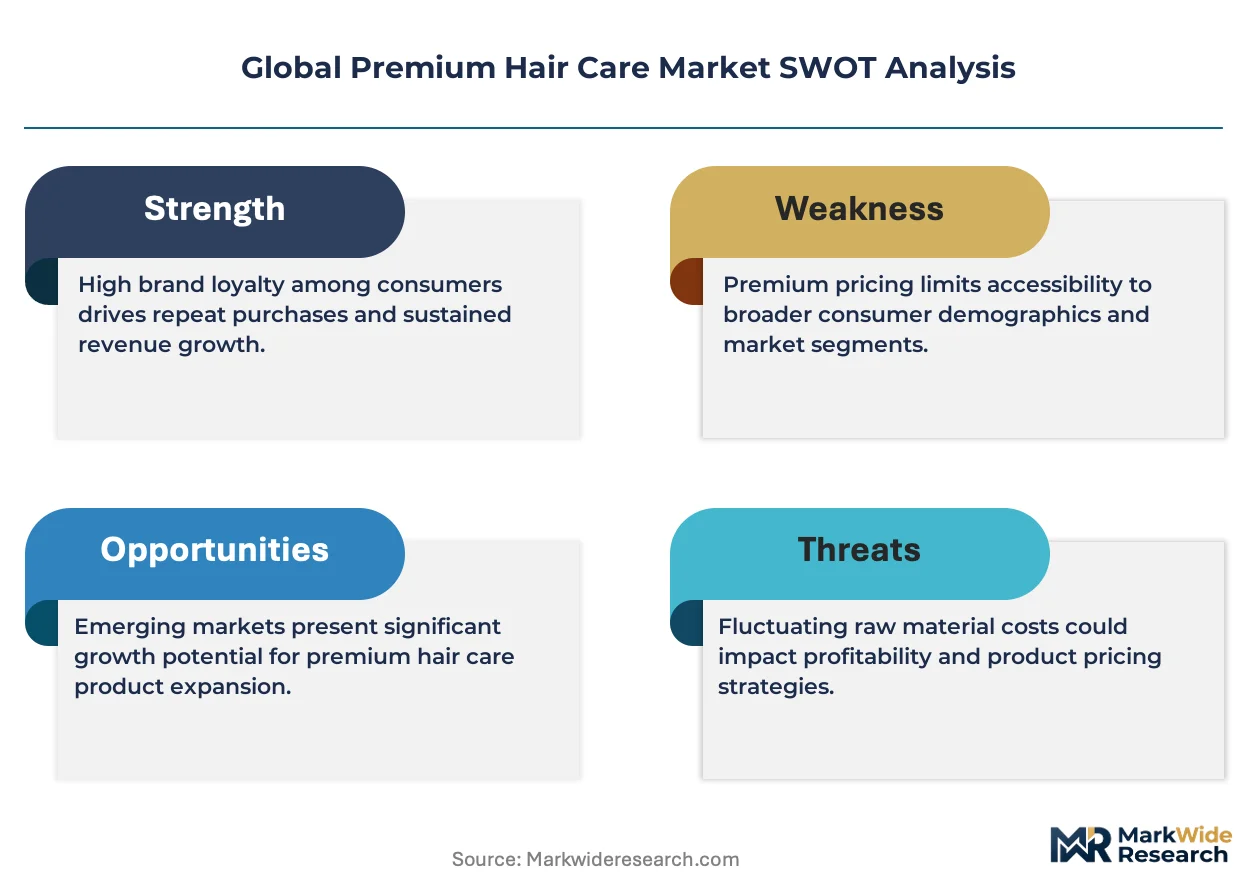
- Biopolymer feedstock volatility:Plant-derived conditioning agents and film-formers face agricultural supply fluctuations that compress formulation margins during poor harvest cycles in key sourcing regions.
- Single-source specialty chemical concentration:High-performance silicones and quaternary ammonium compounds rely on concentrated German and Japanese production bases, creating geographic vulnerability to logistics disruptions.
- Clinical claim substantiation costs:South Korea's MFDS functional cosmetic approval pathways require extended dermatological testing timelines that delay revenue recognition for treatment-positioned launches.
Strategic Opportunities
- Scalp care category white space:Professional channels in Brazil and Mexico show minimal penetration of diagnostic-grade scalp treatment protocols, offering first-mover positioning for technical service-supported launches.
- Waterless format innovation:Powder-to-foam and solid serum technologies align with EU biodegradability mandates while reducing shipping costs for direct-to-consumer distribution models.
- Professional education platform integration:Digital certification programs for salon stylists create captive recommendation channels that lock in backbar purchasing commitments.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation science programs produce insufficient graduates trained in fermented biotechnology and green chemistry synthesis methods required for next-generation product development.
- Multi-regulatory dossier synchronization:Divergent preservative allowances between FDA, REACH, and MFDS frameworks force parallel stability testing programs that extend development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Premium Hair Care Market |
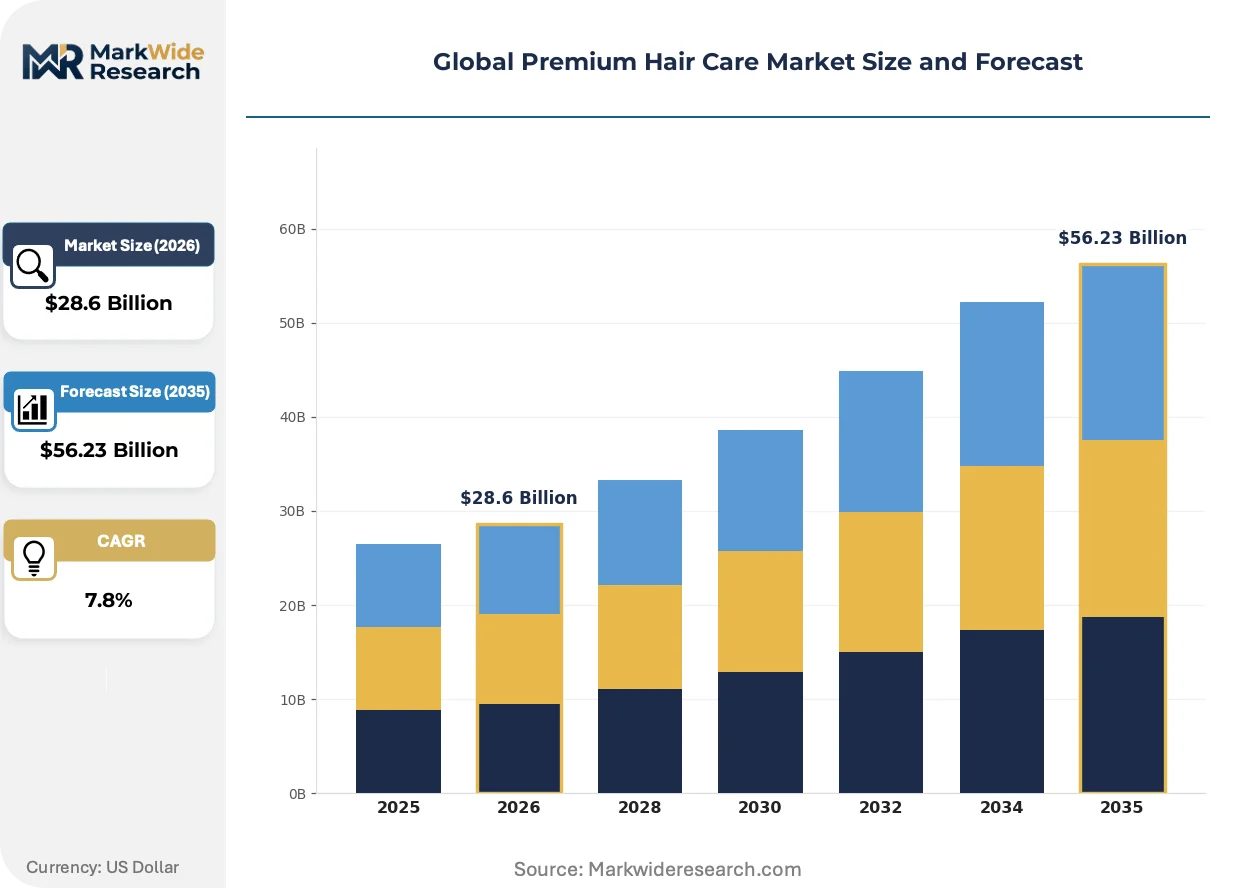
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Hair Serum, Hair Mask, Styling Gel Hair Concern: Dryness, Hair Fall, Dandruff, Frizz Control, Color Protection, Scalp Care End User: Salons, Spas, Luxury Hotels, Personal Use, Professional Stylists, Beauty Clinics Distribution Channel: Specialty Stores, Online Retail, High-End Department Stores, Luxury Boutiques, Direct Sales, Exclusive Brand Outlets |
| Companies Covered | L'Oréal S.A., Procter & Gamble Co., Unilever PLC, The Estée Lauder Companies Inc., Kao Corporation, Henkel AG & Co. KGaA, Coty Inc., Shiseido Company, Limited, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Premium Hair Care Market Shifts & Advancements
Fermentation biotechnology and AI-assisted formulation design are compressing development cycles while regulatory transparency mandates are reshaping ingredient sourcing verification requirements across supplier tiers.
Bioreactor-cultured postbiotics are virtualizing traditional botanical extraction supply chains by delivering standardized active concentrations without agricultural seasonality constraints. Professional salon brands in Seoul and Tokyo are adopting these inputs at accelerated procurement frequencies. The technology is virtualizing conventional raw material procurement relationships into long-term biomanufacturing partnerships with dedicated capacity allocations.
REACH Annex XVII restrictions on cyclic silicones are forcing reformulation of heat-protectant serums and finishing sprays across European professional portfolios. Manufacturers are substituting with plant-derived alternatives that require modified stability testing protocols. Color-treated hair maintenance products face the steepest technical adaptation burden given silicone dependency for cuticle sealing performance.
Subscription-based replenishment models are displacing salon-exclusive retail for maintenance-grade shampoos and conditioners among high-frequency purchasers. Direct-to-consumer platforms capture recurring revenue streams that professional distributors previously controlled through backbar allocation programs. This channel migration is most pronounced in North American urban markets where same-day delivery logistics have achieved critical density thresholds.
Global Premium Hair Care Market Segmentation
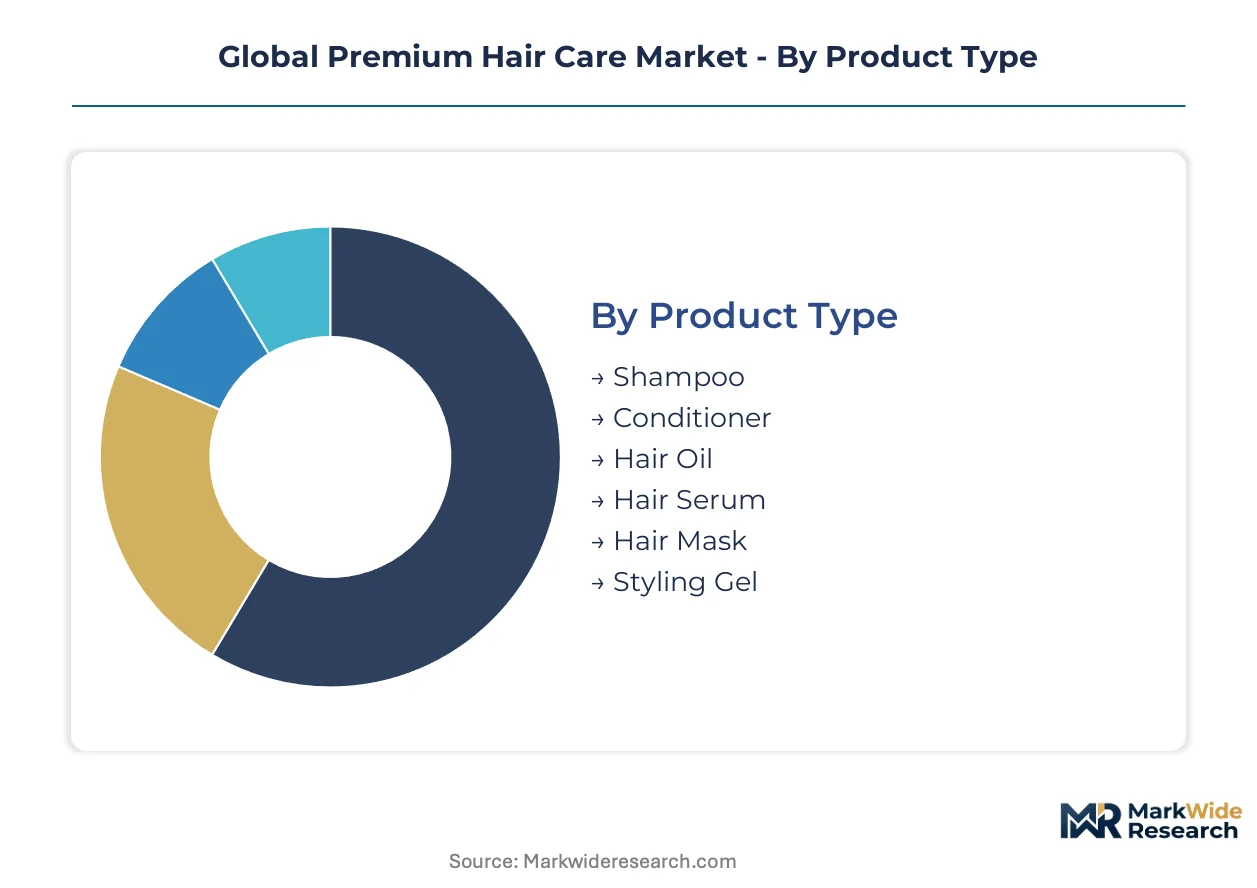
Premium hair care segmentation reveals how formulation intensity, service integration, and channel exclusivity create distinct margin architectures. Each dimension captures a different vector of value capture, from backbar professional deployment to direct-to-consumer subscription mechanics.
Product Type:
The use-case spectrum spans daily cleansing rituals through intensive treatment protocols, with formulation complexity and purchase frequency determining channel economics.
- Shampoo:High-active surfactant bases with keratin and ceramide concentrates dominate professional backbar allocation. Demand concentrates in South Korean salon chains where fermented ingredient positioning commands service premiums.
- Hair Serum:Concentrated leave-in treatments with silicone-alternative film-formers address heat damage and cuticle sealing. Seoul-based innovation clusters are scaling bioreactor-cultured postbiotics for scalp microbiome applications.
- Conditioner:Rinse-out formulations with quaternary ammonium conditioning agents maintain volume share through repeat purchase frequency in direct-to-consumer channels.
- Hair Oil:Lightweight dry oils and traditional botanical blends serve styling and finishing protocols across Middle Eastern and Southeast Asian luxury retail.
- Hair Mask:Intensive weekly treatments with higher active loading capture expanding margin pools as consumers trade up from basic conditioning.
- Styling Gel:Water-based and alcohol-free hold formulations face reformulation pressure under REACH biodegradability mandates.
The dominant share belongs to shampoo, while hair serum is closing the gap fastest.
Hair Concern:
Margin concentration tracks the clinical substantiation burden required for functional claims approval.
- Scalp Care:Diagnostic-grade treatment protocols with prebiotic and postbiotic actives require MFDS functional cosmetic pathways. Professional channels in Brazil and Mexico show minimal penetration, offering first-mover positioning.
- Color Protection:Silicone-dependent cuticle sealing formulations face steepest technical adaptation burden under REACH cyclic silicone restrictions.
- Dryness:Ceramide and plant-derived lipid concentrates serve the largest addressable need state across climate-diverse geographies.
- Hair Fall:Caffeine, biotin, and peptide-based treatments require extended dermatological testing timelines that delay revenue recognition.
- Dandruff:Antifungal actives with pyrithione zinc or salicylic acid compete with prescription positioning in pharmacy channels.
- Frizz Control:Humidity-responsive film-formers align with tropical climate demand in Southeast Asian urban markets.
Scalp care commands the steepest price premiums, while color protection is gaining share fastest among treatment-positioned launches.
End User:
Service integration depth separates volume-driven maintenance from high-margin technical application.
- Salons:Multi-location operator networks are consolidating backbar purchasing power, forcing suppliers to reconfigure technical service deployment around centralized procurement.
- Professional Stylists:Independent practitioners retain influence in color and texture service categories where diagnostic consultation drives product recommendation.
- Spas:Wellness-integrated scalp treatment protocols capture premium positioning through extended service duration and amenity retail.
- Luxury Hotels:Amenity-size formulations serve brand halo functions with limited reorder frequency.
- Personal Use:Subscription replenishment models are displacing salon-exclusive retail for maintenance-grade products among high-frequency purchasers.
- Beauty Clinics:Medical-aesthetic crossover positioning requires clinical claim substantiation that extends development timelines.
Salons retain the largest volume allocation, while beauty clinics are expanding most quickly through medical-aesthetic channel convergence.
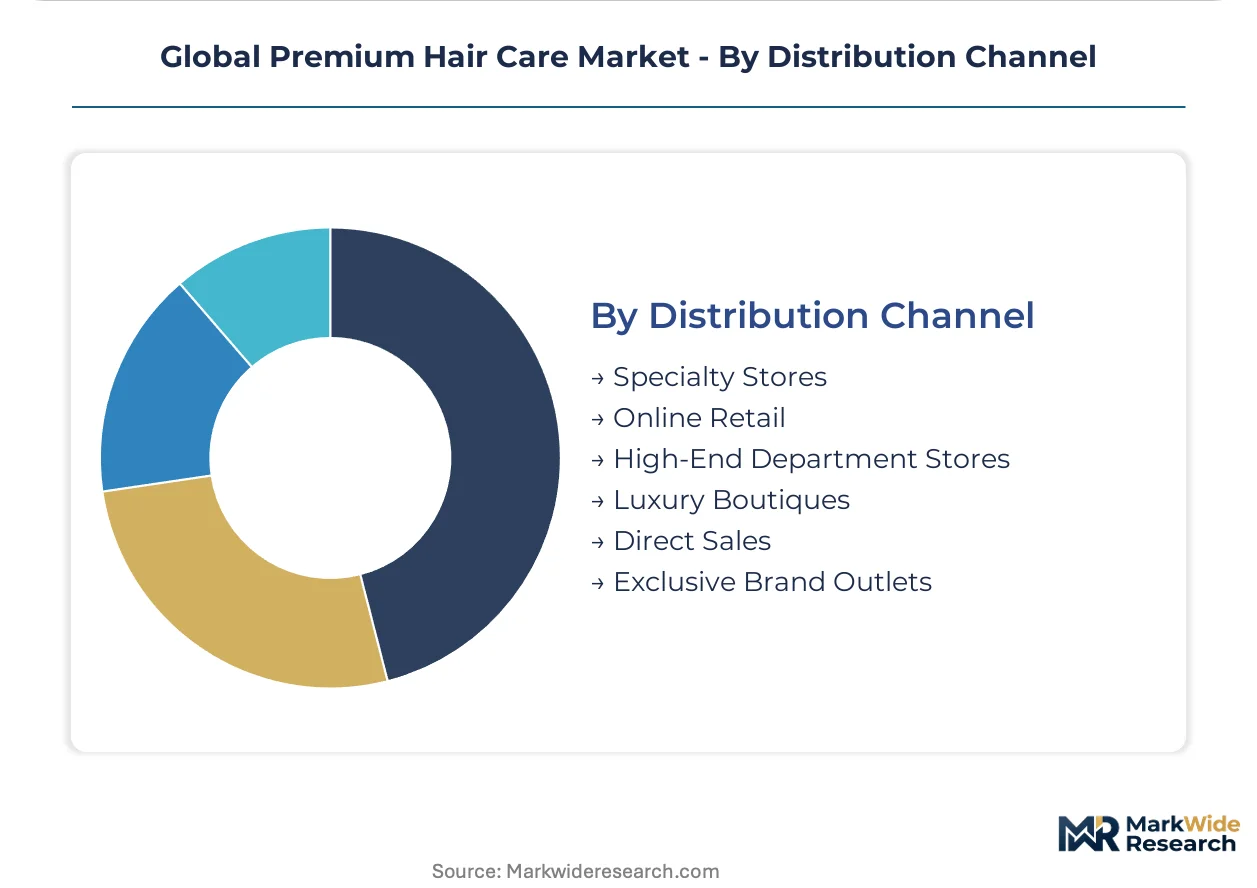
Distribution Channel:
Channel selection determines margin capture versus brand control trade-offs.
- Online Retail:Direct-to-consumer platforms with subscription mechanics capture recurring revenue streams previously controlled through professional distributor allocation.
- Specialty Stores:Curated assortment with diagnostic consultation services maintains premium positioning in urban markets.
- High-End Department Stores:Prestige fragrance-adjacent placement with gift-with-purchase programming drives trial among aspirational purchasers.
- Luxury Boutiques:Exclusive brand-controlled environments with personalized consultation capture highest per-transaction values.
- Direct Sales:Stylist and influencer-mediated recommendations retain influence in texture and color specialty categories.
- Exclusive Brand Outlets:Flagship environments with service integration anchor brand equity in flagship city locations.
Online retail has captured the dominant transaction volume, while luxury boutiques maintain the steepest expansion trajectory in brand-controlled positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS functional cosmetic pathways in South Korea elevate barrier-to-entry for clinical hair treatment claims, anchoring regulatory intensity in the dominant geography. Seoul-based innovation clusters drive fermented ingredient R&D while export manufacturing scales across Southeast Asian and North American distribution networks.
United States
FDA cosmetic ingredient safety standards govern labeling and preservative allowances across professional and direct-to-consumer channels. Subscription replenishment models displace salon-exclusive retail in urban markets where same-day delivery logistics achieve critical density. California and New York Metro anchor brand-controlled flagship environments with personalized consultation services.
Germany
REACH Annex XVII restrictions on cyclic silicones force reformulation of heat-protectant serums and finishing sprays across European professional portfolios. ECHA chemical disclosure requirements accelerate third-party certification infrastructure adoption. The Rhine-Ruhr industrial corridor concentrates specialty chemical production for high-performance conditioning agents.
Japan
METI industrial standards intersect with PMDA oversight for medical-aesthetic crossover positioning in beauty clinic channels. Shiseido anchors prestige distribution across luxury retail doors in Tokyo and Osaka. Kansai region manufacturing maintains specialized scalp-care formulation capacity for professional channel supply.
Brazil
ANVISA cosmetic registration pathways govern import and domestic production of treatment-positioned launches. Professional channels show minimal penetration of diagnostic-grade scalp treatment protocols, offering first-mover positioning for technical service-supported market entry. São Paulo state concentrates salon chain consolidation and multi-location operator procurement networks.
United Arab Emirates
MOHAP cosmetic safety standards regulate luxury retail and spa channel distribution across Dubai and Abu Dhabi. Amenity-size formulations serve brand halo functions in hospitality-integrated retail. Dubai's luxury boutique density captures highest per-transaction values through exclusive brand-controlled environments.
Global Premium Hair Care Market Competitive Landscape
Beauty conglomerates and specialized scalp-care formulators split the market between scale-driven portfolio breadth and technical service depth. Consolidation concentrates backbar purchasing power among fewer multi-location operator networks, forcing suppliers to reconfigure volume commitments and deployment strategies. Three archetypes dominate: fermentation biotechnology specialists, professional channel integrators, and prestige retail anchoring conglomerates. M&A activity targets bioreactor-cultured postbiotic capabilities, while strategic partnerships lock in dedicated capacity allocations with Seoul-based innovation clusters.
Within the fermentation biotechnology tier, L'Oréal S.A. anchors R&D intensity through its Seoul-based innovation hub, exemplifying the geographic co-location strategy that commands professional channel premiums. Kao Corporation occupies a position among specialized scalp-care formulators targeting professional channels with diagnostic-grade treatment protocols. Shiseido Company, Limited represents prestige retail anchoring across Japanese and Southeast Asian luxury distribution, sitting within the medical-aesthetic convergence vector that extends development timelines through clinical claim substantiation.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble Co. |
| Unilever PLC |
| The Estée Lauder Companies Inc. |
| Kao Corporation |
| Henkel AG & Co. KGaA |
| Coty Inc. |
| Shiseido Company, Limited |
| Beiersdorf AG |
| Others |
Supply & Pricing Matrix
Single-source specialty chemical concentration in German and Japanese production bases determines both pricing tier spreads and supply chain shape across premium hair care formulations. Biopolymer feedstock volatility compresses margins during poor harvest cycles while forcing buyers into longer-term offtake commitments to secure conditioning agent supply.
Pricing Analysis
Price spreads between Seoul-manufactured fermented actives and European-sourced silicone alternatives exceed threefold across professional backbar channels. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-certified functional cosmetics from basic maintenance formulations. Cost compression in mid-tier rinse-out conditioners is intensifying because subscription replenishment models displace salon-exclusive retail. Independent stylists show highest price sensitivity while multi-location operator networks extract volume discounts through centralized procurement.
Supply Chain Analysis
Extended payment terms from Seoul-based innovation clusters to Southeast Asian contract manufacturers are restructuring working capital requirements across tier-two suppliers. Bioreactor-cultured postbiotics production draws from South Korean, Japanese, and German biotechnology bases. High-performance quaternary ammonium compounds and cyclic silicone alternatives rest on concentrated chemical production in the Rhine-Ruhr corridor and Kansai region. Single-source vulnerability in plant-derived film-formers creates geographic exposure to climate-driven harvest disruption. Distribution runs through professional distributor networks, direct-to-consumer platforms, and luxury retail doors with diverging margin capture profiles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Professional education platform integration is shifting market power toward ecosystem orchestrators that lock in stylist recommendation channels through digital certification programs. Interoperability between diagnostic scalp analysis tools and personalized formulation protocols is reshaping competitive positioning.
For Market Incumbents: Entrench fermentation biotechnology capabilities through dedicated bioreactor capacity allocations with Seoul-based innovation clusters. Secure multi-year supply agreements for plant-derived conditioning agents before biopolymer feedstock volatility intensifies. Defend against direct-to-consumer subscription encroachment by embedding IoT-enabled replenishment triggers into professional salon backbar systems. For New Entrants and Emerging Players: Diagnostic-grade scalp treatment protocols in Brazilian and Mexican professional channels represent the most penetrable entry point given minimal incumbent penetration. Waterless format innovation—powder-to-foam and solid serum technologies—opens technical differentiation for EU Green Deal compliance positioning. Pursue technical service-supported launches with localized dermatological testing partnerships to accelerate MFDS-equivalent pathway navigation. For Investors and Strategic Acquirers: REACH Annex XVII cyclic silicone restrictions reshape the acquisition landscape toward suppliers with pre-validated sustainable ingredient portfolios and third-party certification infrastructure. Five-to-ten year viability favors biomanufacturing partnerships over traditional botanical extraction supply chains. Target acquisition archetype: fermentation biotechnology specialists with dedicated postbiotic capacity and professional channel technical service deployment. Watch for ANVISA regulatory harmonization with MFDS standards as inflection signal for Latin American market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Biotechnology Scale-Up | Bioreactor-cultured postbiotics virtualize agricultural supply chains for Seoul-based innovation clusters. |
| Professional Education Platform Integration | Digital certification programs for salon stylists create captive recommendation channels with backbar lock-in. |
| Waterless Format Innovation | Powder-to-foam technologies align with EU biodegradability mandates while reducing direct-to-consumer shipping costs. |
| Multi-Location Operator Technical Service Deployment | Centralized procurement networks demand reconfigured volume commitments from formulation suppliers. |
| Sustainable Ingredient Portfolio Certification | Pre-validated REACH-compliant inputs accelerate reformulation cycles for European professional portfolios. |
Research Methodology
The analysis maps fermented ingredient technologies, scalp-care treatment protocols, and professional channel distribution mechanics, each validated through formulation chemists, salon chain procurement directors, and luxury retail category buyers. Primary interviews with multi-location operator network executives, independent stylist educators, and biomanufacturing partnership managers combined with secondary validation from MFDS functional cosmetic filings, REACH Annex XVII regulatory updates, and professional distributor inventory data. Bottom-up segmentation sizing and top-down market triangulation anchored volume and value estimates.
Assumption sets held regulatory pathway timelines and biopolymer feedstock cost curves fixed while varying professional channel consolidation rates and direct-to-consumer subscription penetration across geographies. Segmentation dimensions modeled include product type intensity, hair concern clinical substantiation burden, end-user service integration depth, and distribution channel margin capture structure. CAGRs derived from growth driver elasticity analysis against historical professional backbar allocation patterns and export manufacturing capacity expansion trajectories. Forecast inputs incorporated Seoul-based innovation cluster R&D intensity indices and ANVISA registration pathway efficiency differentials.
Practitioners should monitor biopolymer harvest cycles, REACH preservative allowance evolution, and MFDS-ANVISA regulatory harmonization progress for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Europe Hair Care Market
Hair Care
India Hair Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Mexico Hair Care Market
Hair Care
Chile Hair Care Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Australia Hair Care Market
Hair Care
Russia Hair Care Market
Hair Care
North America Hair Care Market
Hair Care
Hair Clay Market
Hair Care
South Korea Hair Care Market
Hair Care
Global Shampoo Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Hair Extension Market
Hair Care
Artificial Hair Integration Market