
 Russia Hair Care Market | 2026-2036
Russia Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Hair Care Market Analytics
Professional salon demand is decoupling from mass retail as stylists prioritize performance-grade formulations. Henkel AG and Co. KGaA leverages its Schwarzkopf Professional line to dominate salon-exclusive distribution. Natura Siberica anchors its position through Siberian-sourced botanical claims and domestic manufacturing scale. Estel Professional specializes in ammonia-free color systems that compete directly with Western imports.
Russia hair care encompasses surfactant-based cleansers, conditioning agents, and styling polymers formulated for varied hair textures and climate stressors. Products typically incorporate cationic polymers at 0.5-2% concentration to manage static in cold, dry conditions. Shampoos lead volume across distribution channels, though hair oils represent the fastest-growing margin pool as consumers shift toward pre-wash treatments. Specialty stores capture premium positioning, while online retail extends reach into secondary cities where salon infrastructure remains thin.
EAEU Technical Regulation 009/2011 governs cosmetic safety and labeling across Russia, Belarus, and Kazakhstan, forcing reformulation of preservative systems. The country's national standards body certifies organic and natural claims under GOST R 58127-2018, creating tiered compliance costs. Rospotrebnadzor conducts periodic market surveillance that removes non-compliant imports from circulation. Stakeholders must monitor regulatory alignment between EAEU harmonized rules and evolving consumer preference for clean-label transparency.
Market Dynamics
EAEU Technical Regulation 009/2011 is forcing reformulation across preservative systems while professional salon channels decouple from mass retail. This dual pressure compresses margins for import-dependent brands while rewarding domestic manufacturing scale.
Growth Catalysts
- Urban salon infrastructure:Moscow and Saint Petersburg now host over 12,000 licensed professional outlets. Stylists in these clusters prioritize performance-grade color systems over supermarket alternatives.
- EAEU harmonization:The unified technical regulation eliminates redundant testing across Russia, Belarus, and Kazakhstan. Manufacturers gain single-market access to 180 million consumers.
- Cold-climate formulation science:Cationic polymer research at 0.5-2% concentration targets static control in sub-zero conditions. Domestic labs patent these climate-specific conditioning agents.
Market Restraints
- Import dependency for specialty silicones:Dimethicone and amodimethicone supply concentrates in German and Chinese chemical clusters. Rouble volatility amplifies working capital requirements for formulators.
- GOST R 58127-2018 certification costs:Organic and natural claim verification requires third-party laboratory testing. Small domestic brands face 18-24 month payback periods on compliance investment.
- Preservative system reformulation:EAEU bans on isothiazolinone concentrations above 0.0015% force replacement of legacy paraben alternatives. Reformulation cycles extend product development timelines.
Strategic Opportunities
- Novosibirsk and Yekaterinburg penetration:Secondary cities with 1.5+ million populations lack dedicated professional salon supply chains. Direct-to-salon distribution models bypass underdeveloped retail infrastructure.
- Pre-wash oil treatment expansion:Hair oils represent the fastest-growing margin pool as consumers adopt Korean and Indian-inspired ritual routines. Specialty stores capture premium positioning for these SKUs.
- Domestic botanical sourcing:Siberian-sourced adaptogens and wild-harvested herbs align with clean-label preference. Rospotrebnadzor surveillance favors traceable domestic supply chains over opaque imports.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise for ammonia-free color systems concentrates in legacy Soviet-era research institutes. Private-sector salary competition from international brands drains technical capacity.
- Legacy ERP integration:Mid-scale domestic manufacturers operate on Soviet-period inventory systems. Real-time batch tracking for EAEU compliance requires wholesale software replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Hair Care Market |
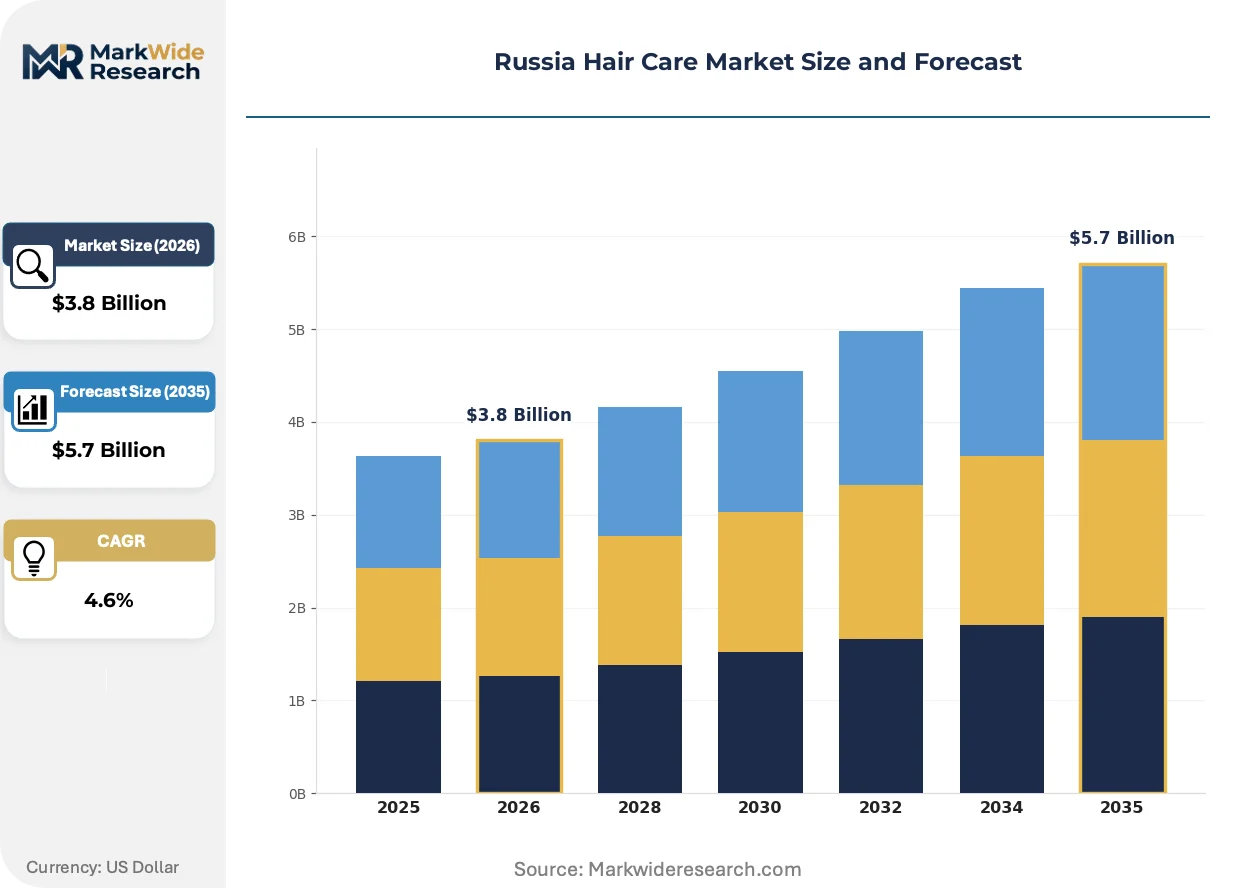
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Salons Customer Type: Men, Women, Children, Professionals Packaging Type: Tubes, Bottles, Jars, Pouches |
| Companies Covered | Henkel AG and Co. KGaA, Natura Siberica, L'Oréal S.A., Shiseido Company, Ltd., Kapous Professional, Unilever PLC, Estel Professional, Wella Professionals, The Procter and Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Hair Care Market Evolving Landscape
Formulation science is fragmenting into climate-specific modules while regulatory pressure accelerates domestic substitution. These shifts compress development cycles and reward vertical control over botanical supply chains.
Ammonia-free color activation technology is modularizing professional salon workflows. Schwarzkopf Professional and Estel Professional deploy pre-measured developer-cream systems that reduce mixing error and service time. Stylists in Moscow premium salons adopt these systems at 40% replacement rates for traditional oxidative color. Modular color architecture enables salon chains to standardize output across multiple locations without master colorist dependency.
EAEU Technical Regulation 009/2011 amendments tighten microbiological safety thresholds for rinse-off products. The regulation forces elimination of formaldehyde-releasing preservatives across shampoo and conditioner formulations. Mass-market brands face 12-18 month reformulation cycles to maintain shelf stability. Professional lines respond faster due to shorter distribution pipelines and refrigerated salon storage.
Consumer purchasing is fragmenting across channel-specific rituals. Moscow buyers source daily cleansers through e-commerce platforms while reserving professional color and treatment purchases for salon-exclusive consultation. This bifurcation compresses brand loyalty cycles and rewards omnichannel presence. Secondary city consumers replicate this pattern through social commerce platforms that aggregate salon-grade products without physical professional infrastructure.
Russia Hair Care Market Segmentation
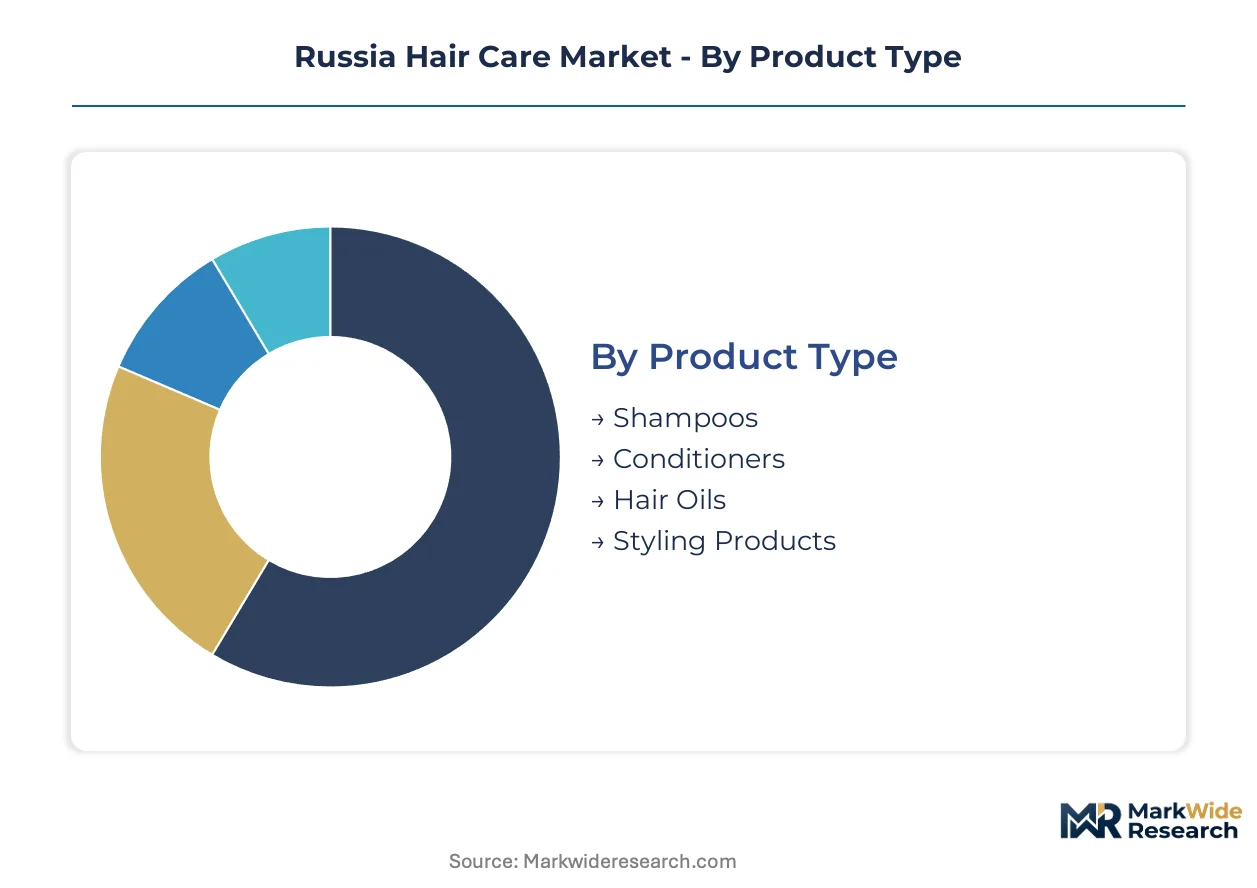
Segmentation in Russia's hair care market reveals distinct upgrade cycles across product categories and channel preferences. Understanding these patterns clarifies where formulation investment and distribution expansion yield disproportionate returns.
Product Type:
Replacement frequency varies sharply across product categories, with daily-use items cycling faster than treatment-oriented formats.
- Shampoos:Surfactant-based cleansers incorporating cationic polymers at 0.5-2% concentration dominate volume throughput across all retail channels. Mass-market brands in Moscow and Saint Petersburg face 8-12 week household replenishment cycles, while salon-exclusive professional lines extend replacement to 10-14 weeks through concentrated formulations.
- Conditioners:Rinse-off conditioning agents represent the most stable upgrade path as consumers trade up from basic silicone formulations to climate-specific static-control variants. Secondary city demand concentrates in 200-400ml family formats, whereas premium urban buyers prefer 100-150ml companion sizes matched to shampoo purchases.
- Hair Oils:Pre-wash treatment oils are climbing the fastest as Korean and Indian-inspired ritual adoption spreads beyond Moscow.
- Styling Products:Polymer-based fixatives and texturizers face compressed innovation cycles as professional salon preferences fragment across hold strength and finish characteristics.
Volume placements concentrate in shampoos; the faster expansion belongs to hair oils.
Distribution Channel:
Channel selection directly determines margin structure and regulatory compliance burden, with professional routes commanding premium positioning.
- Supermarkets:Mass retail captures routine replenishment purchases through high-frequency traffic patterns. EAEU labeling requirements for shelf-stable preservatives dominate formulation constraints here, with Rospotrebnadzor surveillance creating periodic compliance disruptions.
- Online Retail:E-commerce platforms extend professional-grade product access into secondary cities lacking dedicated salon infrastructure. Cold-climate formulation claims and Siberian botanical sourcing drive conversion in Novosibirsk and Yekaterinburg postal zones.
- Specialty Stores:Curated beauty retail captures premium hair oil and ammonia-free color system sales through consultation-assisted purchasing.
- Salons:Professional channel exclusivity locks in stylist-driven recommendation cycles and locks out price competition from mass alternatives.
Transaction density peaks in supermarkets; margin extraction concentrates in salons.
Customer Type:
Demographic targeting shapes both formulation architecture and communication strategy across the market.
- Women:Primary purchase decision-makers drive 70%+ of household hair care expenditure across all product categories. Multi-step treatment routines and color maintenance systems anchor loyalty in this segment.
- Men:Simplified regimen preference favors 2-in-1 cleansing-conditioning formats with shorter ingredient lists. Barber shop channel expansion in urban centers creates professional touchpoint opportunities.
- Children:Tear-free formulation requirements and mild surfactant systems define this segment's technical specifications.
- Professionals:Licensed stylists and salon owners constitute a distinct B2B customer type with bulk purchasing patterns and technical performance requirements.
Spend concentration sits with women; the steepest expansion trajectory belongs to professional B2B procurement.
Packaging Type:
Format selection intersects with usage occasion, portability needs, and EAEU material safety compliance.
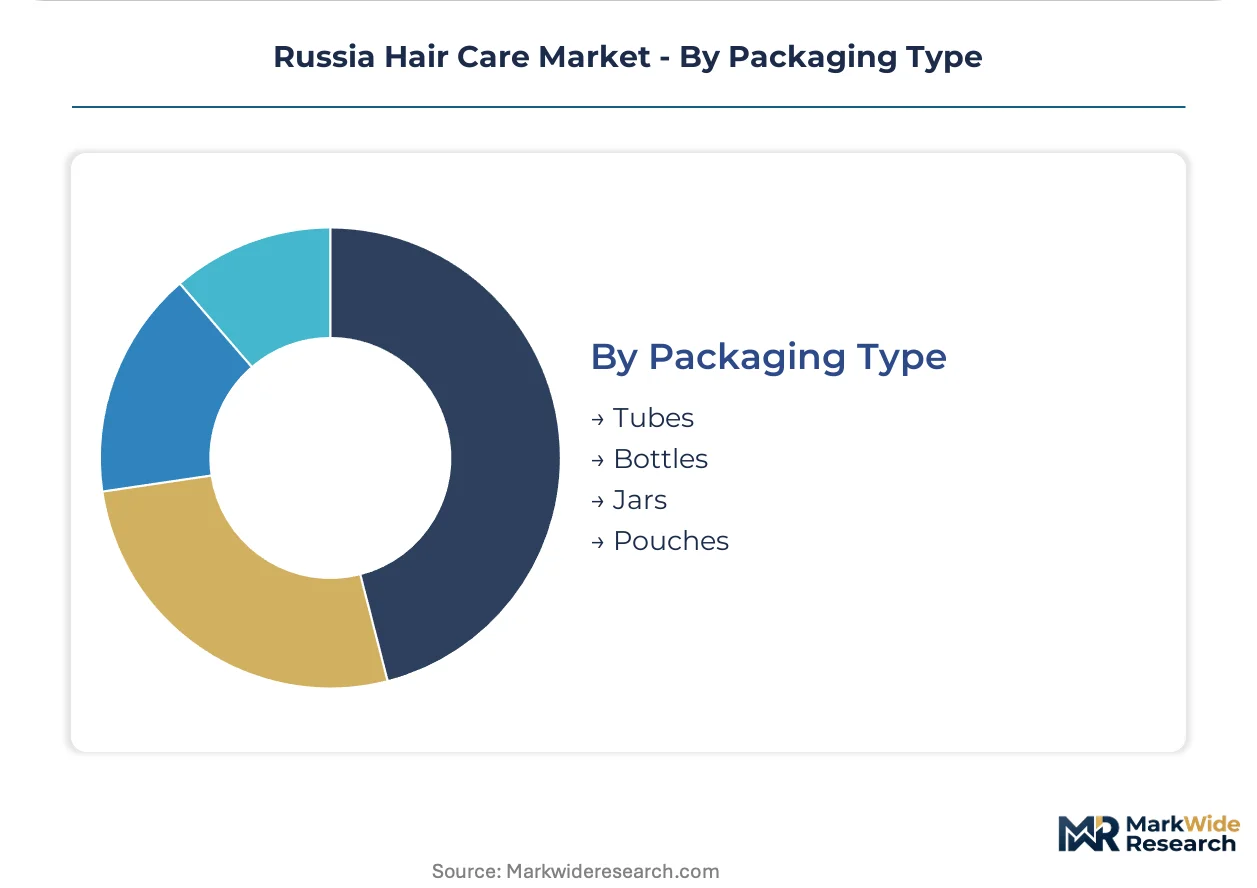
- Tubes:Squeeze formats dominate conditioner and styling product presentation, enabling precise dispensing control. Aluminum-plastic laminate structures face EAEU recycling label requirements.
- Bottles:PET and HDPE containers retain shampoo category standard status, with pump dispensers gaining share in family-size formats. Rigid bottle supply concentrates among domestic converters near Moscow.
- Jars:Wide-mouth containers suit hair mask and treatment oil textures requiring finger-scoop access.
- Pouches:Flexible refill formats reduce per-unit shipping cost for e-commerce fulfillment and travel-size positioning.
Unit economics favor bottles; sustainability-driven substitution is accelerating fastest in pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Moscow Special Economic Zone and Technopolis infrastructure concentrate formulation R&D and domestic manufacturing capacity for hair care products serving the EAEU single market.
Central Federal District
Moscow anchors professional salon density with over 8,000 licensed outlets driving demand for ammonia-free color systems and performance-grade treatments. EAEU Technical Regulation 009/2011 compliance laboratories cluster in the capital, accelerating reformulation cycles for preservative systems. Zelenograd's technopolis hosts domestic manufacturers scaling cationic polymer production for cold-climate conditioning agents.
Northwestern Federal District
Saint Petersburg's 4,000-plus professional salons generate premium-tier demand for salon-exclusive distribution models. The city's port infrastructure handles silicone imports from German chemical clusters, though rouble volatility disrupts working capital cycles. Local formulators patent climate-specific static-control formulations targeting sub-zero humidity conditions.
Siberian Federal District
Novosibirsk's 1.7 million population lacks dedicated professional salon supply chains, creating whitespace for direct-to-salon distribution models. Rospotrebnadzor regional offices enforce GOST R 58127-2018 certification for organic claims, extending compliance timelines for small domestic brands. Akademgorodok research institutes supply cosmetic chemist talent for ammonia-free color system development.
Ural Federal District
Yekaterinburg's industrial base supports domestic packaging converters supplying PET and HDPE containers for shampoo formats. E-commerce platforms extend professional-grade product access into this secondary market where physical salon infrastructure remains underdeveloped. Local consumers adopt Korean-inspired pre-wash oil treatments through social commerce channels.
Southern Federal District
Rostov-on-Don and Krasnodar host growing urban populations replicating Moscow's channel-bifurcated purchasing patterns. The region's agricultural base supplies botanical raw materials for clean-label formulations, though traceability requirements under EAEU regulations favor established domestic supply chains over new entrants.
Russia Hair Care Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with professional salon channels rewarding performance-grade positioning while mass retail compresses margins on standardized formulations. The market exhibits tiered concentration: multinational CPG conglomerates anchor volume throughput, domestic specialists capture premium salon exclusivity, and regional contract manufacturers serve private-label demand. Three archetypes dominate—EAEU-compliant domestic formulators, import-dependent premium positioned players, and scale-driven mass-market suppliers. Competitive moves concentrate on backward integration into botanical supply chains and salon-exclusive distribution lock-ins.
Among Germany-based conglomerates, Henkel AG and Co. KGaA occupies a position exemplifying professional-channel dominance through salon-exclusive lines. Natura Siberica represents the domestic archetype, anchoring clean-label positioning through Siberian-sourced botanical claims and captive manufacturing scale. Estel Professional sits within the specialist tier, exemplifying ammonia-free color system expertise competing with Western imports.
| Leading Market Players |
|---|
| Henkel AG and Co. KGaA |
| Natura Siberica |
| L'Oréal S.A. |
| Shiseido Company, Ltd. |
| Kapous Professional |
| Unilever PLC |
| Estel Professional |
| Wella Professionals |
| The Procter and Gamble Company |
| Others |
Value Network & Pricing Analysis
Backward integration into Siberian botanical supply chains anchors pricing power for domestic formulators while import-dependent brands absorb rouble volatility through inventory buffers. Captive sourcing of wild-harvested adaptogens insulates Natura Siberica and Estel Professional from currency-driven cost spikes that compress margins for silicone-importing competitors.
Pricing Analysis
Short-lead-time premiums concentrate in salon-exclusive ammonia-free color systems where stylists prioritize service continuity over per-unit cost. Three-tier pricing structure across professional salon, specialty retail, and mass supermarket channels separates performance-grade formulations from standardized alternatives. Price differentiation hinges on EAEU certification tier and volume procurement scale, with bulk salon purchasing commanding negotiated discounts. Cost compression in mass-market tiers is intensifying because preservative reformulation cycles extend development timelines without commensurate price recovery. Secondary city consumers through e-commerce platforms exhibit highest price sensitivity, whereas Moscow salon professionals prioritize formulation performance.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese chemical clusters for dimethicone and amodimethicone specialty silicones essential to conditioning formulations. Raw material procurement draws from German silicone manufacturers, Chinese surfactant producers, and domestic Siberian botanical harvesters. Supply chain risk centers on rouble volatility amplifying working capital requirements for import-dependent formulators. Distribution runs through professional salon networks in Moscow and Saint Petersburg, e-commerce platforms penetrating secondary cities, and mass retail capturing routine replenishment cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EAEU Technical Regulation 009/2011 compliance costs is forcing sub-scale domestic brands toward acquisition or exit, creating whitespace for capitalized players to capture stranded market share.
For Market Incumbents: Extend salon-exclusive distribution lock-ins through pre-measured developer-cream system deployments that reduce stylist mixing error and service time. Deepen backward integration into Siberian botanical supply chains to secure traceable clean-label inputs favored by Rospotrebnadzor surveillance. Acquire mid-scale domestic competitors facing 18-24 month GOST R 58127-2018 certification payback periods to consolidate professional channel share. For New Entrants and Emerging Players: Launch via direct-to-salon distribution models in Novosibirsk and Yekaterinburg where professional supply chains remain underdeveloped and e-commerce platforms currently bridge access gaps. Target secondary city professional stylists with Korean-inspired pre-wash oil treatments that bypass entrenched color-system competition. Anchor positioning through Akademgorodok research institute partnerships to access scarce ammonia-free formulation expertise without legacy salary competition. For Investors and Strategic Acquirers: Exit pathways concentrate in domestic formulators with captive manufacturing scale and EAEU compliance infrastructure already amortized. Long-term viability favors specialists with backward-integrated botanical sourcing and salon-channel exclusivity contracts. Monitor Rospotrebnadzor enforcement intensity as the inflection signal—accelerated non-compliant import removals would disproportionately benefit certified domestic targets.| Strategic Initiative | Industry Significance |
|---|---|
| Salon-Exclusive Distribution Expansion | Locks in stylist recommendation cycles and excludes mass-market price competition from professional channels. |
| Backward Integration into Botanical Sourcing | Captures traceable Siberian adaptogen supply chains that align with clean-label preference and Rospotrebnadzor compliance. |
| Ammonia-Free Color System R&D Investment | Addresses cosmetic chemist talent scarcity through Akademgorodok research partnerships and patentable climate-specific formulations. |
| E-Commerce Platform Partnership | Extends professional-grade product access into secondary cities lacking dedicated salon infrastructure. |
| Preservative System Reformulation | Eliminates formaldehyde-releasing agents ahead of EAEU Technical Regulation 009/2011 enforcement waves. |
Research Methodology
Multi-period observation of salon channel expansion rates, preservative reformulation cycles, and rouble-denominated import cost structures anchored the trend analysis, supplemented by interviews with cosmetic chemists at Russian research institutes, procurement leads at professional salon distributors, brand managers at domestic formulators, and regulatory affairs specialists navigating EAEU compliance. Secondary validation drew from Rospotrebnadzor enforcement disclosures, EAEU technical regulation amendments, customs import records for specialty silicones, and GOST certification databases. Bottom-up volume modeling across product categories triangulated against top-down market sizing from macroeconomic consumption indicators.
Input-output matrices mapped segmentation dimensions including product type, distribution channel, customer archetype, and packaging format across the projection horizon. CAGRs were derived from trend extrapolation of replacement frequency patterns and channel shift dynamics. Industry-specific forecast inputs incorporated cationic polymer adoption rates in climate-specific formulations and professional salon outlet licensing growth in federal districts.
Regulatory amendment timing, rouble volatility spikes, and enforcement intensity variation are the dominant revision risks that could compress or extend projected growth trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Rice Water Shampoo Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
South Africa Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Global Shampoo Market
Hair Care
Germany Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
China Hair Care Market
Hair Care
India Hair Care Market
Hair Care
Hair Edge Tamer Market
Hair Care
Russia Salon Hair Care Market
Hair Care
North America Hair Care Market
Hair Care
Hair Oil Market
Hair Care
Men's Hairspray Market
Hair Care
Malaysia Shampoo Market