
 Hair Extension Market | 2026-2036
Hair Extension Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Extension Market Intelligence
China is tilting the global supply balance through concentrated raw hair collection and processing infrastructure in Xuchang and surrounding prefectures. Henan Rebecca Hair Products leverages backward integration into raw material sourcing to control cost structures across remy and virgin grades. Great Lengths Universal Hair Extensions anchors premium positioning through Italian bonding technology and certified salon-only distribution. Balmain Hair Group differentiates via Paris fashion house heritage and limited-edition capsule releases tied to runway calendars.
Hair extensions are supplemental hair systems, typically 18–24 inches in length, attached through mechanical clips, adhesive tapes, keratin fusion bonds, or micro-bead weaves to add volume, length, or color dimension to natural hair; remy human hair variants retain cuticle alignment for reduced tangling and extended reuse cycles. Clip-in and tape-in formats dominate personal-use channels due to consumer self-application convenience and lower price entry points, while fusion and pre-bonded systems command salon-installed premium tiers where stylist labor embeds in total service cost. Synthetic fiber segments occupy mass-market retail shelves with heat-resistant polymer formulations, though remy human hair captures the majority of margin pools in professional and direct-to-consumer premium channels.
REACH in Europe mandates full chemical disclosure for bonding adhesives and solvent residues, while FDA cosmetic labeling rules govern claims around "human hair" origin and synthetic blend ratios in United States commerce. China's GB standards for textile and fiber products, administered by SAMR, set burn-test and labeling baselines that export-oriented processors must satisfy for cross-border shipment clearance. Stakeholders must monitor evolving customs classification disputes around raw versus processed hair to anticipate duty exposure and origin-documentation burdens.
Market Dynamics
Professional salon channels are absorbing extension services into recurring color and cut appointments, converting occasional purchases into subscription-like revenue streams while raw hair processing clusters in Henan province tighten grip on global virgin and remy supply.
Growth Catalysts
- REACH compliance mandates:ECHA disclosure rules for bonding adhesives and solvent residues are forcing formulation upgrades that premiumize product tiers and squeeze unqualified suppliers from European distribution.
- Salon service integration:Stylists now bundle tape-in and fusion installations with root touch-ups and balayage treatments, embedding extensions into recurring appointment calendars rather than standalone purchases.
- Henan processing infrastructure:Xuchang and surrounding prefectures concentrate raw human hair collection, sorting, and acid-treatment capacity that captures 70% of global remy supply chain value.
Market Restraints
- Raw hair input volatility:Donor hair availability fluctuates with rural income levels in source countries, creating 18-24 month price cycles that compress margin predictability for processors.
- FDA labeling friction:Cosmetic labeling rules governing "human hair" origin claims and synthetic blend disclosures create compliance costs that deter small importers from US market entry.
- Heat-resistant polymer substitution:Advanced synthetic fibers from Korean and Japanese chemical producers now mimic remy texture at 40% lower unit cost, pressuring human hair volume in mass retail.
Strategic Opportunities
- Underpenetrated male grooming:Hair loss concealment and volume augmentation for men remains largely unaddressed outside South Korea, where metro salon chains now offer discrete consultation protocols.
- Medical application expansion:Oncology patients and alopecia sufferers represent a reimbursable channel in France and Germany where national health frameworks cover cranial prosthetics including custom-fitted systems.
- Direct-to-consumer bonding innovation:Magnetic and adjustable pressure-fit attachments are eliminating salon dependency for semi-permanent wear, opening 48-hour delivery models through specialized e-commerce platforms.
Industry Challenges
- Certified installation technician scarcity:Keratin fusion and micro-bead weave methods require 40-60 hour training protocols that accredited academies in Italy and the United States struggle to scale against salon demand.
- Origin documentation complexity:Customs classification disputes between raw and processed hair categories trigger duty exposure and shipment delays at Rotterdam, Los Angeles, and Shenzhen ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Extension Market |
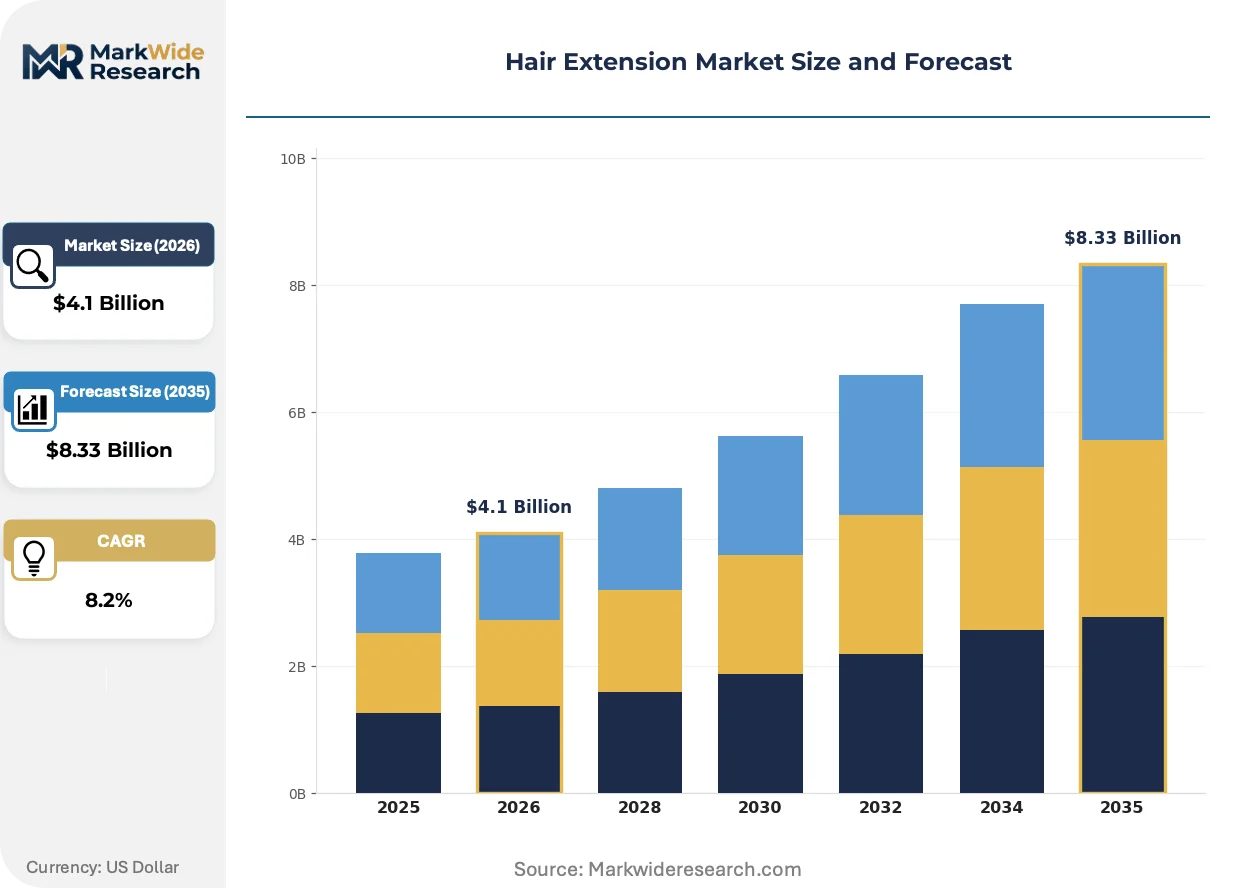
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.33 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clip-In, Tape-In, Sew-In, Fusion, Pre-Bonded, Halo Material: Remy Human Hair, Synthetic Fiber, Virgin Human Hair, Non-Remy Hair, Heat Resistant Fiber, Animal Hair Application: Salon Use, Personal Use, Photo Shoots, Fashion Shows, Film Industry, Special Events Customer Type: Hair Salons, Beauty Clinics, Individual Consumers, Hairstylists, Product Distributors, Retailers |
| Companies Covered | Great Lengths Universal Hair Extensions, Balmain Hair Group, Henan Rebecca Hair Products, Hairdreams, Bellami Hair, Indique Hair, Evergreen Products Group Limited, SO.CAP. Original USA, Hair Visions International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Extension Market Strategic Shifts & Innovations
Digital color-matching algorithms and AI-powered consultation tools are compressing the trial-and-error phase of extension selection, while regulatory disclosure mandates and shifting procurement patterns restructure competitive advantage.
3D scalp-scanning technology is digitizing the measurement and customization workflow for tape-in and clip-in systems. Direct-to-consumer brands deploy smartphone-based imaging to generate precision width and density specifications without salon visits. This capability is digitizing the traditional fitting process that previously required 45-60 minute in-person consultations.
ECHA's REACH enforcement expansion now mandates full chemical inventory disclosure for cyanoacrylate-based bonding adhesives and solvent-based removers. Manufacturers serving European professional channels must reformulate to eliminate methylene chloride and toluene residues. Salon-only distributors in Germany and the Netherlands are consolidating supplier lists to partners with certified safety data sheet compliance.
Subscription replenishment models are displacing one-time retail purchases for synthetic and human hair clip-in sets. Consumers in urban US and UK markets now receive quarterly color-matched shipments aligned to seasonal tone shifts. This pattern concentrates lifetime value capture with vertically integrated brands that control raw sourcing through finished fulfillment.
Hair Extension Market Segmentation
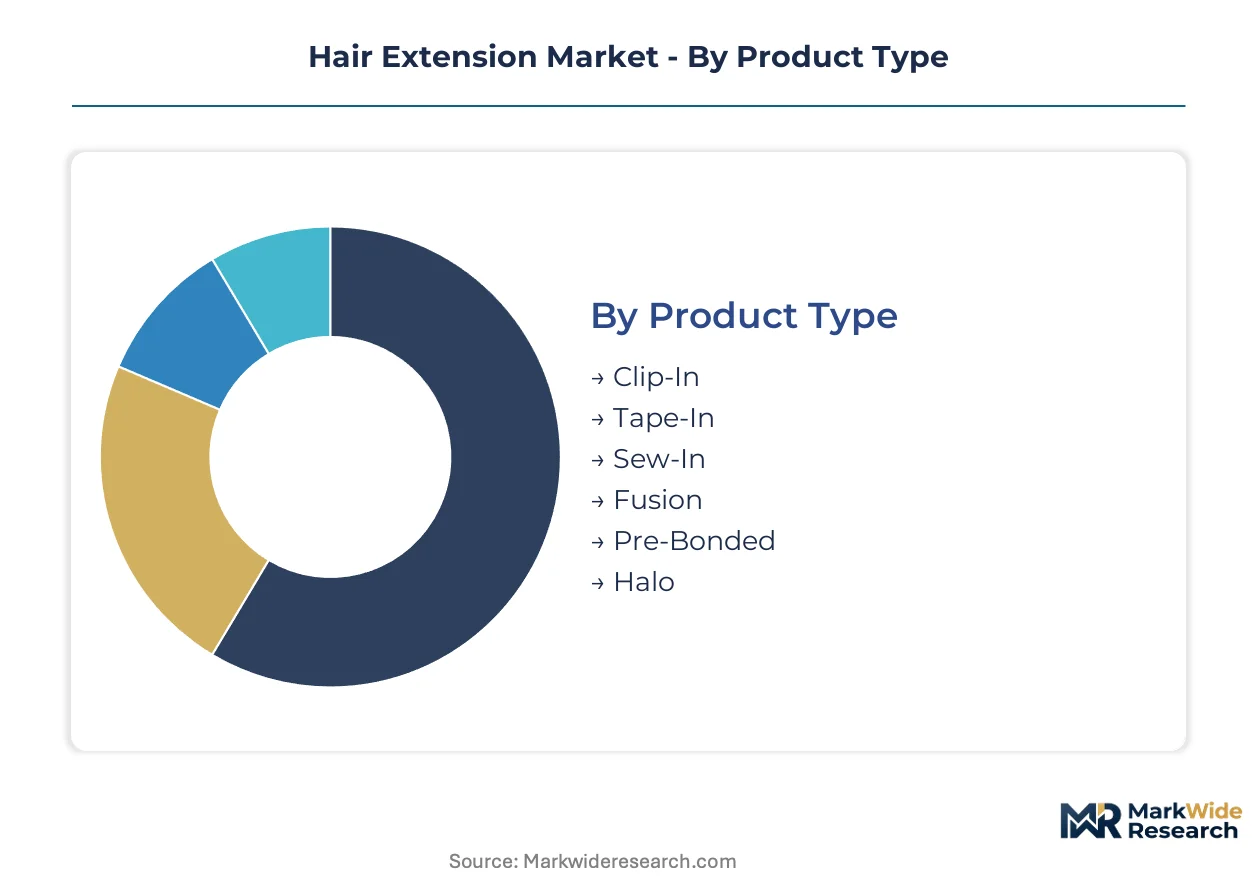
Hair extension segmentation reveals how attachment mechanics, material grades, and channel economics split demand across radically different price points and service models. Understanding these divides exposes where margin pools concentrate and which technology shifts threaten incumbent positions.
Product Type:
The use-case spectrum spans temporary self-application to semi-permanent salon installation, with attachment durability directly mapping to labor embedment and price tier.
- Clip-In:Mechanical pressure clips attach wefts to natural hair roots without adhesive or heat tools, enabling 10-minute self-installation and same-day removal. Demand concentrates in direct-to-consumer e-commerce channels across the United States and United Kingdom, where subscription replenishment models now displace one-time retail purchases as consumers align shipments to seasonal color shifts.
- Tape-In:Medical-grade adhesive strips sandwich thin weft sections between natural hair layers, delivering 6-8 week wear with seamless root blending. Salon service integration in Germany and France bundles tape installations with root touch-ups and balayage treatments, embedding extensions into recurring appointment calendars rather than standalone transactions.
- Sew-In:Braided anchor rows secure wefted hair via needle-and-thread attachment, preferred for textured and coily hair types requiring protective styling.
- Fusion:Keratin protein bonds fused with ultrasonic or heat tools create individual strand attachment lasting 3-4 months.
- Pre-Bonded:Factory-applied keratin tips reduce salon preparation time and standardize bond consistency across installations.
- Halo:Invisible wire crowns suspend weft sections across the occipital ridge, offering damage-free daily wear for thinning hair concealment.
The dominant share belongs to Clip-In, while Tape-In is closing the gap fastest through salon service bundling.
Material:
Cost tier stratification separates raw material provenance into six distinct quality grades, each commanding discrete distribution channels and end-user expectations.
- Remy Human Hair:Cuticle-aligned strands collected from single donors preserve unidirectional scale layering, eliminating tangling and enabling 12-18 month reuse cycles with proper maintenance. Henan province processors in Xuchang and surrounding prefectures capture 70% of global remy supply chain value through concentrated collection, sorting, and acid-treatment infrastructure.
- Synthetic Fiber:Heat-resistant polymer formulations from Korean and Japanese chemical producers mimic remy texture at 40% lower unit cost, pressuring human hair volume in mass retail channels.
- Virgin Human Hair:Unprocessed single-donor strands retain natural color and texture without chemical alteration, commanding premium positioning in professional salon channels.
- Non-Remy Hair:Multi-source collected strands with misaligned cuticles require acid stripping and silicone coating to achieve manageable texture.
- Heat Resistant Fiber:Modified polymer blends withstand styling tool temperatures up to 180°C, bridging performance gaps between standard synthetics and human hair.
- Animal Hair:Yak and horsehair variants serve specialty theatrical and costume applications requiring extreme length or structural rigidity.
Remy Human Hair commands the premium tier by volume, though Synthetic Fiber is gaining share fastest through polymer innovation.
Application:
Volume concentration tracks channel economics, with professional service integration converting occasional purchases into recurring revenue streams.
- Salon Use:Licensed stylists perform fusion, tape-in, and micro-bead installations with certified technique protocols, embedding labor cost into total service pricing. ECHA REACH compliance mandates for bonding adhesives and solvent removers are forcing formulation upgrades that premiumize European professional tiers and squeeze unqualified suppliers from distribution.
- Personal Use:Self-applied clip-in and halo systems dominate direct-to-consumer channels, with 3D scalp-scanning technology now digitizing measurement workflows previously requiring 45-60 minute in-person consultations.
- Photo Shoots:Editorial and commercial photography demands rapid color and length transformation without long-term wear commitment.
- Fashion Shows:Runway calendars drive limited-edition capsule releases tied to seasonal collection launches.
- Film Industry:Production designers specify custom-matched systems for period accuracy and character continuity.
- Special Events:Wedding and gala occasion styling concentrates demand in metropolitan salon clusters.
Salon Use retains the largest volume position, while Personal Use is expanding most quickly through digital fitting tools and subscription logistics.
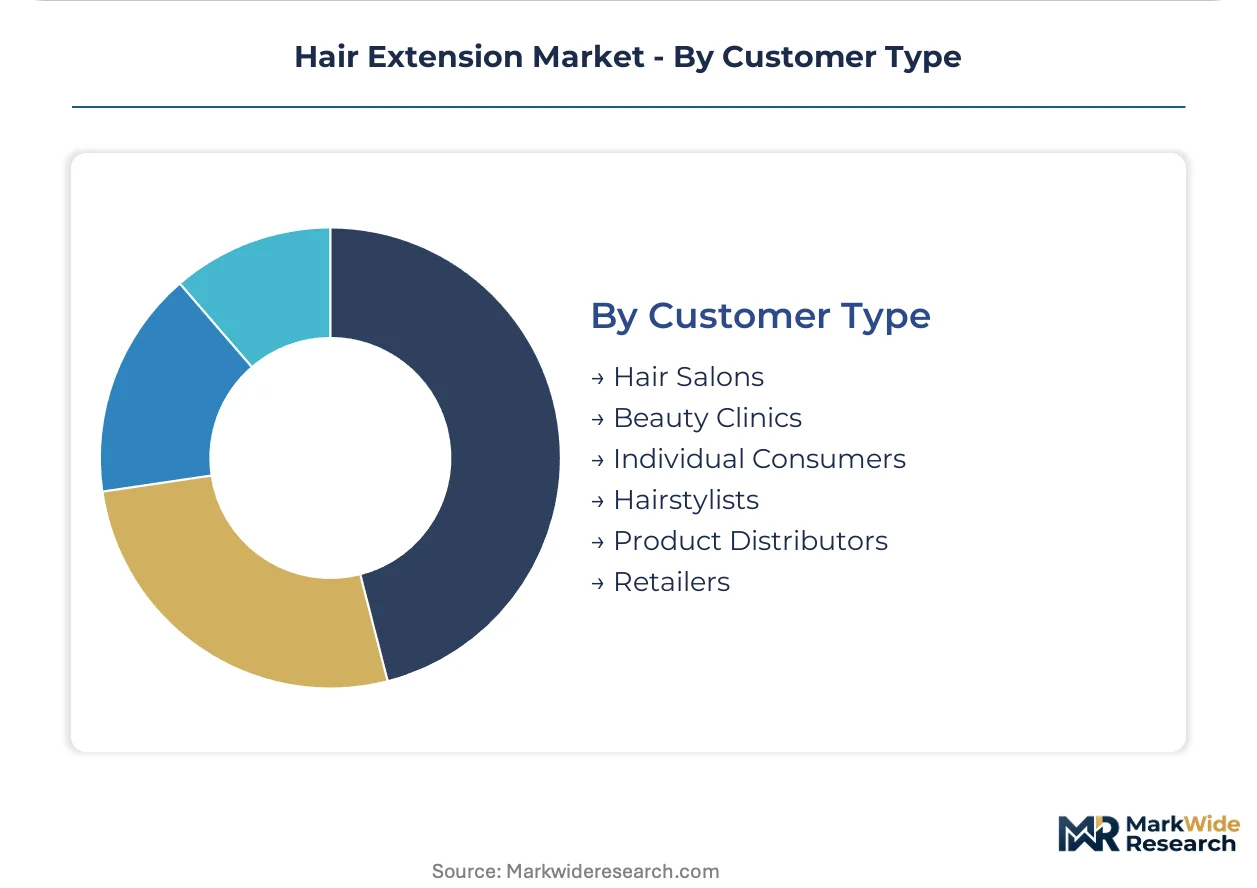
Customer Type:
Margin capture varies sharply across B2B service providers, institutional buyers, and individual consumers with divergent technical sophistication and price sensitivity.
- Hair Salons:Full-service establishments bundle extension installation with color, cut, and treatment menus, converting standalone purchases into recurring appointment relationships. Certified installation technician scarcity for keratin fusion and micro-bead methods creates 40-60 hour training bottlenecks that accredited academies in Italy and the United States struggle to scale against demand.
- Beauty Clinics:Medical-aesthetic crossover providers serve oncology patients and alopecia sufferers in France and Germany, where national health frameworks cover cranial prosthetics including custom-fitted systems.
- Individual Consumers:Direct purchasers span self-applied clip-in users to salon clients seeking maintenance products between appointments.
- Hairstylists:Independent contractors purchase wholesale for mobile or booth rental service models.
- Product Distributors:Regional wholesalers manage inventory and logistics for salon-only and retail channels.
- Retailers:Mass-market and specialty stores stock synthetic and entry-level human hair for self-selection purchase.
Hair Salons anchor the value chain, while Beauty Clinics are climbing the fastest through medical application expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: European salons prioritize certified installation protocols, American consumers favor direct-to-consumer subscription models, and Chinese processors control upstream raw material flows. These structural differences shape how value distributes through the value chain.
United States
FDA cosmetic labeling rules govern claims around "human hair" origin and synthetic blend ratios, creating compliance costs that deter small importers. Direct-to-consumer brands deploy 3D scalp-scanning technology to digitize fitting workflows previously requiring in-person consultations. Subscription replenishment models now displace one-time retail purchases in urban coastal markets.
Germany
ECHA REACH enforcement mandates full chemical inventory disclosure for cyanoacrylate-based bonding adhesives and solvent removers. Salon-only distributors consolidate supplier lists to partners with certified safety data sheet compliance. Beauty clinics in Berlin and Munich serve oncology patients where national health frameworks cover cranial prosthetics.
China
GB standards administered by SAMR set burn-test and labeling baselines that export-oriented processors must satisfy for cross-border clearance. Xuchang and surrounding Henan prefectures concentrate raw human hair collection, sorting, and acid-treatment infrastructure capturing the majority of global remy supply chain value.
France
ANSM oversees medical-aesthetic crossover providers serving alopecia sufferers through reimbursable channels under national health coverage. Paris fashion house heritage drives limited-edition capsule releases tied to runway calendars. Stylists in the capital bundle tape-in installations with root touch-ups and balayage treatments.
United Kingdom
Self-applied clip-in systems dominate direct-to-consumer e-commerce channels where quarterly color-matched shipments align to seasonal tone shifts. London metropolitan salon clusters concentrate demand for special events styling. Post-Brexit customs classification disputes around raw versus processed hair categories trigger duty exposure at Rotterdam transshipment points.
Hair Extension Market Key Industry Players
Capability concentration sits with Italian bonding technology specialists and Chinese raw material processors; scale advantage sits with vertically integrated manufacturers controlling collection through fulfillment. The vendor base organizes into three strategic archetypes: heritage fashion house licensees, backward-integrated raw material processors, and direct-to-consumer digital natives. Competitive moves center on M&A to secure donor hair supply agreements and technology licensing partnerships for magnetic attachment systems.
Among heritage-positioned players, Great Lengths Universal Hair Extensions and Balmain Hair Group exemplify the premium salon-only distribution archetype. Henan Rebecca Hair Products represents the backward-integrated processor model with captive supply of remy and virgin grades. These three anchors illustrate how geographic origin—Italian, French, and Chinese respectively—correlates with strategic positioning across the value chain.
| Leading Market Players |
|---|
| Great Lengths Universal Hair Extensions |
| Balmain Hair Group |
| Henan Rebecca Hair Products |
| Hairdreams |
| Bellami Hair |
| Indique Hair |
| Evergreen Products Group Limited |
| SO.CAP. Original USA |
| Hair Visions International |
| Others |
Cost & Logistics Intelligence
Idle capacity at Xuchang processing clusters is forcing Henan-based processors to absorb margin compression while European salon distributors exploit formulation compliance gaps to premiumize adhesive tiers. This utilization imbalance creates divergent pricing power between raw material processors and certified downstream distributors.
Pricing Analysis
Contract-based long-term offtake agreements dominate raw remy procurement between Xuchang processors and Italian bonding specialists, while spot-market transactions govern synthetic fiber sourcing from Korean chemical producers. Price differentiation separates cuticle-aligned virgin grades from acid-stripped non-remy tiers, with certification investment in REACH-compliant bonding systems commanding premium positioning. Cost compression in synthetic segments is intensifying because heat-resistant polymer innovation narrows performance gaps with human hair at 40% lower unit economics. Individual consumers purchasing self-applied clip-in systems exhibit highest price sensitivity, whereas salon channels embedding labor into bundled service pricing demonstrate lowest sensitivity to raw material fluctuations.
Supply Chain Analysis
Export-control friction around dual-use chemical precursors limits cyanoacrylate adhesive flows from Chinese manufacturers into European professional channels, forcing reformulation partnerships with certified German and Italian compounders. Geographic supply concentration centers on China for raw human hair collection and acid-treatment infrastructure, Italy for keratin bonding technology, and South Korea for heat-resistant synthetic fiber production. Raw material dependencies include single-donor hair collection networks, medical-grade adhesive polymers, and ultrasonic fusion equipment components. Single-source vulnerability in Xuchang's 70% concentration of global remy processing creates tariff exposure and customs classification disputes at Rotterdam and Los Angeles ports. Distribution runs through salon-only certified networks in Europe, direct-to-consumer e-commerce platforms in the United States and United Kingdom, and wholesale beauty supply channels for mass-market synthetic tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across male grooming and medical-aesthetic crossover segments as discrete consultation protocols and reimbursable cranial prosthetic channels create defensible niches outside saturated female consumer markets.
For Market Incumbents: Insulate salon-only positioning by deepening captive supply agreements with Xuchang processors and accelerating REACH-compliant adhesive certification investments that squeeze unqualified competitors from European distribution. Threat from magnetic attachment direct-to-consumer innovators demands preemptive technology licensing partnerships or acquisition of adjustable pressure-fit patent portfolios.
For New Entrants and Emerging Players: Build out underpenetrated male grooming infrastructure through discrete metropolitan salon consultation protocols modeled on South Korean metro chains, targeting hair loss concealment and volume augmentation demand outside traditional female segments. Medical-aesthetic crossover in France and Germany offers reimbursable channel access with lowest competitive density; partner with oncology centers and alopecia specialists for custom-fitted system distribution.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated brands controlling raw sourcing through subscription replenishment logistics; these archetypes concentrate lifetime value capture as quarterly color-matched shipments displace one-time retail purchases. Long-term viability over the projection horizon favors processors with backward integration into donor collection networks and certified salon distributors with exclusive territory agreements. Signal to monitor: customs classification rulings on raw versus processed hair categories that would shift duty exposure and origin-documentation burdens across the value chain.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Donor Collection Networks | Henan Rebecca's captive supply of remy grades demonstrates margin control against volatile 18-24 month price cycles. |
| REACH-Compliant Adhesive Reformulation | ECHA enforcement is squeezing unqualified suppliers from German and Dutch salon distribution channels. |
| Subscription Replenishment Model Launch | Quarterly color-matched shipments align to seasonal tone shifts and concentrate lifetime value with vertically integrated brands. |
| Magnetic Attachment Technology Licensing | Eliminates salon dependency for semi-permanent wear and opens 48-hour direct-to-consumer delivery models. |
| Medical-Aesthetic Channel Partnership | France and Germany national health frameworks cover cranial prosthetics for oncology and alopecia patients. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with salon owners, certified installation technicians, raw material procurement managers at Henan processors, and adhesive formulation chemists; and secondary validation through customs trade records, SAMR GB standard filings, ECHA REACH registration databases, and FDA cosmetic labeling guidance documents. Bottom-up triangulation across attachment method segmentation and top-down reconciliation against end-use channel economics anchored volume and value estimates.
Forecast inputs considered salon service integration velocity, synthetic fiber substitution rates, and regulatory compliance cost pass-through across the projection horizon. Segmentation dimensions modeled include attachment mechanics, material grade tiers, channel structure, and geographic regulatory clusters. CAGRs derived from historical growth pattern analysis adjusted for penetration ceiling effects in mature markets and infrastructure buildout trajectories in emerging segments. Industry-specific inputs incorporated donor hair availability cycles and certified technician training pipeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer magnetic attachment innovators or subsidized synthetic fiber producers would shift outcomes beyond modeled ranges. Material shifts in customs classification rulings on raw versus processed hair, or ECHA enforcement expansion into additional chemical categories, would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Canada Hair Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Protein Shampoo Market
Hair Care
Japan Hair Care Market
Hair Care
Artificial Hair Integration Market
Hair Care
Global Hair Color Market
Hair Care
India Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
North America Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Sweden Hair Care Market
Hair Care
Hair Care Market