
 Hair Serum Market | 2026-2036
Hair Serum Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Serum Market Intelligence
The hair serum category is pivoting along a widening gap between prestige biotech-infused treatments and mass-market silicone blends. L'Oréal S.A. anchors its position through captive biotechnology labs that develop keratin-mimetic peptides. Unilever PLC competes by leveraging scale economics across its water-based formulation lines. Kao Corporation differentiates through JIS-compliant manufacturing standards that sustain premium positioning in Asian export markets.
Hair serum denotes a concentrated topical preparation, typically comprising active complexes at 2-8% weight concentration in a carrier base of cyclomethicone or aqueous gel, designed to deposit conditioning agents onto the cuticle layer without rinse-off. Its primary commercial purpose is to deliver targeted cosmetic benefits—frizz control, thermal protection, or bond repair—between wash cycles. The oil-based formulation segment occupies established margin pools among consumers with coarse or chemically treated hair, while water-based serums lead volume expansion due to lighter sensory profiles favored by Asian markets. Online distribution channels are accelerating fastest, though beauty salons retain pricing power through professional endorsement and in-salon application services.
The FDA governs cosmetic labeling and ingredient safety under the Federal Food, Drug, and Cosmetic Act, while the EU enforces REACH registration and the EU Green Deal's sustainable chemistry mandates that restrict petrochemical-derived silicones. China's NMPA and GB standards for cosmetics impose separate safety assessment requirements that fragment product registration costs for multinational portfolios. Stakeholders must monitor evolving ingredient disclosure rules across the FDA, ECHA, and SAMR to determine whether centralized or regional formulation strategies minimize compliance burden.
Market Dynamics
Professional salons in the United States and Germany are accelerating procurement of bond-repair formulations as post-chemical treatment care becomes a standard service tier, compressing demand for basic silicone-based alternatives and forcing reformulation investments across manufacturing networks.
Growth Catalysts
- EU REACH Registration:The EU's chemical safety framework is accelerating ingredient transparency investments, pushing manufacturers toward documented biotech-derived actives that command premium positioning in European retail channels.
- Keratin-Mimetic Peptide Synthesis:Biotechnology labs in Switzerland and Massachusetts are scaling peptide production for bond-repair serums, creating supply security for professional salon chains seeking clinically validated claims.
- Urban Premium Consumer Concentration:Dense metropolitan clusters in Seoul, New York, and London generate concentrated demand for high-performance hair repair solutions between salon visits.
Market Restraints
- Cyclomethicone Supply Concentration:Petrochemical-derived silicone feedstock production clusters in Texas and Rotterdam create input cost volatility when energy markets fluctuate.
- Biotech Peptide Manufacturing Bottleneck:Fermentation capacity for custom peptides remains limited to specialized facilities in Basel and Cambridge, constraining formulation scale-up for mass-market penetration.
- China NMPA Registration Burden:Separate safety dossier requirements for each active ingredient fragment product registration timelines and inflate compliance costs for multinational portfolios seeking market entry.
Strategic Opportunities
- Water-Based Formulation Expansion:Lighter sensory profiles favored by consumers in Japan and South Korea present volume growth potential as manufacturers reformulate away from heavy silicone bases.
- Online Direct-to-Consumer Channels:E-commerce platforms are capturing share from traditional beauty retail, enabling subscription models that lock in recurring serum purchases.
- EU Green Deal Chemistry Mandates:Sustainable chemistry incentives are creating competitive advantage for manufacturers with bio-based carrier systems and carbon-accounted supply chains.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise spanning biotech actives and sensory engineering concentrates in Basel, New Jersey, and Osaka, creating recruitment competition among manufacturers.
- Multi-Jurisdiction Labeling Complexity:Divergent ingredient disclosure rules across FDA, ECHA, and SAMR require parallel packaging runs that inflate production overhead.
- Legacy Silicone Inventory Stranding:Manufacturers holding cyclomethicone stock face write-down pressure as clean-beauty positioning accelerates consumer rejection of petrochemical-derived bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Serum Market |
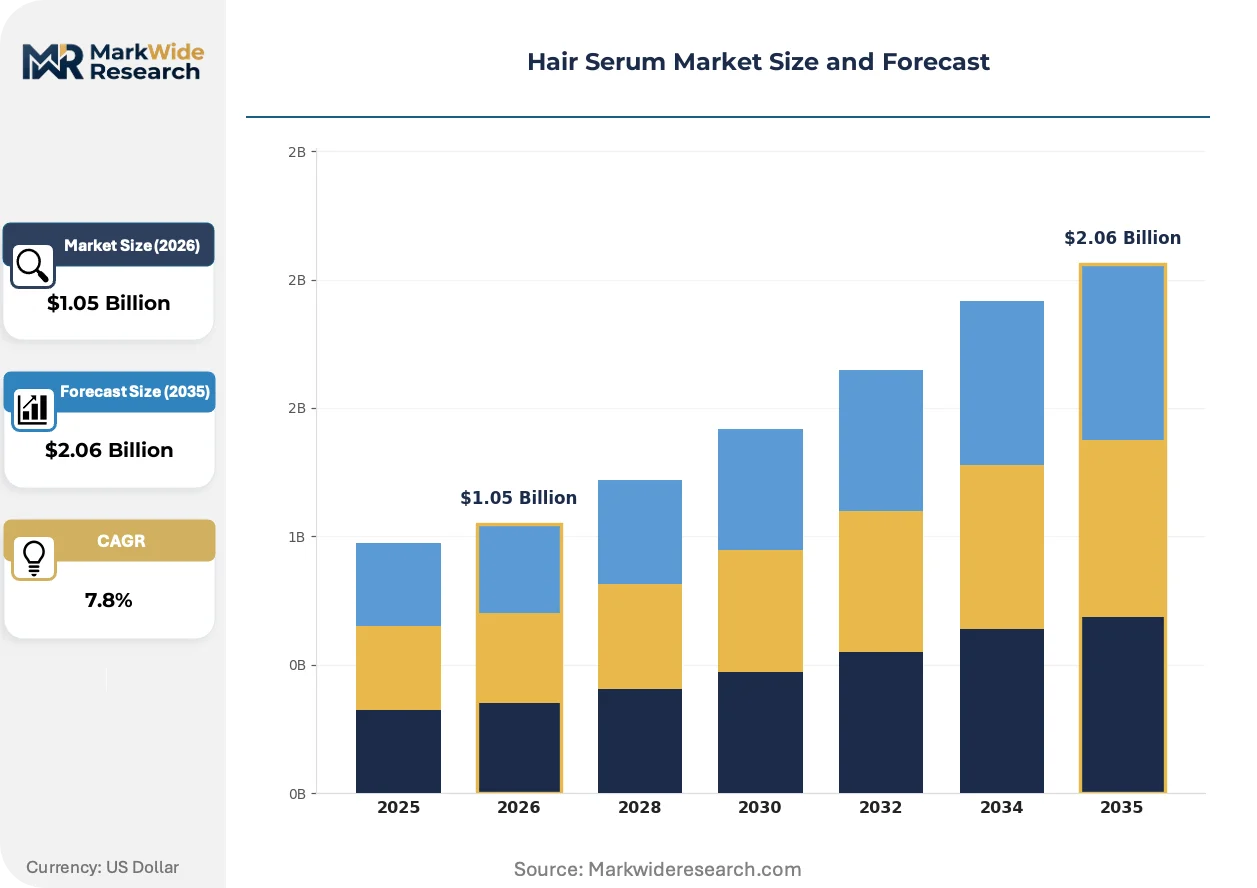
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizing, Smoothing, Volumizing, Regeneration Formulation: Oil-based, Water-based, Gel, Cream Distribution Channel: Online, Supermarkets, Beauty Salons, Pharmacies Target Audience: Women, Men, Children, Professionals |
| Companies Covered | Henkel AG & Co KGaA, Revlon Consumer Products Corporation, L'Oréal S.A, Redken, John Paul Mitchell Systems, Unilever PLC, Kao Corporation, Giovanni Cosmetics, The Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Serum Market Strategic Shifts & Innovations
Biotechnology-derived actives are displacing conventional conditioning chemistry across premium formulation tiers, while regulatory pressure on petrochemical ingredients and channel fragmentation between professional salons and direct-to-consumer platforms are simultaneously reshaping competitive positioning.
Peptide-based bond repair technology is modularizing how manufacturers construct serum efficacy claims. Custom keratin-mimetic sequences developed through solid-phase synthesis allow formulators to target specific damage mechanisms—thermal, chemical, or mechanical—within unified product architectures. Professional salon chains in Germany and the United States are adopting these modular systems to differentiate service tiers. The technology is modularizing supply chain relationships, enabling smaller brands to access previously captive biotechnology through contract manufacturing partnerships rather than internal R&D infrastructure.
REACH authorization requirements for cyclic siloxanes are forcing systematic ingredient substitution across European manufacturing. ECHA's restriction roadmap for D4, D5, and D6 compounds has compressed acceptable formulation timelines, with downstream consequences for global product lines that share packaging and labeling. Asian export manufacturers serving EU markets are most affected, accelerating partnerships with bio-based emollient suppliers to maintain market access without parallel inventory systems.
Subscription-based replenishment models are capturing serum consumers who previously purchased through periodic retail visits. Direct-to-consumer platforms in the United Kingdom and Australia are bundling diagnostic tools—porosity tests, damage assessments—with automated reorder algorithms that lock in brand loyalty. Professional salons are responding with membership programs that include take-home serum allocations, preserving their intermediary position through service bundling rather than transactional product sales.
Hair Serum Market Segmentation
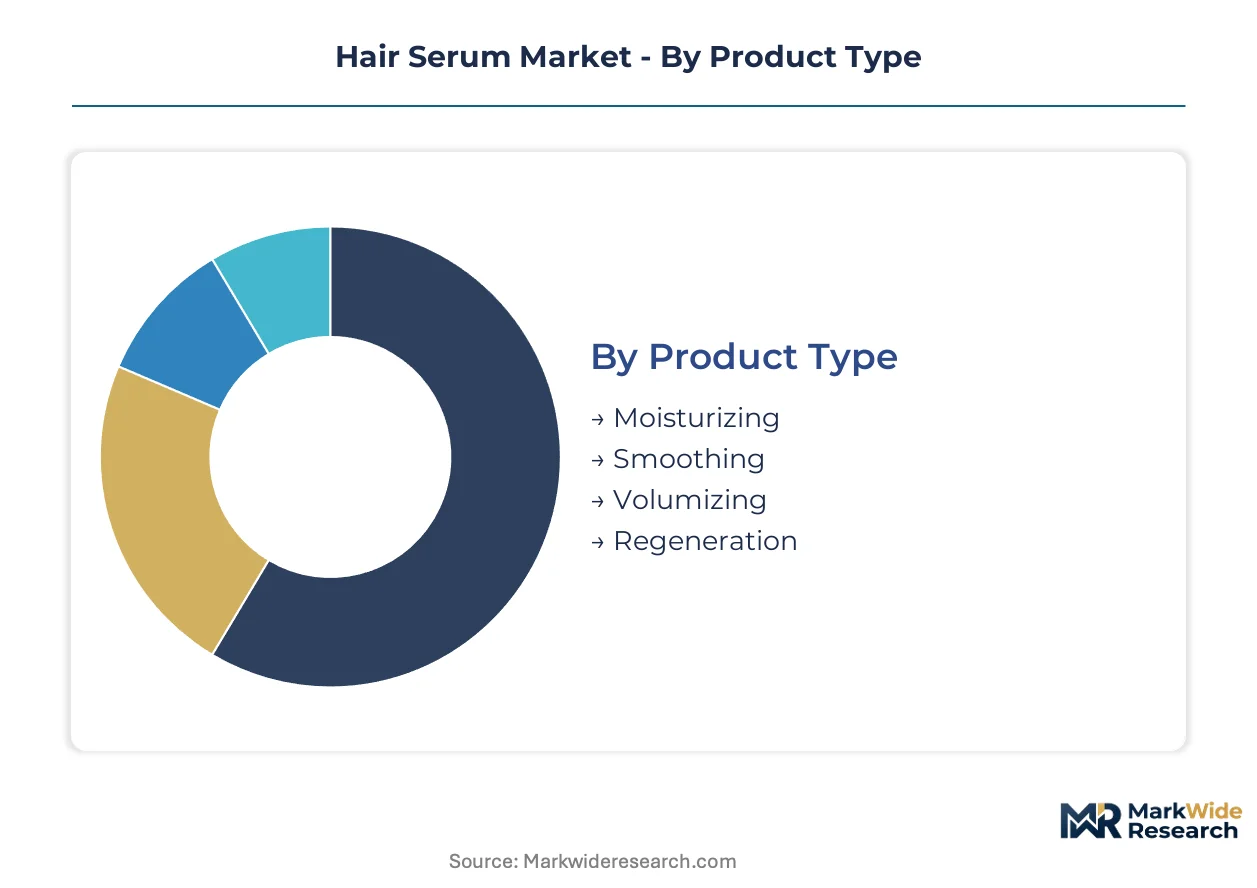
Hair serum segmentation reveals how formulation chemistry and channel access determine regulatory burden and margin capture. Product architecture and distribution pathway choices cascade through compliance requirements, manufacturing scale, and consumer pricing tolerance.
Product Type:
FDA cosmetic labeling rules apply uniformly across functional claims, yet ECHA REACH registration intensifies for bond-repair actives in Regeneration variants versus basic conditioning claims.
- Moisturizing:Glycerin and hyaluronic acid-based humectants at 3-7% concentration address routine dryness between wash cycles. Demand clusters in Seoul and Mumbai among consumers with chemically treated hair seeking daily hydration maintenance.
- Smoothing:Silicone-dominant or plant-derived emollient systems reduce friction and static. Professional salons in Germany and the United States specify these for post-blow-dry finishing services where tactile immediatey drives repurchase.
- Volumizing:Lightweight polymers coat individual strands without weight accumulation. Asian markets favor these formulations for fine hair textures.
- Regeneration:Peptide and keratin-mimetic complexes target cortex-level repair. Premium positioning requires clinical validation dossiers for EU and China NMPA entry.
Leading the category by volume: Moisturizing. Growing fastest: Regeneration.
Formulation:
Cost tier stratification separates premium biotechnology carriers from commodity silicone bases, with mid-tier aqueous systems capturing volume expansion.
- Oil-based:Concentrated lipid esters and botanical oils deliver intensive conditioning for coarse or Afro-textured hair. Consumers in Lagos and São Paulo sustain margin pools through willingness to pay for visible shine and manageability.
- Water-based:Aqueous gel matrices with 2-5% active loading enable lighter sensory profiles. Japanese and South Korean manufacturers lead technical development here, with domestic consumers rejecting heavy residue.
- Gel:Carbomer-thickened systems offer precise application control. Professional stylists specify these for targeted scalp-to-end distribution.
- Cream:Emulsion-based hybrids bridge serum and leave-in conditioner categories. Mass-market penetration concentrates in supermarket retail channels.
Highest margin capture: Oil-based. Steepest volume expansion: Water-based.
Distribution Channel:
Application context determines whether professional endorsement or convenience purchasing dominates consumer decision architecture.
- Online:Direct-to-consumer platforms enable subscription replenishment and diagnostic bundling. Australian and United Kingdom retailers deploy porosity-matching algorithms that automate reorder cycles.
- Supermarkets:Mass-market placement demands price compression and simplified claims. These channels sustain volume for basic silicone-based formulations.
- Beauty Salons:In-salon application services preserve pricing power through professional endorsement. German salon chains are standardizing bond-repair serums as post-treatment care tiers.
- Pharmacies:Clinical positioning and dermocosmetic claims require substantiation dossiers. European pharmacy channels favor peptide-based actives with documented efficacy.
Dominant by revenue: Beauty Salons. Expanding most quickly: Online.
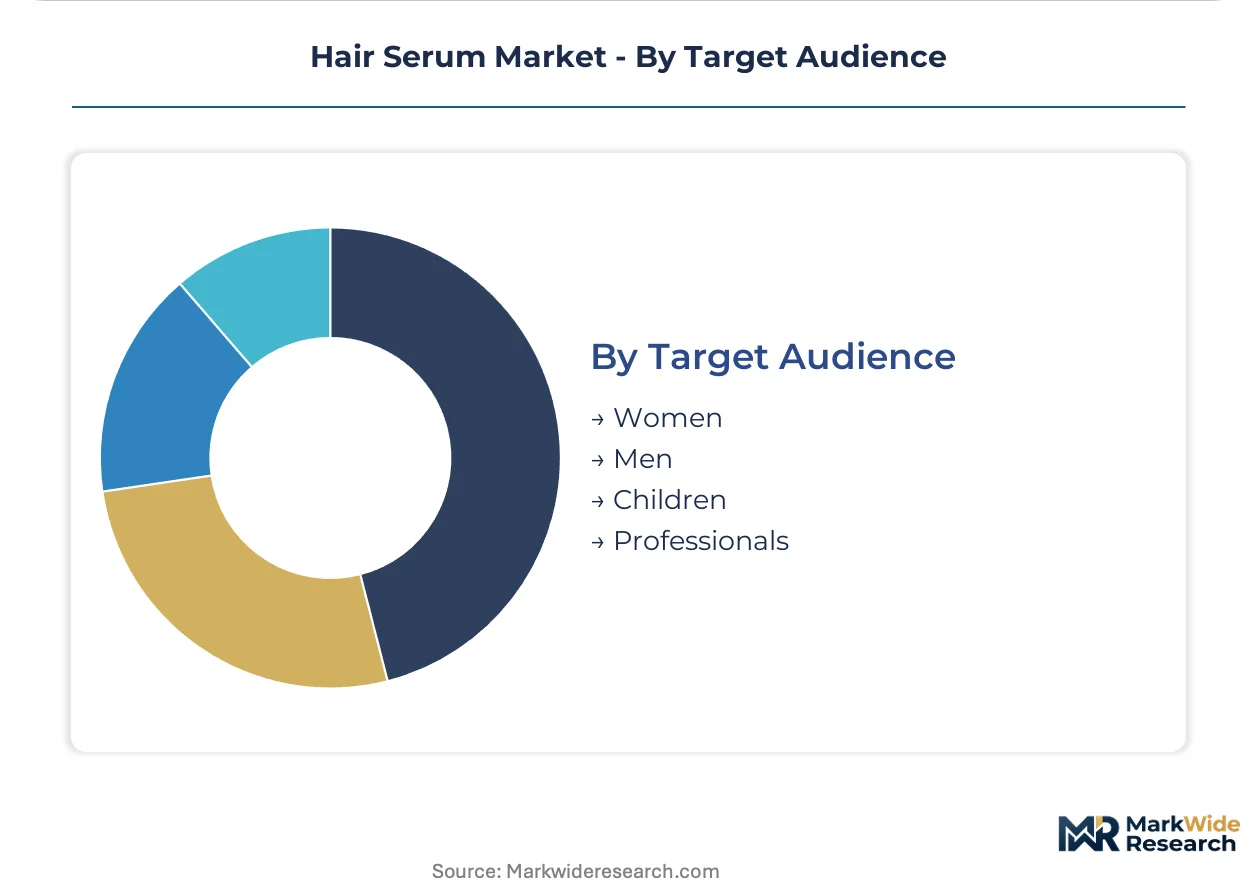
Target Audience:
Demographic specificity drives formulation customization and marketing resource allocation across gendered and occupational segments.
- Women:Historically dominant demand segment spanning all functional categories. Product development pipelines prioritize this audience with the broadest variant coverage.
- Men:Styling-focused serums with matte finish and scalp health positioning. Urban professionals in London and New York drive growth in gender-specific SKUs.
- Children:Hypoallergenic and tear-free formulations with minimal fragrance. Pediatric dermatologist endorsement requirements elevate regulatory burden.
- Professionals:High-frequency heat styling users require thermal protection and bond repair. Salon professionals themselves represent a concentrated B2B specification channel.
Largest absolute demand: Women. Gaining share fastest: Men.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York Metro anchors concentrated demand for clinically validated bond-repair serums among premium urban consumers. Seoul and London follow as dense metropolitan clusters generating high-frequency purchases between salon visits. Regulatory divergence across FDA, ECHA, and NMPA jurisdictions fragments formulation strategies for multinational portfolios.
United States
Professional salon chains in New York and Los Angeles are standardizing post-chemical treatment care tiers with peptide-based serums. FDA cosmetic labeling under the Federal Food, Drug, and Cosmetic Act governs ingredient disclosure without pre-market approval. Boston-area biotechnology labs supply keratin-mimetic peptides to national salon networks seeking substantiated repair claims.
Germany
ECHA REACH registration for cyclic siloxanes is accelerating systematic substitution of petrochemical-derived silicones in manufacturing facilities. The EU Green Deal's sustainable chemistry mandates incentivize bio-based carrier system investments. Frankfurt and Hamburg salon chains are procuring bond-repair formulations as standard post-treatment services.
Japan
Water-based formulation demand concentrates in Tokyo and Osaka where consumers reject heavy silicone residue on fine hair textures. METI oversees cosmetic safety alongside JIS-compliant manufacturing standards that sustain premium export positioning. Kansai-region formulators lead technical development of aqueous gel matrices with lighter sensory profiles.
China
NMPA and GB standards impose separate safety dossier requirements for each active ingredient, inflating registration timelines for multinational entrants. Shanghai and Beijing urban consumers drive demand for high-performance repair solutions between salon visits. Domestic manufacturers are partnering with bio-based emollient suppliers to maintain EU market access.
South Korea
MFDS regulates cosmetic ingredient safety while Seoul Capital Area consumers concentrate demand for lightweight, water-based serums. Domestic manufacturers leverage fermentation capacity for custom peptide production. Busan-Ulsan industrial corridors supply biotechnology-derived actives to regional formulation networks.
Hair Serum Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulation sophistication and channel access dimensions. The market structure consolidates around biotechnology-enabled specialists, scale-driven mass-market producers, and professional salon-captive brands. Three archetypes dominate: peptide synthesis laboratories with captive formulation pipelines, multinational consumer goods conglomerates leveraging water-based scale economics, and JIS-compliant Asian manufacturers serving export markets. Competitive intensity concentrates on M&A activity targeting fermentation capacity and strategic partnerships bridging biotech R&D with contract manufacturing scale.
Within the biotechnology-specialist tier, L'Oréal S.A. and Kao Corporation exemplify divergent geographic anchoring strategies. L'Oréal S.A. occupies a position tied to European peptide synthesis infrastructure. Kao Corporation represents Japanese JIS-compliant manufacturing standards sustaining premium Asian export positioning. Unilever PLC sits within the scale-driven archetype, leveraging water-based formulation lines across mass-market distribution. Henkel AG & Co KGaA and Revlon Consumer Products Corporation exemplify professional salon-captive and consumer retail channel strategies respectively.
| Leading Market Players |
|---|
| Henkel AG & Co KGaA |
| Revlon Consumer Products Corporation |
| L'Oréal S.A |
| Redken |
| John Paul Mitchell Systems |
| Unilever PLC |
| Kao Corporation |
| Giovanni Cosmetics |
| The Procter & Gamble Company |
| Others |
Cost & Logistics Intelligence
Peptide synthesis scale-up in Basel and Cambridge is compressing unit economics for bond-repair actives while simultaneously concentrating supply leverage among fermentation specialists. This dual transformation forces mid-tier formulators to absorb margin pressure or cede premium positioning to biotechnology-integrated competitors.
Pricing Analysis
Clinical validation tiers anchor value-based pricing across the Hair Serum Market, with peptide-backed regeneration serums commanding substantial premiums over silicone-based alternatives. Three-tier pricing structure across premium, standard, and economy levels separates substantiated bond-repair formulations from basic conditioning and mass-market silicone blends. Price differentiation rests on certification depth and biotechnology sourcing transparency. Cost compression in standard tiers is intensifying because cyclomethicone feedstock volatility transmits directly to manufacturing economics. Supermarket channels exhibit highest price sensitivity, while professional salons demonstrate lowest sensitivity due to service-bundled purchasing.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and Massachusetts-based fermentation facilities supplying custom keratin-mimetic peptides. Geographic supply concentration clusters in Switzerland, Japan, and the United States for biotechnology actives, with China and Germany dominating silicone precursor production. Raw material dependencies center on petrochemical-derived cyclomethicone, bio-based emollient alternatives, and solid-phase peptide synthesis reagents. Regulatory restriction through ECHA REACH authorization timelines for cyclic siloxanes presents structural supply risk. Distribution runs through professional salon networks for premium tiers and direct-to-consumer platforms for volume expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Hair Serum Market has become a vertical-integration race where captive peptide synthesis capabilities determine margin capture. Players are pursuing upstream control over fermentation capacity to secure supply and substantiate premium claims.
For Market Incumbents: Anticipate margin compression from contract-manufactured peptide alternatives by securing exclusive fermentation partnerships in Basel or Cambridge. Deepen backward integration into solid-phase synthesis infrastructure to defend biotechnology-enabled positioning against emerging biotech-specialist entrants. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models with diagnostic bundling to bypass established salon channel gatekeepers. White-space opportunity concentrates in water-based formulations for South Korean and Japanese consumers rejecting silicone residue. Target pharmacy channels in Germany with clinically substantiated regeneration claims requiring lower marketing investment than prestige retail. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational consumer goods conglomerates seeking biotechnology capabilities. Long-term viability favors fermentation-integrated specialists with documented peptide libraries and JIS or REACH-compliant manufacturing infrastructure. Watch ECHA restriction timeline acceleration on cyclic siloxanes as inflection indicator for bio-based carrier system valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Synthesis Capacity Expansion | Captive fermentation infrastructure secures supply for bond-repair formulations amid Basel and Cambridge bottlenecks. |
| Direct-to-Consumer Channel Launch | Subscription models with porosity-matching algorithms capture recurring revenue from Australian and United Kingdom consumers. |
| Bio-Based Carrier System Transition | ECHA REACH restrictions on D4-D6 siloxanes force systematic substitution to maintain EU market access. |
| Professional Salon Partnership Program | In-salon application services preserve pricing power through German and United States chain standardization. |
| Clinical Validation Dossier Investment | Substantiated efficacy documentation enables China NMPA entry and European pharmacy channel placement. |
Research Approach
Multi-period observation of peptide synthesis capacity utilization, salon procurement patterns, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with cosmetic formulators, professional salon chain procurement directors, biotechnology R&D leads, and retail category buyers. Secondary validation drew from ECHA REACH registration databases, FDA cosmetic labeling guidance, NMPA safety dossier records, and customs trade data for silicone feedstock flows. Bottom-up volume modeling triangulated against top-down market sizing across formulation chemistry tiers.
Segment-weighting applied product type, formulation base, distribution channel, and geographic regulatory cluster dimensions throughout the forecast period. CAGRs were derived from elasticity-adjusted demand projections incorporating urban premium consumer concentration indices and salon service tier adoption curves. Industry-specific inputs included fermentation capacity expansion timelines and ECHA restriction roadmap implementation phases.
Peptide manufacturing bottleneck persistence, REACH authorization timeline acceleration, and NMPA registration backlog clearance are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding biotechnology scale-up economics and regulatory implementation pacing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Global Professional Hair Care Market
Hair Care
Hair Care Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Extension Market
Hair Care
Hair Oil Market
Hair Care
Global Shampoo Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Asia-Pacific Shampoo Market
Hair Care
Hair Care Appliances Market
Hair Care
United States Hair Care Market
Hair Care
Hair and Scalp Care Market
Hair Care
India Hair Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Canada Hair Care Market
Hair Care
Europe Hair Care Market