
 North America Hair Care Market | 2026-2036
North America Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hair Care Market Analytics
Multi-source ingredient procurement is pivoting toward vertically integrated supply chains as brands seek traceability for botanical actives. Procter & Gamble leverages captive sourcing for sulfate-free surfactants across its mass-market portfolio. L'Oréal sustains R&D intensity through dedicated innovation centers in New Jersey and Montreal. Unilever anchors its North American position via specialized manufacturing for multicultural hair textures.
North America hair care encompasses formulations designed for cleansing, conditioning, styling, and scalp treatment of human hair, typically incorporating surfactants, emollients, polymers, and active ingredients at pH ranges between 4.5 and 6.5 to maintain cuticle integrity. These products serve consumer grooming needs across retail, professional, and medical dermatology channels. Shampoos and conditioners occupy the mature volume core, while styling products capture expanding margin pools through premiumization. The customer-type dimension reveals salons as the fastest-growing procurement segment, outpacing retail consumers as service-based hair health protocols gain traction. Distribution through specialty stores and online channels now exceeds supermarket velocity for premium and mid-range price tiers.
The FDA's Modernization of Cosmetics Regulation Act imposes facility registration and adverse-event reporting obligations that elevate compliance costs for new market entrants. Health Canada and the EPA jointly influence ingredient permissibility, with the former restricting certain preservatives and the latter governing volatile organic compound limits in aerosol styling products. State-level legislation in California under Proposition 65 adds disclosure requirements for trace contaminants. Stakeholders must monitor evolving federal rulemaking while calibrating regional formulation strategies.
Market Dynamics
Clean-label ingredient mandates under the FDA's Modernization of Cosmetics Regulation Act are compressing formulation development cycles while forcing supply chain reconfiguration across the United States and Canada.
Growth Catalysts
- Scalp-care protocol expansion:Professional salons in California and New York are integrating diagnostic scalp treatments into standard service menus, pulling premium product volumes through B2B procurement channels.
- REACH-aligned ingredient transparency:Cross-border alignment between Health Canada restrictions and emerging state-level disclosure rules is accelerating clean-label certification adoption among mid-tier brands.
- Biotechnology-derived surfactants:Fermentation-based alternatives to petrochemical sulfates are achieving cost parity, enabling mass-market reformulation without price tier disruption.
Market Restraints
- Botanical supply concentration:Premium active sourcing clusters in specific growing regions create weather-dependent input volatility for argan oil and quinoa protein derivatives.
- Aerosol VOC compliance:EPA volatile organic compound limits constrain styling spray innovation, forcing reformulation investment without commensurate price recovery mechanisms.
- Waterless format adoption barriers:Consumer habit formation lags behind powder shampoo and solid conditioner technical readiness, limiting manufacturer ROI on production line conversion.
Strategic Opportunities
- Multicultural texture specialization:Underpenetrated segments for coily and tightly curled hair textures in Canada present whitespace for texture-specific product ecosystems beyond current mass-market offerings.
- Professional channel captive distribution:Direct-to-salon supply relationships bypass retail margin compression while building brand equity through stylist recommendation authority.
- State-level green chemistry incentives:California's Proposition 65 disclosure requirements are creating competitive differentiation for preemptively compliant formulations in premium positioning.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise at the intersection of clean-label compliance and performance benchmarking commands premium compensation, constraining mid-cap R&D scaling.
- Facility registration timeline compression:FDA's Modernization of Cosmetics Regulation Act adverse-event reporting infrastructure demands capital deployment before revenue generation from new manufacturing assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hair Care Market |
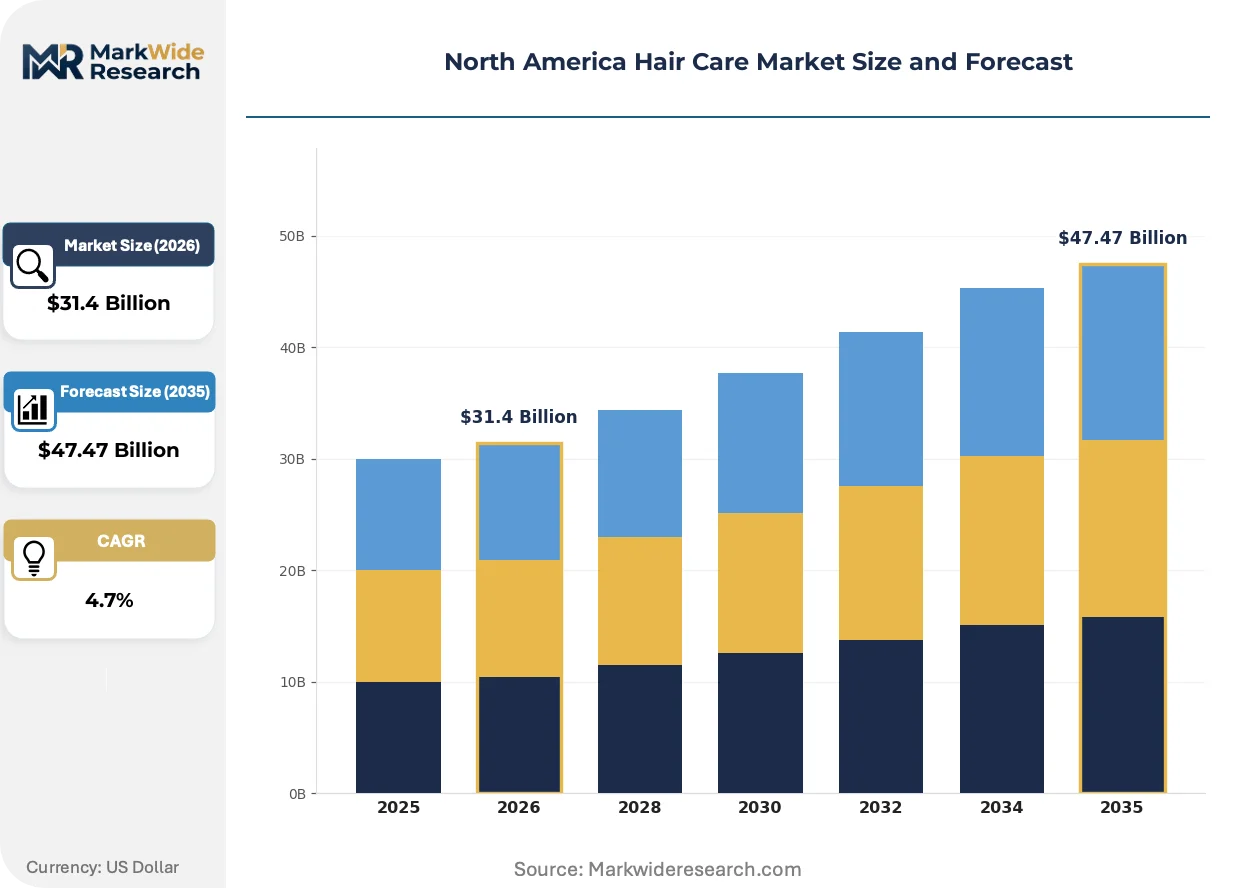
| Market Size in 2026 | $31.4 Billion |
| Market Size in 2035 | $47.47 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products Customer Type: Retail Consumers, Salons, E-commerce, Wholesale Price Tier: Premium, Mid-Range, Budget, Discount Distribution Channel: Online, Supermarkets, Drugstores, Specialty Stores |
| Companies Covered | Henkel, Shiseido Company, Procter & Gamble, John Paul Mitchell Systems, Kao Corporation, L'Oréal, Estee Lauder, Amway Corporation, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hair Care Market Evolving Landscape
Biotechnology and digital diagnostic tools are restructuring how products reach consumers and how efficacy is validated before purchase.
Precision fermentation for bio-identical keratin and ceramide production is decentralizing active ingredient sourcing away from agricultural supply chains. Mid-market brands in Texas and Florida are adopting these materials faster than legacy players, compressing the traditional 18-month formulation cycle toward 8-month iterations. This acceleration is fragmenting competitive advantage away from scale economies toward formulation agility.
The FDA's Modernization of Cosmetics Regulation Act facility registration and adverse-event reporting mandates are elevating compliance infrastructure to core competitive capability. Small and mid-sized manufacturers face disproportionate cost absorption, triggering consolidation pressure in the contract manufacturing sector. Professional salon brands with established quality systems are capturing market access advantages over direct-to-consumer entrants.
Subscription-based replenishment models are capturing recurring revenue from high-loyalty segments while displacing supermarket impulse purchases. Specialty retailers and brand-owned digital channels now dominate premium and mid-tier customer acquisition, with California and New York metropolitan areas showing highest subscription attachment rates. Service-based hair health protocols in professional channels are reinforcing this shift through prescribed home-care regimens.
North America Hair Care Market Segmentation
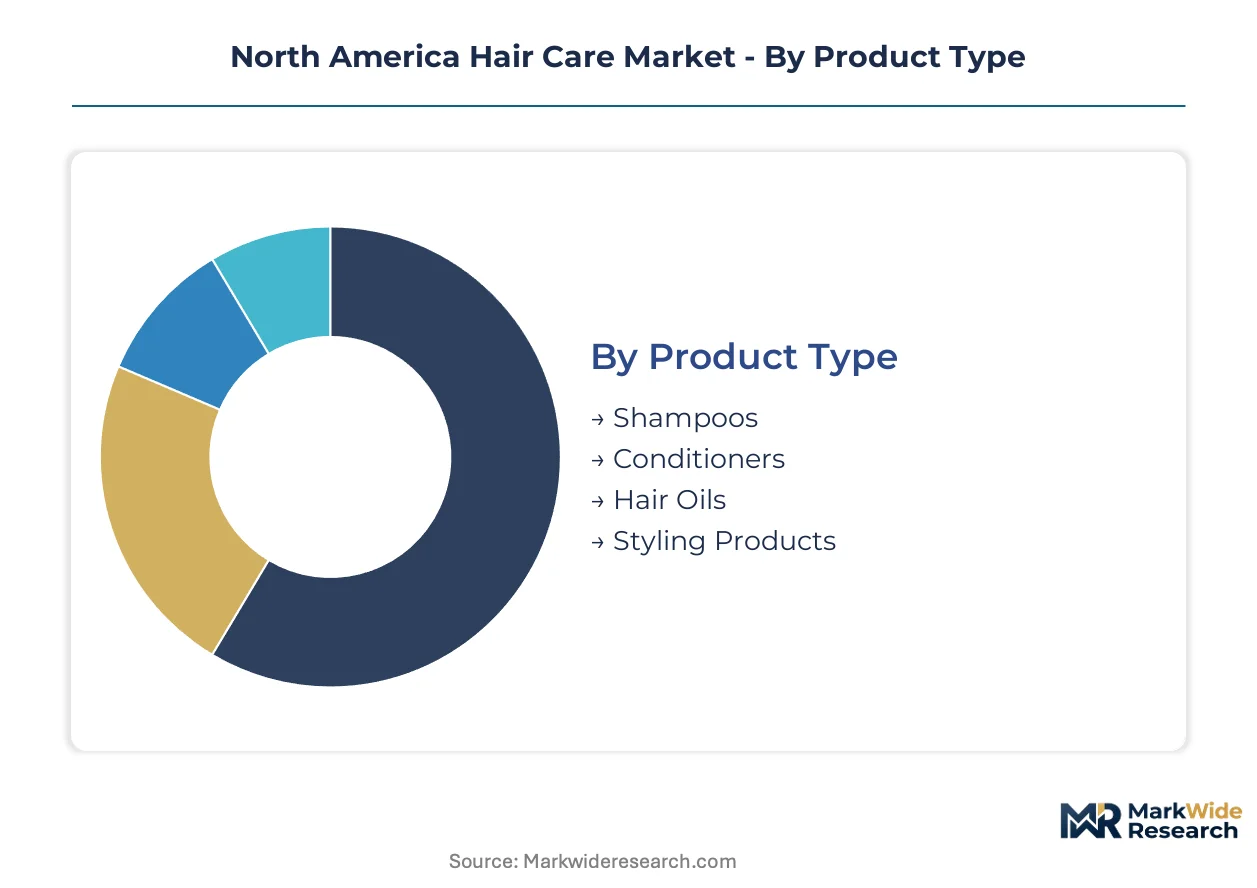
Hair care segmentation in North America reflects divergent paths between mass-market volume engines and precision-formulated premium tiers. Technology differentiation now separates segments more sharply than traditional price positioning, with biotechnology-derived actives and diagnostic-enabled protocols reshaping category boundaries.
Product Type:
Formulation chemistry and functional specification define competitive position across the four product categories, with pH optimization and active delivery systems serving as primary technical differentiators.
- Shampoos:Surfactant systems range from traditional sulfates to fermentation-derived alternatives, with pH buffering between 4.5 and 6.5 to preserve cuticle integrity. Mass-market procurement in Texas and Florida favors cost-optimized sulfate-free bases, while California salons specify diagnostic-matched cleansing protocols.
- Conditioners:Cationic emulsion technology incorporating ceramide complexes and hydrolyzed proteins dominates premium positioning. Professional channel demand in New York metropolitan salons pulls high-viscosity, leave-in formulations with specified slip coefficients for textured hair protocols.
- Hair Oils:Botanical lipid profiles from argan, jojoba, and marula sources concentrate in specialty retail and professional recommendation channels.
- Styling Products:Polymer film-formers and volatile organic compound-compliant aerosol systems serve distinct end-uses across retail and salon segments.
Mature deployment sits with shampoos and conditioners. Newer deployment is concentrated in styling products with biotechnology-derived hold polymers.
Customer Type:
Procurement authority and purchase frequency create four distinct demand profiles, with service-based channels gaining relative share against traditional retail.
- Retail Consumers:Supermarket and drugstore velocity remains substantial but declining in relative share, with California and New York consumers showing highest subscription-model attachment for replenishment cycles.
- Salons:Diagnostic scalp treatment integration and prescribed home-care regimens are expanding B2B procurement volumes. Professional recommendation authority commands premium pricing power that mass retail cannot replicate.
- E-commerce:Direct-to-consumer channels capture first-time trial and subscription conversion, with specialty ingredient transparency driving purchase decisions.
- Wholesale:Volume consolidation for multi-location salon chains and private-label manufacturing.
Established volume flows through retail consumers. Salons represent the steepest expansion trajectory for premium and professional-grade formulations.
Price Tier:
Cost positioning aligns with ingredient sourcing transparency and certification density rather than purely functional performance claims.
- Premium:Clean-label certification, biotechnology-derived actives, and supply chain traceability command shelf space in specialty stores and professional channels. California Proposition 65 preemptive compliance differentiates positioning.
- Mid-Range:Reformulated mass-market alternatives with selective clean-label attributes target conversion from budget tiers without full premium pricing.
- Budget:Volume-driven supermarket placement with conventional surfactant systems and minimal active ingredient loading.
- Discount:Price-competitive positioning through simplified formulations and private-label supply.
Premium tier deployment concentrates in coastal metropolitan markets. Mid-range tier is gaining share fastest as mass-market brands accelerate clean-label reformulation.
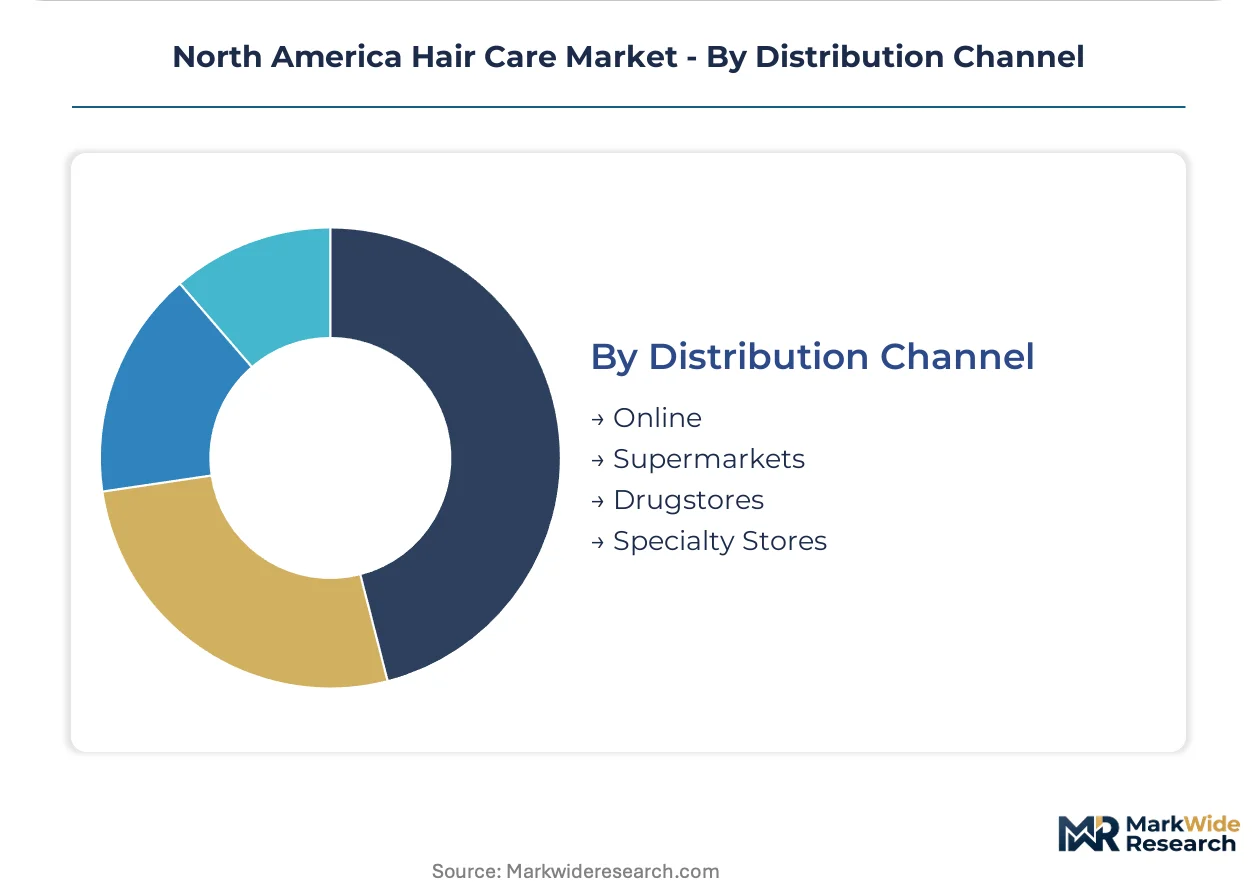
Distribution Channel:
Channel selection determines margin structure and consumer relationship depth, with digital and specialty formats displacing traditional supermarket dominance in premium tiers.
- Online:Subscription replenishment and direct-to-consumer trial capture recurring revenue with highest customer lifetime value metrics in California and New York.
- Supermarkets:Mass-market volume core with declining relative share as premium consumers migrate to specialty formats.
- Drugstores:Convenience-positioned mid-range and budget tier access with limited premium assortment depth.
- Specialty Stores:Curated premium and professional-grade selection with educated staff recommendation authority.
Supermarkets anchor mature volume distribution. Specialty stores and online channels are expanding most quickly for premium and mid-tier customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Botanical lipid sourcing from Moroccan argan cooperatives and Andean quinoa protein suppliers anchors North American formulation supply chains. FDA facility registration timelines and Health Canada ingredient restrictions are compressing new entrant market access across the region.
United States
California salons drive diagnostic scalp treatment adoption while New York metropolitan professionals command premium styling product volumes. FDA Modernization of Cosmetics Regulation Act adverse-event reporting infrastructure elevates compliance costs for contract manufacturers. The New Jersey innovation corridor concentrates biotechnology-derived surfactant R&D facilities serving mass-market reformulation cycles.
Canada
Multicultural texture specialization presents whitespace opportunity as coily hair protocols remain underpenetrated beyond mass-market offerings. Health Canada preservative restrictions align with emerging state-level disclosure rules, accelerating clean-label certification adoption. Montreal hosts dedicated innovation centers supporting cross-border formulation development for premium tier brands.
Mexico
Professional salon channel expansion in Mexico City and Guadalajara metro areas pulls B2B procurement volumes for prescribed home-care regimens. COFEPRIS cosmetic registration requirements create timeline friction for imported premium formulations. Northern border states concentrate contract manufacturing assets serving US retail private-label demand.
North America Hair Care Market Competitive Landscape
Global majors compete with regional champions across distribution channel access and formulation agility dimensions. The vendor base stratifies between scale-driven mass-market portfolios, professional-channel specialists, and biotechnology-enabled mid-tier disruptors. Three archetypes dominate: multinational CPG conglomerates with captive R&D infrastructure, salon-exclusive brands with stylist recommendation authority, and clean-label insurgents leveraging fermentation-derived actives. Consolidation pressure targets contract manufacturers facing FDA facility registration cost absorption, while strategic partnerships between ingredient biotech firms and mid-market brands accelerate formulation cycle compression.
Among multinational CPG conglomerates, Procter & Gamble, L'Oréal, and Unilever occupy positions defined by captive supply chain infrastructure and dedicated North American innovation assets. Procter & Gamble exemplifies scale-driven mass-market reformulation capability through internal sulfate-free surfactant production. L'Oréal represents professional-channel integration with innovation center investments in New Jersey and Montreal. Unilever anchors multicultural texture specialization through manufacturing assets configured for tightly curled hair protocol development.
| Leading Market Players |
|---|
| Henkel |
| Shiseido Company |
| Procter & Gamble |
| John Paul Mitchell Systems |
| Kao Corporation |
| L'Oréal |
| Estee Lauder |
| Amway Corporation |
| Unilever |
| Others |
Value Network & Pricing Analysis
Precision fermentation for bio-identical keratin and ceramide production is simultaneously compressing active ingredient costs and fragmenting supply concentration away from traditional agricultural clusters toward distributed biotech facilities.
Pricing Analysis
Service bundling separates professional salon channels from retail, with diagnostic scalp protocols and prescribed home-care regimens justifying premium positioning through stylist authority rather than standalone product pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification density and biotechnology-derived active loading. Cost compression in mass-market tiers intensifies as fermentation-based surfactants achieve parity with petrochemical alternatives. Retail consumers exhibit highest price sensitivity, while professional salons demonstrate lowest sensitivity due to recommendation-driven purchase authority.
Supply Chain Analysis
FDA facility registration and Health Canada ingredient qualification requirements create gating barriers that favor established manufacturers with pre-built compliance infrastructure. Raw material sourcing draws from Morocco for argan oil, Andean regions for quinoa protein derivatives, and New Jersey biotech clusters for fermentation-derived actives. Single-source vulnerability concentrates in weather-dependent botanical harvesting for premium lipid inputs. Distribution runs through direct-to-salon relationships for professional tiers, specialty retail for premium positioning, and mass retail for volume tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's Modernization of Cosmetics Regulation Act elevates facility registration and adverse-event reporting costs into a structural moat that protects compliant incumbents while filtering undercapitalized entrants.
For Market Incumbents: Cement market position by accelerating captive sourcing for sulfate-free surfactants and biotechnology-derived actives before cost parity erodes differentiation. Expand dedicated innovation center capacity in New Jersey and Montreal to compress formulation cycles below competitor response times. Prioritize direct-to-salon supply relationships that bypass retail margin compression and build stylist recommendation lock-in against clean-label insurgents.
For New Entrants and Emerging Players: California's Proposition 65 disclosure requirements open a window for preemptively compliant formulations that command premium positioning through transparency credentials rather than scale economies. Target multicultural texture specialization in Canada, where coily hair protocols remain underpenetrated beyond mass-market offerings. Pursue subscription-based replenishment models with ingredient transparency as the primary customer acquisition hook.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of contract manufacturers with established FDA adverse-event reporting infrastructure, as facility registration timelines compress new entrant market access. Long-term viability favors players with backward integration into fermentation-derived active production and professional channel distribution control. Monitor biotechnology cost parity achievement as the inflection signal for mass-market reformulation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | FDA Modernization of Cosmetics Regulation Act compliance creates barrier-to-entry moat for certified manufacturers. |
| Professional Channel Captive Distribution | Direct-to-salon relationships bypass retail margin compression while building stylist recommendation authority. |
| Biotechnology-Derived Active Sourcing | Precision fermentation for bio-identical keratin decentralizes supply away from agricultural weather dependency. |
| Multicultural Texture Specialization | Underpenetrated coily hair segments in Canada present whitespace beyond current mass-market offerings. |
| Subscription Replenishment Model Launch | Recurring revenue capture from high-loyalty segments displaces supermarket impulse purchase dependency. |
Research Methodology
Independent corroboration across cosmetic chemist interviews, professional salon procurement managers, and retail category buyers underwrites the qualitative findings on clean-label adoption trajectories. Secondary validation draws from FDA facility registration databases, Health Canada cosmetic ingredient hotlists, EPA volatile organic compound compliance records, and Nielsen retail audit data. Bottom-up segmentation modeling triangulates against top-down market sizing from trade customs and manufacturer revenue disclosures.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window, with CAGRs derived from segment-level trend extrapolation and regulatory impact assessment. Segmentation dimensions include product type, customer type, price tier, and distribution channel, with biotechnology adoption intensity modeled as an orthogonal technology dimension. Forecast inputs incorporate salon service protocol expansion rates and fermentation-based surfactant cost parity timelines.
The model assumes a particular technology adoption path; alternative pathways for solid and waterless format consumer acceptance would alter the outlook. Forecasts reflect assumptions on regulatory enforcement intensity and raw material supply stability. A model refresh is warranted upon material change in FDA facility registration timeline enforcement or biotechnology-derived active cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Care Appliances Market
Hair Care
Israel Hair Care Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Mask Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Europe Hair Care Market
Hair Care
Germany Hair Care Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Mexico Hair Care Market
Hair Care
Russia Hair Care Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Artificial Hair Integration Market