
 India Hair Care Market | 2026-2036
India Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
India Hair Care Market Insights
Domestic Ayurvedic formulation producers in Kerala and Rajasthan is consolidating raw herb sourcing networks to secure consistent supply of amla, bhringraj, and henna. Hindustan Unilever leverages its extensive rural distribution infrastructure to push mass-market shampoo sachets into tier-three towns. Marico sustains brand loyalty through its heritage coconut oil portfolio while extending into premium serum categories. Dabur India anchors its position with clinically tested Ayurveda positioning across hair oils and anti-dandruff treatments.
India hair care encompasses formulations designed to cleanse, condition, nourish, style, or treat scalp and hair fiber, typically comprising surfactant bases, emollients, active botanical extracts, and functional polymers delivered through aqueous, oil, or aerosol vehicles. These products serve consumer grooming needs ranging from daily hygiene to therapeutic intervention against hair loss, premature graying, and environmental damage. Shampoos and hair oils occupy the dominant revenue share due to entrenched daily-use rituals across rural and urban households alike. Natural and organic formulations are expanding fastest as consumers migrate from chemical-laden alternatives toward BIS-compliant clean-label products with traceable ingredient chains.
BIS standards govern cosmetic safety labeling and ingredient disclosure, while CDSCO oversees medicated anti-hair-fall claims requiring clinical substantiation, and the PLI scheme incentivizes domestic manufacturing scale-up for export-oriented personal care units. FSSAI-aligned scrutiny on herbal extract purity is tightening supply chain accountability for Ayurvedic-positioned brands. Stakeholders must monitor evolving BIS notification timelines and state-level Ayurveda board certifications to preempt compliance gaps and capture formulation-first positioning.
Market Dynamics
The India hair care sector is experiencing a fundamental shift as BIS mandatory standards for cosmetics enforcement compresses formulation timelines and forces domestic manufacturers to requalify supply chains around traceable ingredient documentation.
Growth Catalysts
- PLI scheme incentives:Domestic manufacturing scale-up subsidies under India's Production Linked Incentive scheme are pulling export-oriented personal care units toward captive production facilities.
- Maharashtra and Karnataka demand concentration:Affluent urban consumers in these states are absorbing premium salon-grade home care products at volumes that justify dedicated distribution infrastructure.
- Ayurvedic ingredient patent surge:Accelerated filing of amla, bhringraj, and henna extraction patents is validating traditional formulations through clinical substantiation pathways.
Market Restraints
- Raw herb supply volatility:Consolidation of sourcing networks in Kerala and Rajasthan has not eliminated seasonal availability gaps for cold-pressed botanical inputs.
- CDSCO claim substantiation costs:Medicated anti-hair-fall positioning requires clinical trial documentation that stretches R&D budgets for mid-tier formulators.
- FSSAI-aligned extract purity scrutiny:Tightening herbal certification standards is disqualifying legacy suppliers lacking chromatographic testing capabilities.
Strategic Opportunities
- Tier-three town penetration:Sachet-format distribution into underserved urban peripheries offers volume expansion beyond saturated metro markets.
- Salon-channel convergence:Professional-grade home care hybrid positioning captures consumers seeking stylist-recommended maintenance protocols.
- State-level Ayurveda board certification:Early alignment with evolving regional credentialing requirements secures formulation-first positioning against compliance-lagged competitors.
Industry Challenges
- Chromatographic testing skill scarcity:FSSAI-mandated purity verification requires analytical chemists in short supply across domestic contract laboratories.
- BIS notification timeline uncertainty:Evolving cosmetic safety labeling standards force repeated packaging redesign cycles without predictable implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Hair Care Market |
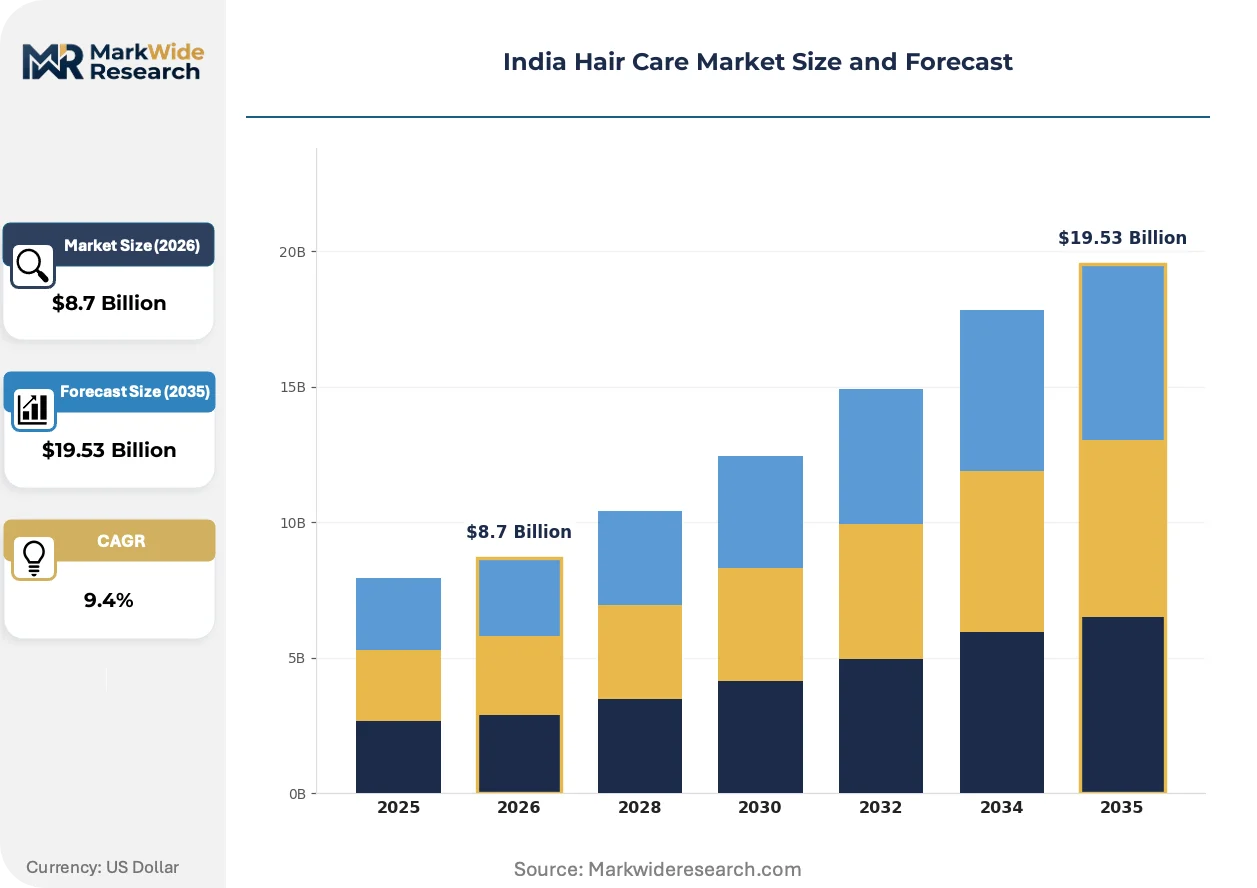
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products Consumer Type: Men, Women, Children, Elderly Formulation: Natural, Organic, Paraben-Free, Chemical Distribution Channel: Supermarkets, Online Retail, Beauty Stores, Pharmacies |
| Companies Covered | Marico, Johnson & Johnson, Hindustan Unilever, Lotus Herbals, Lakmé, Procter & Gamble, Dabur India, Himalaya, L'Oréal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Hair Care Market Trends and Innovations
Clean-label formulation science is compressing the gap between clinical efficacy claims and natural ingredient positioning, forcing manufacturers to rebuild R&D pipelines around substantiated botanical actives rather than cosmetic-grade extracts.
Encapsulation technology for volatile Ayurvedic compounds is unifying stability and bioavailability in a single delivery architecture. Premium serum manufacturers in Mumbai and Bangalore are adopting lipid-shell encapsulation at accelerated procurement cycles. This convergence is unifying previously separate supply chains for pharmaceutical-grade and cosmetic-grade botanical processing.
BIS cosmetic safety standards are mandating granular ingredient disclosure down to trace contaminant thresholds. Formulators must now document supply chain provenance for every surfactant and emollient batch. Anti-dandruff treatment categories face the steepest compliance recertification burdens as CDSCO overlap intensifies.
Urban millennial women are compressing their trial-to-loyalty cycles through digital ingredient verification tools. Metro consumers now cross-reference BIS registration numbers before repurchase, displacing brand heritage as the primary trust signal. This behavioral pivot is most visible in Maharashtra, where app-based transparency platforms have achieved critical adoption mass.
India Hair Care Market Segmentation
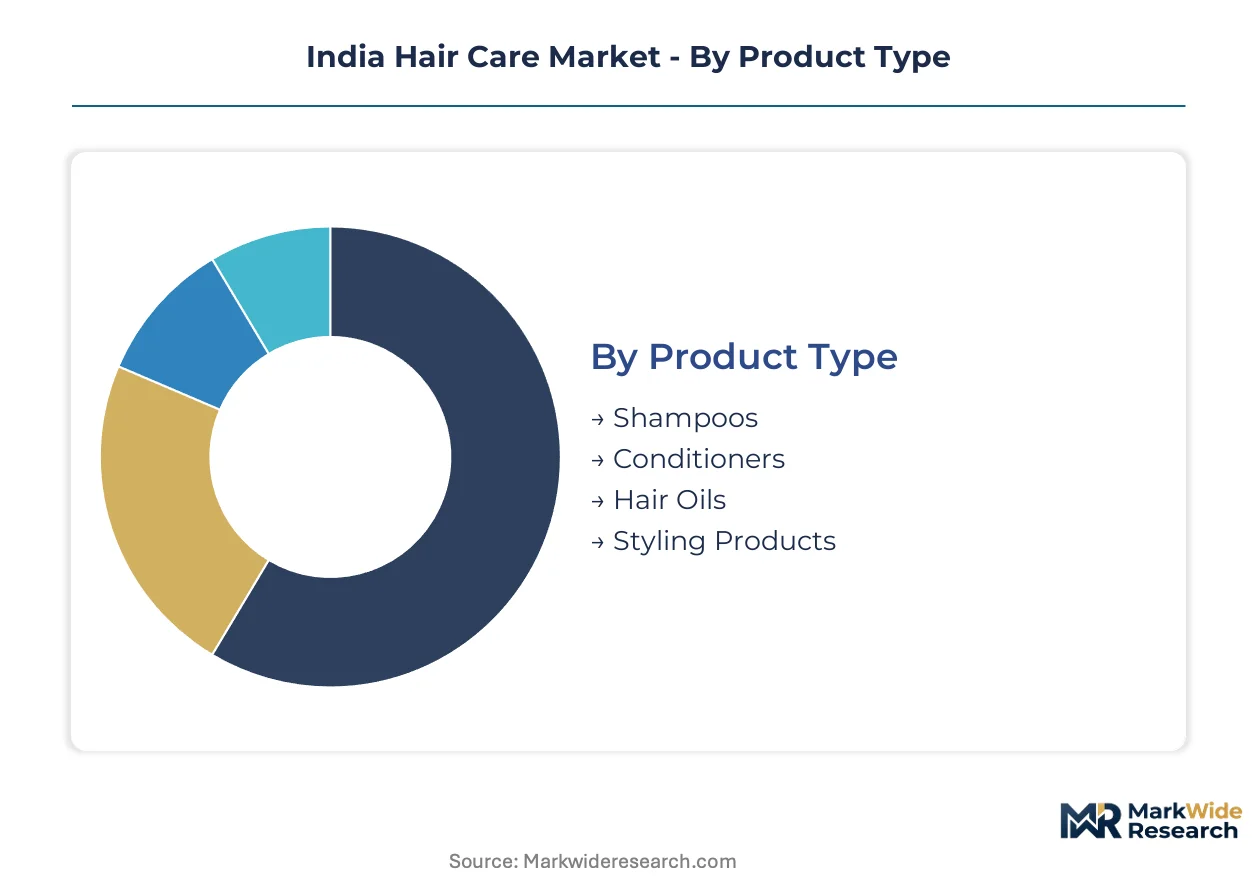
Segmentation in the India hair care market reveals how purchasing decisions fragment across ritual-driven usage patterns, regulatory-conscious formulation preferences, and channel accessibility. Understanding these divides exposes where BIS compliance investments and Ayurvedic patent strategies deliver disproportionate returns.
Product Type:
Standardization dominates daily-use formats while customization concentrates in treatment-grade and professional hybrid categories.
- Shampoos:Surfactant-based cleansing formulations range from mass-market sachets to pH-balanced salon variants. Demand concentrates in Maharashtra and Karnataka urban corridors where BIS-compliant clean-label variants displace legacy chemical formulations amid millennial ingredient scrutiny.
- Hair Oils:Coconut, amla, and bhringraj-based nourishing preparations anchored in pre-wash and overnight rituals. Kerala and Rajasthan sourcing networks supply cold-pressed botanical inputs to formulators targeting tier-three town expansion through heritage positioning.
- Conditioners:Cationic surfactant and silicone emulsion systems for post-shampoo detangling. Premium serum hybrids from Mumbai and Bangalore manufacturers are compressing standalone conditioner relevance.
- Styling Products:Aerosol, wax, and polymer-based hold formulations including gels, mousses, and sprays. Metro male grooming adoption in Delhi and Hyderabad drives niche volume.
Leading the category by volume: Shampoos. Expanding most quickly: Hair Oils with clinical Ayurveda substantiation.
Consumer Type:
Volume aggregates around high-frequency users while margin concentrates in segments demanding specialized therapeutic claims.
- Women:Primary decision-makers across household purchasing with expanded routines spanning cleansing through treatment. Urban millennial cohorts in metro cities validate BIS registration numbers via transparency apps before repurchase.
- Men:Grooming routine simplification favors multi-functional 2-in-1 formats though beard care and anti-hair-fall positioning are extending category participation.
- Children:Tear-free, mild surfactant systems with FSSAI-aligned safety certification requirements. Formulators face elevated purity verification burdens for this sensitive-application segment.
- Elderly:Therapeutic positioning around gray coverage, scalp circulation, and hair density restoration. CDSCO claim substantiation costs filter mid-tier competitors from this prescription-adjacent space.
Dominant by purchase frequency: Women. Steepest expansion trajectory: Men through hybrid grooming formats.
Formulation:
Regulatory pressure and sourcing traceability are compressing the cost gap between premium natural positioning and legacy chemical alternatives.
- Natural:Botanical extract and cold-pressed oil systems with documented herb provenance. Amla, bhringraj, and henna patent filings validate traditional formulations through clinical pathways.
- Organic:Certified organic ingredient chains with third-party audit documentation. Supply scarcity limits scale compared to natural-positioned mass-market variants.
- Paraben-Free:Preservation systems using phenoxyethanol, sodium benzoate, or natural antimicrobial alternatives. BIS cosmetic safety standards mandate explicit preservative disclosure driving reformulation cycles.
- Chemical:Synthetic surfactant, silicone, and polymer-based conventional formulations. Share erosion accelerates as metro consumers migrate toward clean-label alternatives with traceable ingredient chains.
Highest volume: Natural-positioned products. Gaining share fastest: Organic-certified variants despite supply constraints.
Distribution Channel:
Physical proximity governs mass-market access while digital verification tools reshape premium and therapeutic positioning routes.
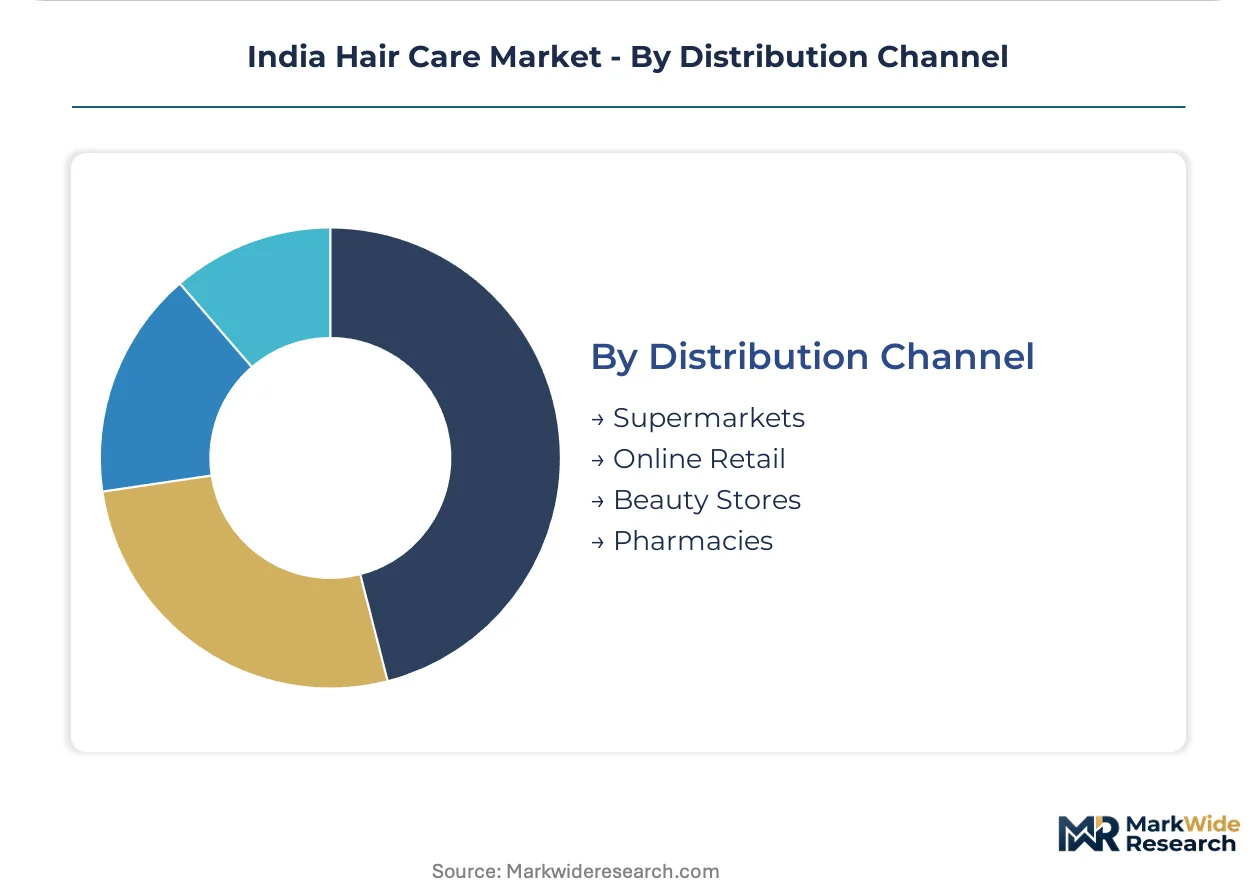
- Supermarkets:Organized retail shelf space for branded mass-market and mid-tier portfolios. Maharashtra and Karnataka modern trade density supports premium salon-grade home care placement.
- Online Retail:E-commerce platforms enabling ingredient transparency tools and subscription replenishment models. Metro millennial women cross-reference BIS numbers before repurchase through app-based verification.
- Beauty Stores:Specialized retail carrying professional-grade and imported positioning. Stylist recommendation protocols drive trial-to-loyalty compression in urban corridors.
- Pharmacies:CDSCO-regulated medicated anti-hair-fall and anti-dandruff formulations with clinical substantiation requirements. Prescription-adjacent credibility supports premium pricing for therapeutic claims.
Dominant by transaction volume: Supermarkets. Climbing the fastest: Online Retail through transparency-enabled repurchase loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Herb cultivation belts in Kerala and Rajasthan supply cold-pressed botanical inputs that anchor formulation quality across Indian hair care manufacturing. State-level demand concentration and regulatory enforcement intensity create divergent growth trajectories across sub-national markets.
Maharashtra
Mumbai and Pune absorb premium salon-grade home care products at volumes justifying dedicated distribution infrastructure. BIS cosmetic safety standards enforcement is tightest in this corridor, accelerating clean-label migration among urban millennial women. Western Maharashtra clusters host encapsulation technology providers serving premium serum manufacturers.
Karnataka
Bangalore's affluent consumer base drives professional-grade hybrid positioning and digital ingredient verification tool adoption. CDSCO-regulated medicated anti-hair-fall claims concentrate in this market due to higher clinical substantiation cost tolerance. The state's PLI scheme beneficiaries include export-oriented personal care manufacturing units.
Tamil Nadu
Chennai's organized retail density supports branded mass-market penetration through modern trade shelf space allocation. FSSAI-aligned herbal extract purity scrutiny has disqualified legacy suppliers lacking chromatographic testing capabilities here. Coimbatore industrial zones house contract manufacturers serving national Ayurvedic-positioned brands.
Kerala
Amla and bhringraj raw herb sourcing networks consolidate around Thrissur and Kochi to secure consistent cold-pressed botanical supply. State-level Ayurveda board certification requirements are evolving fastest in this traditional medicine stronghold. Domestic formulators backward-integrate into captive herb processing to preempt supply volatility.
Delhi-NCR
Metro male grooming adoption in Delhi and adjacent Noida corridors drives niche styling product volume. Pharmacy-channel medicated positioning achieves prescription-adjacent credibility through CDSCO claim substantiation. Gurugram distribution hubs coordinate tier-three town sachet-format penetration into underserved urban peripheries.
India Hair Care Market Competitive Landscape
Global majors compete with regional champions across distribution depth and Ayurvedic heritage positioning, producing a tiered structure with concentrated premium spheres and fragmented mass-market battlegrounds. Three archetypes dominate: multinational CPG conglomerates leveraging scale, domestic Ayurvedic heritage houses with clinical substantiation capabilities, and emerging clean-label specialists exploiting BIS compliance gaps. Competitive intensity manifests through backward integration into herb sourcing and state-level certification racing.
Within the heritage Ayurvedic tier, Dabur India and Marico exemplify clinical substantiation strategies that validate traditional formulations through CDSCO-aligned pathways. Among multinational CPG incumbents, Hindustan Unilever occupies a position defined by rural distribution infrastructure scale and sachet-format penetration capabilities. L'Oréal represents the premium salon-channel convergence archetype, capturing stylist-recommended maintenance protocol demand in Maharashtra and Karnataka urban corridors.
| Leading Market Players |
|---|
| Marico |
| Johnson & Johnson |
| Hindustan Unilever |
| Lotus Herbals |
| Lakmé |
| Procter & Gamble |
| Dabur India |
| Himalaya |
| L'Oréal |
| Others |
Pricing and Supply Chain Analysis
Encapsulation technology adoption for volatile Ayurvedic compounds is compressing cost economics for premium serum manufacturers while simultaneously pulling supply concentration toward Mumbai and Bangalore clusters with lipid-shell processing capabilities. This production-method transition rewards formulators with captive encapsulation infrastructure while marginalizing competitors dependent on third-party contract facilities.
Pricing Analysis
Service-bundling separates clinical substantiation packages from bare formulation sales, with CDSCO-aligned medicated claim documentation commanding substantial premiums over cosmetic-grade alternatives. Three-tier pricing structure across premium salon-grade, standard retail, and economy sachet levels reflects divergence in BIS compliance investment and Ayurvedic patent protection. Pricing pressure stems from FSSAI-mandated chromatographic purity verification, which disqualifies legacy suppliers and forces mid-tier formulators toward cost-absorbing quality upgrades. Tier-three town buyers exhibit highest price sensitivity, while Maharashtra and Karnataka urban millennials prioritize ingredient transparency over absolute cost.
Supply Chain Analysis
Regional distribution centers in Gurugram and Delhi-NCR coordinate hub-and-spoke patterns for sachet-format penetration into underserved urban peripheries. Raw herb supply concentrates in Kerala and Rajasthan for amla, bhringraj, and henna cold-pressed inputs, with seasonal availability gaps creating procurement volatility. Chromatographic testing skill scarcity across domestic contract laboratories poses structural risk to FSSAI-aligned extract purity compliance. Distribution runs through modern trade supermarkets in Maharashtra and Karnataka, pharmacy channels for medicated positioning, and e-commerce platforms enabling transparency-enabled repurchase loyalty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromatographic testing capacity scarcity props pricing for certified-natural formulations, creating supply-constrained margin pools for qualified competitors.
For Market Incumbents: Anticipate BIS notification timeline uncertainty by maintaining redundant packaging design cycles and dual-sourcing herb inputs from Kerala and Rajasthan networks. Backward integration into captive cold-pressing facilities defends margin position against FSSAI-aligned supplier disqualification. Preempt state-level Ayurveda board certification evolution in Kerala to lock formulation-first positioning before compliance-lagged rivals recover. For New Entrants and Emerging Players: Begin with tier-three town sachet penetration through Hindustan Unilever-competitive distribution economics, exploiting underdeveloped organized retail in urban peripheries. Salon-channel professional-grade hybrid positioning offers white-space capture in Maharashtra and Karnataka corridors where stylist recommendation protocols compress trial-to-loyalty cycles. Digital ingredient verification tool integration enables transparency-native brand building among millennial verification-app users. For Investors and Strategic Acquirers: Re-rating potential sits with encapsulation-technology-enabled formulators given lipid-shell delivery architecture adoption acceleration across premium serum categories. Five-to-ten year viability favors clinical substantiation capabilities aligned with CDSCO medicated claim pathways. The signal to watch is state-level Ayurveda board certification timeline acceleration, which would compress competitive response windows for uncertified assets.| Strategic Initiative | Industry Significance |
|---|---|
| Ayurvedic Patent Filing Acceleration | Amla and bhringraj extraction patents validate traditional formulations through CDSCO-aligned clinical substantiation pathways. |
| Backward Integration into Herb Processing | Captive cold-pressing facilities in Kerala preempt seasonal supply volatility and FSSAI purity verification bottlenecks. |
| Salon-Channel Professional Hybrid Launch | Stylist-recommended maintenance protocols capture Maharashtra and Karnataka affluent urban consumers seeking premium home care. |
| Chromatographic Testing Capability Buildout | In-house analytical chemistry capacity secures FSSAI-aligned extract purity compliance amid contract laboratory skill scarcity. |
| State-Level Ayurveda Board Certification | Early alignment with Kerala's evolving credentialing requirements locks formulation-first positioning against compliance-lagged competitors. |
Research Methodology
Trade databases, BIS cosmetic safety notification records, and CDSCO clinical trial registries formed the secondary backbone, supplemented by customs records tracking amla and bhringraj raw herb import flows. Primary interviews with Ayurvedic formulators, modern trade category buyers, contract manufacturing plant managers, and pharmacy channel distributors validated supply chain concentration patterns and pricing tier boundaries. Bottom-up unit economics across sachet, retail, and salon-grade formats triangulated against top-down state-level demand aggregation from Maharashtra, Karnataka, and Tamil Nadu consumption clusters.
Historical trendline analysis of PLI scheme beneficiary expansion and encapsulation technology procurement cycles anchored the projection framework. Segmentation modeling spanned product type, consumer demographic, formulation certification tier, and distribution channel accessibility throughout the forecast period. CAGRs derived from penetration rate assumptions for digital transparency tools, clean-label migration velocity, and tier-three town modern trade expansion. Ayurvedic patent filing velocity and state-level certification timeline evolution served as industry-specific forecast sensitivity inputs.
Underlying measurement precision varies by segment; shampoo and hair oil volume estimates carry tighter precision than emerging serum categories with nascent encapsulation adoption. Forecasts reflect documented assumptions around BIS enforcement intensity, PLI subsidy continuity, and FSSAI chromatographic testing mandate implementation. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Russia Salon Hair Care Market
Hair Care
Argentina Hair Care Market
Hair Care
Malaysia Shampoo Market
Hair Care
Hair Dye Market
Hair Care
Global Professional Hair Care Market
Hair Care
China Hair Care Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
South Africa Hair Care Market
Hair Care
Rice Water Shampoo Market
Hair Care
Hair Serum Market
Hair Care
Qatar Hair Care Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Hair Care Appliances Market
Hair Care
Hair Relaxer Market
Hair Care
China Hair Care Products Market
Hair Care
Australia Hair Removal Market