
 Artificial Hair Integration Market | 2026-2036
Artificial Hair Integration Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Hair Integration Market Outlook
Subscription-based maintenance and color-matching refresh programs is recalibrating how artificial hair integration systems generate lifetime revenue. Aderans Co., Ltd. leverages its salon-direct model to sustain recurring attachment services across Asian markets. Hairdreams Haarhandels GmbH anchors premium positioning through certified stylist training networks. Great Lengths S.p.A. differentiates via keratin-bond technology leadership and controlled distribution.
Artificial hair integration encompasses removable and semi-permanent systems constructed from synthetic polymers, processed human hair, or hybrid blends, attached via fusion bonds, tape adhesives, micro-links, or clip mechanisms to augment volume, length, or coverage for cosmetic or medical indications. Wigs and extensions represent the most established product categories, while toppers capture accelerating share among demographic segments seeking targeted crown coverage with lower maintenance commitment. Heat-resistant fiber formulations command widening adoption in professional styling environments where thermal tool exposure exceeds standard synthetic tolerance thresholds.
REACH substance restrictions in Europe, FDA cosmetic safety oversight in the United States, and China's GB standards for fiber labeling collectively elevate compliance burdens for cross-border suppliers. These frameworks pressure manufacturers toward traceable sourcing documentation and restricted substance testing, particularly for formaldehyde-based adhesives and azo dye applications. Stakeholders must monitor evolving classification debates over whether certain bonding agents trigger medical device rather than cosmetic regulatory pathways.
Market Dynamics
Subscription-based attachment maintenance and color-refresh programs are restructuring revenue capture across the artificial hair integration value chain, compressing upfront purchase cycles while elongating customer lifetime value through recurring service touchpoints.
Growth Catalysts
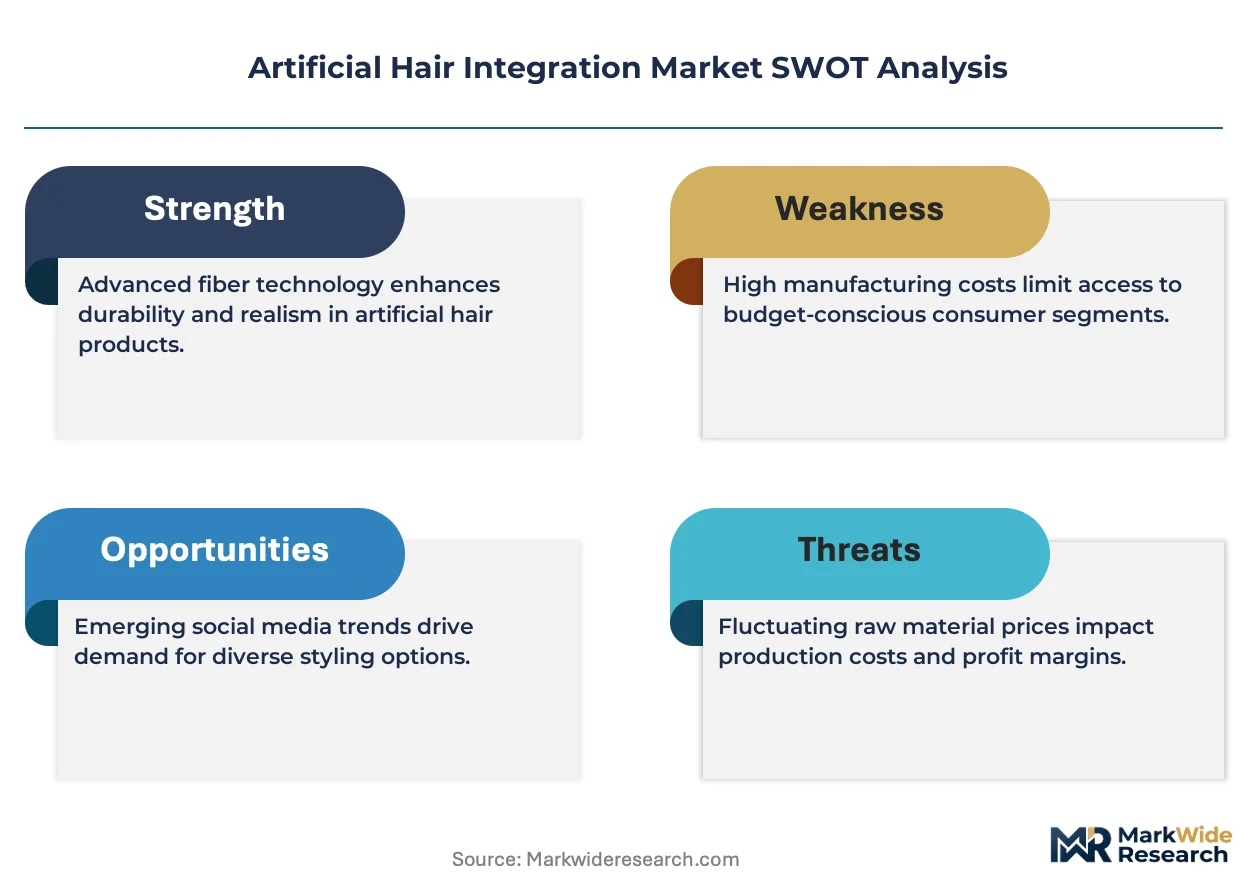
- REACH substance restrictions:ECHA's tightening formaldehyde limits in bonding adhesives are accelerating reformulation investments toward bio-based keratin alternatives, creating first-mover advantages for compliant European suppliers.
- Medical aesthetics clinics:Post-oncology reconstruction protocols and alopecia treatment centers are expanding integration system procurement beyond cosmetic salons into clinical reimbursement pathways.
- Heat-resistant fiber engineering:Advanced polymer blends tolerating thermal styling tools above 180°C are penetrating professional salon environments where styling versatility drives repurchase decisions.
Market Restraints
- Processed human hair supply concentration:Raw material sourcing clusters in Southeast Asian temple donation networks and Indian hair collection cooperatives create geographic vulnerability to export restriction shocks.
- FDA cosmetic device classification uncertainty:Ambiguity over whether certain micro-link and tape adhesive systems trigger medical device rather than cosmetic regulatory pathways extends product launch timelines and legal review costs.
- Synthetic polymer feedstock volatility:Acrylonitrile and polyester chip price swings tied to petrochemical refining margins compress gross margins for mid-tier fiber manufacturers lacking backward integration into resin production.
Strategic Opportunities
- Brazilian metropolitan salon corridors:São Paulo and Rio de Janeiro's dense stylist networks present underpenetrated channels for certified integration training programs and exclusive product distribution.
- AI-driven color-matching systems:Spectrophotometry and machine vision convergence enables real-time scalp tone analysis and fiber blend customization, reducing remake rates and consultation friction.
- China's GB fiber labeling mandates:Stricter origin and composition disclosure requirements create competitive openings for transparent supply chain operators against opaque bulk importers.
Industry Challenges
- Certified integration specialist scarcity:Fusion bond and micro-link application requires 40-120 hours of hands-on training, yet accredited programs remain concentrated in Western European and North American urban centers, constraining service capacity expansion.
- Cross-border customs classification disputes:Inconsistent HS code application for human hair versus synthetic fiber shipments triggers unexpected duty assessments and detention delays at major import gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Hair Integration Market |
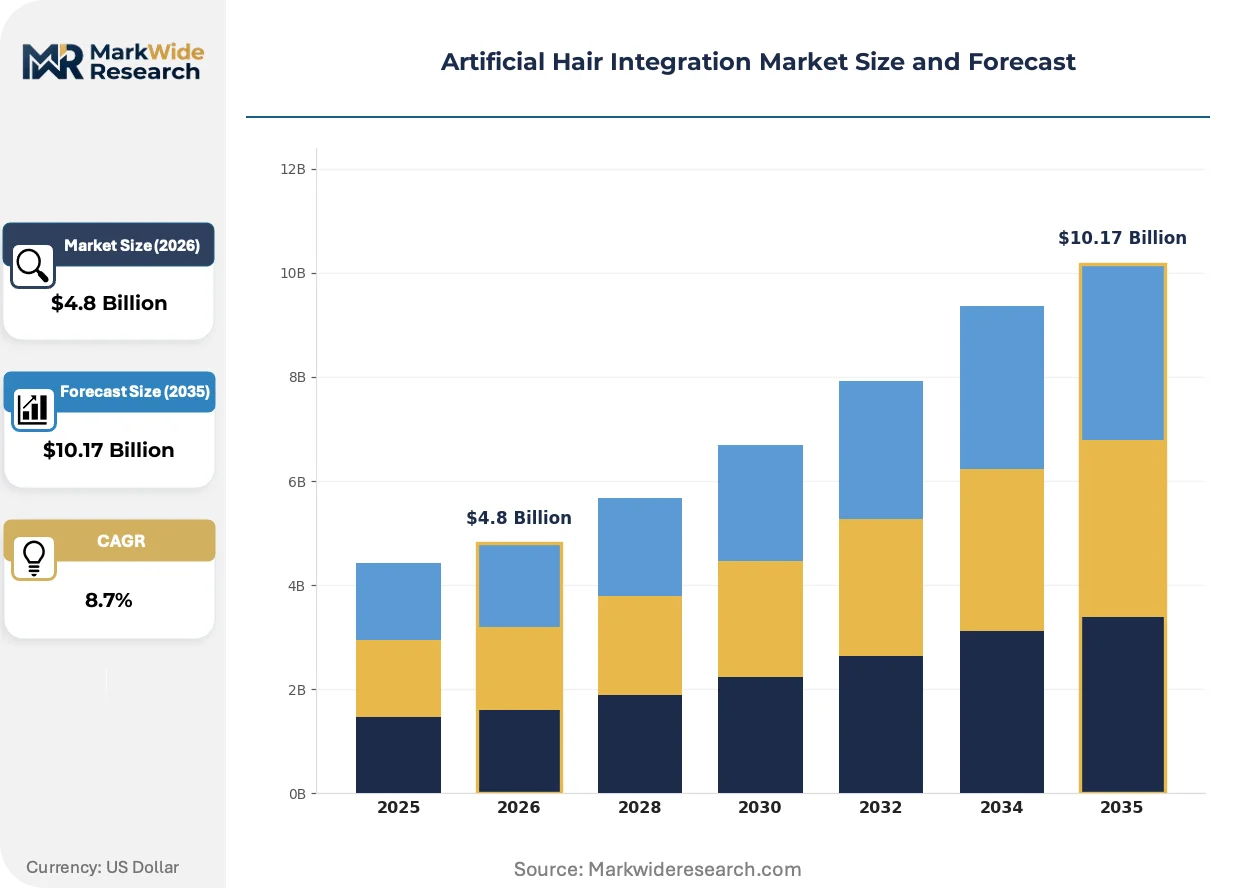
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wigs, Hairpieces, Toppers, Extensions Material: Synthetic Fiber, Human Hair, Blend, Heat-Resistant Fiber Application: Beauty Salons, Theatrical Performances, Fashion Shows, Personal Use End User: Individuals, Professionals, Celebrities, Hair Stylists |
| Companies Covered | Godrej Consumer Products Ltd., Jon Renau Inc., Evergreen Products Group Ltd., Hairdreams Haarhandels GmbH, Great Lengths S.p.A., Aderans Co., Ltd., Donna Bella Hair Inc., Lordhair, Artnature Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Hair Integration Market Strategic Shifts
Material science breakthroughs and regulatory transparency mandates are converging to reshape product architecture and customer acquisition economics across integration system categories.
Hybrid fiber construction—layering heat-resistant synthetic cores with processed human hair cuticle overlays—is modularizing product tiering strategies. Premium salons in South Korean beauty districts are adopting these constructions at accelerated refresh cycles, enabling single-system offerings to span multiple price points through component ratio adjustments rather than discrete inventory SKUs.
ECHA's 2023 extension of REACH annex XVII restrictions to cover formaldehyde-releasing preservatives in cosmetic adhesives is forcing bonding agent reformulations across European supply chains. Manufacturers serving the EU market are migrating toward medical-grade cyanoacrylate alternatives and plant-derived keratin polymers, with tape-adhesive system producers facing the steepest compliance cost gradients due to higher skin-contact surface areas.
Direct-to-stylist digital platforms are compressing traditional distributor markups by enabling certified professionals to order attachment systems, maintenance tools, and color-matching consumables through manufacturer-managed portals. This channel shift is most pronounced in Brazil's independent salon sector, where stylist collectives are consolidating procurement volume to access tiered pricing previously reserved for franchise chains.
Artificial Hair Integration Market Segmentation
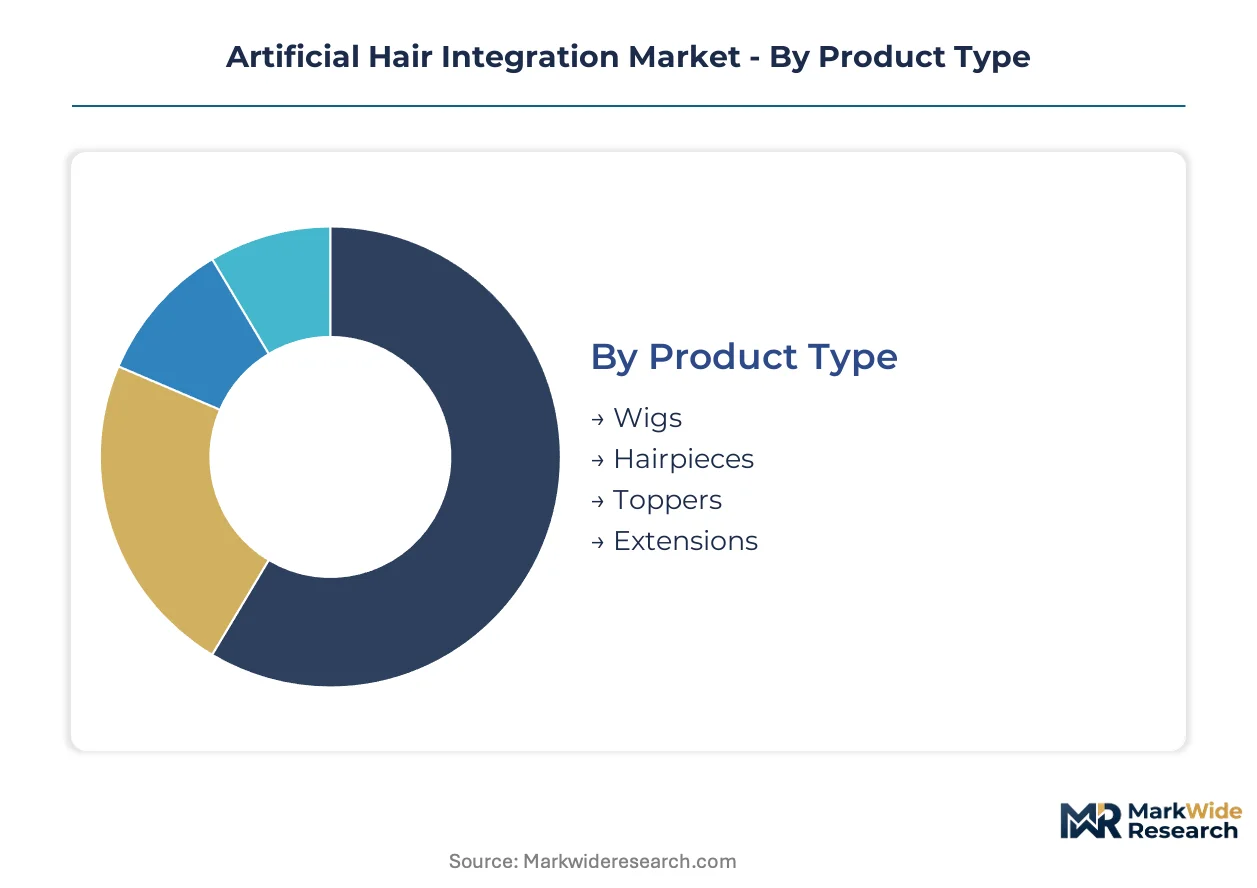
Artificial hair integration systems fragment across four structural dimensions that determine manufacturing specifications, distribution channel selection, and service model economics. Product architecture and material composition drive unit economics, while application context and end-user profile shape pricing power and attachment maintenance frequency.
Product Type:
Full-coverage systems serve standalone cosmetic or medical needs, while partial systems embed into existing hair architecture requiring professional integration services.
- Wigs:Complete scalp coverage systems constructed on lace-front or monofilament bases deliver immediate transformation for alopecia patients and theatrical performers. Demand concentrates in South Korean medical aesthetics clinics where post-oncology reconstruction protocols reimburse integration systems through clinical pathways.
- Extensions:Strand-by-strand or weft-based additions bond to natural hair via keratin fusion, tape adhesive, or micro-link mechanisms to augment length and volume. Brazilian metropolitan salon corridors drive volume for tape and sew-in methods where stylist density enables rapid service scaling.
- Hairpieces:Targeted coverage systems address crown thinning or temporal recession through clip-in or semi-permanent attachment. Men's grooming salons in São Paulo anchor demand for discrete frontal hairline restoration.
- Toppers:Crown-focused partial systems attach via pressure-sensitive clips or perimeter bonding for clients seeking lower maintenance commitment than full wigs. South Korean beauty districts accelerate adoption among demographic segments prioritizing styling versatility with minimal daily adjustment.
Wigs lead volumes today; toppers are gaining share fastest.
Material:
Raw material selection determines thermal tolerance limits, styling longevity, and regulatory compliance burden across import jurisdictions.
- Synthetic Fiber:Acrylonitrile and polyester-based polymers offer colorfastness and moisture resistance at accessible price points. Mid-tier manufacturers face margin compression from petrochemical feedstock volatility absent backward integration into resin production.
- Human Hair:Temple-donated or cooperatively collected strands retain cuticle alignment for directional styling and heat tolerance. Supply concentrates in Southeast Asian collection networks and Indian cooperatives, creating geographic vulnerability to export restriction shocks.
- Blend:Hybrid constructions layer synthetic cores with human hair overlays to bridge price-performance gaps. Premium salons in Seoul deploy these constructions for modular tiering across multiple price points through component ratio adjustments.
- Heat-Resistant Fiber:Advanced polymer formulations tolerate thermal styling tools above 180°C, penetrating professional environments where styling versatility drives repurchase decisions. ECHA's REACH formaldehyde restrictions pressure reformulation toward bio-based alternatives.
Human hair dominates premium positioning; heat-resistant fiber is expanding most quickly.
Application:
Service context determines attachment permanence, stylist certification requirements, and inventory refresh cadence.
- Beauty Salons:Certified integration specialists perform fusion bond, tape, and micro-link applications requiring 40-120 hours of hands-on training. Scarcity of accredited programs outside Western European and North American urban centers constrains service capacity expansion.
- Personal Use:Clip-in and temporary adhesive systems enable consumer-direct application without professional intervention. Direct-to-stylist digital platforms compress distributor markups by enabling certified professionals to order systems through manufacturer-managed portals.
- Theatrical Performances:Custom-constructed units demand rapid color transformation and durability under stage lighting heat. Costume departments prioritize heat-resistant fiber for thermal tolerance during extended performance runs.
- Fashion Shows:Runway contexts require extreme length and color experimentation with single-use or limited-refresh economics. Stylists favor synthetic systems for predictable color saturation and structural integrity under rapid changeover schedules.
Beauty salons anchor service revenue; personal use is climbing the fastest.
End User:
User sophistication and procurement authority determine attachment system selection, maintenance subscription uptake, and price elasticity.
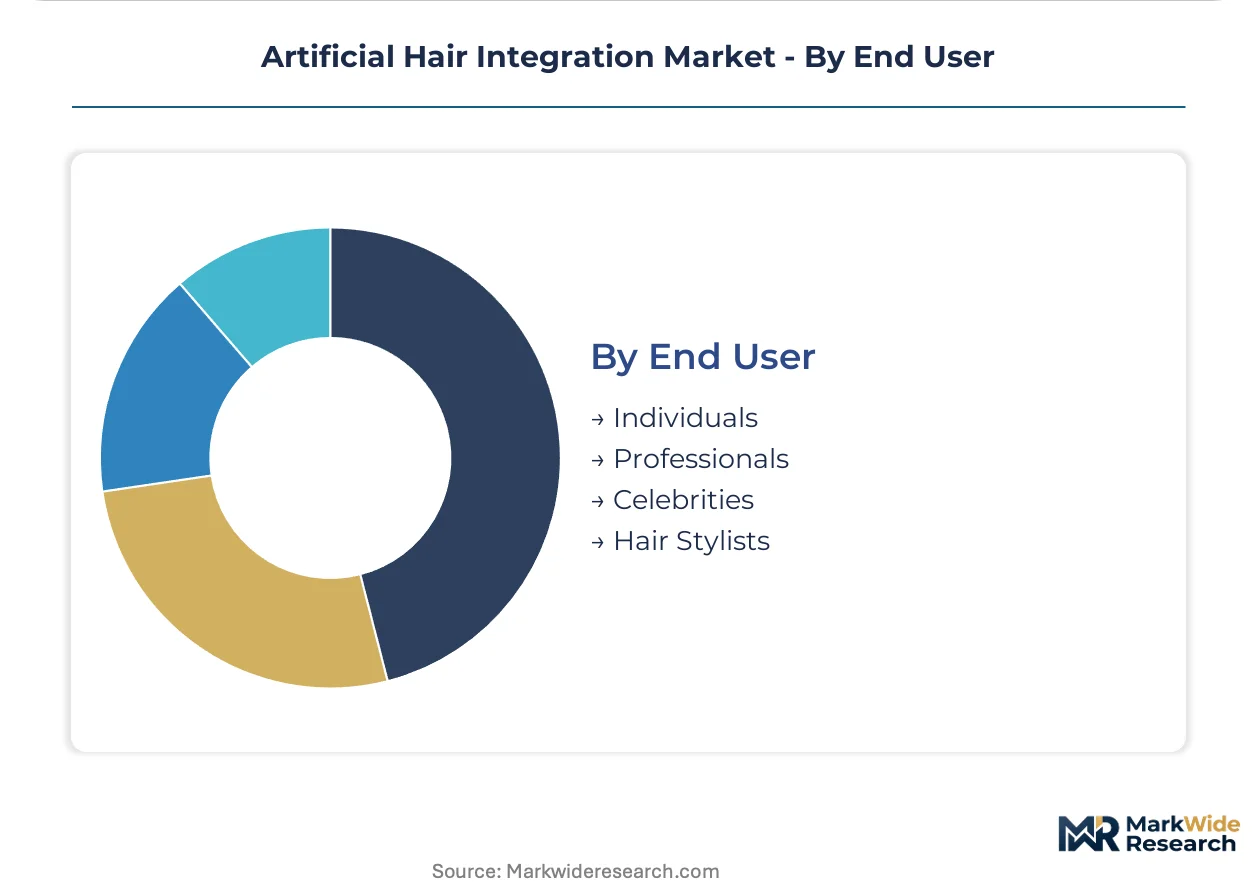
- Individuals:Consumer purchasers prioritize discrete attachment methods and natural movement for daily wear contexts. Subscription-based color-refresh programs recalibrate lifetime revenue capture through recurring service touchpoints.
- Hair Stylists:Professional procurement agents consolidate volume for tiered pricing access and exclusive distribution territories. Brazilian stylist collectives leverage collective buying power to unlock terms previously reserved for franchise chains.
- Professionals:Corporate and broadcast contexts demand consistent appearance standards with rapid replacement capability. News anchors and public-facing executives drive demand for seamless lace-front integration with minimal daily adjustment.
- Celebrities:High-visibility users require custom color-matching and expedited production timelines. AI-driven spectrophotometry systems reduce remake rates through real-time scalp tone analysis and fiber blend customization.
Individuals represent the largest addressable base; hair stylists are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's metropolitan salon corridors generate volume through stylist density, while South Korean beauty districts drive premium adoption through rapid refresh cycles and medical aesthetics integration.
United States
FDA cosmetic device guidance ambiguity extends product launch timelines for tape and micro-link systems. The agency's evolving classification debates over bonding agents pressure manufacturers toward legal review investments. Los Angeles and New York anchor demand among broadcast professionals and celebrity stylists seeking seamless lace-front integration.
Germany
ECHA's REACH annex XVII formaldehyde restrictions accelerate reformulation toward bio-based keratin alternatives. The regulation creates first-mover advantages for compliant European suppliers serving salon-direct channels. Düsseldorf and Munich concentrate certified stylist training networks and premium distribution infrastructure.
Brazil
São Paulo and Rio de Janeiro's dense independent stylist networks enable rapid service scaling for tape and sew-in methods. ANVISA's cosmetic safety oversight shapes import documentation requirements for fiber shipments. Stylist collectives consolidate procurement volume to access tiered pricing through direct-to-stylist digital platforms.
South Korea
Post-oncology reconstruction protocols in Seoul medical aesthetics clinics reimburse integration systems through clinical pathways. MFDS oversight of cosmetic devices influences bonding agent approval timelines. Gangnam beauty districts accelerate hybrid fiber adoption for modular tiering across multiple price points.
China
GB standards for fiber labeling elevate compliance burdens for cross-border suppliers through stricter origin and composition disclosure. SAMR enforcement creates competitive openings for transparent supply chain operators. Shanghai and Beijing concentrate demand among professionals and broadcast contexts requiring consistent appearance standards.
Artificial Hair Integration Market Competitive Environment
Top-tier vendors anchor premium positioning through certified training networks and controlled distribution, while mid-tier competitors compete on stylist volume access and procurement consolidation. The vendor base organizes around three strategic archetypes: salon-direct operators with recurring service models, technology specialists with proprietary bonding or fiber formulations, and scale-driven manufacturers with resin backward integration. Dominant competitive moves include geographic expansion into underpenetrated stylist corridors and portfolio diversification toward medical aesthetics channels.
Among Asian salon-direct specialists, Aderans Co., Ltd. and Artnature Inc. exemplify recurring attachment service models across metropolitan markets. Hairdreams Haarhandels GmbH and Great Lengths S.p.A. occupy positions within the European premium tier through certified stylist network investments. Godrej Consumer Products Ltd. represents scale-driven manufacturing with established distribution infrastructure across multiple geographies.
| Leading Market Players |
|---|
| Godrej Consumer Products Ltd. |
| Jon Renau Inc. |
| Evergreen Products Group Ltd. |
| Hairdreams Haarhandels GmbH |
| Great Lengths S.p.A. |
| Aderans Co., Ltd. |
| Donna Bella Hair Inc. |
| Lordhair |
| Artnature Inc. |
| Others |
Value Chain & Pricing Dynamics
Subscription-based attachment maintenance programs across Brazilian stylist collectives and South Korean beauty districts are compressing upfront purchase cycles while elongating customer lifetime value, forcing manufacturers to restructure inventory financing and service capacity investments around recurring revenue models rather than transactional unit economics.
Pricing Analysis
Capacity additions in Southeast Asian fiber processing hubs are reshaping price floors for mid-tier synthetic extensions, intensifying competition among manufacturers lacking backward integration into acrylonitrile resin production. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and stylist training network access, with Hairdreams and Great Lengths commanding brand premiums through exclusive distribution control. Cost compression in standard-tier tape-adhesive systems stems from petrochemical feedstock volatility and Brazilian procurement consolidation. Individual consumers show highest price sensitivity, while medical aesthetics clinics demonstrate lowest elasticity due to reimbursement pathway insulation.
Supply Chain Analysis
Certified integration specialist scarcity in Western Europe and North America creates qualification gating that limits service capacity expansion and concentrates margin capture among accredited training networks. Raw material sourcing draws from Indian temple donation cooperatives, Southeast Asian collection networks, and Chinese petrochemical resin manufacturers, creating geographic concentration risk. Processed human hair supply faces vulnerability to Indian export restriction shocks and Southeast Asian logistics chokepoints. Distribution runs through salon-direct portals and certified stylist procurement collectives, bypassing traditional wholesale markups in Brazil's independent salon sector.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in artificial hair integration rests on reformulation cost-down from bio-based keratin alternatives displacing formaldehyde-releasing adhesives, alongside premium-tier shift toward hybrid fiber constructions with modular component ratios.
For Market Incumbents: Deploy exclusive stylist certification networks as a defensive moat against direct-to-stylist digital platforms eroding distributor control. Deepen captive supply of heat-resistant polymer formulations to offset petrochemical feedstock volatility compressing mid-tier margins. Accelerate medical aesthetics channel penetration before reimbursement pathway standardization lowers entry barriers for emerging competitors. For New Entrants and Emerging Players: Begin with AI-driven color-matching system deployment targeting Brazilian independent stylist collectives seeking procurement consolidation tools. White-space opportunity concentrates in São Paulo and Rio de Janeiro corridor certification gaps, where 40-120 hour training requirements exceed local program supply. Go-to-market angle should leverage transparent supply chain documentation against opaque bulk importers facing China's GB fiber labeling mandates. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid fiber technology specialists possessing proprietary heat-resistant polymer formulations and modular construction IP. Long-term viability favors operators with dual-channel presence across cosmetic salon networks and clinical reimbursement pathways. Signal to watch is ECHA formaldehyde restriction enforcement acceleration triggering reformulation investment spikes among non-compliant adhesive manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Stylist Network Expansion | Hairdreams' Düsseldorf training hub anchors premium positioning through exclusive skill certification control. |
| Bio-Based Adhesive Reformulation | REACH-compliant keratin alternatives create first-mover advantage for European suppliers serving ECHA-regulated markets. |
| Direct-to-Stylist Digital Platform Launch | Brazilian procurement consolidation through manufacturer portals compresses traditional distributor markups. |
| Medical Aesthetics Channel Partnership | Seoul clinic reimbursement pathways open clinical procurement volumes beyond cosmetic salon demand. |
| Hybrid Fiber Product Architecture | Seoul premium salons deploy modular constructions spanning multiple price points through component ratio adjustments. |
Study Parameters
Direct dialogue with certified integration specialists, salon procurement managers, medical aesthetics clinic directors, and adhesive formulation chemists grounded qualitative insights, cross-referenced against customs trade records, ECHA regulatory filings, ANVISA import documentation, and SEC disclosures from listed personal care manufacturers. Bottom-up and top-down triangulation validated volume estimates across product tiers and regional clusters.
Bottom-up modeling built from stylist network density, attachment service frequency, and fiber consumption per application, while top-down analysis tracked personal care distributor revenue allocations and import shipment classifications. Segmentation dimensions spanned product architecture, material composition, application context, and end-user procurement authority. CAGRs derived from fitted growth curves incorporating regulatory compliance cost trajectories and channel shift velocity across the projection horizon. Industry-specific inputs included ECHA formaldehyde restriction implementation timelines and Brazilian stylist collective procurement consolidation rates.
Caveats apply where ECHA enforcement intensity, Indian human hair export policy shifts, or FDA cosmetic device classification rulings could materially shift the outlook. Forecasts reflect assumptions regarding certification program expansion rates and reimbursement pathway standardization. A model refresh is warranted upon material change in REACH annex XVII amendment scope or ANVISA fiber import documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Russia Salon Hair Care Market
Hair Care
Hair Spray Market
Hair Care
Chile Hair Care Market
Hair Care
Professional Hair Care Products Market
Hair Care
Malaysia Shampoo Market
Hair Care
United States Hair Care Market
Hair Care
Hair Clay Market
Hair Care
Hair Tonic Market
Hair Care
Hair Serum Market
Hair Care
Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Argentina Hair Care Market
Hair Care
Hair Texturizer Products Market
Hair Care
Global Professional Hair Care Market
Hair Care
South Africa Hair Care Market
Hair Care
Hair Bond Multiplier Market