
 Asia-Pacific Shampoo Market | 2026-2036
Asia-Pacific Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Shampoo Market Outlook
Market Context
Asset-light contract manufacturing and third-party leasing arrangements is fragmenting competitive boundaries in the Asia-Pacific shampoo landscape, allowing regional challengers to scale without heavy capital deployment. The Procter & Gamble Company leverages its manufacturing scale to sustain cost leadership across Southeast Asian retail networks. Dabur India Limited anchors its position through Ayurvedic ingredient specialization and deep distribution in India's traditional trade channels. Amorepacific Corporation differentiates via fermented biotechnology R&D and premium positioning in South Korean duty-free and domestic prestige segments.
Technical Definition and Segment Structure
Asia-Pacific shampoo comprises surfactant-based liquid or solid formulations designed for cleansing hair and scalp, typically containing 10-20% active surfactant systems alongside conditioning polymers, preservatives, and functional actives such as zinc pyrithione or plant-derived extracts. The product serves consumer hygiene, therapeutic scalp treatment, and cosmetic hair maintenance across household and professional salon environments. Organic formulations command premium shelf positioning as clean-label preference intensifies, though anti-dandruff variants retain volume leadership through sustained pharmacy and mass retail penetration. Online retail channels are capturing disproportionate growth momentum, while specialty stores concentrate margin pools through personalized consultation and exclusive brand curation.
Regulatory Environment
India's BIS and CDSCO frameworks govern cosmetic safety labeling and active ingredient thresholds, directly shaping permissible formulation ranges for medicated and herbal-positioned shampoos. China's NMPA and GB standards enforce microbiological limits and ingredient disclosure protocols that determine market access timelines for imported and domestic brands alike. Japan's METI and quasi-drug classification system create distinct compliance pathways for functional claims such as hair growth or sebum regulation. Stakeholders must monitor evolving ASEAN cosmetic directive harmonization and country-specific ingredient ban lists to preempt reformulation costs and registration delays.
Market Dynamics
India's PLI scheme for domestic manufacturing is compressing competitive entry costs and attracting contract manufacturers to establish surfactant blending facilities in Gujarat and Maharashtra industrial corridors.
Growth Catalysts
- CDSCO medicated shampoo classification:India's streamlined approval pathway for anti-dandruff and therapeutic formulations is accelerating pharmacy channel penetration for functional hair care products.
- Fermented biotechnology R&D:South Korean cosmetic science advances are enabling bioactive ingredient stabilization at scale, differentiating premium positioning in duty-free retail.
- Tier-two Indian urban households:Mass-market personal care adoption is deepening across secondary cities as modern trade expansion reaches Nagpur, Indore, and Kochi consumer corridors.
Market Restraints
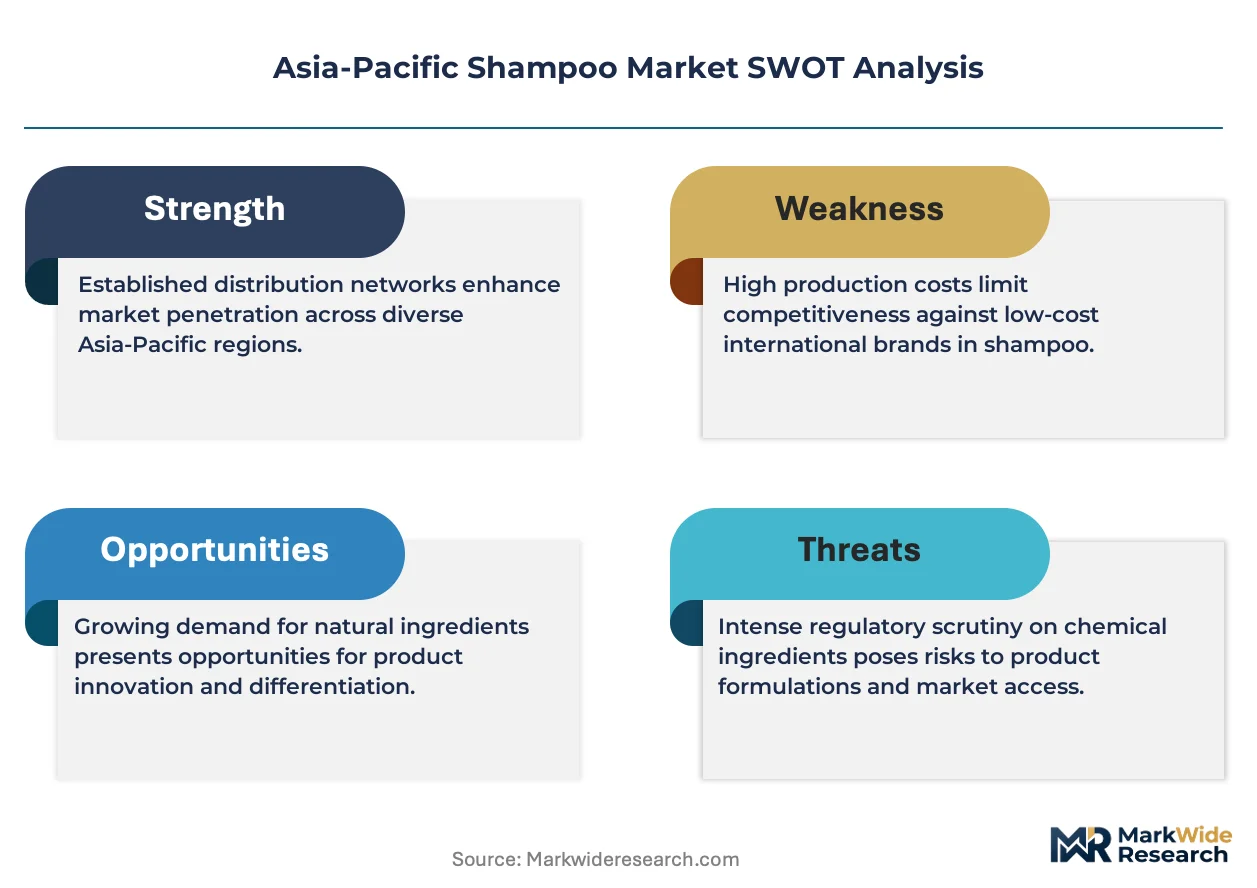
- Palm kernel oil price volatility:Primary surfactant feedstock fluctuations are squeezing gross margins for mid-tier brands dependent on imported oleochemicals.
- China NMPA registration timelines:Extended microbiological testing protocols for imported formulations are delaying market access by 12-18 months for non-domestic manufacturers.
- Solid shampoo bar substitution:Waterless concentrated formats are capturing environmentally conscious segments in Australian and New Zealand urban markets.
Strategic Opportunities
- Vietnam emerging consumer corridors:Ho Chi Minh City and Da Nang retail modernization is creating whitespace for mass-premium positioning between local and multinational offerings.
- ASEAN cosmetic directive harmonization:Streamlined ingredient disclosure protocols are reducing cross-border compliance costs for regional brand expansion.
- Live commerce integration:Shopee and Lazada streaming commerce is virtualizing product education and trial conversion for herbal-positioned entrants.
Industry Challenges
- Formulation chemist scarcity:Specialized talent in Ayurvedic-synthetic hybrid development commands premium compensation, constraining mid-cap R&D scaling.
- BIS certification backlog:Bureau of Indian Standards testing queue delays are extending product launch timelines for domestic manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Shampoo Market |
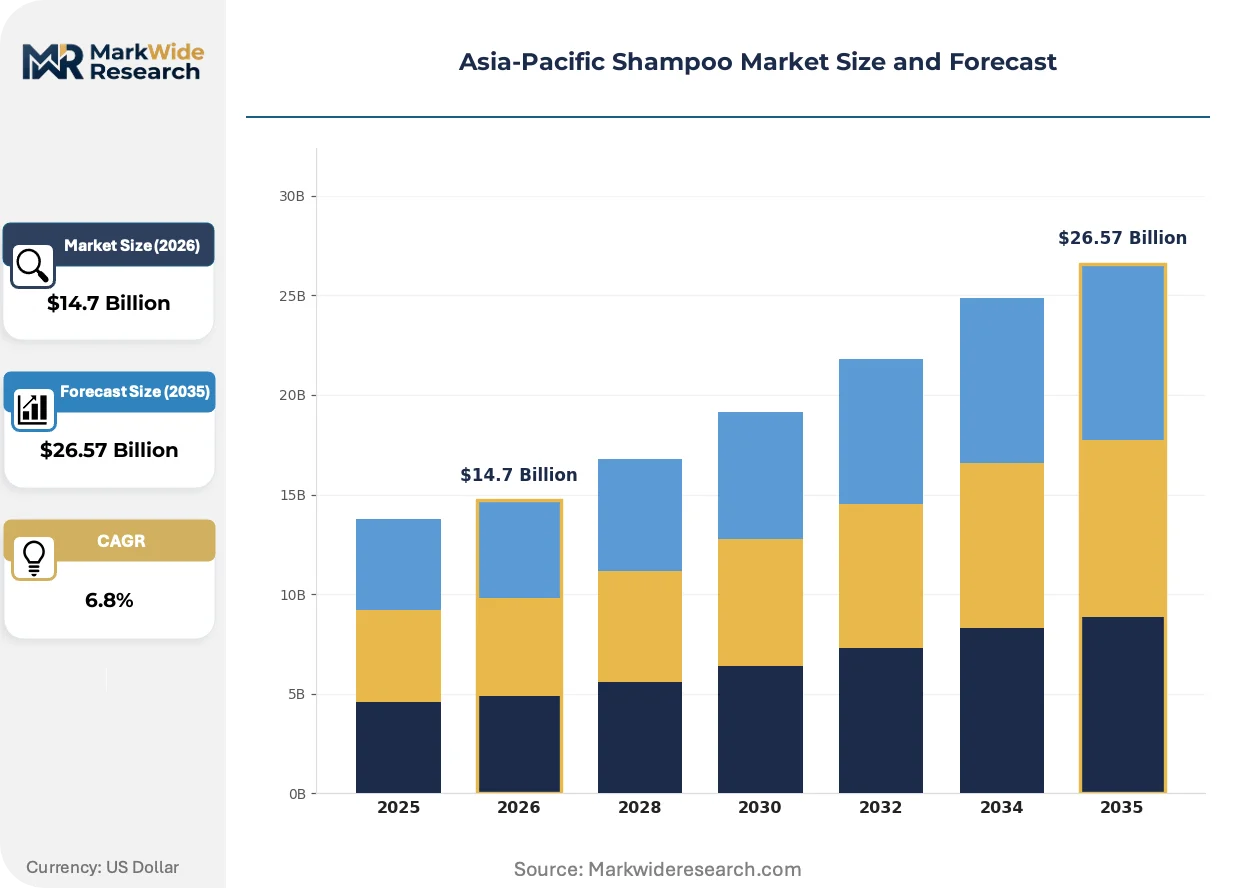
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Anti-Dandruff, Moisturizing, Color Protection Application: Personal Care, Professional Use, Spa Treatments, Retail End User: Adults, Children, Women, Men Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | The Procter & Gamble Company, Dabur India Limited, L'Oréal S.A., Amorepacific Corporation, Himalaya Global Holdings Ltd, Unilever PLC, Shiseido Company, Limited, Marico Limited, Kao Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Shampoo Market Strategic Shifts
Biotechnology-derived actives and waterless formats are displacing conventional petrochemical surfactant systems across the Asia-Pacific shampoo landscape, compressing traditional formulation paradigms.
Biotechnology is virtualizing ingredient sourcing and efficacy validation in premium shampoo development. South Korean and Japanese cosmetic laboratories are adopting cell-culture derived ceramides and peptide complexes to replace plant-extraction dependent supply chains. This shift is compressing raw material lead times from agricultural harvest cycles to bioreactor batch production.
Japan's METI quasi-drug classification system is tightening functional claim substantiation requirements for hair growth and sebum regulation products. Manufacturers must now submit clinical trial data for previously self-certified formulations. Premium domestic brands are responding by segregating cosmetic and therapeutic product lines to isolate compliance risk.
Social commerce livestreaming is displacing traditional sampling and in-store consultation across Southeast Asian markets. Indonesian and Vietnamese consumers are purchasing shampoo through TikTok Shop and Shopee Live demonstrations hosted by dermatologists and hair stylists. This channel is capturing disproportionate growth momentum in herbal and Ayurvedic-positioned segments where ingredient storytelling drives conversion.
Asia-Pacific Shampoo Market Segmentation
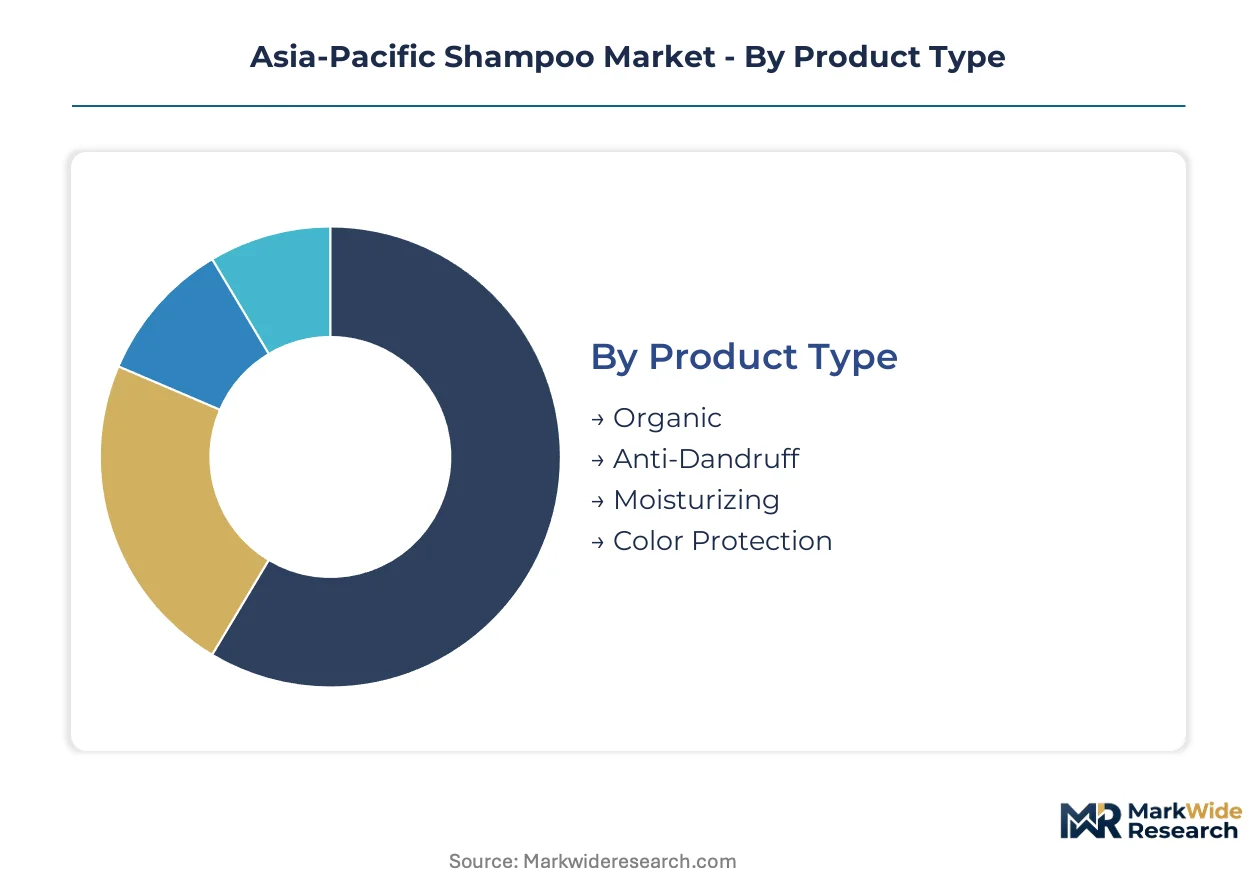
Segmentation in Asia-Pacific shampoo markets reveals divergent velocity patterns across formulation types and channel structures. Cycle times vary dramatically between mass-market anti-dandruff variants and slow-turning premium organic lines. Understanding these cadence differences enables inventory positioning and margin capture strategies.
Product Type:
Anti-dandruff formulations turn fastest through pharmacy and modern trade channels, while organic variants sit longer on prestige retail shelves awaiting consumer education conversion.
- Anti-Dandruff:Zinc pyrithione and ketoconazole-based formulations targeting therapeutic scalp treatment. Demand concentrates in India's tier-two cities where CDSCO-mandated pharmacy distribution deepens household penetration for functional hair care. The segment's clinical positioning commands price premiums over standard cosmetic variants.
- Organic:Plant-derived surfactant systems excluding sulfates, parabens, and synthetic fragrances. South Korean duty-free retail and Australian urban markets drive concentration as clean-label preference intensifies among environmentally conscious consumers. Fermented biotechnology R&D enables bioactive stabilization without petrochemical preservatives.
- Moisturizing:Conditioning polymer-enriched formulations targeting dry scalp and damaged hair repair.
- Color Protection:UV filter and antioxidant systems preserving artificial hair pigment integrity.
Anti-dandruff dominates installed base. Organic is where expansion concentrates.
Application:
Professional salon channels command higher per-unit economics but slower inventory velocity compared to household personal care consumption.
- Personal Care:Daily-use household shampoo consumption across mass and premium positioning tiers. Vietnam's emerging consumer corridors in Ho Chi Minh City and Da Nang drive concentration as modern trade expansion reaches secondary urban households. Shopee and Lazada live commerce integration accelerates trial conversion for herbal-positioned entrants.
- Professional Use:Salon-exclusive formulations with concentrated active systems requiring stylist application training. India's traditional trade channels in Gujarat and Maharashtra industrial corridors anchor distribution as contract manufacturers establish surfactant blending facilities under PLI scheme incentives.
- Spa Treatments:Ritual-positioned products bundled with scalp massage and aromatherapy services.
- Retail:Standard commercial packaging for unassisted consumer selection in self-service environments.
Personal care generates volume throughput. Professional use captures margin expansion.
End User:
Women's segments sustain higher purchase frequency and SKU complexity, while children's formulations face slower replenishment cycles due to smaller usage volumes.
- Women:Multi-step hair care routines driving conditioner and treatment companion purchases. India's tier-two cities including Nagpur, Indore, and Kochi concentrate demand as mass-market personal care adoption deepens across secondary urban households. Ayurvedic ingredient specialization anchors brand loyalty through traditional trade channel penetration.
- Adults:Gender-neutral positioning targeting shared household consumption with simplified formulation claims.
- Men:Two-in-one and three-in-one convenience formulations emphasizing speed and simplicity.
- Children:Tear-free mild surfactant systems with playful packaging and parental safety reassurance.
Women's segments dominate SKU proliferation. Men's positioning is climbing the fastest.
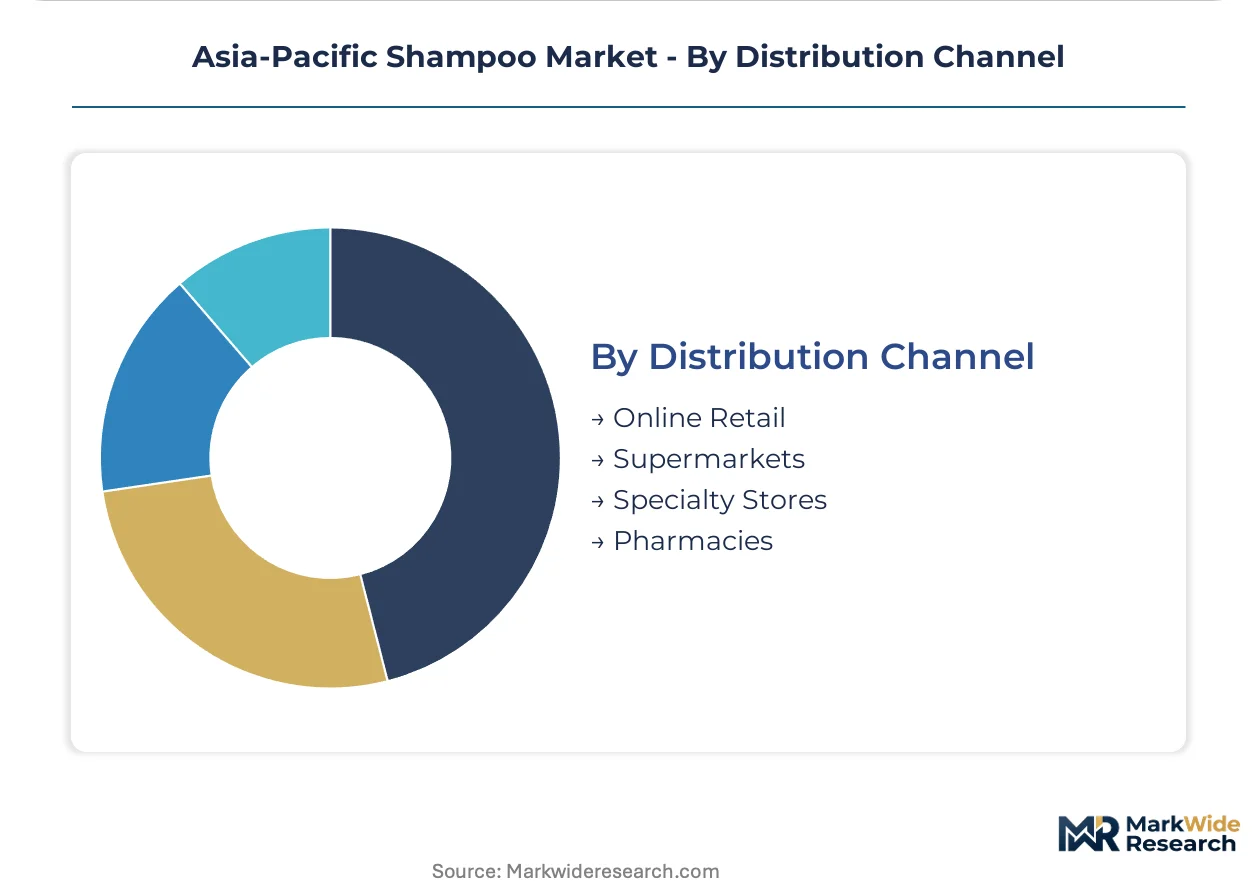
Distribution Channel:
Online retail compresses replenishment cycles through subscription models, while specialty stores turn slowly due to high-touch consultation requirements.
- Online Retail:E-commerce and social commerce platforms capturing disproportionate growth momentum. Indonesian and Vietnamese consumers purchase through TikTok Shop and Shopee Live demonstrations where dermatologist-hosted ingredient storytelling drives conversion. ASEAN cosmetic directive harmonization reduces cross-border compliance costs for regional brand expansion.
- Specialty Stores:Curated retail environments with personalized consultation and exclusive brand access. South Korean duty-free segments concentrate here as Amorepacific Corporation and domestic prestige competitors deploy fermented biotechnology R&D differentiation.
- Supermarkets:High-velocity self-service retail with promotional pricing and multi-brand comparison.
- Pharmacies:Therapeutic and medicated shampoo distribution governed by CDSCO classification requirements.
Supermarkets dominate installed base. Online retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban households across Southeast Asian secondary cities and India's tier-two markets concentrate shampoo purchasing power. Modern trade expansion and pharmacy channel deepening reshape distribution economics. Regulatory divergence between CDSCO, NMPA, and METI frameworks fragments compliance pathways.
India
Tier-two cities including Nagpur, Indore, and Kochi drive mass-market personal care adoption as modern trade penetrates secondary urban corridors. The PLI scheme for domestic manufacturing compresses competitive entry costs and attracts contract manufacturers to establish surfactant blending facilities in Gujarat and Maharashtra industrial corridors. CDSCO medicated shampoo classification accelerates pharmacy channel penetration for anti-dandruff and therapeutic formulations.
China
NMPA registration timelines for imported formulations extend market access delays by 12-18 months through microbiological testing protocols. GB standards enforce ingredient disclosure and microbiological limits that determine access timelines for domestic and foreign brands. Shanghai and Guangzhou retail modernization concentrates premium positioning opportunities as duty-free segments recover.
Japan
METI quasi-drug classification tightens functional claim substantiation for hair growth and sebum regulation products. Tokyo and Osaka prestige retail segments concentrate fermented biotechnology R&D differentiation. Clinical trial data requirements now govern previously self-certified therapeutic formulations.
Vietnam
Ho Chi Minh City and Da Nang retail modernization creates whitespace for mass-premium positioning between local and multinational offerings. Shopee and Lazada live commerce integration virtualizes product education for herbal-positioned entrants. ASEAN cosmetic directive harmonization reduces cross-border compliance costs for regional brand expansion.
South Korea
Seoul duty-free and domestic prestige segments concentrate premium biotechnology-derived positioning. Fermented cosmetic science advances enable bioactive ingredient stabilization at scale. Cell-culture derived ceramides and peptide complexes replace plant-extraction dependent supply chains in premium development laboratories.
Asia-Pacific Shampoo Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented shelf-space allocation. Mass-market multinational incumbents leverage manufacturing scale for cost leadership in Southeast Asian retail networks. Ayurvedic-specialist domestic anchors and fermented-biotechnology premium differentiators represent the dominant strategic archetypes. Capacity expansion under India's PLI scheme and live commerce platform integration constitute the primary competitive moves reshaping market access economics.
Within the Ayurvedic-specialist tier, Dabur India Limited and Himalaya Global Holdings Ltd occupy positions anchored through traditional trade channel penetration and herbal ingredient positioning. Among scale-driven multinationals, The Procter & Gamble Company exemplifies manufacturing-led cost leadership across mass retail networks. Amorepacific Corporation sits within the fermented-biotechnology premium tier, representing South Korean cosmetic science differentiation in duty-free and prestige segments.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Dabur India Limited |
| L'Oréal S.A. |
| Amorepacific Corporation |
| Himalaya Global Holdings Ltd |
| Unilever PLC |
| Shiseido Company, Limited |
| Marico Limited |
| Kao Corporation |
| Others |
Value Chain & Pricing Dynamics
Gujarat's surfactant blending corridor concentrates feedstock conversion capacity, compressing unit economics for mid-tier brands while amplifying pricing power for integrated manufacturers with captive oleochemical sourcing. CDSCO-mandated pharmacy distribution for anti-dandruff variants creates tiered margin structures where therapeutic positioning commands premiums over standard cosmetic formulations.
Pricing Analysis
Certification level (BIS-grade versus non-certified) creates the primary spread between mass-market and pharmacy-channel positioning. Three-tier pricing structure across premium Ayurvedic, standard cosmetic, and economy sachet levels stratifies consumer access points. Cost compression in mid-tier segments is intensifying because palm kernel oil volatility squeezes imported feedstock-dependent brands. Tier-two urban households exhibit highest price sensitivity, while duty-free prestige segments absorb biotechnology-derived premiums without volume erosion.
Supply Chain Analysis
Extended payment terms from Shopee and Lazada marketplace operators are restructuring working capital requirements for herbal-positioned entrants. Manufacturing concentrates in India, China, and South Korea, with surfactant blending anchored in Gujarat and Maharashtra industrial corridors. Formulation chemistry draws from palm-derived oleochemicals, fermented biotechnology actives, and Ayurvedic botanical extracts. Single-source vulnerability in palm kernel feedstock imports from Southeast Asian producers exposes margin stability to commodity price swings. Distribution runs through modern trade expansion in tier-two cities complemented by live commerce platform integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in Vietnam's emerging consumer corridors where mass-premium whitespace sits between local and multinational offerings. Social commerce livestreaming is fragmenting traditional channel control, creating entry niches for ingredient-storytelling specialists.
For Market Incumbents:Entrench pharmacy channel dominance through CDSCO medicated shampoo certification investments that raise regulatory barriers for emerging competitors. Deepen backward integration into surfactant production under India's PLI scheme incentives to insulate margin structures from palm kernel oil volatility. Solid shampoo bar substitution in Australian and New Zealand markets threatens volume retention in environmentally conscious segments.
For New Entrants and Emerging Players:Pursue tier-two Indian urban corridors in Nagpur, Indore, and Kochi where modern trade penetration lags brand saturation in metro markets. Target Vietnam's Ho Chi Minh City and Da Nang retail modernization zones where mass-premium positioning captures whitespace between economy local brands and premium multinational lines. Deploy dermatologist-hosted live commerce demonstrations on TikTok Shop and Shopee Live to virtualize ingredient education and trial conversion.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors fermented-biotechnology R&D specialists with cell-culture derived ceramide capabilities over plant-extraction dependent legacy formulators. Long-term viability hinges on supply chain decoupling from agricultural harvest cycles through bioreactor batch production scaling. Acquisition focus should concentrate on Ayurvedic-synthetic hybrid development laboratories with scarce formulation chemist talent. Monitor ASEAN cosmetic directive harmonization progress as inflection indicator for cross-border compliance cost reduction enabling regional brand rollup opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| PLI Scheme Capacity Expansion | Domestic surfactant blending in Gujarat reduces import dependency and compresses unit economics. |
| Fermented Biotechnology R&D Investment | South Korean cell-culture derived ceramides replace plant-extraction supply chains in premium positioning. |
| Live Commerce Platform Integration | Shopee and Lazada streaming virtualizes dermatologist-hosted ingredient education for herbal entrants. |
| CDSCO Medicated Classification Pathway | Pharmacy channel penetration for anti-dandruff variants raises regulatory barriers against commodity competitors. |
| Solid Format Sustainability Repositioning | Waterless concentrated bars capture environmentally conscious segments in Australian and New Zealand urban markets. |
Study Parameters
Cross-validation between primary interviews with brand managers, category buyers at modern trade retailers, Ayurvedic formulation chemists, and contract manufacturing executives anchors the qualitative findings. Secondary validation draws from CDSCO registration databases, BIS certification records, ASEAN cosmetic directive harmonization documents, and Shopee-Lazada marketplace transaction data. Bottom-up channel volume estimates and top-down macro consumption patterns triangulate market sizing.
Calibration against historical CAGRs and segment elasticity patterns shapes the projection framework across the analysis window. Segmentation dimensions include product type (anti-dandruff, organic, moisturizing), application (personal care, professional use), end user (women, men, children), and distribution channel (online retail, specialty stores, supermarkets, pharmacies). CAGRs derive from trend extrapolation moderated by regulatory event probability and channel shift velocity. Forecast inputs incorporate PLI scheme capacity buildout timelines and live commerce penetration curves in Indonesian and Vietnamese markets.
Sensitivities concentrate around NMPA registration timeline extensions, palm kernel oil price volatility spikes, and solid shampoo bar substitution acceleration in environmentally conscious segments. Forecasts reflect documented assumptions regarding regulatory harmonization progress and channel modernization rates. Macroeconomic contraction, ingredient ban list expansions, or biotechnology scale-up failures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Argentina Hair Care Market
Hair Care
India Hair Care Market
Hair Care
Professional Hair Care Products Market
Hair Care
Artificial Hair Integration Market
Hair Care
Brazil Hair Care Market
Hair Care
Hair Serum Market
Hair Care
Hair Relaxer Market
Hair Care
Hair Bond Multiplier Market
Hair Care
France Haircare Market
Hair Care
Global Professional Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Israel Hair Care Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Global Premium Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
Asia Pacific Hair Styling Products Market