
 Mexico Hair Care Market | 2026-2036
Mexico Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Hair Care Market Foresight
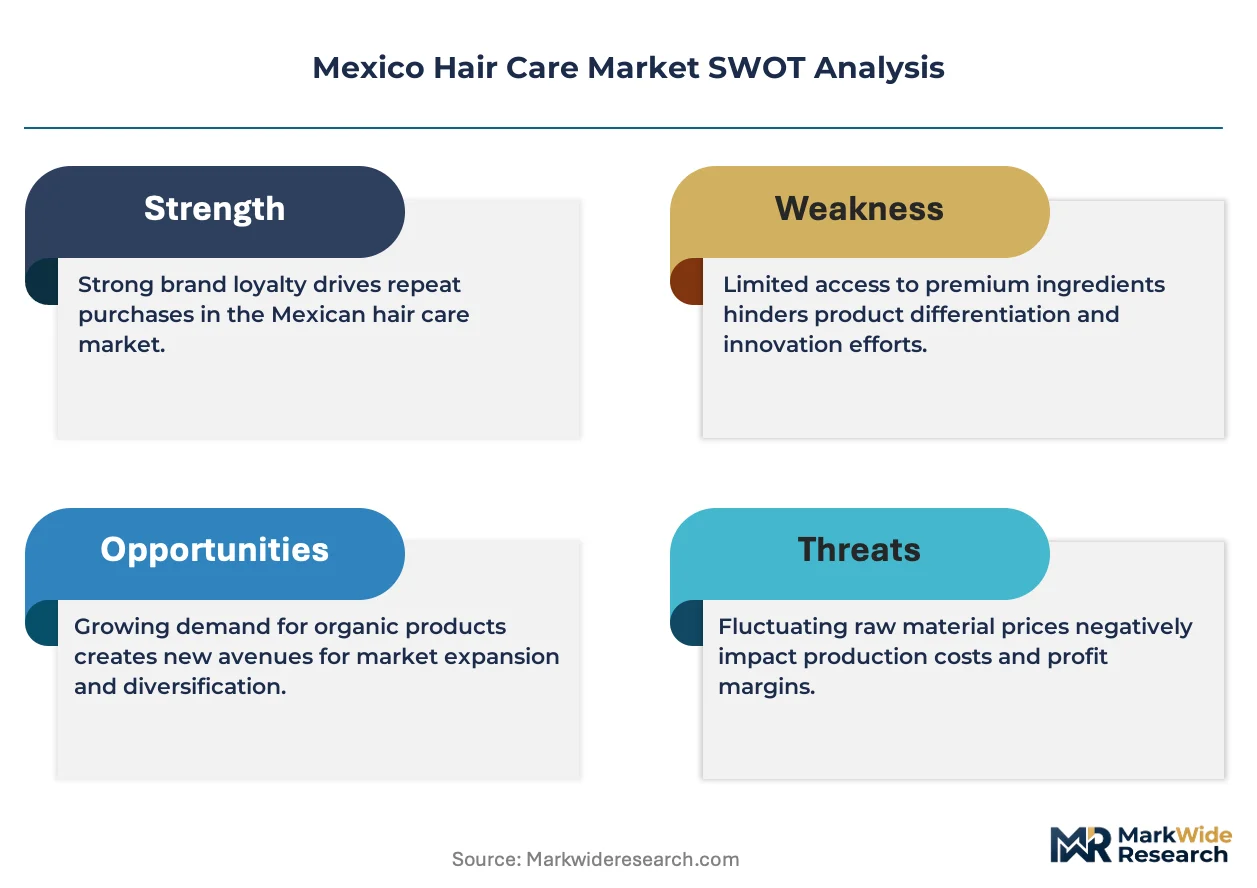
Multi-source ingredient procurement is consolidating across Mexico's hair care supply base as brands seek greater control over botanical extract quality and synthetic surfactant consistency. Genomma Lab Internacional leverages its domestic manufacturing footprint to anchor distribution across pharmacy and mass-market channels. L'Oréal SA sustains R&D intensity in specialized hair treatment formulations for the professional salon segment. Unilever PLC competes through extensive brand portfolios spanning economy to premium positioning.
Hair care encompasses formulations designed to cleanse, condition, treat, and style human hair, typically combining surfactant systems, emollients, active ingredients, and preservatives at pH ranges between 4.5 and 6.5 to maintain cuticle integrity and scalp health. Shampoos and conditioners constitute the volume core of the Mexican market, while hair treatments capture disproportionate margin pools due to higher active-ingredient concentrations and professional-channel pricing power. Natural and organic ingredient segments attract investment as COFEPRIS tightens labeling scrutiny and consumers gravitate toward plant-derived formulations. Salons emerge as a high-growth customer type, with professional-only SKUs generating recurring bulk purchases distinct from retail dynamics.
COFEPRIS mandates pre-market registration for all cosmetic products sold in Mexico, compelling reformulation cycles and documentation investments that favor established players with regulatory affairs capacity. NOM standards for product safety and labeling, alongside evolving state-level environmental regulations governing plastic packaging waste in Jalisco and Nuevo León, reshape operational compliance burdens. Stakeholders must monitor pending federal legislation on extended producer responsibility for personal care packaging, as this will determine capital allocation between recyclable bottles, refill pouches, and alternative material formats.
Market Dynamics
Professional salon channel expansion across Mexican metropolitan zones is restructuring demand concentration, pulling formulation standards upward and fragmenting procurement patterns between mass retail and specialized institutional buyers.
Growth Catalysts
- Salon channel proliferation:Professional styling services multiply across Mexico City, Guadalajara, and Monterrey, generating recurring bulk purchases of treatment-grade formulations distinct from retail dynamics.
- COFEPRIS registration maturation:Pre-market cosmetic registration requirements favor established players with regulatory affairs capacity, consolidating market access for compliant domestic and international brands.
- Botanical extract quality control:Multi-source ingredient procurement consolidation enables brands to anchor surfactant consistency and plant-derived formulation integrity across pharmacy and mass-market channels.
Market Restraints
- Synthetic surfactant input volatility:Petroleum-derived feedstock price instability compresses margin pools for standard shampoo and conditioner formulations.
- COFEPRIS documentation burden:Pre-market registration cycles and reformulation requirements create fixed compliance costs that disproportionately burden smaller domestic manufacturers.
- Plastic packaging substitution pressure:State-level environmental regulations in Jalisco and Nuevo León constrain conventional bottle formats while viable alternatives remain cost-prohibitive at scale.
Strategic Opportunities
- Refill pouch distribution innovation:Extended producer responsibility legislation pending at federal level creates first-mover advantage for brands investing in alternative material formats.
- Professional-only SKU expansion:Salon-exclusive treatment lines with higher active-ingredient concentrations capture disproportionate margin pools through institutional pricing power.
- NOM standards alignment:Evolving federal safety and labeling mandates reward early compliance investment with accelerated market access versus lagging competitors.
Industry Challenges
- Regulatory affairs talent scarcity:COFEPRIS documentation expertise concentrates among established players, constraining new entrant capacity to navigate pre-market registration timelines.
- Packaging format capex intensity:Transition capital requirements for recyclable bottles, refill pouches, and alternative materials strain mid-tier manufacturer balance sheets.
- Legacy distribution integration friction:Pharmacy and mass-market channel incumbents face complexity embedding salon-direct institutional sales operations alongside retail logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Hair Care Market |
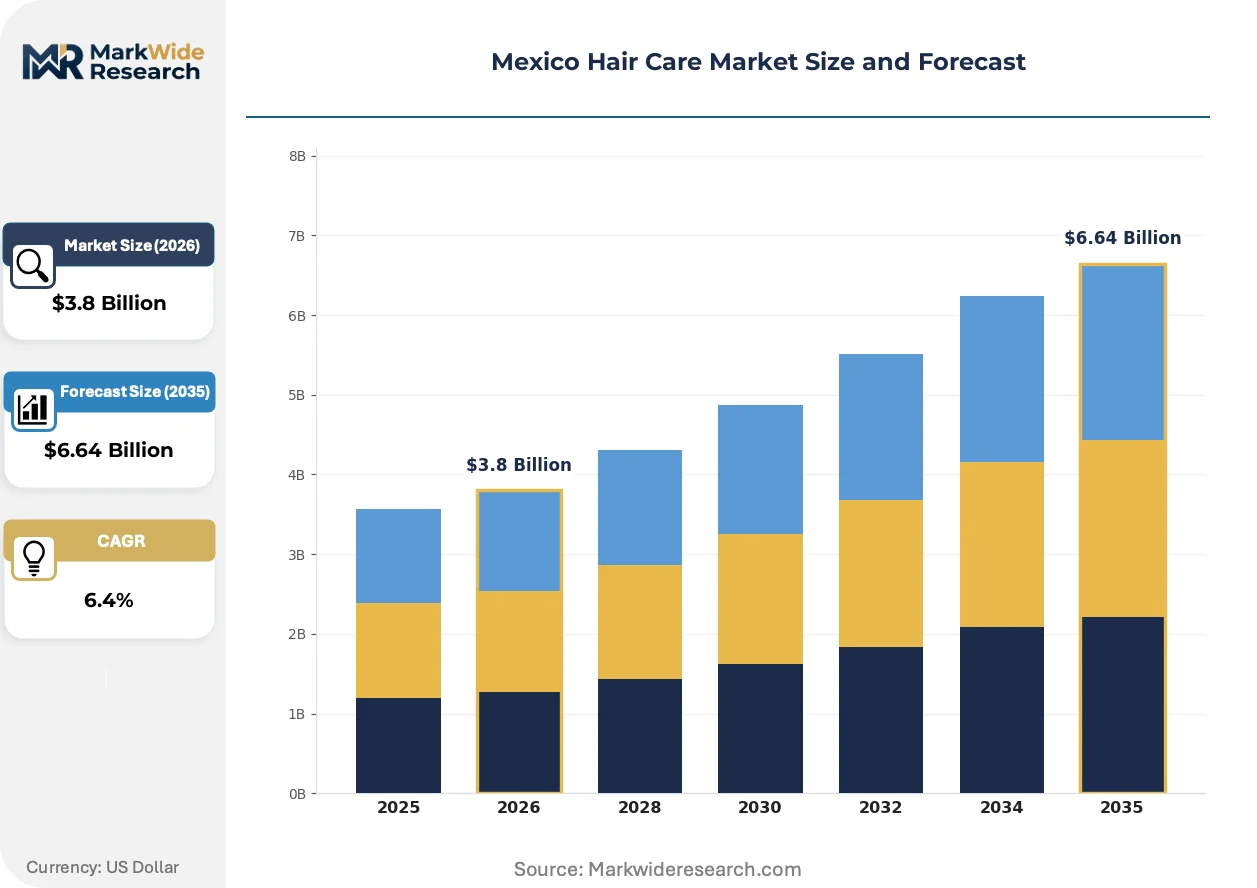
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Hair Treatments Customer Type: Men, Women, Children, Salons Ingredient: Natural, Synthetic, Organic, Herbal Packaging Type: Bottles, Tubes, Jars, Pouches |
| Companies Covered | Genomma Lab Internacional, S.A.B. de C.V., Henkel AG and Co. KGaA, Unilever PLC, Beiersdorf AG, Kao Corporation, L'Oréal SA, Kenvue, Alticor Global Holdings Inc., The Procter and Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Hair Care Market Shifts & Advancements
Formulation transparency and channel specialization are restructuring competitive positioning in Mexican hair care, with regulatory scrutiny and professional service expansion driving divergence between mass and premium segments.
Biotechnology-derived active ingredients are decentralizing traditional botanical extraction supply chains. Domestic manufacturers adopt enzymatic and fermentation-based processes to produce ceramides, peptides, and scalp microbiome modifiers. This technology is decentralizing raw material sourcing away from concentrated agricultural regions toward controlled bioreactor facilities near formulation plants.
COFEPRIS labeling scrutiny tightens disclosure requirements for "natural" and "organic" claims, compelling reformulation cycles and third-party certification investments. The industrial consequence is margin compression for brands relying on ambiguous ingredient positioning. Professional salon segments respond fastest, leveraging institutional buyer sophistication to transition toward verified clean-label portfolios before mass-market adaptation.
Salon-direct procurement models disrupt traditional distributor intermediation. Professional stylists and clinic operators consolidate purchasing through institutional accounts, bypassing wholesale layers that previously captured value. This channel disintermediation concentrates most visibly in Mexico City and Monterrey, where salon density supports dedicated sales force economics and bulk delivery infrastructure.
Mexico Hair Care Market Segmentation
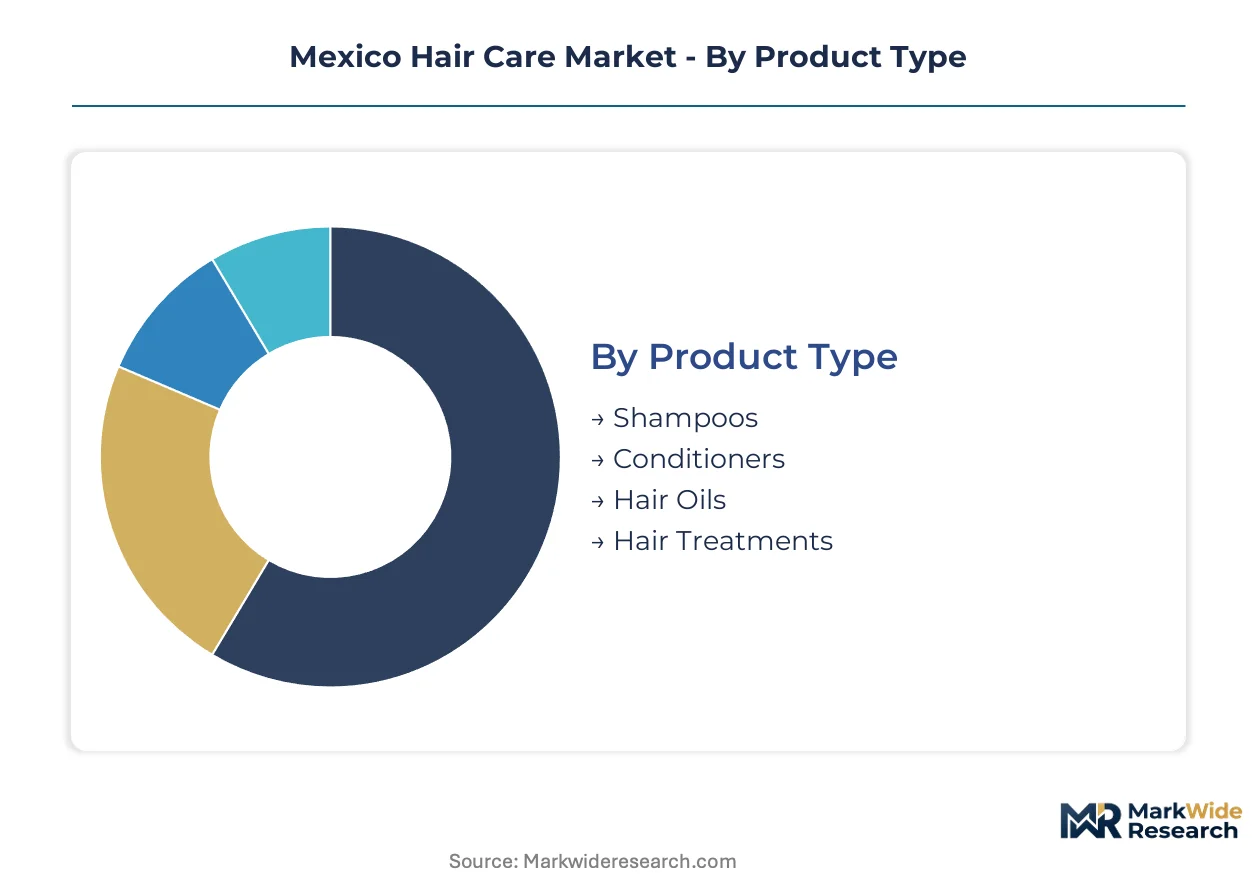
Segmentation in Mexican hair care reveals distinct procurement patterns between mass retail and professional channels, with COFEPRIS registration requirements and salon expansion reshaping how categories perform across customer touchpoints.
Product Type:
Shampoos and conditioners operate as standalone daily-use essentials, while hair treatments embed within professional service protocols and intensive home regimens.
- Shampoos:Surfactant-based cleansing formulations at pH 4.5-6.5 maintain cuticle integrity through anionic and amphoteric systems. Demand concentrates in mass retail across Mexico City and Guadalajara, where urban consumers drive frequent repurchase cycles and bulk-format adoption.
- Conditioners:Cationic emulsion systems deposit fatty alcohols and silicones to reduce friction and enhance combability. Salon channels in Monterrey generate disproportionate institutional volumes as professional stylists specify treatment-grade variants for post-chemical service recovery.
- Hair Oils:Occlusive and penetrating oil blends target specific porosity profiles in curly and coily hair segments.
- Hair Treatments:High-active-concentration masks and serums command premium positioning through pharmacy and professional-only distribution.
Shampoos lead volumes today; hair treatments are gaining share fastest.
Customer Type:
Volume distribution splits between individual consumers purchasing at retail price points and institutional buyers capturing wholesale economies through recurring bulk orders.
- Women:Primary decision-makers for household hair care procurement across all product categories, with elevated spend on conditioning and treatment segments. Concentration in metropolitan zones drives premium-format uptake and multi-step regimen adoption.
- Salons:Professional styling services generate recurring institutional purchases of treatment-grade formulations and back-bar sizes unavailable at retail. Channel expansion across Guadalajara and Monterrey creates dedicated sales force economics for bulk delivery infrastructure.
- Men:Simplified regimen preferences favor combination shampoo-conditioner formats and styling products over intensive treatments.
- Children:Mild-formulation demand concentrates in pharmacy channels with tear-free and hypoallergenic positioning requirements.
Women lead volumes today; salons are expanding most quickly.
Ingredient:
Formulation philosophy determines regulatory pathway complexity and margin structure, with verified claims commanding shelf price premiums.
- Synthetic:Petroleum-derived surfactants and silicones deliver consistent performance at scale. Jalisco and Nuevo León manufacturing bases anchor domestic production, though feedstock price volatility compresses margin pools for standard formulations.
- Natural:Plant-derived extracts and minimally processed oils attract COFEPRIS labeling scrutiny, compelling third-party certification investments. Mexico City consumers drive disproportionate demand for verified botanical claims.
- Organic:Certified organic raw materials command premium positioning through pharmacy and specialty retail with full traceability documentation.
- Herbal:Traditional botanical preparations target specific scalp conditions through ethnic retail and regional pharmacy networks.
Synthetic leads volumes today; natural is climbing the fastest.
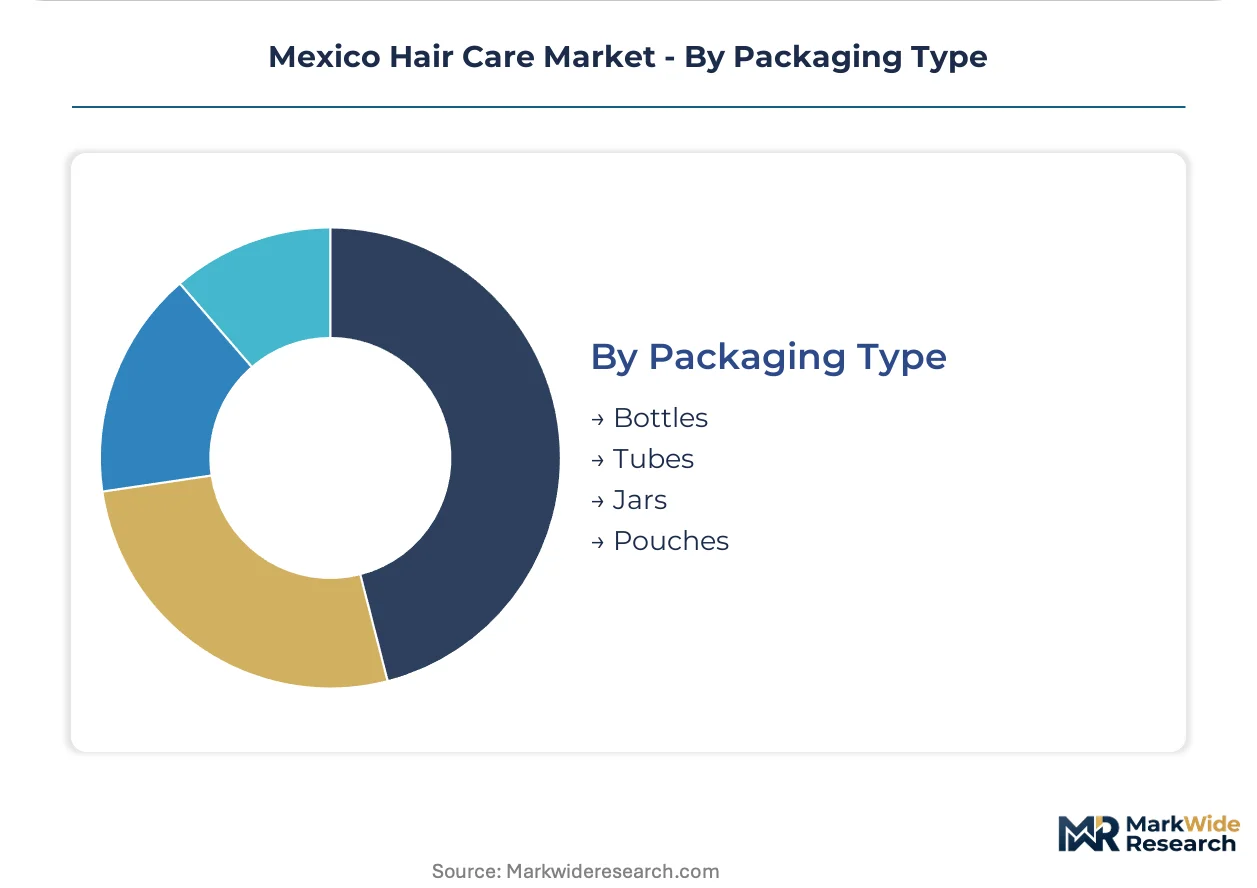
Packaging Type:
Format selection intersects with state-level environmental regulations and distribution channel requirements, determining capital allocation and operational compliance burdens.
- Bottles:Conventional PET and HDPE formats dominate mass retail shelf presence. Jalisco state regulations on plastic waste constrain conventional formats while recyclable alternatives remain cost-prohibitive at scale for mid-tier manufacturers.
- Pouches:Flexible refill formats reduce material intensity and logistics cost for high-velocity shampoo and conditioner SKUs. Pending federal extended producer responsibility legislation positions early movers for compliance advantage.
- Tubes:Collapsible aluminum and laminate structures suit treatment and styling products with lower velocity and higher margin profiles.
- Jars:Rigid containers accommodate thick cream and mask consistencies for professional back-bar and premium retail positioning.
Bottles lead volumes today; pouches show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City Metro anchors the national hair care demand base, with professional salon density and pharmacy channel penetration driving formulation standards across the country.
Mexico City Metro
Urban consumers in the capital drive premium product uptake and multi-step regimen adoption across pharmacy and specialty retail channels. COFEPRIS headquarters proximity accelerates registration compliance timelines for brands maintaining local regulatory affairs capacity. The metropolitan zone concentrates professional styling service expansion, generating institutional bulk purchases of treatment-grade formulations distinct from mass retail dynamics.
Nuevo León
Monterrey's industrial base supports manufacturing operations for domestic and multinational brands serving northern Mexico and export markets. State-level environmental regulations on plastic packaging waste constrain conventional bottle formats while positioning early movers for federal extended producer responsibility compliance. The metropolitan area's salon density enables dedicated sales force economics for professional-only SKU distribution.
Jalisco
Guadalajara anchors western Mexico demand with elevated pharmacy channel penetration and natural-ingredient product preference. State environmental mandates on plastic waste reshape operational compliance burdens for manufacturers operating local production facilities. The metropolitan cluster supports institutional procurement consolidation as salon chains expand professional service capacity.
Bajío Region
Querétaro and Guanajuato manufacturing corridors attract formulation plant investment due to central logistics positioning and skilled labor availability. NOM standards alignment investments reward early compliance with accelerated market access versus lagging competitors. The region's emerging urban centers generate incremental retail channel demand for standard shampoo and conditioner formats.
Northern Border States
Cross-border commercial flows in Baja California and Chihuahua expose consumers to US product availability and pricing benchmarks. Customs and trade facilitation protocols shape import logistics for international brands entering through Tijuana and Ciudad Juárez. The border corridor concentrates duty-free and informal channel dynamics that fragment official retail tracking.
Mexico Hair Care Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue botanical certification and salon-direct specialization. The market exhibits moderate consolidation around multinational FMCG portfolios and domestic manufacturing specialists with regulatory affairs capacity. Three archetypes dominate: mass-market brand houses with pharmacy channel anchoring, professional salon specialists with institutional pricing power, and natural-ingredient challengers with third-party certification investments. Competitive moves concentrate on portfolio diversification into treatment-grade formulations and geographic expansion through salon channel penetration.
Within the domestic manufacturing tier, Genomma Lab Internacional occupies a position exemplifying pharmacy and mass-market channel anchoring through local production infrastructure. L'Oréal SA and Unilever PLC represent multinational archetypes with diversified brand portfolios spanning economy to premium positioning and professional salon segmentation. These three companies illustrate the competitive spectrum from domestic regulatory compliance specialization to global R&D intensity and channel breadth.
| Leading Market Players |
|---|
| Genomma Lab Internacional, S.A.B. de C.V. |
| Henkel AG and Co. KGaA |
| Unilever PLC |
| Beiersdorf AG |
| Kao Corporation |
| L'Oréal SA |
| Kenvue |
| Alticor Global Holdings Inc. |
| The Procter and Gamble Company |
| Others |
Supply & Pricing Matrix
Formulation chemist concentration in Guadalajara and Mexico City creates labor-cost differentials that widen pricing-tier spreads between mass-market shampoos and professional salon treatments. COFEPRIS compliance expertise scarcity in peripheral states further fragments cost structures across domestic manufacturing bases.
Pricing Analysis
Petroleum-derived surfactant cost pass-through from Jalisco petrochemical suppliers compresses margins for standard shampoo formulations while protecting premium treatment-grade SKUs. Three-tier pricing structure across premium, standard, and economy levels separates salon-exclusive lines with verified botanical certification from mass retail variants with ambiguous natural claims. Price differentiation hinges on COFEPRIS registration tier and active-ingredient concentration grade. Cost compression in economy tiers is intensifying because feedstock volatility outpaces reformulation cycle timelines. Pharmacy channel buyers in Mexico City exhibit lowest price sensitivity; rural mass-market distributors face highest.
Supply Chain Analysis
Synthetic surfactant supply rests on petroleum feedstock flows from US Gulf Coast refineries and domestic Pemex derivative production. Specialty botanical extracts draw from concentrated agricultural regions in Oaxaca and Veracruz, with ceramide and peptide inputs increasingly sourced from controlled bioreactor facilities near Monterrey formulation plants. Single-source vulnerability concentrates in COFEPRIS-certified preservative suppliers, where import documentation delays create batch-release bottlenecks. Distribution runs through pharmacy wholesale consolidators in Mexico City, with salon-direct institutional accounts bypassing traditional layers in Monterrey and Guadalajara metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by the shift from synthetic surfactant formulations toward verified clean-label portfolios with third-party botanical certification.
For Market Incumbents: Cement salon channel control through exclusive back-bar size distribution and institutional pricing frameworks that lock professional stylists into recurring bulk orders. Defend against natural-ingredient challengers by accelerating COFEPRIS pre-registration of biotechnology-derived active portfolios before labeling scrutiny tightens. Priority lever: captive supply of fermentation-based ceramide production through backward integration into Guadalajara bioreactor infrastructure.
For New Entrants and Emerging Players: COFEPRIS registration maturation in Mexico opens a window for regulatory affairs specialists to capture pharmacy channel access that larger multinationals have not prioritized. Target white-space in salon-exclusive treatment lines for curly and coily hair segments, where institutional buyer sophistication supports premium positioning without mass-market advertising scale. Go-to-market angle: direct sales force deployment in Monterrey metropolitan zone with bulk delivery infrastructure bypassing wholesale intermediation.
For Investors and Strategic Acquirers: Domestic pharmaceutical conglomerates are the most active acquirer in this space, seeking brand portfolios with established COFEPRIS compliance capacity and pharmacy channel anchoring. Long-term viability centers on 5-10 year regulatory tailwinds favoring clean-label verification and professional salon expansion. Acquisition target archetype: mid-tier manufacturers with Jalisco production facilities and underexploited salon-direct sales infrastructure. Signal to watch: federal extended producer responsibility legislation passage triggering packaging format capex consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Salon-Direct Distribution Buildout | Bypasses wholesale intermediation in Monterrey and Guadalajara, capturing institutional pricing power. |
| Biotechnology-Derived Active Investment | Decentralizes supply from Oaxaca agricultural regions toward controlled Guadalajara bioreactor facilities. |
| COFEPRIS Pre-Registration Acceleration | Locks market access ahead of labeling scrutiny tightening on natural and organic claims. |
| Refill Pouch Format Scale-Up | Positions early movers for federal extended producer responsibility compliance advantage. |
| Professional-Only SKU Expansion | Captures disproportionate margin pools through treatment-grade formulations unavailable at retail. |
Research Methodology
Multiple input streams — primary interviews with formulation chemists, salon chain procurement directors, and pharmacy category buyers; secondary validation through COFEPRIS registration databases, customs import records, and NOM standards documentation; plus retail audit data from Nielsen and Circana — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned domestic manufacturers in Jalisco, multinational brand managers in Mexico City, and professional stylist networks across Guadalajara and Monterrey.
Data-stream reconciliation anchored volume and value outputs across product type, customer segment, ingredient philosophy, and packaging format dimensions, with geographic clustering modeled at metropolitan zone resolution. CAGRs were derived from segment-level growth trajectory analysis incorporating salon channel expansion rates and COFEPRIS registration timeline assumptions. Industry-specific forecast inputs included petroleum feedstock price volatility indices and state-level environmental regulation implementation schedules.
Revisions become necessary when federal extended producer responsibility legislation accelerates, COFEPRIS labeling scrutiny tightens beyond current NOM alignment timelines, or biotechnology-derived active ingredient adoption outpaces fermentation capacity buildout. Forecasts reflect documented assumptions on salon density growth and regulatory compliance cost trajectories. A small set of named triggers — federal packaging mandates, feedstock price shock events, and professional channel consolidation waves — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Global Premium Hair Care Market
Hair Care
Global Shampoo Market
Hair Care
North America Hair Care Market
Hair Care
Hair Care Appliances Market
Hair Care
Global Hair Color Market
Hair Care
Hair Edge Tamer Market
Hair Care
United Arab Emirates Hair Care Market
Hair Care
Hair Care Products Market
Hair Care
India Hair Care Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Hair Spray Market
Hair Care
Europe Hair Care Market
Hair Care
Chile Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Sweden Hair Care Market
Hair Care
Germany Hair Care Market