
 Chile Hair Care Market | 2026-2036
Chile Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Hair Care Market Outlook
Chile's cosmetic ingredient disclosure regulation is consolidating compliance costs for new entrants while favoring incumbents with established quality infrastructure. L'Oreal SA leverages its global R&D network to navigate these standards efficiently. Laboratorio Durandin S.A.I anchors its position through deep distribution in Chilean pharmacies and specialty retail channels.
Chile hair care encompasses products formulated for cleansing, conditioning, treating, and styling human hair, typically incorporating surfactant systems, emollients, active botanical extracts, and functional polymers designed to maintain scalp health and hair fiber integrity across diverse climate conditions from coastal humidity to Andean aridity. Shampoos and conditioners occupy the core volume base, while sulfate-free and organic formulations capture expanding margin pools as consumers prioritize scalp-sensitive and clean-label positioning. Specialty stores and online retail channels represent the fastest-growing distribution vectors, though supermarkets still dominate absolute transaction volume.
Chile's Instituto de Salud Pública enforces cosmetic safety standards aligned with MERCOSUR technical regulations, while the national consumer protection agency monitors labeling claims; together these bodies elevate transparency requirements and restrict unsubstantiated benefit messaging. Compliance with these frameworks shapes product development timelines and import authorization processes for multinational suppliers. Stakeholders must monitor evolving MERCOSUR harmonization proposals and local enforcement intensity to calibrate portfolio and market entry timing.
Market Dynamics
Chile's Instituto de Salud Pública cosmetic ingredient disclosure mandate is forcing reformulation across the entire hair care supply chain, compressing product development timelines while elevating compliance costs for importers and domestic manufacturers alike.
Growth Catalysts
- MERCOSUR Technical Regulation Harmonization:Alignment with regional standards streamlines cross-border product registration and reduces duplicative testing burdens for Chilean manufacturers exporting to Argentina and Brazil.
- Santiago Metropolitan Region Urban Density:Concentrated professional salon networks in Santiago's Providencia and Las Condes districts generate sustained demand for premium treatment formulations and scalp-specific products.
- Sulfate-Free Surfactant Substitution:Sodium cocoyl isethionate and amino acid-derived cleansing systems capture expanding shelf space as scalp-sensitive positioning penetrates pharmacy and specialty retail channels.
Market Restraints
- Import Dependency on Active Botanicals:Chilean formulators rely on concentrated extracts from Amazonian and Asian supply bases, exposing margins to currency volatility and maritime shipping disruptions.
- Laboratory Testing Bottleneck:Limited Instituto de Salud Pública-accredited facilities for cosmetic safety evaluation extend product authorization timelines for new entrants.
- Water Scarcity in Northern Regions:Antofagasta and Atacama manufacturing sites face extraction restrictions that constrain production scaling for water-intensive emulsion products.
Strategic Opportunities
- Valparaíso Regional Port Logistics:Free trade zone infrastructure enables re-export positioning to Pacific Alliance markets with reduced tariff friction.
- Pharmacy Channel Professionalization:Farmacias Ahumada and Cruz Verde expansion of dermocosmetic sections creates dedicated shelf space for clinically positioned hair treatment lines.
- Indigenous Botanical IP Development:Quillay saponin and maqui extract commercialization offers differentiated positioning against standardized international ingredient portfolios.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Chilean universities produce limited formulation specialists trained in MERCOSUR-compliant safety assessment protocols.
- Legacy ERP Integration:Mid-tier domestic manufacturers struggle to implement batch-level traceability systems required for ingredient disclosure compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Hair Care Market |
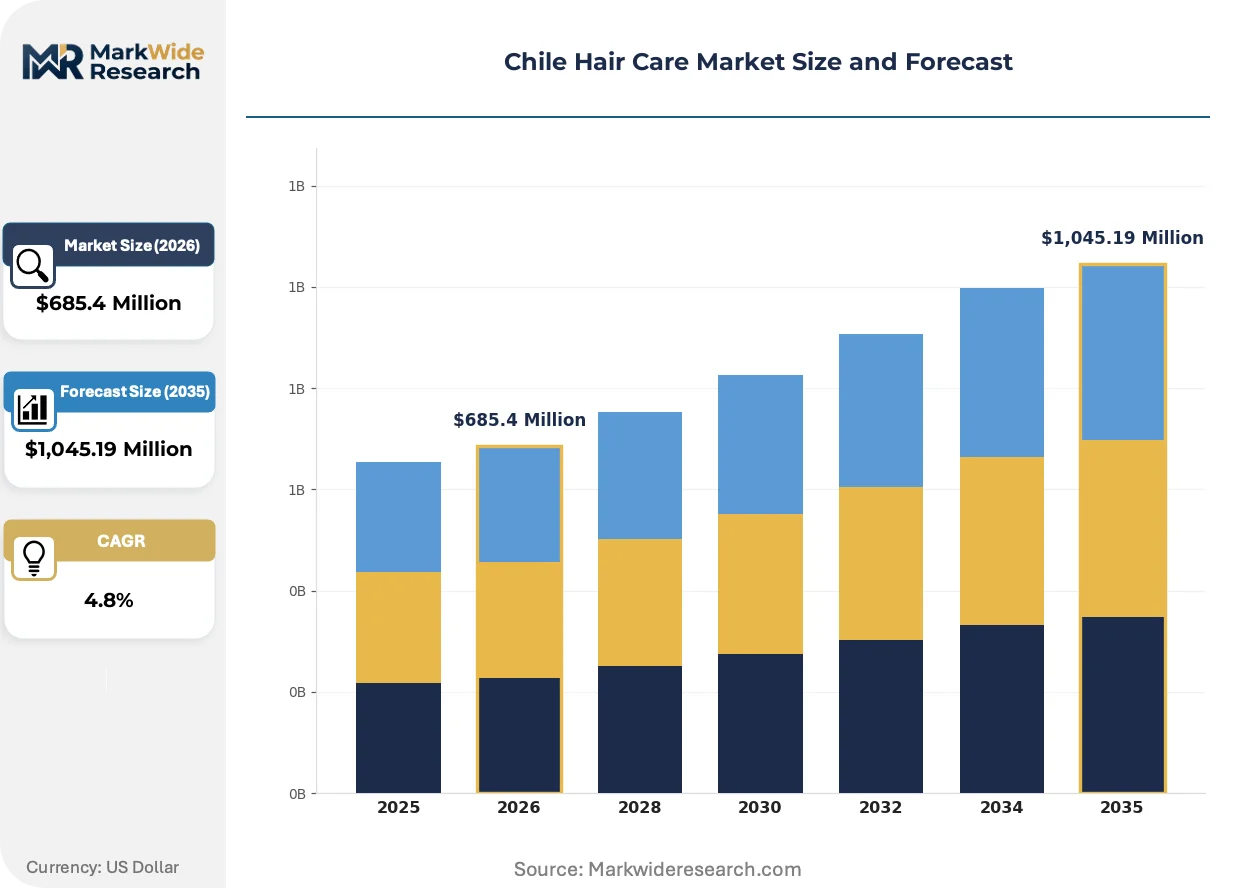
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Styling Products End User: Women, Men, Salons, Children Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Pharmacies Formulation: Organic, Chemical-Based, Herbal, Sulfate-Free |
| Companies Covered | Coty Inc, Shiseido Company Limited, L'Oreal SA, Laboratorio Durandin S.A.I, Laboratorio Ballerina Ltd, The Procter & Gamble Company, Henkel AG & Co KGaA, Moroccanoil Israel Ltd, Unilever Plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Hair Care Market Strategic Shifts
Sustainability verification and digital channel expansion are restructuring how Chilean consumers evaluate and purchase hair care products, with transparency claims now serving as primary purchase filters alongside performance.
Biodegradable conditioning polymers derived from fermented agricultural feedstocks are modularizing traditional silicone-based detangling systems. Professional salons in Santiago's upscale districts adopt these materials rapidly to align with client sustainability expectations. The technology is modularizing supplier relationships as domestic compounders gain formulation autonomy previously held by multinational specialty chemical houses.
Chile's Instituto de Salud Pública disclosure rules now mandate full fragrance component enumeration on cosmetic labels, eliminating previous loopholes for proprietary scent blends. Domestic manufacturers accelerate reformulation to reduce complex allergen profiles. Color-treated hair segments face the steepest adjustment costs as oxidative dye systems require extensive re-documentation.
Subscription-based replenishment models displace supermarket bulk purchasing among metropolitan millennials. Digital-native brands capture recurring revenue through personalized algorithmic recommendations. This pattern concentrates in Santiago's higher-income comunas where delivery logistics density supports unit-economics viability.
Chile Hair Care Market Segmentation
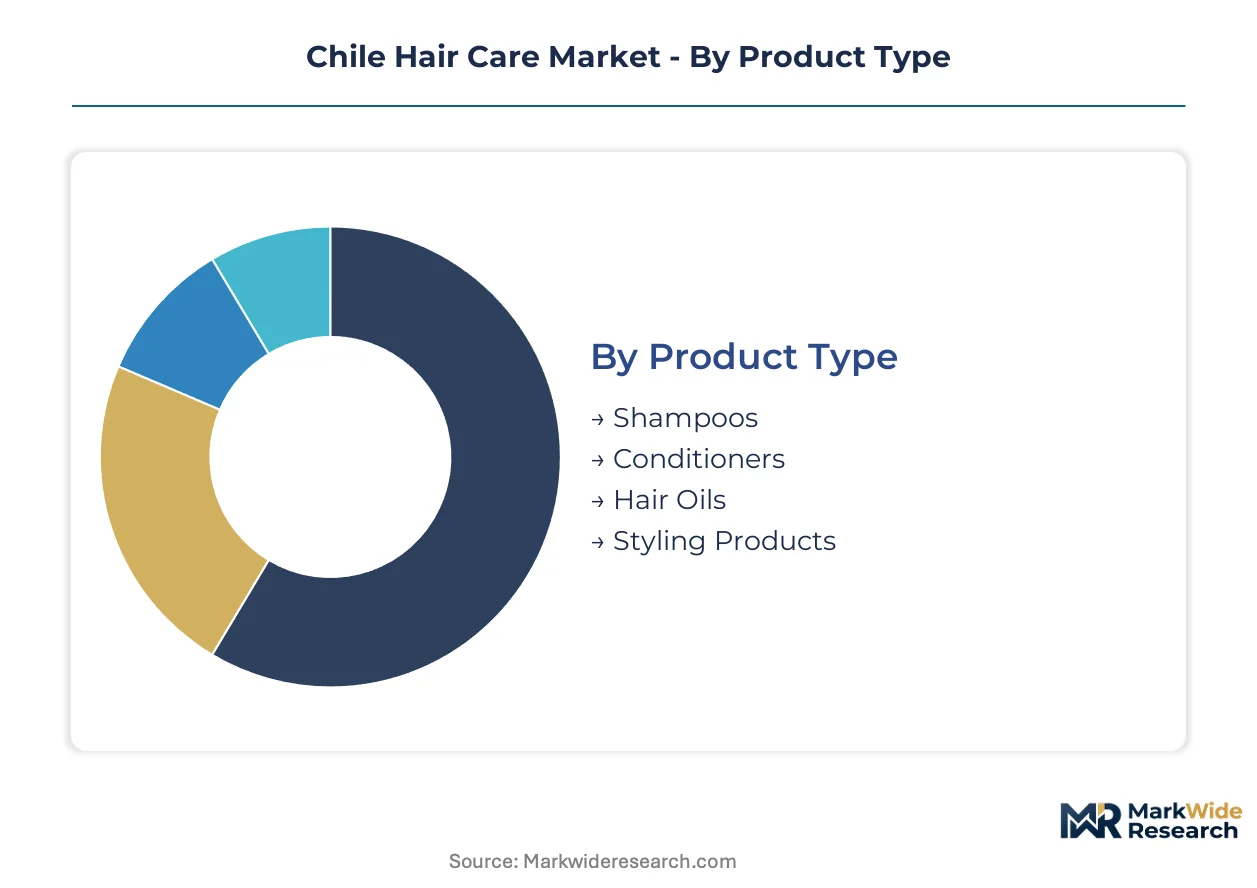
Chile's hair care segmentation reveals how consumer priorities fragment across performance expectations, channel accessibility, and ingredient transparency mandates. Understanding these divides enables suppliers to calibrate portfolio depth and pricing architecture against distinct buyer willingness-to-pay thresholds.
Product Type:
Shoppers prioritize cleansing efficacy and scalp compatibility as foundational purchase criteria, with secondary consideration for styling versatility and treatment intensity.
- Shampoos:Surfactant-based cleansing formulations dominate household penetration across Santiago's metropolitan comunas, where hard water mineral content drives demand for chelating variants. Supermarket shelf space allocation and pharmacy dermocosmetic positioning sustain volume leadership despite margin compression from private-label competition.
- Conditioners:Cationic emulsion systems capture premium positioning in Las Condes and Providencia salon channels, where Brazilian blowout maintenance and color-treated fiber repair command elevated price points. Silicone-free and quaternium-free alternatives accelerate in pharmacy segments aligned with clean-label preferences.
- Hair Oils:Argan and native botanical blends concentrate in specialty retail and online subscription models targeting Antofagasta's arid climate conditions.
- Styling Products:Polymer-based hold systems and sea salt sprays cluster in urban professional networks and coastal humidity-exposed consumer bases.
Shampoos lead on scale; conditioners lead on momentum.
End User:
Volume concentration and margin capture diverge sharply across demographic segments, with professional intermediaries extracting service premiums unavailable in direct-to-consumer channels.
- Women:Multi-step regimen adherence drives category breadth in household purchasing decisions, spanning daily cleansing through weekly treatment masking. Santiago's higher-income female demographics sustain premium natural-positioned brand loyalty despite supermarket promotional intensity.
- Salons:Professional service providers in Vitacura and Ñuñoa districts generate concentrated demand for back-bar treatment systems and oxidative color maintenance protocols. Technical education requirements and Instituto de Salud Pública compliance documentation elevate supplier switching costs.
- Men:Simplified routine preferences favor 2-in-1 conditioning cleansers and styling hybrids distributed through mass retail and convenience channels.
- Children:Tear-free surfactant systems and allergen-minimized formulations concentrate in pharmacy and pediatric-directed specialty retail.
Women dominate absolute transaction volume; salons generate steepest margin expansion.
Distribution Channel:
Channel selection determines regulatory exposure, working capital intensity, and consumer education requirements for brand builders.
- Supermarkets:Cencosud and Walmart Chile networks sustain mass-market volume through promotional calendar density and private-label shelf presence. Sulfate-free and natural-positioned entrants face placement barriers against incumbent multinational slotting fee structures.
- Pharmacies:Farmacias Ahumada and Cruz Verde dermocosmetic expansions create clinically positioned hair treatment destinations with pharmacist endorsement leverage. Instituto de Salud Pública disclosure compliance serves as entry qualification rather than differentiation.
- Online Retail:Algorithmic personalization and subscription replenishment models capture Santiago metropolitan millennials through Mercado Libre and direct-to-native brand platforms.
- Specialty Stores:Professional-only and clean beauty boutiques concentrate in Providencia and Lastarria districts, curating indie and imported portfolios.
Supermarkets retain volume dominance; online retail climbs the fastest.
Formulation:
Ingredient transparency mandates and climate-adaptive performance requirements reshape formulation investment priorities across the supply base.
- Sulfate-Free:Sodium cocoyl isethionate and amino acid-derived surfactant systems displace traditional SLS/SLES bases in pharmacy and specialty channels, responding to scalp sensitivity positioning and Santiago dermatologist recommendations. Reformulation costs and preservative system stability challenges constrain mid-tier domestic manufacturer adoption.
- Organic:Certified botanical content and biodegradable claim verification capture premium shelf space in specialty retail and export-oriented production. Quillay saponin and maqui extract commercialization offers indigenous IP differentiation against standardized international portfolios.
- Herbal:Traditional botanical positioning without formal certification concentrates in mass-market price tiers and regional interior distribution.
- Chemical-Based:Conventional synthetic active systems retain cost-competitive positioning in supermarket volume segments and professional oxidative color categories.
Chemical-based formulations retain scale leadership; sulfate-free alternatives gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hair care manufacturing in Chile traces its commercial lineage to mid-20th century pharmacy compounding traditions in Santiago, where local laboratories first scaled emulsion production for domestic distribution before multinational entrants established formulation facilities during the 1990s trade liberalization era.
Santiago Metropolitan Region
Providencia and Las Condes districts concentrate professional salon networks generating concentrated demand for premium treatment formulations. Instituto de Salud Pública disclosure mandates reshape product authorization timelines for manufacturers headquartered in this region. Vitacura and Ñuñoa industrial zones host blending facilities serving pharmacy and specialty retail channels.
Valparaíso Region
Port logistics infrastructure enables re-export positioning to Pacific Alliance markets with reduced tariff friction. Free trade zone status attracts multinational distribution centers seeking Andean market access. Quillay extract processing facilities near San Antonio support indigenous botanical ingredient commercialization.
Antofagasta Region
Arid climate conditions drive specialized demand for moisture-retention formulations among coastal mining communities. Water extraction restrictions constrain emulsion manufacturing scale at regional production sites. Local distributors prioritize oil-based treatment products requiring minimal water content.
Bío Bío Region
Concepción metropolitan area anchors southern Chile retail distribution networks reaching Temuco and Valdivia markets. Regional pharmacy chains expand dermocosmetic shelf space for clinically positioned hair treatments. Manufacturing subcontractors serve Santiago-based brands seeking production diversification.
Chile Hair Care Market Competitive Environment
The competitive structure tilts toward multinational incumbents with established regulatory compliance infrastructure. Market concentration reflects high barriers from Instituto de Salud Pública authorization requirements and pharmacy channel slotting arrangements. Three archetypes dominate: global beauty conglomerates with integrated R&D networks, regional specialists leveraging Andean botanical positioning, and domestic laboratories with deep pharmacy distribution relationships. Capacity expansion and indigenous ingredient IP development represent the dominant competitive vectors.
Within the multinational tier, L'Oreal SA and Shiseido Company Limited occupy positions reflecting global formulation standardization adapted to MERCOSUR compliance frameworks. Among domestic specialists, Laboratorio Durandin S.A.I exemplifies pharmacy-anchored distribution models. Coty Inc represents the fragrance-forward archetype navigating Chile's expanded disclosure requirements for scent component enumeration.
| Leading Market Players |
|---|
| Coty Inc |
| Shiseido Company Limited |
| L'Oreal SA |
| Laboratorio Durandin S.A.I |
| Laboratorio Ballerina Ltd |
| The Procter & Gamble Company |
| Henkel AG & Co KGaA |
| Moroccanoil Israel Ltd |
| Unilever Plc |
| Others |
Value Chain & Pricing Dynamics
Cosmetic chemist concentration in Santiago Metropolitan Region establishes labor-cost differentials that widen pricing-tier spreads between multinational premium formulations and domestic standard-economy alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates Chile hair care, with price differentiation resting on Instituto de Salud Pública compliance certification and salon channel exclusivity versus mass retail accessibility. Pricing pressure stems from private-label supermarket competition compressing mid-tier margins. Pharmacy channel buyers exhibit lowest price sensitivity due to dermocosmetic endorsement premiums, while mass-market consumers demonstrate highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Santiago and Valparaíso manufacturing zones elevate production costs for MERCOSUR-compliant formulation specialists. Supply concentrates in Brazil, Argentina, and domestic Chilean facilities for finished goods, with raw material dependencies on Amazonian botanical extracts, Asian surfactant feedstocks, and European specialty polymers. Single-source vulnerability in maritime shipping routes from Asian suppliers poses structural risk. Distribution runs through pharmacy chains, supermarket networks, and direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile hair care operates as a stable compounder, with urban demographic expansion in Santiago Metropolitan Region driving steady regimen penetration and premium tier upgrading.
For Market Incumbents: Extend formulation R&D investment into indigenous botanical IP to preempt emerging Andean specialist competitors. Deepen pharmacy channel control through exclusive Farmacias Ahumada and Cruz Verde shelf arrangements. Instituto de Salud Pública disclosure mandates favor incumbents with established compliance infrastructure. For New Entrants and Emerging Players: Enter via sulfate-free subscription models targeting Santiago millennials through Mercado Libre and native direct-to-consumer platforms. White-space concentration exists in indigenous ingredient storytelling for export-oriented Pacific Alliance positioning. Pharmacy dermocosmetic sections offer most penetrable channel entry with pharmacist endorsement leverage. For Investors and Strategic Acquirers: Regional beauty conglomerates with MERCOSUR manufacturing footprints are the most active acquirers in this space, seeking pharmacy-distributed domestic laboratories to anchor Andean market access. Long-term viability centers on indigenous ingredient IP portfolios and compliance infrastructure amortization across regional harmonization. Monitor Instituto de Salud Pública enforcement intensity as inflection indicator for authorization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Indigenous Botanical IP Development | Quillay saponin and maqui extract commercialization differentiates against standardized international ingredient portfolios. |
| Pharmacy Channel Professionalization | Farmacias Ahumada and Cruz Verde dermocosmetic expansions create clinically positioned hair treatment destinations. |
| Sulfate-Free Formulation Transition | Sodium cocoyl isethionate systems capture scalp-sensitive positioning in pharmacy and specialty retail channels. |
| Subscription Replenishment Launch | Algorithmic personalization models capture recurring revenue among Santiago metropolitan millennials. |
| Pacific Alliance Re-Export Positioning | Valparaíso free trade zone infrastructure enables tariff-reduced access to Andean markets. |
Study Parameters
Direct dialogue with cosmetic formulators, pharmacy category buyers, salon network owners, and Instituto de Salud Pública regulatory officers grounded qualitative insights. Secondary validation drew from MERCOSUR technical regulation databases, Chilean customs trade records, Nielsen retail audit data, and pharmaceutical distribution disclosures. Bottom-up SKU-level modeling and top-down category sizing enabled triangulation across data sources.
Segmentation outputs reflect product type, end user archetype, distribution channel, and formulation technology dimensions across the analysis window. CAGRs derived from historical trajectory fitting adjusted for regulatory event impacts and channel shift elasticity. Forecast inputs incorporated Santiago urban density projections, pharmacy expansion schedules, and indigenous ingredient commercialization timelines.
Inputs from regulatory filing databases and retail audit panels were available through the study window; gaps in real-time salon channel transaction data introduce uncertainty bands around professional segment estimates. Forecasts reflect documented assumptions regarding MERCOSUR harmonization pace and enforcement consistency. Material deviation in Instituto de Salud Pública authorization timelines or Pacific Alliance tariff restructuring warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Clay Market
Hair Care
United States Hair Care Market
Hair Care
Artificial Hair Integration Market
Hair Care
Latin America Hair Care Market
Hair Care
Asia Pacific Hair Styling Products Market
Hair Care
Protein Shampoo Market
Hair Care
Hair Edge Tamer Market
Hair Care
Anti-Pollution Hair Care Market
Hair Care
Hair Spray Market
Hair Care
Russia Salon Hair Care Market
Hair Care
Hair Wigs and Extensions Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Bond Multiplier Market
Hair Care
Global Premium Hair Care Market
Hair Care
Organic Hair Care Market