
 Australia Hair Care Market | 2026-2036
Australia Hair Care Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Hair Care Market Analysis
A widening capability gap in local manufacturing infrastructure is rotating strategic investment toward brands with captive supply chains. Procter & Gamble leverages its integrated production network to secure shelf dominance across Australian supermarket channels. L'Oréal anchors its position through dedicated R&D facilities serving Asia-Pacific formulation requirements. Eleven Australia specializes in salon-exclusive distribution, navigating professional channel control against mass-market incumbents.
Australia hair care encompasses cosmetic and therapeutic preparations formulated with surfactant bases, conditioning quaternaries, active botanical extracts, and pH-balanced systems designed to cleanse, condition, protect, or treat human hair. Shampoos and conditioners constitute the volume core of retail sales, though treatments command disproportionate margin contribution due to higher per-unit pricing and repeat purchase loyalty. The distribution channel structure splits sharply between supermarkets, which drive unit velocity through promotional cycling, and beauty salons, where professional-only lines sustain premium positioning through service bundling. Online retail is expanding fastest among customer segments, particularly for sulfate-free and organic formulations where ingredient literacy drives digital discovery and subscription replenishment.
TGA oversight governs therapeutic claims and active ingredient thresholds, while ACCC enforcement actions on misleading environmental representations are reshaping how brands communicate sustainability credentials. The Australian Competition and Consumer Commission's recent targeting of greenwashing in personal care has forced reformulation documentation and supply chain substantiation. ISO 16128 compliance for natural and organic cosmetic ingredients provides a voluntary benchmark that premium brands increasingly adopt to differentiate against conventional competitors. Stakeholders must monitor evolving state-level cosmetic waste regulations and prepare for potential extended producer responsibility frameworks that would shift disposal accountability upstream to manufacturers.
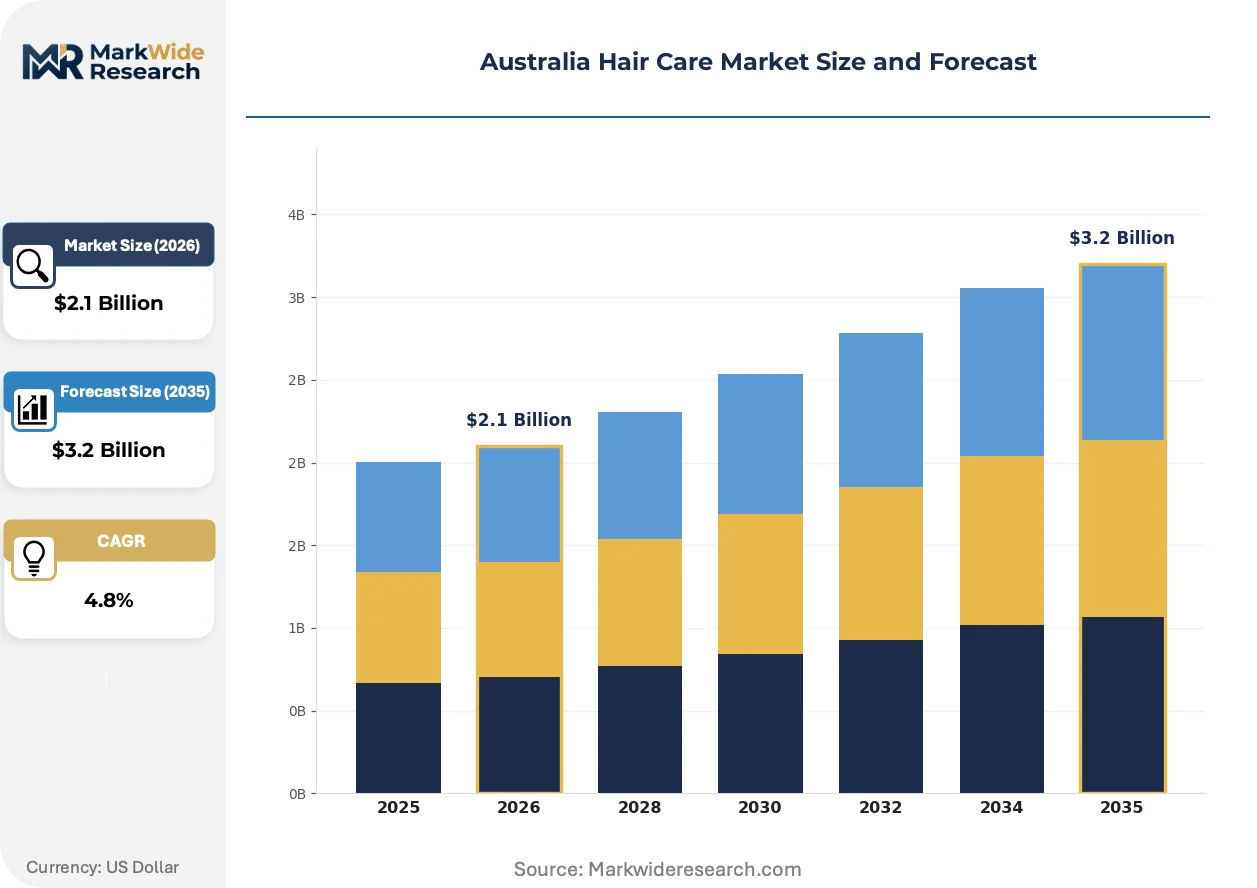
Market Dynamics
ACCC greenwashing enforcement is compressing marketing flexibility and forcing reformulation documentation across Australian hair care brands, while TGA therapeutic claim thresholds simultaneously elevate compliance costs for treatment-positioned products.
Growth Catalysts
- Salon-grade service bundling:Professional styling studios in Sydney and Melbourne are expanding service-integrated product sales, creating captive demand channels that mass retail cannot replicate.
- ISO 16128 adoption:Premium brands are leveraging this voluntary natural and organic benchmark to differentiate formulations against conventional competitors in clean beauty positioning.
- Metropolitan premium clustering:Affluent inner suburbs concentrate disposable income and specialty retail infrastructure, concentrating demand for high-margin treatment products.
Market Restraints
- Captive supply chain scarcity:Local manufacturing infrastructure gaps force dependence on imported active ingredients and packaging materials, exposing margins to currency and freight volatility.
- TGA therapeutic threshold friction:Active ingredient concentration limits for anti-dandruff and hair loss claims require separate registration pathways that extend time-to-market by 12-18 months.
- Sulfate-free substitution complexity:Mild surfactant alternatives struggle to match cleansing efficacy at equivalent cost points, limiting mass-market penetration of clean formulations.
Strategic Opportunities
- Subscription replenishment channels:Direct-to-consumer platforms for sulfate-free and organic lines are capturing repeat purchase loyalty through automated delivery models.
- Extended producer responsibility preparation:Anticipated state-level cosmetic waste frameworks will reward early movers with compliance infrastructure and retailer preferential placement.
- Professional-exclusive distribution:Salon-only lines bypass supermarket promotional cycling, preserving margin through service bundling and stylist recommendation authority.
Industry Challenges
- Formulation chemist scarcity:pH-balanced system design and quaternary conditioning expertise is concentrating among legacy manufacturers, constraining new entrant R&D velocity.
- Supply chain substantiation costs:ACCC enforcement demands documented ingredient provenance and environmental claim verification, requiring capital investment in traceability systems.
- Multi-channel inventory complexity:Brands serving both supermarket promotional cycles and salon steady-state demand face working capital strain from divergent replenishment patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Hair Care Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Hair Oils, Treatments Distribution Channel: Supermarkets, Online Retail, Beauty Salons, Pharmacies Customer Type: Men, Women, Children, Professionals Formulation: Organic, Sulfate-Free, Color-Protect, Moisturizing |
| Companies Covered | Procter & Gamble, Unilever, L'Oréal, Henkel, Kao Corporation, Johnson & Johnson, Revlon, Eleven Australia, Muk Haircare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Hair Care Market Emerging Trajectories
Ingredient literacy and digital discovery are compressing traditional brand loyalty cycles, while regulatory transparency mandates reshape how sustainability credentials are communicated and substantiated across Australian distribution channels.
Biotechnology-derived actives are fragmenting the botanical extract segment that has dominated premium positioning. Peptide complexes and fermented ingredients are gaining traction among Sydney and Melbourne salon channels seeking differentiated treatment outcomes. Established natural-positioned brands face margin compression as these lab-engineered alternatives claim clinical efficacy with shorter supply chains.
TGA ingredient disclosure mandates are tightening label transparency requirements for therapeutic-positioned products. The regulator's expanded oversight of anti-dandruff and hair growth claims is forcing brands to either reformulate below active thresholds or pursue costly registration pathways. Professional-only lines are responding by shifting positioning toward maintenance and aesthetic benefits that avoid therapeutic classification.
Digital-first discovery is displacing in-supermarket impulse purchasing for specialty formulations. Subscription platforms and ingredient-filtered search tools are capturing Australian consumers researching sulfate-free and organic options, particularly among metropolitan millennials. This channel rotation is most visible in Melbourne's inner-north and Sydney's eastern suburbs, where specialty e-commerce penetration exceeds national averages by significant margins.
Australia Hair Care Market Segmentation
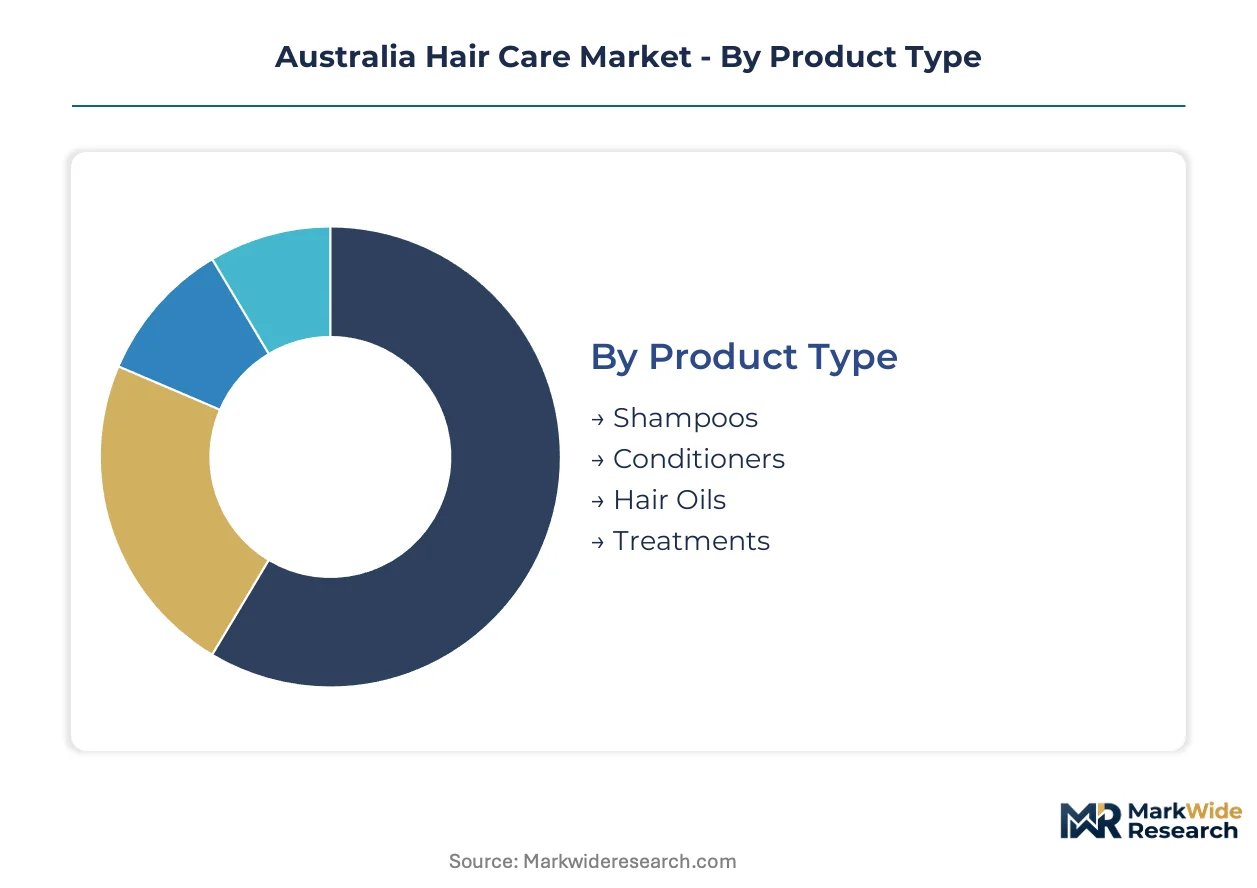
Australian hair care segmentation reflects the tension between TGA therapeutic oversight and ACCC marketing enforcement, with each category demanding distinct compliance pathways. Channel and formulation choices determine margin structure, while customer and product type splits reveal where professional authority versus retail accessibility drives purchase decisions.
Product Type:
TGA thresholds reshape how therapeutic-positioned products separate from cosmetic maintenance formulations, forcing brands into distinct registration or reformulation strategies.
- Shampoos:Surfactant-based cleansing systems dominate unit velocity through supermarket promotional cycling. Sydney and Melbourne mass retail channels concentrate volume for standard formulations, though sulfate-free variants face cost-efficacy trade-offs that limit penetration.
- Conditioners:Quaternary conditioning agents deliver detangling and cuticle smoothing benefits across all price tiers. Salon-exclusive distribution in affluent inner suburbs captures premium positioning through stylist recommendation authority and service bundling.
- Hair Oils:Botanical and silicone-based finishing treatments target frizz control and shine enhancement. Melbourne's inner-north specialty retailers and Sydney's eastern suburbs e-commerce platforms concentrate demand for premium oil formulations.
- Treatments:Intensive repair masks and bond-building systems command disproportionate margin contribution. Anti-dandruff and hair growth variants trigger TGA therapeutic classification, extending time-to-market through registration pathways.
Shampoos handle the majority of throughput; treatments are the fastest mover on share.
Distribution Channel:
Cost tier stratification separates mass-market velocity engines from premium margin preservation systems, with each channel demanding incompatible inventory and promotional rhythms.
- Supermarkets:Coles and Woolworths drive national unit velocity through deep promotional cycling and shelf-space dominance. Procter & Gamble leverages integrated production networks to secure placement for standard shampoo and conditioner lines.
- Online Retail:Subscription platforms and ingredient-filtered search tools capture sulfate-free and organic discovery among metropolitan millennials. Melbourne and Sydney penetration exceeds national averages through specialty e-commerce infrastructure.
- Beauty Salons:Professional-only lines bypass retail promotional pressure through stylist-controlled recommendation and service integration. Eleven Australia anchors this channel with salon-exclusive distribution preserving margin authority.
- Pharmacies:TGA-registered therapeutic treatments and medicated anti-dandruff formulations concentrate in Priceline and Chemist Warehouse networks. Pharmacist consultation drives trust for hair loss and scalp condition positioning.
Supermarkets handle the majority of throughput; online retail is gaining share fastest.
Customer Type:
Application intensity varies sharply across demographic segments, with professional use demanding performance validation that diverges from household maintenance expectations.
- Women:Multi-step routines spanning cleansing, conditioning, treatment, and styling drive category spending concentration. Melbourne and Sydney metropolitan areas concentrate demand for premium treatment products through specialty retail and salon channels.
- Men:Simplified two-step regimens favor all-in-one formulations and grooming-integrated positioning. Barbershop retail partnerships and male-focused subscription platforms expand share in Sydney's inner suburbs.
- Children:Tear-free formulations and gentle surfactant systems dominate this safety-sensitive segment. Pharmacy and supermarket channels concentrate distribution for pediatric-positioned lines.
- Professionals:Stylists and salon operators purchase bulk backbar quantities with performance specifications exceeding consumer-grade alternatives. L'Oréal's Asia-Pacific R&D facilities formulate specifically for this channel's technical requirements.
Women handle the majority of throughput; professionals are expanding most quickly on share.
Formulation:
Margin tier stratification separates certified natural positioning from conventional chemistry, with ISO 16128 compliance emerging as a voluntary differentiation benchmark.
- Organic:Plant-derived surfactants and preservative systems certified to ISO 16128 standards command shelf price premiums. ACCC greenwashing enforcement demands documented supply chain substantiation for environmental claims.
- Sulfate-Free:Mild alternative surfactants replace sodium lauryl sulfate for sensitive scalp and color-treated hair positioning. Cleansing efficacy gaps versus conventional formulations limit mass-market penetration despite metropolitan millennial demand concentration.
- Color-Protect:UV filters and pH-balanced systems extend vibrancy for dyed hair segments. Salon channels bundle these formulations with professional coloring services in Sydney and Melbourne studios.
- Moisturizing:Humectant and emollient-rich systems target dry climate damage and chemical processing recovery. Queensland and Western Australian distribution concentrates this positioning for sun and heat exposure contexts.
Moisturizing handles the majority of throughput; sulfate-free is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
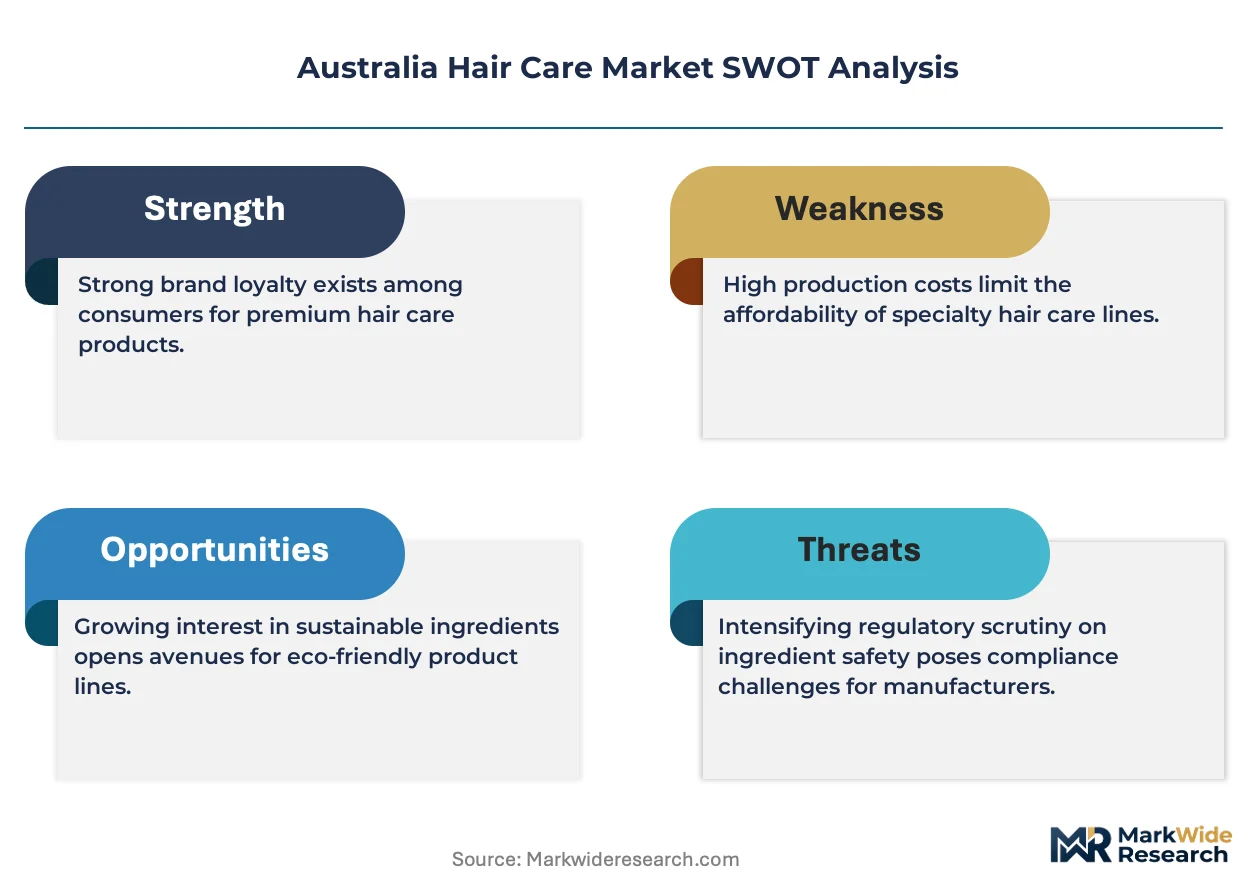
Pricing power concentrates in Sydney and Melbourne metropolitan corridors, where premium salon channels command margin premiums unavailable in regional Queensland or Western Australian retail networks. TGA regulatory harmonization applies nationally, yet enforcement intensity and consumer ingredient literacy vary sharply across state boundaries.
New South Wales
Sydney's eastern suburbs and inner-west concentrate Australia's highest per-capita spending on professional hair treatments. TGA headquarters in Canberra drives regulatory interpretation that NSW-based importers must navigate first. North Sydney and Parramatta host distribution hubs serving salon chains with same-day replenishment capabilities.
Victoria
Melbourne's inner-north specialty retailers capture disproportionate sulfate-free and organic formulation demand. The state's Consumer Affairs Victoria enforces ACCC-aligned greenwashing standards with documented penalties against unsubstantiated natural claims. Fitzroy and Brunswick clusters sustain independent boutiques that bypass supermarket promotional cycles entirely.
Queensland
Humidity-driven moisturizing formulation demand exceeds national averages across Brisbane and Gold Coast corridors. The Queensland Health product safety unit operates parallel cosmetic notification systems that add procedural steps for therapeutic-positioned imports. Sunshine Coast salon density remains below southern-state benchmarks, constraining professional-channel penetration.
Western Australia
Perth's isolation inflates landed costs for imported active ingredients and packaging materials. The state's Department of Health maintains distinct cosmetic incident reporting that shapes distributor liability calculations. Fremantle port throughput constraints periodically disrupt inventory cycles for salon-only lines dependent on Asian manufacturing.
South Australia
Adelaide's smaller metropolitan scale limits specialty retail infrastructure for premium treatment positioning. The SA Health therapeutic goods branch applies TGA guidelines with variable interpretation timelines that extend product registration uncertainty. Local manufacturing presence remains minimal, forcing complete dependence on eastern-state distribution networks.
Australia Hair Care Market Vendor Landscape
Concentration sits with multinational FMCG conglomerates that leverage integrated production networks to dominate supermarket shelf space. Three strategic archetypes define competitive positioning: mass-market velocity players, salon-exclusive premium specialists, and Asia-Pacific R&D-anchored formulation leaders. Dominant competitive moves include backward integration into captive ingredient supply and professional-channel acquisition to bypass retail promotional dependency.
Within the multinational conglomerate tier, Procter & Gamble and L'Oréal exemplify scale-driven market presence through supermarket channel dominance and dedicated Asia-Pacific R&D facilities respectively. Eleven Australia occupies a distinct position as a salon-exclusive specialist navigating professional channel control against mass-market incumbents. These three anchors represent the structural tension between velocity-focused retail strategies and margin-preserving professional distribution.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| L'Oréal |
| Henkel |
| Kao Corporation |
| Johnson & Johnson |
| Revlon |
| Eleven Australia |
| Muk Haircare |
| Others |
Supply Flow & Price Mechanics
Procter & Gamble's integrated production network and L'Oréal's Asia-Pacific R&D facilities anchor scale advantages that compress unit economics for supermarket-channel incumbents while elevating price floors for salon-exclusive entrants lacking captive supply chains. Scale concentration among multinational conglomerates shapes a bifurcated pricing architecture where mass-market velocity players absorb promotional cycling costs that specialty brands cannot shoulder.
Pricing Analysis
The customization-premium spread separates standard supermarket shampoo and conditioner lines from salon-exclusive treatment formulations configured to stylist specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by channel control and certification grade, with ISO 16128 compliance commanding shelf price premiums in Melbourne and Sydney specialty retail. Pricing pressure stems from ACCC greenwashing enforcement demanding documented supply chain substantiation that elevates compliance overhead. Mass-market supermarket buyers exhibit highest price sensitivity, while professional salon operators prioritize performance validation over per-unit cost.
Supply Chain Analysis
China and South Korea anchor active ingredient manufacturing for surfactant bases and conditioning quaternaries, while Australian packaging converters supply pH-balanced system components. The supply chain draws from imported botanical extracts, fermented actives, and peptide complexes for premium treatment positioning. Single-source vulnerability concentrates in Asian manufacturing hubs exposed to Fremantle port throughput constraints and currency volatility. Distribution runs through Coles and Woolworths supermarket networks for velocity, beauty salons for margin preservation, and subscription platforms for sulfate-free and organic replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics dynamics are reshaping competitive positioning as subscription replenishment channels and ingredient-filtered discovery tools fragment traditional brand loyalty cycles. Interoperability between professional salon software and direct-to-consumer platforms creates new ecosystem control points.
For Market Incumbents: Consolidate backward integration into captive surfactant and quaternary supply to defend margin compression from imported input volatility. Expand ISO 16128 certification infrastructure to preempt ACCC enforcement exposure on natural claims. Channel control through salon-exclusive acquisition offsets supermarket promotional dependency.
For New Entrants and Emerging Players: TGA registration fast-tracks for therapeutic-positioned treatments offer white-space entry below multinational incumbent radar. Target sulfate-free subscription replenishment in Melbourne's inner-north and Sydney's eastern suburbs where ingredient literacy drives digital discovery. Professional channel partnership with independent stylists bypasses shelf-space barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-platform brands with automated replenishment and ingredient-filtered search integration. Long-term viability favors acquisition targets with documented supply chain substantiation systems and salon-exclusive distribution contracts. Watch TGA therapeutic threshold adjustments as inflection signal for treatment-category registration cost shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Salon-Exclusive Distribution Expansion | Eleven Australia's channel control preserves margin authority against supermarket promotional cycling. |
| ISO 16128 Certification Investment | Documented natural and organic benchmarks differentiate premium positioning under ACCC scrutiny. |
| Subscription Platform Launch | Automated replenishment captures repeat purchase loyalty for sulfate-free and organic formulations. |
| Backward Integration into Active Ingredients | Captive supply chains mitigate currency and freight volatility from Asian manufacturing dependence. |
| Professional Channel Acquisition | Stylist recommendation authority bypasses retail shelf-space competition and promotional margin erosion. |
Methodological Framework
Cross-validation between primary interviews with salon owners, formulation chemists, and supermarket category buyers anchors the qualitative findings against secondary validation. Stakeholder consultations included professional stylists, TGA regulatory consultants, ACCC enforcement specialists, and e-commerce platform operators. Secondary sources comprised TGA therapeutic goods registers, ACCC enforcement action databases, Nielsen retail audit data, and customs import records for surfactant and conditioning agent categories. Bottom-up segment sizing triangulated against top-down market value estimates.
Sensitivity analysis around TGA registration pathway timelines and ACCC enforcement intensity brackets the forecast range across the analysis window. Segmentation dimensions modeled include product type, distribution channel, customer application intensity, and formulation certification tier. CAGRs derived from trend extrapolation of salon-grade service bundling, subscription platform penetration, and sulfate-free substitution rates calibrated against historical supermarket promotional cycling patterns.
Decision-makers should treat outputs as directional under sustained TGA therapeutic threshold stability and ACCC greenwashing enforcement continuity; material deviation would warrant model refresh. Forecasts reflect assumptions on metropolitan premium clustering persistence and professional channel margin preservation. Recalibration cycles align with material shifts in regulatory enforcement intensity and supply chain substantiation cost trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Texturizer Products Market
Hair Care
Global Professional Hair Care Market
Hair Care
Hair Tonic Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Hair Mask Market
Hair Care
Hair Edge Tamer Market
Hair Care
Argentina Hair Care Market
Hair Care
United States Hair Care Market
Hair Care
Hair Care Appliances Market
Hair Care
Hair Extension Market
Hair Care
Rice Water Shampoo Market
Hair Care
Brazil Hair Care Market
Hair Care
Middle East and Africa Hair Care Market
Hair Care
Japan Hair Care Market
Hair Care
Qatar Hair Care Market
Hair Care
South Korea Hair Care Market