
 Hair Clay Market | 2026-2036
Hair Clay Market Size, Share, and Industry Trends Forecast 2026-2036
Hair Clay Market Analytics
Premium matte-finish specifications is redrawing competitive boundaries in hair clay. Hanz de Fuko leverages its specialty formulations to command shelf positioning in professional channels. Baxter of California anchors its presence through barbershop-exclusive distribution networks. Kevin Murphy differentiates via salon-certified ingredient transparency protocols.
Hair clay denotes a water-based or oil-based styling compound incorporating bentonite or kaolin with wax binders, engineered to deliver reworkable hold with low shine. The formulation achieves pliable texture control for commercial grooming applications. Matte clay occupies the dominant volume position among product type segments, while natural ingredient features capture expanding margin pools as clean-label preferences intensify. Jar packaging sustains the largest share by format, though tube configurations gain traction in travel-retail channels.
FDA cosmetic labeling requirements govern ingredient disclosure for products entering United States distribution, while REACH frameworks in Europe restrict specific preservatives and fragrance allergens. These regulatory architectures elevate compliance costs but simultaneously filter lower-tier competitors from premium positioning. Stakeholders must monitor evolving preservative bans and clean-certification standards to sustain formulation relevance.
Market Dynamics
Matte-finish protocols in professional grooming are compressing demand for high-shine alternatives, forcing reformulation investments across water-based and oil-based compound portfolios.
Growth Catalysts
- Barbershop channel expansion:Professional grooming establishments in the United States are standardizing clay-based styling across service menus, creating institutional demand pull.
- REACH compliance cycles:European Union preservative threshold tightening is accelerating clean-label innovation, filtering lower-tier competitors from premium positioning.
- Bentonite sourcing diversification:Kaolin and alternative mineral deposits in Wyoming and Georgia are reducing input concentration risk for domestic manufacturers.
Market Restraints
- Petroleum-derived wax volatility:Crude-linked binder costs expose margins to energy market fluctuations without long-term hedging instruments.
- Preservative regulatory fragmentation:Divergent FDA cosmetic labeling and ECHA REACH frameworks create dual-compliance burdens for cross-border distribution.
- Pomade substitution elasticity:Traditional oil-based styling compounds retain loyalty among demographic segments resistant to texture experimentation.
Strategic Opportunities
- Travel-retail tube formats:TSA-compliant packaging configurations are capturing margin pools in airport duty-free channels previously dominated by jar formats.
- Salon-certified transparency protocols:Ingredient disclosure standards exceeding baseline FDA requirements are enabling premium positioning in metropolitan chains.
- Natural feature expansion:Clean-label preference intensification across California and New York is opening shelf space for preservative-free formulations.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise spanning mineral rheology and clean-preservative systems commands compensation premiums that compress R&D budgets.
- Reformulation capex cycles:REACH-driven preservative bans require pilot-scale validation before commercial rollout, extending payback periods.
- Cross-border labeling complexity:Dual-language FDA and state-level disclosure requirements create packaging SKU proliferation that strains inventory systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair Clay Market |
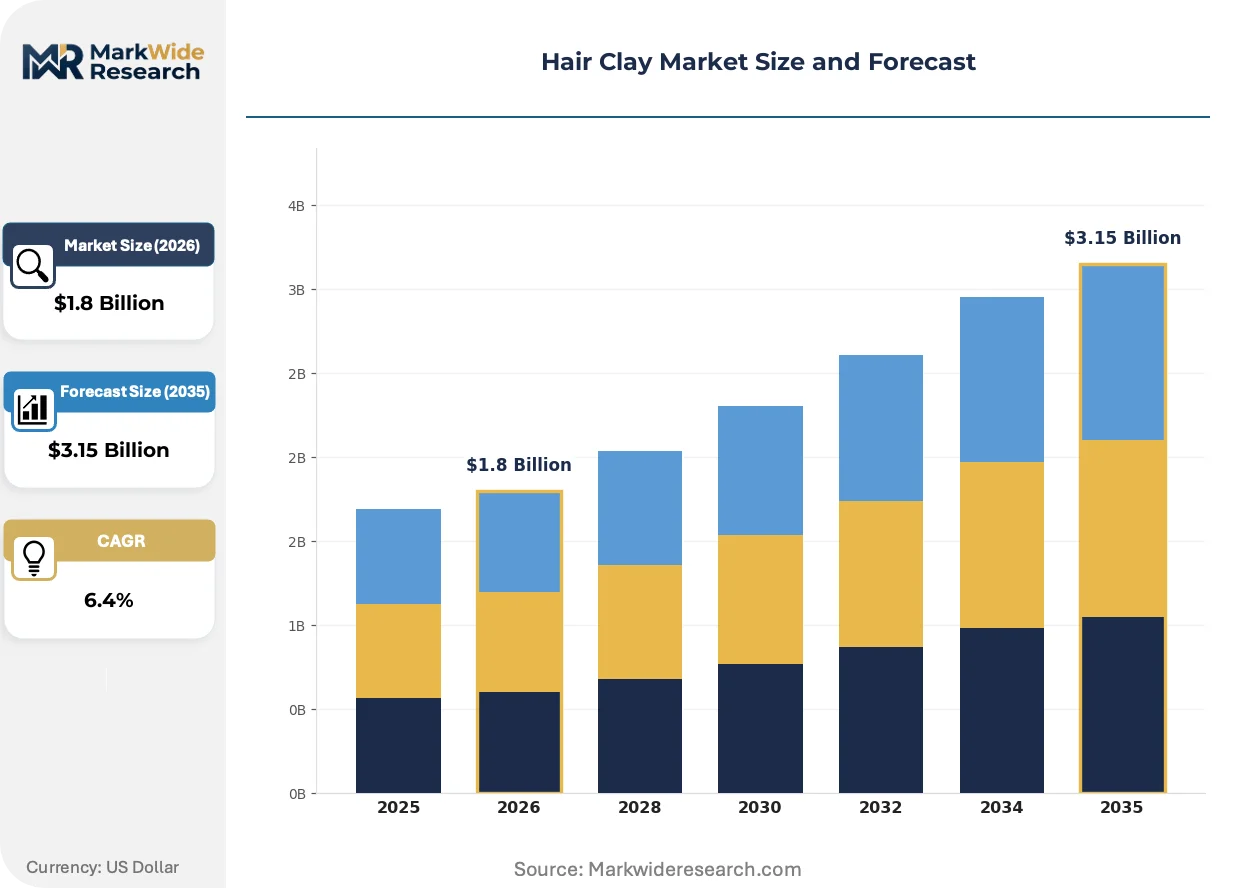
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matte Clay, Glossy Clay, Texturizing Clay, Volumizing Clay End User: Salons, Barbershops, Individual Consumers, Professional Stylists Feature: Natural Ingredients, Long-Lasting Hold, Easy Wash, Non-Greasy Finish Packaging Type: Tubes, Jars, Sachets, Pump Bottles |
| Companies Covered | Hanz de Fuko, Baxter of California, American Crew, Layrite, Recipe for Men, Kevin Murphy, House 99, BYRD, Lock Stock & Barrel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair Clay Market Evolving Landscape
Formulation chemistry is pivoting toward reworkable hold systems that sacrifice maximum fixation for pliability, reflecting professional stylist preference evolution over consumer convenience alone.
Water-dispersible bentonite complexes are displacing traditional petroleum-wax binders in salon-grade compounds. Barbershop chains in Texas and California are adopting these formulations at accelerated procurement cycles. The shift is displacing high-shine pomade inventories from back-bar positioning and compressing shelf space for oil-based alternatives.
REACH Annex XVII restrictions on isothiazolinone preservatives are forcing preservative system redesigns across European-bound production lines. Manufacturers serving EU distribution are migrating toward phenoxyethanol and organic acid alternatives ahead of enforcement windows. Salon-exclusive lines face compressed certification timelines compared to mass-market portfolios.
Certification-driven procurement is altering distributor relationships in metropolitan markets. Stylists in Chicago and Miami are prioritizing salon-certified transparency documentation over traditional brand loyalty. The pattern concentrates in independent barbershops with direct supplier relationships, bypassing conventional wholesale intermediaries.
Hair Clay Market Segmentation
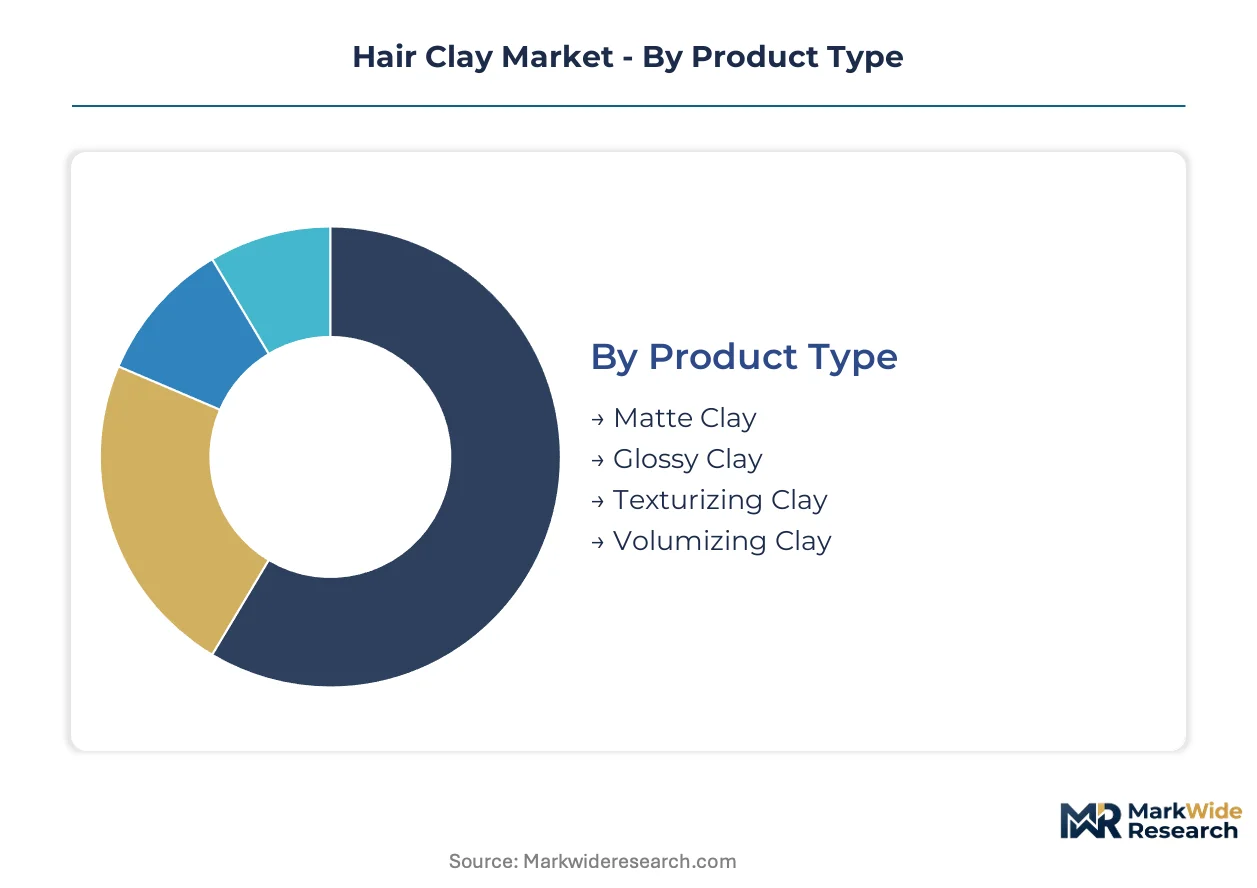
Hair clay segmentation reveals how formulation chemistry, channel positioning, and consumer preference layers create distinct margin architectures. Each dimension carries implications for R&D allocation, packaging investment, and distribution partnerships.
Product Type:
Margin pools concentrate in matte-finish formulations as professional grooming protocols abandon high-shine alternatives.
- Matte Clay:Bentonite-kaolin compounds with petroleum or water-based binders deliver reworkable hold with near-zero reflectance. Barbershop chains in Texas and California standardize this specification across back-bar inventories, displacing pomade alternatives from premium shelf positioning.
- Texturizing Clay:Lightweight mineral complexes with micro-particle distribution enable separation and definition for layered cuts. Independent stylists in metropolitan Miami and Chicago prioritize procurement of salon-certified transparency documentation for this segment over traditional brand loyalty.
- Glossy Clay:Oil-dominant formulations with higher wax ratios retain niche demand among demographic segments resistant to matte-finish experimentation.
- Volumizing Clay:Expanded mineral matrices with lower density structure lift fine hair types through root-level application.
Matte Clay holds installed capacity. Texturizing Clay is rotating up the share rankings.
End User:
Channel concentration determines pricing power, with professional establishments capturing bulk procurement discounts unavailable to retail purchasers.
- Barbershops:Institutional procurement cycles standardize clay-based styling across service menus, creating demand pull with volume commitments. Metropolitan chains negotiate direct supplier relationships that bypass wholesale intermediaries and compress distributor margins.
- Salons:Certification-driven procurement prioritizes ingredient transparency exceeding baseline FDA requirements, enabling premium positioning in high-rent districts.
- Professional Stylists:Independent operators with mobile or booth-rental models drive sachet and travel-format demand for kit portability.
- Individual Consumers:Mass-market purchasers through e-commerce and big-box retail exhibit higher price elasticity and brand-switching behavior.
Barbershops anchor volume throughput. Salons command the steepest expansion trajectory in per-unit margin contribution.
Feature:
Clean-label preference intensification across coastal metropolitan markets is opening shelf space for preservative-free positioning at 40-60% price premiums.
- Natural Ingredients:Formulations excluding synthetic preservatives and petroleum-derived binders capture expanding margin pools in California and New York. REACH Annex XVII restrictions on isothiazolinone preservatives accelerate migration toward phenoxyethanol and organic acid alternatives for EU-bound production.
- Non-Greasy Finish:Water-dispersible bentonite complexes displace traditional petroleum-wax binders, aligning with stylist preference evolution toward pliability over maximum fixation.
- Long-Lasting Hold:Higher wax concentration and film-forming polymers extend style duration for humid climates and active lifestyles.
- Easy Wash:Water-soluble binder systems reduce residue accumulation and appeal to daily users with sensitive scalp conditions.
Natural Ingredients holds installed capacity. Non-Greasy Finish is rotating up the share rankings.
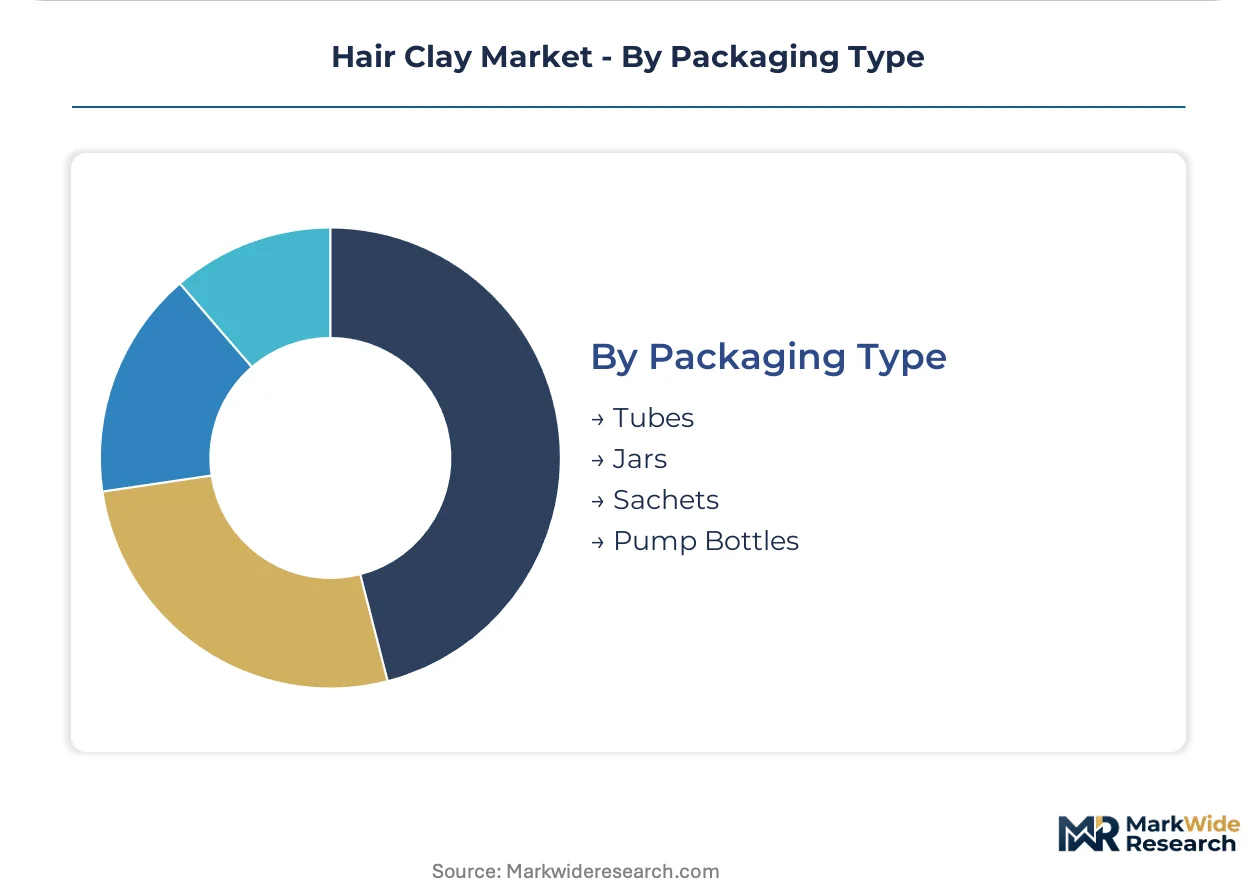
Packaging Type:
Format selection reflects channel destination and usage occasion, with travel-retail configurations capturing margin pools previously dominated by traditional containers.
- Jars:Wide-mouth containers sustain the largest format share through professional back-bar placement and home vanity storage. Bulk purchasing by barbershop chains favors 4-ounce and 8-ounce jar configurations with extended use cycles.
- Tubes:TSA-compliant configurations under 3.4 fluid ounces expand presence in airport duty-free channels and gym bag portability segments. Squeeze dispensing reduces product waste compared to finger-dip jar access.
- Sachets:Single-use pouches serve trial sampling programs and hotel amenity partnerships with minimal per-unit cost.
- Pump Bottles:Airless dispensing systems preserve formulation integrity for water-based compounds with higher preservative sensitivity.
Jars hold installed capacity. Tubes are gaining share fastest in travel-retail and subscription box channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation laboratories and mineral processing facilities cluster in the United States, Germany, and Japan, with secondary capacity emerging in South Korea and Australia. Domestic bentonite deposits in Wyoming and Georgia reduce input costs for North American manufacturers. REACH-driven reformulation cycles in Europe are accelerating supplier qualification timelines.
United States
Metropolitan salon chains in Texas and California are standardizing clay-based styling across service menus, creating institutional procurement pull. FDA cosmetic labeling requirements govern ingredient disclosure for products entering interstate distribution. The Pacific Northwest hosts specialty mineral processors supplying bentonite-kaolin complexes to professional grooming compound manufacturers.
Germany
Barbershop chains in Berlin and Munich are adopting water-dispersible bentonite formulations at compressed procurement cycles. ECHA REACH Annex XVII restrictions on isothiazolinone preservatives are forcing preservative system redesigns across production lines serving EU distribution. The Rhine-Ruhr industrial corridor concentrates cosmetic chemist talent pools for clean-preservative formulation development.
Japan
Professional stylists in Tokyo and Osaka are prioritizing reworkable hold systems that sacrifice maximum fixation for pliability. METI guidelines on chemical substance management influence domestic formulation standards for grooming compounds. The Kansai region hosts precision mineral processing facilities supplying micro-particle distribution technologies for texturizing clay segments.
South Korea
Metropolitan grooming establishments in Seoul are integrating matte-finish protocols into standard service offerings. MFDS cosmetic safety regulations govern preservative thresholds for products entering domestic distribution. The Seoul Capital Area concentrates contract manufacturing capacity for water-based styling compound exports.
Australia
Independent barbershops in Sydney and Melbourne are bypassing conventional wholesale intermediaries for direct supplier relationships. TGA cosmetic ingredient disclosure requirements align with salon-certified transparency documentation demands. The New South Wales industrial corridor hosts natural ingredient formulation specialists serving preservative-free product segments.
Hair Clay Market Competitive Landscape
Concentration sits with specialty grooming houses and salon-exclusive distributors rather than mass-market conglomerates. The vendor base spans three tiers: premium formulation specialists commanding professional channel positioning, mid-tier barbershop distributors with exclusive territory agreements, and emerging clean-label entrants capturing coastal metropolitan shelf space. Dominant competitive moves include strategic partnerships with metropolitan salon chains and portfolio diversification into travel-retail tube formats.
Within the premium formulation tier, Hanz de Fuko and Kevin Murphy exemplify archetypes built on specialty mineral complexes and salon-certified transparency protocols respectively. Baxter of California occupies a position anchored through barbershop-exclusive distribution networks. These three entities represent distinct competitive vectors: formulation chemistry leadership, ingredient disclosure standards, and professional channel control.
| Leading Market Players |
|---|
| Hanz de Fuko |
| Baxter of California |
| American Crew |
| Layrite |
| Recipe for Men |
| Kevin Murphy |
| House 99 |
| BYRD |
| Lock Stock & Barrel |
| Others |
Value Network & Pricing Analysis
Domestic bentonite processing scale in Wyoming and Georgia establishes minimum efficient scale thresholds that filter sub-scale competitors from premium formulation tiers while anchoring price floors for salon-grade compounds. REACH-driven reformulation cycles and FDA cosmetic labeling requirements compound compliance burdens that concentrate pricing power among integrated manufacturers with captive mineral supply.
Pricing Analysis
FDA cosmetic labeling and ECHA REACH frameworks dictate the pricing tier structure across professional and retail channels. Three-tier pricing structure across premium salon-certified, standard barbershop-grade, and economy mass-market levels separates certification investment levels. Price differentiation rests on ingredient transparency documentation and preservative system complexity. Pricing pressure stems from petroleum-derived wax volatility without long-term hedging coverage. Individual consumers through e-commerce exhibit highest price sensitivity; metropolitan salon chains with direct supplier relationships show lowest elasticity due to institutional procurement commitments.
Supply Chain Analysis
Wyoming bentonite deposits and Georgia kaolin mines anchor raw material concentration for North American formulation. Mineral extraction draws from domestic deposits, petroleum wax binders feed from Gulf Coast refineries, and phenoxyethanol preservative alternatives source from specialty chemical producers in Germany and Japan. Single-source vulnerability concentrates in Wyoming bentonite processing for premium matte-finish grades. Distribution runs through barbershop-exclusive networks and salon-direct relationships bypassing conventional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
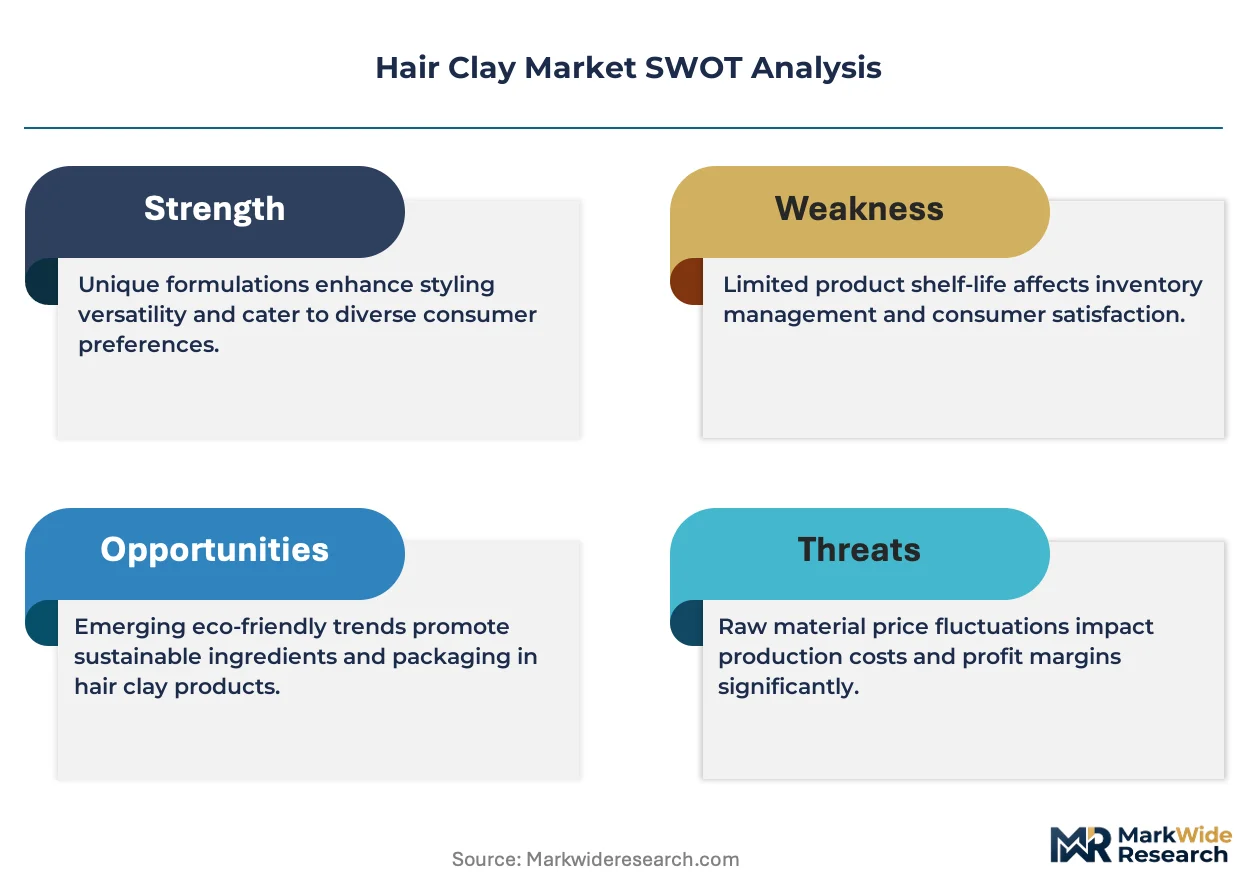
Regulatory entrenchment creates defendable moats in hair clay as REACH preservative bans and FDA disclosure requirements elevate compliance costs beyond emerging entrant capital access. Network effects concentrate in metropolitan salon chain procurement standardization that locks in formulation specifications across service menus.
For Market Incumbents: Fortify barbershop-exclusive distribution networks against clean-label entrants by accelerating salon-certified transparency documentation beyond baseline FDA requirements. Invest pilot-scale validation capacity for REACH-driven preservative system redesigns to compress certification timelines. Threat: Independent stylists in Miami and Chicago are bypassing wholesale intermediaries for direct supplier relationships. Lever: Backward integration into Wyoming bentonite processing secures input cost control. For New Entrants and Emerging Players: Travel-retail tube format under-service by established jar-dominant portfolios creates white-space opportunity in TSA-compliant airport duty-free channels. Target preservative-free natural ingredient positioning in California and New York where clean-label preference intensification commands 40-60% price premiums. Go-to-market: Subscription box partnerships with grooming kit aggregators bypass traditional retail slotting fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation specialists with mineral rheology expertise and clean-preservative system capabilities. Long-term viability frames around REACH Annex XVII enforcement windows and FDA disclosure requirement evolution. Acquisition target archetype: Regional barbershop distributors with exclusive territory agreements in Texas and California. Signal to watch: Metropolitan salon chain standardization velocity as indicator of institutional demand pull concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Salon-Certified Transparency Investment | Exceeding FDA baseline requirements enables premium positioning in high-rent metropolitan districts. |
| Preservative System Redesign | REACH Annex XVII compliance migration toward phenoxyethanol alternatives filters sub-scale competitors. |
| Travel-Retail Tube Format Launch | TSA-compliant packaging captures margin pools in airport duty-free channels previously jar-dominated. |
| Direct Supplier Relationship Development | Bypassing wholesale intermediaries compresses distributor margins while securing institutional volume commitments. |
| Domestic Bentonite Integration | Wyoming and Georgia mineral deposit control reduces input concentration risk for matte-finish formulations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with professional stylists, barbershop procurement managers, salon chain operations directors, cosmetic chemists, and specialty mineral processors. Secondary validation drew from FDA cosmetic labeling databases, ECHA REACH Annex XVII substance restrictions, customs trade records for bentonite and kaolin imports, and SEC filings from publicly traded personal care conglomerates. Bottom-up volume estimates from channel-specific procurement patterns were triangulated against top-down market sizing from mineral processing capacity and formulation laboratory throughput.
Across the analysis window, the forecasting framework modeled product type segmentation by finish specification, end-user channel concentration, feature-driven clean-label positioning, and packaging format adoption curves. CAGRs were derived from mineral input demand trajectories, professional establishment expansion rates, and regulatory-driven reformulation cycle timing. Industry-specific inputs included barbershop back-bar inventory turnover data and salon-certified transparency documentation adoption velocity in metropolitan markets.
Forecasts assume regulatory continuity in FDA cosmetic labeling and ECHA REACH frameworks; material policy shifts in preservative thresholds or ingredient disclosure requirements would require re-modeling. Practitioner judgment on stylist preference evolution toward reworkable hold systems introduces uncertainty. Practitioners should keep alternative scenarios live as REACH enforcement windows and clean-certification standard evolution unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hair Care
Hair Wigs and Extensions Market
Hair Care
Plant-Based Hair Dye Market
Hair Care
Global Professional Hair Care Market
Hair Care
Sweden Hair Care Market
Hair Care
South Africa Cosmetics and Personal Care Products Market
Hair Care
Female Hair Piece, Wig, and Extension Market
Hair Care
Qatar Hair Care Market
Hair Care
Global Hair Color Market
Hair Care
Hair Care Appliances Market
Hair Care
Hair Relaxer Market
Hair Care
China Hair Care Products Market
Hair Care
Italy Hair Care Market
Hair Care
Men's Hairspray Market
Hair Care
Germany Hair Care Market
Hair Care
Mexico Hair Care Market
Hair Care
Hair Care Products Market