
 Ballistic Floatation Vest Market | 2026-2036
Ballistic Floatation Vest Market Size, Share, and Industry Trends Forecast 2026-2036
Ballistic Floatation Vest Market Analysis
Software-defined buoyancy calibration is restructuring how manufacturers package value around ballistic floatation vests. Point Blank Enterprises leverages its domestic manufacturing footprint to anchor Navy and Coast Guard contracts. Rheinmetall AG competes through European defense channel control and NATO-aligned certification depth. Honeywell International sustains materials science leadership in aramid and polyethylene fiber supply for integrated vest systems.
A ballistic floatation vest combines projectile-resistant paneling with closed-cell flotation foam to deliver simultaneous protection against ballistic threats and drowning immersion, typically rated for buoyancy of 35–50 pounds and NIJ Level IIIA–IV ballistic resistance depending on configuration. The primary purpose is to sustain operator survivability during maritime interdiction, overboard recovery, or amphibious operations where conventional body armor would sink the wearer. Tactical Vests dominate procurement volume among military end users due to modular load-bearing integration and plate-carrier compatibility. Kevlar retains share in legacy programs but Polyethylene is displacing it in new designs where weight reduction drives mobility outcomes. Rescue Operations applications show the fastest structural expansion as civilian emergency services adopt dual-use equipment previously restricted to defense budgets.
The U.S. Coast Guard sets flotation performance mandates through 46 CFR standards, while the EU's CE marking and Personal Protective Equipment Regulation impose conformity requirements on vests sold across member states. India's BIS certification and DGFT import controls shape market access for foreign suppliers bidding on Ministry of Defence tenders. Stakeholders must monitor how divergent national testing protocols for combined ballistic and flotation performance create compliance fragmentation that favors regional certification specialists over global generalists.
Market Dynamics
Software-defined buoyancy calibration is restructuring value capture in ballistic floatation vest manufacturing, forcing suppliers to embed programmable foam density controls that adjust flotation profiles without hardware swaps.
Growth Catalysts
- Maritime Interdiction Modernization:Southeast Asian naval forces are expanding dual-function protective equipment procurement to address piracy and territorial enforcement missions in contested waters.
- NIJ Standard Updates:The National Institute of Justice's revised ballistic resistance protocols for maritime environments are mandating integrated flotation-ballistic testing that validates combined performance claims.
- Closed-Cell Foam Chemistry:Advances in cross-linked polyethylene foam manufacturing are reducing vest dry weights while maintaining 35-pound minimum buoyancy ratings under saltwater saturation conditions.
Market Restraints
- Aramid Fiber Supply Concentration:Dupont and Teijin control over seventy percent of para-aramid global supply, creating input cost volatility when defense procurement cycles synchronize.
- Dual Certification Burden:Manufacturers must separately validate ballistic performance through NIJ protocols and flotation compliance through 46 CFR, doubling timeline-to-revenue for new designs.
- Conventional Body Armor Substitution:Land-focused military units continue procuring standalone plate carriers at lower unit costs, diverting budget from maritime-specific configurations.
Strategic Opportunities
- Civilian Emergency Services Expansion:Swift-water rescue teams and coastal fire departments are adopting military-derived dual-use equipment previously restricted to defense procurement channels.
- India Coastal Defense Programs:The Indian Navy's amphibious modernization and Ministry of Home Affairs marine police expansion are creating tender opportunities for foreign suppliers meeting BIS certification requirements.
- Modular Load-Bearing Integration:Convergence between MOLLE-compatible tactical platforms and inflatable flotation collars enables single-vest configurations adaptable to mission threat levels.
Industry Challenges
- Specialized Composite Fabrication Skills:The intersection of ballistic panel lamination and marine-grade sealing requires technicians trained in both armor manufacturing and nautical equipment production, a scarce hybrid competency.
- Legacy Inventory Recertification:The U.S. Coast Guard's updated flotation performance standards are forcing manufacturers to retest existing designs or write down non-compliant stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballistic Floatation Vest Market |
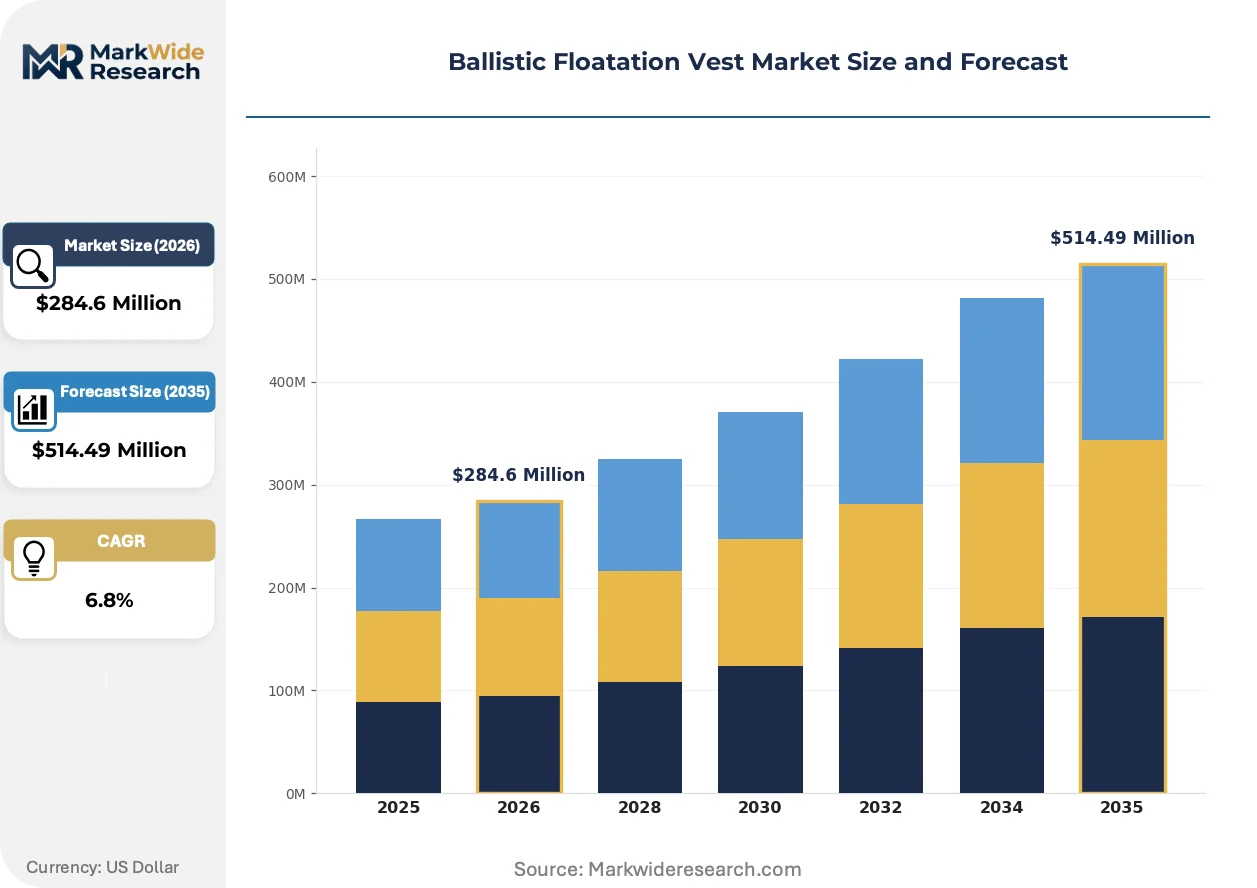
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coastal Vests, Tactical Vests, Work Vests, Recreational Vests Material: Kevlar, Nylon, Polyethylene, Neoprene Application: Military, Law Enforcement, Rescue Operations, Personal Safety End User: Maritime Agencies, Security Firms, Emergency Services, Civilian Users |
| Companies Covered | BAE Systems, Rheinmetall AG, Point Blank Enterprises, Survitec Group, MKU Limited, Honeywell International, Seyntex N.V., Morgan Advanced Materials, Craig International Ballistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballistic Floatation Vest Market Emerging Trajectories
Active materials science and regulatory harmonization pressures are compressing product development cycles while expanding the addressable user base beyond traditional military maritime units.
Polyethylene fiber reinforcement is decentralizing the ballistic panel supply base by enabling smaller composite shops to achieve NIJ Level IIIA ratings without aramid licensing dependencies. Regional manufacturers in Eastern Europe and Southeast Asia are adopting these alternative fibers to bypass Teijin and Dupont supply queues. The resulting supply fragmentation is compressing lead times for mid-tier defense contractors while eroding the procurement advantages of vertically integrated prime suppliers.
REACH chemical restrictions and the EU's updated Personal Protective Equipment Regulation are mandating substitution of legacy chloroprene flotation foams with halogen-free alternatives. Manufacturers serving European defense and coast guard markets must reformulate buoyancy layers to maintain CE marking compliance. The regulatory pressure is accelerating R&D investment in thermoplastic elastomer foams that satisfy both ballistic backface deformation limits and new chemical safety thresholds.
Direct-to-unit procurement through defense e-commerce platforms is displacing traditional prime contractor intermediaries for replacement vest orders below fleet-wide replacement thresholds. Naval special operations units and marine interdiction teams are leveraging simplified acquisition channels to source mission-specific configurations outside standard program office timelines. This purchasing pattern shift is most visible in U.S. and Australian special forces communities where operational tempo demands rapid equipment refresh cycles.
Ballistic Floatation Vest Market Segmentation
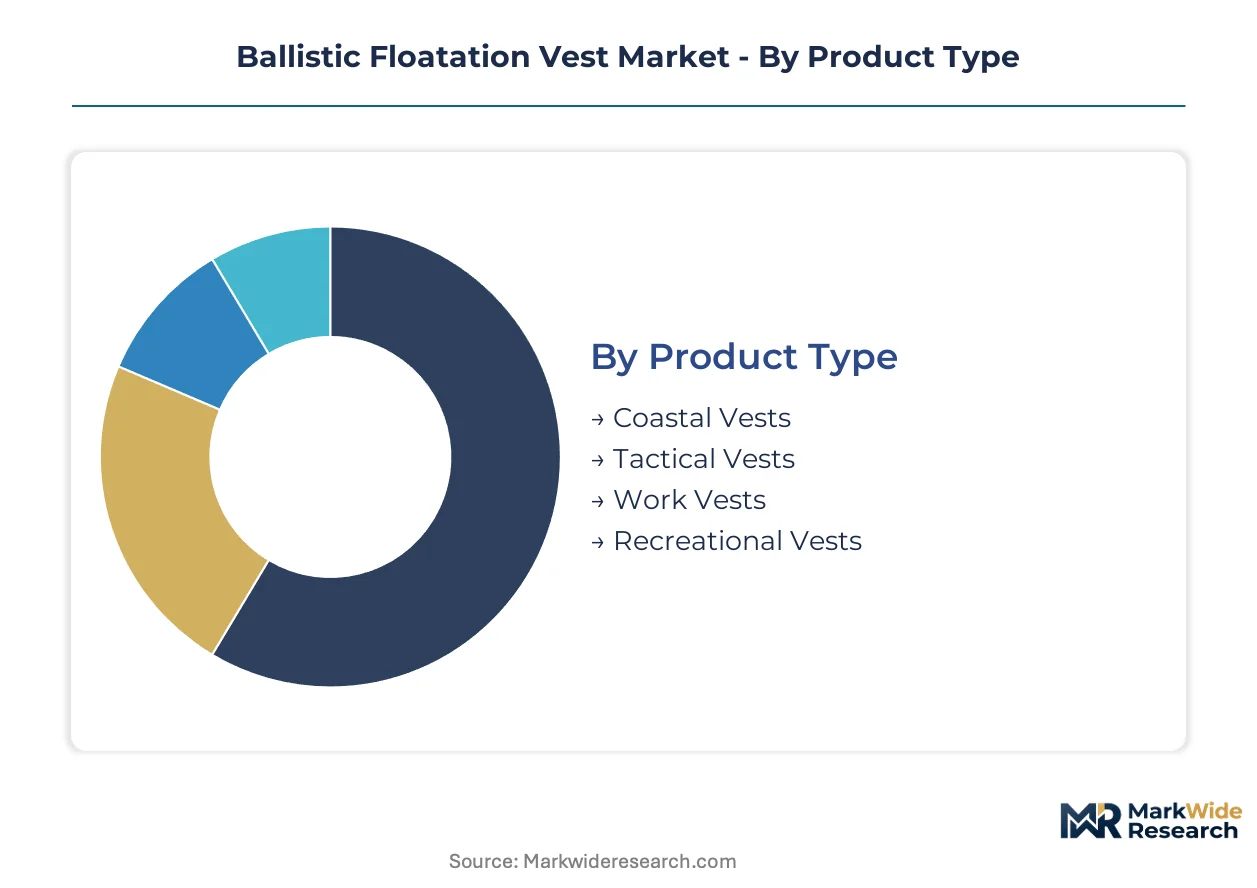
Ballistic floatation vest procurement fragments across four distinct category axes, each imposing unique certification burdens that reshape supplier economics. Material selection and application context determine whether manufacturers pursue NIJ ballistic validation, 46 CFR flotation compliance, or both.
Product Type:
Certification requirements diverge sharply across vest configurations, with tactical platforms demanding dual NIJ-Coast Guard validation while recreational variants face lighter recreational boating standards.
- Tactical Vests:Modular plate-carrier architectures integrate MOLLE webbing with closed-cell flotation collars rated for 35-pound minimum buoyancy. Maritime interdiction teams in the Philippines and Vietnam are concentrating procurement here as territorial enforcement missions intensify.
- Coastal Vests:Fixed-panel designs prioritize saltwater corrosion resistance over modularity, serving harbor patrol and customs enforcement with streamlined 46 CFR certification paths that bypass ballistic backface deformation testing.
- Work Vests:Commercial fishing and offshore energy applications favor economy-tier polyethylene reinforcement with single-function flotation ratings.
- Recreational Vests:Personal watercraft and yachting markets drive volume through Coast Guard Type III compliance without ballistic layering.
Tactical Vests sits at the top of the volume ranking, with Coastal Vests climbing the fastest as Southeast Asian naval modernization accelerates.
Material:
Raw material selection dictates upstream supply relationships and chemical regulatory exposure, particularly for European markets facing REACH foam restrictions.
- Polyethylene:Ultra-high molecular weight fibers enable Level IIIA protection at 30% weight reduction versus aramid alternatives. Indian Ministry of Defence tenders increasingly specify polyethylene for amphibious unit equipment as domestic composite fabrication capacity expands.
- Kevlar:Para-aramid retains installed base dominance in U.S. Navy legacy programs requiring proven saltwater degradation resistance over decade-long service lives.
- Nylon:Ballistic nylon serves cost-sensitive law enforcement contracts with Level II ratings and simplified supply chains.
- Neoprene:Chloroprene-based flotation layers face phase-out pressure under EU halogen-free mandates, accelerating thermoplastic elastomer substitution.
Kevlar commands the largest existing inventory position, though Polyethylene is gaining share fastest as weight-driven mobility outcomes reshape procurement criteria.
Application:
Application context determines whether procurement flows through defense program offices, municipal emergency services budgets, or commercial distribution channels.
- Military:Integrated ballistic-flotation systems for amphibious assault and maritime special operations require concurrent NIJ Level IIIA-IV and 46 CFR Subpart 160.064 validation, extending development timelines to 18-24 months.
- Rescue Operations:Swift-water teams and helicopter rescue swimmers are adopting military-derived dual-use configurations previously restricted to defense procurement, creating new commercial demand outside traditional prime contractor relationships.
- Law Enforcement:Marine police and harbor security units prioritize coastal patrol variants with intermediate threat protection and simplified logistics.
- Personal Safety:Private security contractors and high-net-worth individuals drive niche demand for concealable flotation-ballistic hybrids.
Military procurement maintains volume leadership, with Rescue Operations expanding most quickly as civilian emergency services budgets absorb defense-sector equipment innovations.
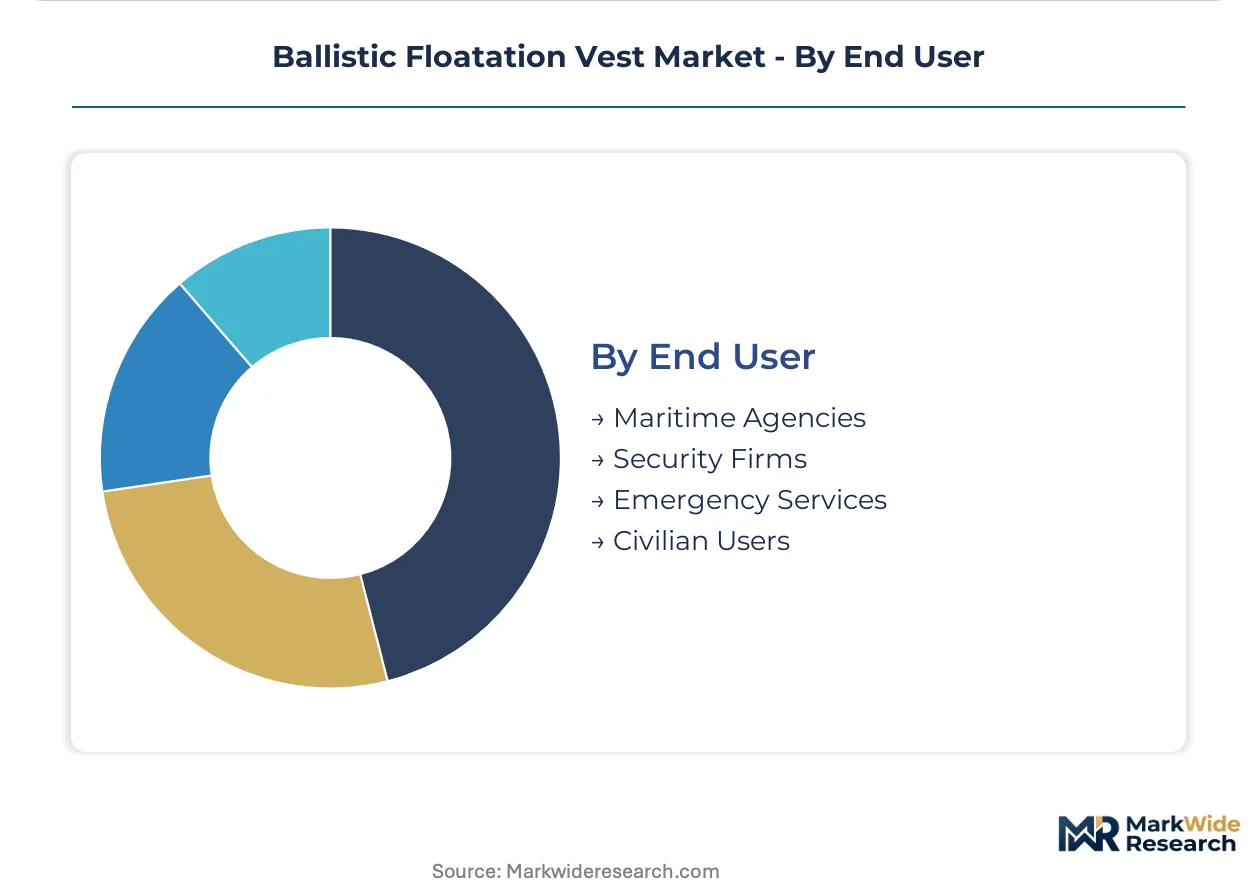
End User:
End-user category shapes contract structure, with maritime agencies favoring multi-year fleet replacements while security firms pursue spot procurement through simplified acquisition channels.
- Maritime Agencies:Coast guard and naval organizations mandate comprehensive dual-certification portfolios, with U.S. 46 CFR and Indian BIS standards creating divergent compliance roadmaps for global suppliers.
- Emergency Services:Fire departments and swift-water rescue teams prioritize rapid donning and modular flotation activation over ballistic protection, opening procurement to recreational-tier manufacturers with defense partnerships.
- Security Firms:Private maritime security contractors seek NIJ Level IIIA protection with discretionary flotation for vessel boarding operations.
- Civilian Users:Yacht owners and commercial fishermen drive replacement demand through retail and e-commerce channels with minimal certification overhead.
Maritime Agencies anchor procurement volume, with Emergency Services showing the steepest expansion trajectory as dual-use equipment crosses from defense to civilian budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as suppliers migrate production toward jurisdictions with streamlined dual-certification pathways for combined ballistic and flotation performance validation.
United States
Maritime interdiction teams and Coast Guard units drive procurement volume through 46 CFR flotation mandates and NIJ ballistic protocols. The U.S. Coast Guard's updated Subpart 160.064 standards are forcing recertification of legacy inventory. Domestic manufacturing clusters in Florida and Virginia anchor Navy and Coast Guard contract fulfillment.
Germany
NATO-aligned defense channels and CE marking requirements under the Personal Protective Equipment Regulation shape supplier economics. Rheinmetall AG leverages European certification depth to capture Bundeswehr amphibious modernization tenders. Industrial concentration in North Rhine-Westphalia supports composite fabrication for integrated vest systems.
India
Coastal defense modernization and marine police expansion under Ministry of Home Affairs programs concentrate demand. BIS certification and DGFT import controls filter market access for foreign bidders. Defense production corridors in Tamil Nadu and Maharashtra are scaling domestic polyethylene fiber lamination capacity.
Vietnam
Naval territorial enforcement missions in contested waters accelerate dual-function equipment procurement. The country lacks indigenous ballistic certification infrastructure, creating dependency on imported NIJ-validated designs. Manufacturing zones near Ho Chi Minh City are emerging as flotation foam assembly hubs for regional re-export.
Australia
Special forces rapid acquisition channels bypass standard program office timelines for mission-specific configurations. TGA alignment with ISO standards simplifies European supplier market entry. Perth and Sydney defense clusters support Pacific maritime security partnership equipment provisioning.
Ballistic Floatation Vest Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense prime contractors dominating fleet-scale tenders while regional fabricators capture spot procurement through simplified acquisition channels. The supplier base organizes into three archetypes: vertically integrated armor houses with captive materials science capabilities, modular system integrators sourcing ballistic panels and flotation cores from separate supply chains, and regional certification specialists exploiting divergent national testing protocols. Competitive moves concentrate on backward integration into polyethylene fiber supply and geographic expansion toward Indian and Southeast Asian tender markets.
Among defense prime contractors, BAE Systems and Rheinmetall AG exemplify the vertically integrated archetype with European and NATO channel control. Point Blank Enterprises anchors the specialist tier with domestic U.S. manufacturing proximity to Navy and Coast Guard program offices. These three entities represent distinct competitive positioning vectors: transnational defense conglomerate, regional European systems house, and focused domestic contractor.
| Leading Market Players |
|---|
| BAE Systems |
| Rheinmetall AG |
| Point Blank Enterprises |
| Survitec Group |
| MKU Limited |
| Honeywell International |
| Seyntex N.V. |
| Morgan Advanced Materials |
| Craig International Ballistics |
| Others |
Supply Flow & Price Mechanics
Maritime agency procurement programs concentrate buying power among coast guard and naval organizations in the United States, India, and Southeast Asia, anchoring contract-based long-term offtake as the dominant pricing model with volume-scale discounts and multi-year fleet replacement schedules.
Pricing Analysis
Capacity additions in Vietnam and India are reshaping price floors for polyethylene-reinforced tactical vests, compressing margins for legacy aramid-dependent suppliers. Pricing stratifies across NIJ Level IV premium configurations, Level IIIA standard maritime units, and economy-tier work vests for commercial fishing applications. Cost compression in the standard tier is intensifying as domestic Indian composite fabrication scales. Law enforcement marine units exhibit the highest price sensitivity due to municipal budget constraints, while naval special operations commands prioritize performance over unit cost.
Supply Chain Analysis
Specialized composite technicians trained in both ballistic lamination and marine sealing remain scarce in Florida, Virginia, and North Rhine-Westphalia manufacturing clusters, constraining output expansion despite equipment investment. Raw material supply draws from ultra-high molecular weight polyethylene fiber producers, para-aramid suppliers controlled by Dupont and Teijin, and cross-linked closed-cell foam chemistries. Single-source vulnerability in aramid fiber feedstock creates procurement risk when defense cycles synchronize. Distribution runs through defense prime contractor intermediaries for fleet-scale orders, with direct-to-unit e-commerce channels capturing replacement vest demand below program office thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ballistic floatation vests rests on polyethylene fiber substitution reducing material costs and rescue operations applications commanding premium pricing for dual-use certification.
For Market Incumbents: To counter polyethylene fiber decentralization eroding procurement advantages, anchor Navy and Coast Guard relationships through 46 CFR recertification support and captive supply of ultra-high molecular weight fiber via backward integration into domestic composite fabrication capacity. For New Entrants and Emerging Players: Capture swift-water rescue team procurement outside traditional prime contractor channels by targeting Australian and U.S. special forces rapid acquisition platforms with MOLLE-compatible inflatable collar configurations and simplified NIJ validation pathways. For Investors and Strategic Acquirers: Defense conglomerates seeking maritime portfolio depth are the most active acquirer in this space, with long-term viability hinging on dual-certification capability spanning ballistic and flotation protocols. Monitor Indian BIS certification approval timelines as the inflection signal for foreign supplier market access expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyethylene Fiber Supply | Captive UHMWPE production insulates against Teijin and Dupont queue volatility. |
| Dual Certification Investment | Concurrent NIJ and 46 CFR validation accelerates timeline-to-revenue for new designs. |
| Rescue Operations Channel Development | Civilian emergency services budgets absorb defense-sector equipment innovations. |
| Indian Manufacturing Footprint Expansion | Tamil Nadu and Maharashtra corridors satisfy BIS and DGFT localization requirements. |
| Software-Defined Buoyancy R&D | Programmable foam density controls differentiate premium tactical configurations. |
Methodological Framework
Multiple input streams — procurement officer interviews at U.S. Coast Guard and Indian Navy program offices, composite fabrication plant assessments in Florida and North Rhine-Westphalia, and regulatory filing analysis — were reconciled with secondary validation from NIJ protocol documentation, 46 CFR Subpart 160.064 standards, and customs trade data. Primary discussions with ballistic materials scientists, maritime equipment distributors, and swift-water rescue team equipment coordinators informed supply chain and demand segmentation assumptions. Bottom-up unit shipment estimates and top-down defense budget allocation analysis were triangulated for cross-verification.
Data-stream reconciliation across product type, material composition, application context, and end-user category dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of procurement cycle timing, certification backlog duration, and polyethylene fiber cost curves. Modeled inputs included Southeast Asian naval modernization tender pipelines, EU REACH foam chemistry substitution timelines, and special forces simplified acquisition channel penetration rates.
Regulatory harmonization failures, aramid fiber supply synchronization shocks, and coast guard standard revision delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding certification timeline compression and material substitution elasticity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Hazmat Suits Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Americas Reusable Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Smart Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Functional Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Emergency Lighting Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Safety Goggles Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market