
 Electrophotography Printing for Packaging Market | 2026-2036
Electrophotography Printing for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Electrophotography Printing for Packaging Market Foresight
Modular short-run packaging configurations is hardening as the default procurement model for mid-size consumer brands. HP Inc. leverages its Indigo platform to dominate high-mix label production across North American pharma converters. Xeikon N.V. anchors its position in European flexible packaging through dry-toner systems optimized for food-contact compliance. Canon Inc. extends its reach into folding carton work with liquid electrophotography engines that compete on metallic substrate fidelity.
Electrophotography printing for packaging deploys charged photoconductor drums or belts to transfer dry toner or liquid ink onto paper, film, and board substrates at resolutions reaching 2400 dpi, with primary purpose of enabling variable-data branding and regulatory marking without plate changes. Labels sustain the largest revenue pool among product type segments because SKU proliferation across food and beverage chains demands frequent artwork turnover. Liquid electrophotography technology leads in premium folding carton applications where gloss uniformity and fine-line detail command price premiums over flexographic alternatives. Short-run jobs represent the fastest-growing application category as brand owners reduce inventory risk through just-in-time packaging campaigns.
FDA serialization requirements for pharmaceutical packaging and EU MDR traceability mandates together reshape demand toward digital presses with integrated variable-data engines. REACH compliance on toner chemistry and substrate recyclability further constrains formulation choices for equipment sold into European converter bases. Stakeholders must monitor how EPA VOC regulations and emerging state-level extended producer responsibility laws in California and New York redefine acceptable material sets for domestic packaging production.
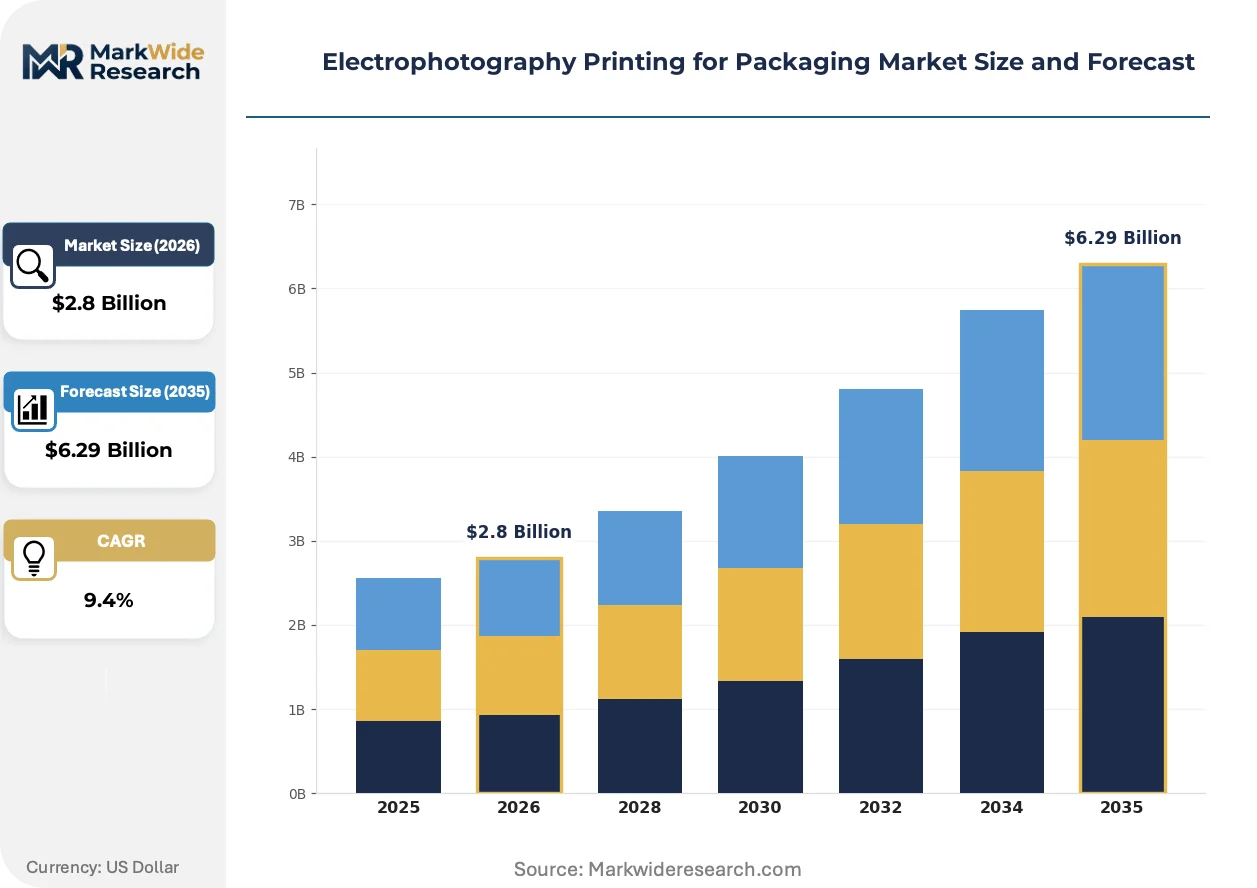
Market Dynamics
Pharmaceutical serialization mandates from the FDA and EU MDR are compressing print run lengths and eliminating plate-based workflows across packaging converters serving regulated supply chains. This regulatory pressure is restructuring capital allocation toward digital press platforms with integrated variable-data engines.
Growth Catalysts
- EU MDR traceability mandates:European medical device packaging must carry unique device identifiers, forcing converters to abandon analog plate systems for on-demand digital production capable of single-unit serialization.
- SKU proliferation in food and beverage:Brand owners launch limited-edition and regional variants at accelerating cadence, demanding packaging workflows that switch artwork without makeready delays or plate inventory.
- Germany's industrial packaging corridor:Premium cosmetic and pharmaceutical brands concentrated in Baden-Württemberg and Bavaria drive concentrated demand for short-run digital folding carton and label production.
Market Restraints
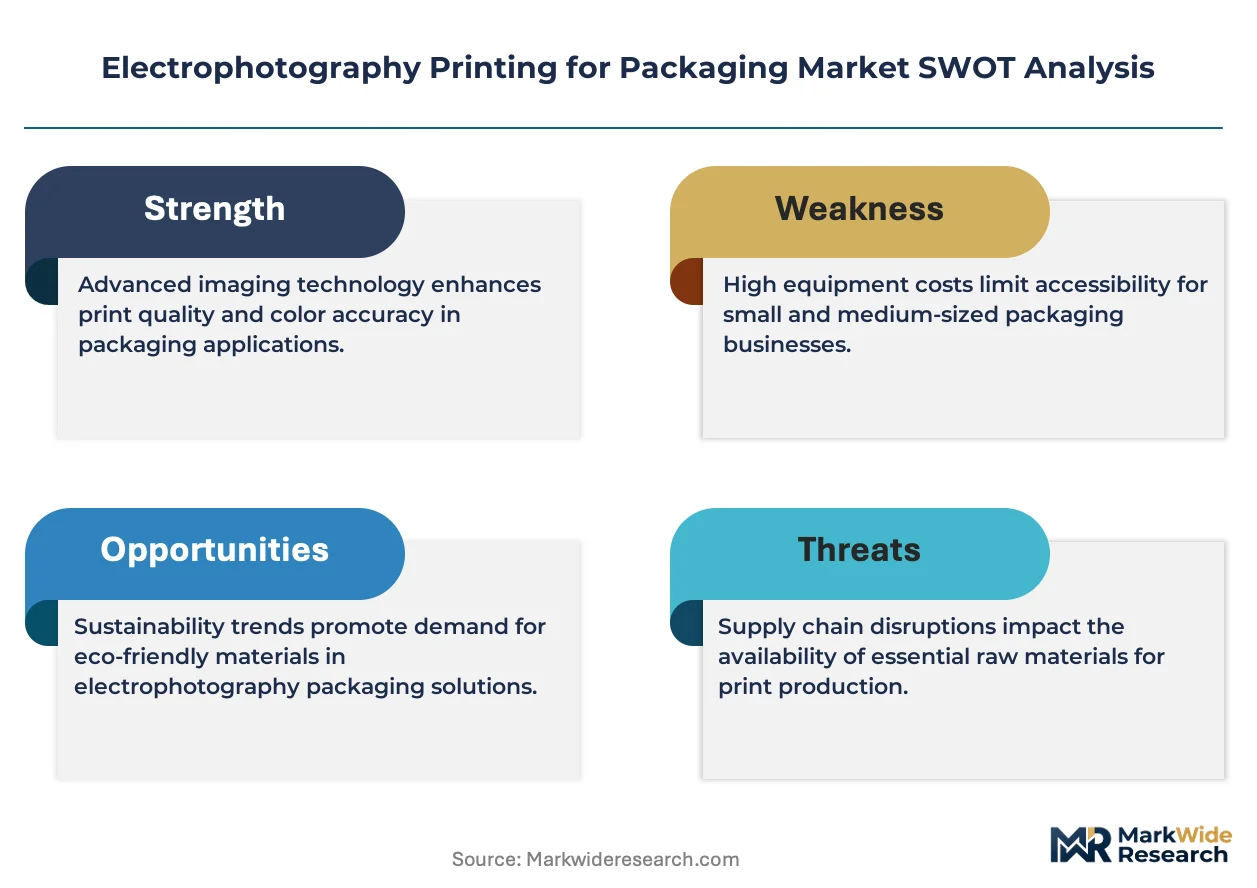
- Specialty toner chemistry costs:Food-contact-compliant dry toner formulations command 40-60% raw material premiums over standard grades, compressing converter margins on compliant jobs.
- Photoconductor drum supply concentration:Precision electrophotographic imaging components concentrate among Japanese and Korean component suppliers, exposing equipment OEMs to single-source risks.
- Flexographic quality convergence:High-definition flexo with fixed palette expanded gamut ink systems narrows the quality gap for long-run folding carton work, threatening electrophotography's premium positioning.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO serialization requirements for export-bound drug products create virgin demand for digital label capacity in Mumbai and Hyderabad converter clusters.
- California extended producer responsibility laws:State-level packaging recyclability mandates favor mono-material substrate constructions that liquid electrophotography handles without adhesive lamination layers.
- Near-field communication tag integration:Convergence of printed electronics with electrophotographic decoration enables smart packaging with embedded authentication and consumer engagement triggers.
Industry Challenges
- Variable-data workflow integration:Converter IT departments struggle to marry ERP serialization databases with press-side raster image processors without custom middleware development.
- Food-contact certification timelines:REACH compliance documentation for novel toner chemistries requires 18-24 month toxicological review cycles, delaying product launches in European markets.
- Color management standardization gaps:Absence of unified ICC profile exchange protocols between brand owner design studios and converter prepress departments generates costly proofing iterations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrophotography Printing for Packaging Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Flexible Packaging, Folding Cartons, Corrugated Boxes End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Technology: Dry Electrophotography, Liquid Electrophotography, Hybrid Systems, Inkjet Integration Application: Branding, Promotional Packaging, Information Labels, Short-Run Jobs |
| Companies Covered | HP Inc., Xeikon N.V., Domino Printing Sciences plc, Eastman Kodak Company, Canon Inc., Xerox Corporation, Ricoh Company, Ltd., Konica Minolta Business Solutions, Seiko Epson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrophotography Printing for Packaging Market Shifts & Advancements
Liquid electrophotography platforms are capturing premium folding carton volume by delivering metallic substrate fidelity and gloss uniformity that analog alternatives cannot match at short run lengths. Three developments are actively restructuring competitive positioning.
Liquid electrophotography is consolidating its position in high-value folding carton applications through superior ink transfer efficiency on coated boards. Premium cosmetic and spirits brands in France and Switzerland have adopted this technology for 85% of their metallic and pearlescent packaging requirements. The structural consequence is consolidation of converter investment away from hybrid flexo-digital workflows toward single-pass liquid electrophotographic engines.
REACH restrictions on per- and polyfluoroalkyl substances in food-contact materials are eliminating legacy toner additives across European converter bases. Equipment manufacturers reformulate liquid ink vehicles to maintain fusing performance without fluorinated surfactants. Folding carton converters serving German retail chains are absorbing 12-18 month requalification cycles as they transition to compliant chemistry platforms.
Brand owner sourcing departments are unbundling print procurement from legacy long-term contract structures toward campaign-based digital sourcing. Mid-size consumer brands in North American metropolitan markets now issue packaging purchase orders tied to individual product launch windows rather than annual volume commitments. This behavioral shift concentrates demand in converter facilities with sub-48-hour turnaround capabilities and eliminates capacity planning advantages of traditional long-run specialists.
Electrophotography Printing for Packaging Market Segmentation
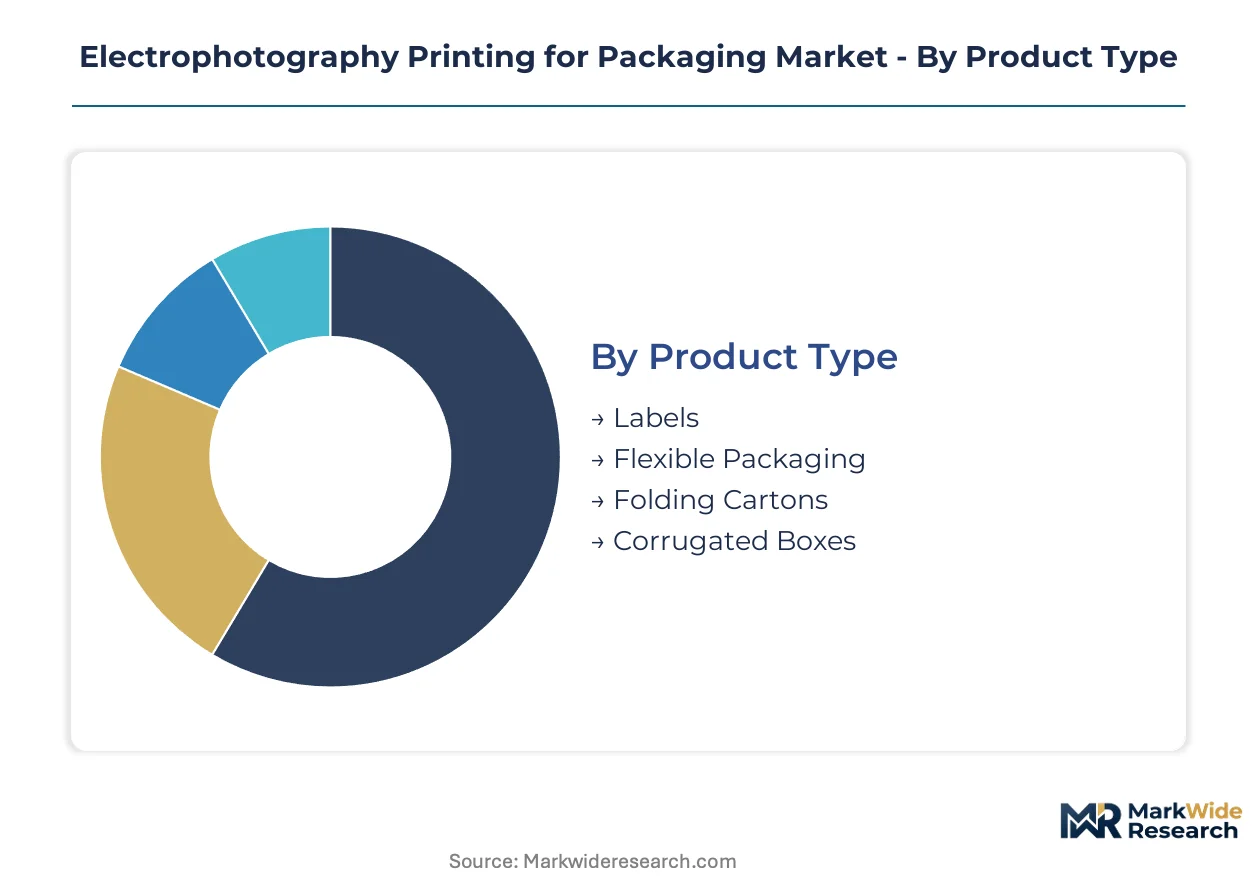
Electrophotography printing for packaging serves divergent substrate requirements and regulatory environments across label, carton, and flexible film applications. Segmentation reveals how capital deployment, compliance burdens, and run-length economics concentrate demand in specific technology-product combinations.
Product Type:
Capital intensity varies sharply across substrate formats, with folding carton and corrugated configurations demanding the heaviest upfront press investments while label production enables modular entry points.
- Labels:Pressure-sensitive and shrink-sleeve formats dominate pharmaceutical serialization workflows where FDA mandates require variable-data printing at 2400 dpi resolution. German converters in Baden-Württemberg cluster serve premium cosmetic brands with short-run digital label capacity. Most installed capacity flows through Labels. Expansion is steepest in Short-Run Jobs.
- Flexible Packaging:Dry-toner systems optimized for food-contact compliance command specialized fusing architectures to handle thin-gauge films without thermal distortion. European converters face REACH-driven reformulation cycles that extend equipment qualification timelines.
- Folding Cartons:Liquid electrophotography engines deliver metallic substrate fidelity on coated boards for spirits and luxury cosmetics. French and Swiss brand owners specify this technology for pearlescent effects unattainable through flexographic alternatives.
- Corrugated Boxes:Heavy-board applications remain limited by toner adhesion challenges on recycled flute structures, though hybrid inkjet-electrophotography integrations are penetrating point-of-purchase display segments.
Labels absorb the majority of installed electrophotography capacity. Folding Cartons are climbing the fastest as premium brand owners abandon plate-based workflows for metallic effects.
End User:
Margin profiles diverge across end-use verticals, with pharmaceutical and personal care applications supporting premium pricing while food and beverage volumes drive equipment utilization.
- Food & Beverage:SKU proliferation in craft beverages and limited-edition snacks compresses run lengths and accelerates artwork turnover. North American metropolitan brand owners now issue campaign-based purchase orders rather than annual volume commitments.
- Personal Care:Premium cosmetic packaging in Germany's industrial corridor demands short-run folding carton production with metallic effects. Liquid electrophotography captures 85% of pearlescent requirements for French and Swiss luxury brands.
- Pharmaceuticals:FDA serialization mandates and EU MDR traceability requirements eliminate analog plate workflows across regulated supply chains. Indian export packaging to CDSCO-compliant markets creates virgin demand in Mumbai and Hyderabad converter clusters.
- Electronics:Anti-static toner formulations and ESD-compliant substrates serve semiconductor and consumer device packaging with specialized fusing requirements.
Pharmaceuticals commands the highest equipment specification tiers. Food & Beverage is expanding most quickly as regional variant launches multiply.
Technology:
Supply-side concentration in photoconductor drum manufacturing shapes technology accessibility, with Japanese and Korean component suppliers controlling precision imaging subsystems.
- Dry Electrophotography:Powder toner systems dominate label and flexible packaging workflows where food-contact compliance requires specialized formulation. REACH restrictions on per- and polyfluoroalkyl substances are forcing 18-24 month requalification cycles across European converter bases.
- Liquid Electrophotography:Ink vehicle systems deliver superior gloss uniformity and fine-line detail on coated folding cartons. HP Indigo platforms anchor North American pharma converter capacity while Canon engines extend into metallic substrate work.
- Hybrid Systems:Configurations combining electrophotographic units with flexographic or screen stations address multi-process decoration requirements for security and tactile effects.
- Inkjet Integration:Tandem architectures merge electrophotography's variable-data precision with inkjet's broader substrate latitude for corrugated and display applications.
Liquid Electrophotography holds the premium positioning tier. Dry Electrophotography maintains the broadest installed base across compliant food packaging.
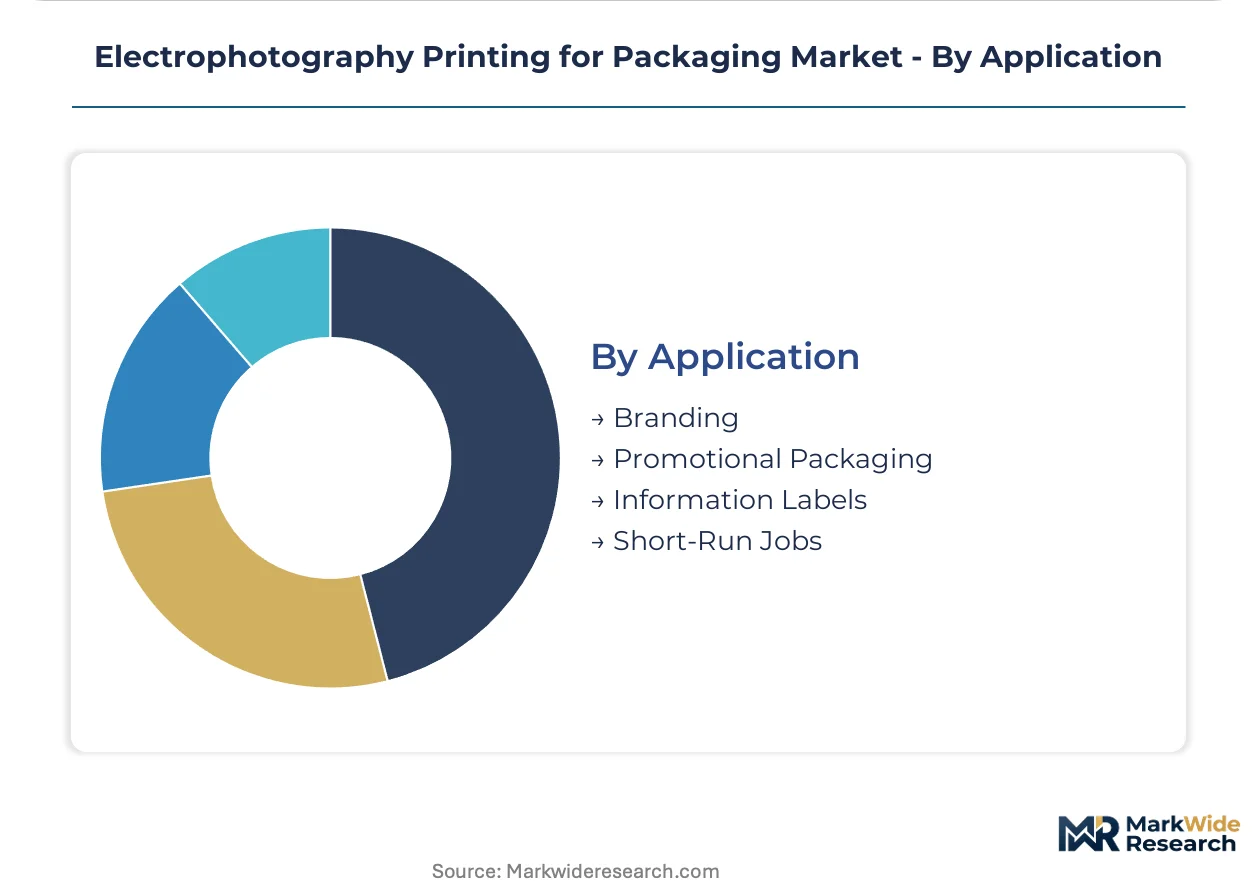
Application:
Workflow integration complexity escalates from static branding through serialized information labels to fully variable short-run production.
- Branding:Corporate identity and shelf-impact graphics require color consistency across repeat orders, favoring electrophotography's digital proofing repeatability over analog makeready variations.
- Promotional Packaging:Limited-edition and seasonal campaigns demand 48-hour turnaround capabilities that eliminate plate inventory and prepress delays.
- Information Labels:Regulatory marking including ingredients, warnings, and traceability codes integrates ERP serialization databases with press-side raster image processors.
- Short-Run Jobs:Just-in-time procurement models for mid-size consumer brands concentrate demand in converter facilities with sub-48-hour artwork changeover capabilities.
Branding retains the largest volume share. Short-Run Jobs are gaining share fastest as inventory risk reduction reshapes procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electrophotography printing for packaging traces its industrial lineage to post-war precision manufacturing in Germany and Japan, where photoconductor drum engineering first scaled for commercial document reproduction before migrating into packaging workflows.
Germany
Baden-Württemberg and Bavaria host Europe's densest cluster of folding carton converters serving premium cosmetic and pharmaceutical brands. EU MDR traceability mandates from EMA force these facilities to abandon analog plate systems for liquid electrophotography platforms with integrated serialization engines. Stuttgart-area equipment manufacturers supply precision photoconductor subsystems to global OEMs.
United States
North American pharma converters concentrate in New Jersey and Pennsylvania corridors where FDA serialization deadlines compress print run lengths toward digital production. EPA VOC regulations and emerging California extended producer responsibility laws reshape acceptable toner chemistries for domestic packaging. HP Indigo platforms dominate high-mix label capacity across these Mid-Atlantic converter bases.
India
Mumbai and Hyderabad converter clusters absorb virgin demand from CDSCO serialization requirements on export-bound pharmaceutical packaging. Domestic food-contact compliance from FSSAI drives dry-toner system adoption for flexible packaging serving regional snack and beverage brands. Tamil Nadu's industrial corridor hosts emerging capacity for electronics anti-static packaging applications.
Japan
Precision photoconductor drum manufacturing concentrates among Osaka and Nagoya component suppliers, exposing equipment OEMs to single-source supply risks. METI industrial standards govern toner chemistry disclosure requirements for food-contact applications. Yokohama-based converters serve luxury cosmetics brands with metallic substrate folding carton production.
Switzerland
Geneva and Basel pharmaceutical headquarters drive specification authority for European serialization-compliant packaging workflows. Swissmedic device regulations align with EU MDR traceability mandates, requiring unique device identifiers on medical packaging. Lausanne-area converters capture premium spirits and luxury goods volume through liquid electrophotography metallic effects.
Electrophotography Printing for Packaging Market Competitive Landscape
The competitive structure tilts toward diversified imaging conglomerates with captive toner chemistry development. Japanese and Korean component suppliers concentrate precision photoconductor manufacturing, creating upstream bottlenecks that shape equipment OEM sourcing strategies. Two strategic archetypes dominate: integrated technology platforms spanning hardware through consumables, and specialized digital press fabricators focused on narrow substrate segments. Competitive moves concentrate on vertical integration into consumables supply and geographic expansion through distributor partnerships in emerging pharmaceutical export corridors.
Within the integrated technology tier, HP Inc. and Canon Inc. exemplify platform-spanning strategies that couple electrophotographic engines with proprietary ink and toner formulations. Xeikon N.V. occupies a specialist position among European flexible packaging converters, representing the narrow-focus archetype centered on dry-toner food-contact compliance. These three anchors illustrate how competitive positioning diverges between scale-driven consumables economics and application-specific regulatory expertise.
| Leading Market Players |
|---|
| HP Inc. |
| Xeikon N.V. |
| Domino Printing Sciences plc |
| Eastman Kodak Company |
| Canon Inc. |
| Xerox Corporation |
| Ricoh Company, Ltd. |
| Konica Minolta Business Solutions |
| Seiko Epson Corporation |
| Others |
Supply & Pricing Matrix
California's extended producer responsibility laws gate qualified supply access and premium-tier pricing power for converters serving West Coast brand owners. Equipment OEMs must certify liquid electrophotography platforms for mono-material substrate compatibility before qualifying for high-margin pharmaceutical and cosmetics contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated serialization systems from general commercial label equipment and refurbished legacy presses. Price differentiation hinges on food-contact certification grade and geographic delivery cost to regulated pharmaceutical corridors. Cost compression in standard-tier dry-toner systems is intensifying because Japanese photoconductor drum suppliers extract component premiums. Mid-size consumer brands in North American metropolitan markets exhibit highest price sensitivity, while Swiss and German luxury cosmetics houses accept premium positioning for metallic substrate fidelity.
Supply Chain Analysis
REACH food-contact certification timelines of 18-24 months gate supply access for novel toner chemistries entering European converter bases. Precision photoconductor drum manufacturing concentrates in Japan, South Korea, and Germany, with Osaka and Nagoya suppliers controlling imaging subsystems. Raw material dependencies include fluorinated surfactant alternatives, coated board substrates, and specialized fusing oils. Single-source vulnerability in Japanese component suppliers exposes equipment OEMs to allocation risk during demand surges. Distribution runs through authorized dealer networks and direct converter relationships, with spare parts flowing through regional service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on REACH-compliant chemistry platforms that command 40-60% raw material premiums while displacing legacy flexographic workflows in premium folding carton segments.
For Market Incumbents: Cement control over photoconductor drum supply through long-term offtake agreements with Osaka and Nagoya component manufacturers. Deepen captive toner chemistry development to defend against Xeikon's dry-toner food-contact expertise in European flexible packaging. Incumbent equipment OEMs face substitution threat from high-definition flexo with expanded gamut ink systems in long-run folding carton work. For New Entrants and Emerging Players: Converter IT departments represent an underserved channel partner type for middleware solutions bridging ERP serialization databases with press-side raster image processors. White-space targets include Mumbai and Hyderabad pharmaceutical export corridors where CDSCO mandates create virgin digital label demand, and California extended producer responsibility compliance services for mono-material substrate qualification. A software-first go-to-market angle bypasses capital-intensive press manufacturing while capturing recurring workflow revenue. For Investors and Strategic Acquirers: Roll-up economics work for regional converter networks because EU MDR and FDA serialization mandates force fragmented analog shops toward digital platform standardization. Five-to-ten year viability favors targets with installed liquid electrophotography capacity serving pharmaceutical and medical device verticals. Watch for REACH restrictions on per- and polyfluoroalkyl substances as the inflection indicator that triggers accelerated equipment replacement cycles across European converter bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toner Chemistry | Captive formulation development compresses 18-24 month REACH requalification cycles for European food-contact compliance. |
| Pharmaceutical Serialization Partnership | Integrated variable-data engines from HP Indigo platforms anchor high-mix label production across New Jersey and Pennsylvania converter corridors. |
| Regional Service Hub Expansion | Mumbai and Hyderabad facilities capture CDSCO-compliant export packaging demand from Indian pharmaceutical clusters. |
| Mono-Material Substrate Certification | Liquid electrophotography qualification for California extended producer responsibility laws unlocks premium folding carton contracts. |
| Near-Field Communication Tag Integration | Convergence with printed electronics enables smart packaging authentication for Swiss and German luxury cosmetics brands. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with packaging converter operations managers, pharmaceutical regulatory affairs leads, brand owner sourcing directors, and equipment OEM product strategists with secondary validation from FDA 483 inspection observations, EMA guidance documents, REACH substance restriction updates, and customs trade data on toner chemistry imports. Bottom-up press installation counts and top-down addressable market sizing were triangulated against converter capacity utilization surveys.
Historical reference periods anchored the projection horizon to pre-pandemic baseline demand and post-mandate inflection points across pharmaceutical serialization compliance deadlines. Segmentation dimensions modeled include substrate format, end-use vertical, technology type, and regional regulatory cluster. CAGRs were derived from equipment shipment trajectories and consumables attach rate analysis, with forecast inputs incorporating EU MDR implementation timelines and California extended producer responsibility phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansions and flexographic quality convergence in metallic substrate applications. Deviation in FDA or EMA serialization enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Label Printing Software Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Flex Banner Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Label Printers Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Flexographic Printing Machine Market
Packaging Printing
Rotogravure Printing Machine Market