
 Pad Printing Machine Market | 2026-2036
Pad Printing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pad Printing Machine Market Outlook
Distributor networks across Southeast Asia are rewriting how pad printing equipment reaches mid-sized decorators. Tampoprint AG leverages its Swiss engineering heritage to sustain premium positioning in medical device marking. Inkcups Now Corporation competes through North American service density and localized ink formulation support. ITW Trans Tech anchors industrial end-user relationships with integrated pad-print-to-cure workflow systems.
A pad printing machine transfers ink from an engraved cliché plate to a substrate via a flexible silicone pad, typically operating with 60–90 Shore A pad hardness and achieving print resolutions down to 40 microns for precision component decoration. Conventional pneumatic machines still dominate installed base volumes, though UV-cured digital pad systems are capturing fastest growth in electronics applications where solvent restrictions tighten. Semi-automatic configurations occupy the largest margin pool among product types by balancing throughput flexibility with capital accessibility for job shops serving automotive and packaging clients.
REACH chemical restrictions in Europe and OSHA permissible exposure limits in the United States are reshaping ink formulation roadmaps and ventilation specifications for installed equipment. China's GB standards for volatile organic compound emissions from printing operations are forcing domestic manufacturers toward water-based ink compatibility in new machine designs. Stakeholders must monitor how regional regulatory divergence affects cross-border equipment certification costs and ink supply chain localization requirements.
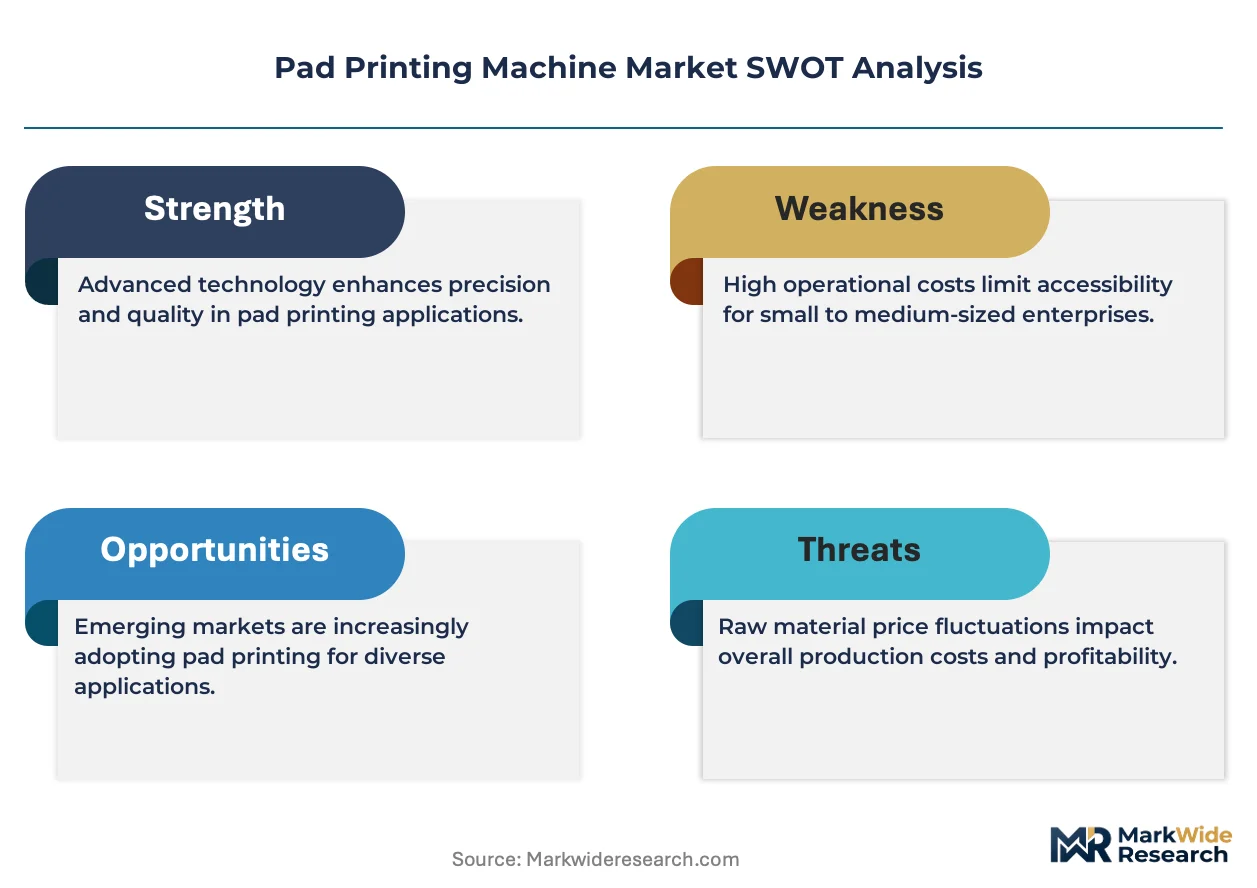
Market Dynamics
UV-cured digital pad systems are compressing solvent-based equipment replacement cycles as REACH and OSHA exposure limits harden ink formulation requirements across automotive traceability and medical device marking applications.
Growth Catalysts
- Automotive Traceability Mandates:REACH and JIS standards in Germany and Japan are forcing OEM component decorators to upgrade pad printing capacity for permanent part identification.
- Electronics Miniaturization:40-micron print resolution requirements for curved smartphone housings in China's Yangtze River Delta are pulling high-precision equipment demand.
- Medical Device Serialization:EU MDR and FDA UDI requirements are expanding pad printing adoption for surgical instrument and implant marking.
Market Restraints
- Silicone Pad Input Concentration:Specialized 60–90 Shore A silicone pad manufacturing concentrates among Japanese and German chemical suppliers, creating price volatility exposure.
- Capital Intensity for UV Integration:Digital UV-cured systems require 2–3x the upfront investment of pneumatic alternatives, compressing accessibility for job shops.
- Substitution by Laser Marking:Fiber laser systems are capturing permanent marking applications in aerospace and high-volume automotive where solvent restrictions tighten fastest.
Strategic Opportunities
- Water-Based Ink Compatibility:China's GB standards for volatile organic compound emissions are creating first-mover advantage for equipment OEMs with native water-based system architecture.
- Southeast Asia Contract Manufacturing:Vietnam and Indonesia electronics assembly corridors remain underpenetrated by precision pad printing relative to China saturation.
- Integrated Print-to-Cure Workflows:Converging pad printing with inline UV curing and robotic handling is opening system-level sales in automotive tier-one supplier plants.
Industry Challenges
- Multi-Standard Certification Burden:Equipment must simultaneously satisfy CE marking, OSHA ventilation specs, and China's GB emissions standards, extending validation timelines.
- Legacy Pneumatic Fleet Obsolescence:Installed base of conventional machines faces stranded asset risk as solvent ink availability contracts under regional chemical restrictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pad Printing Machine Market |
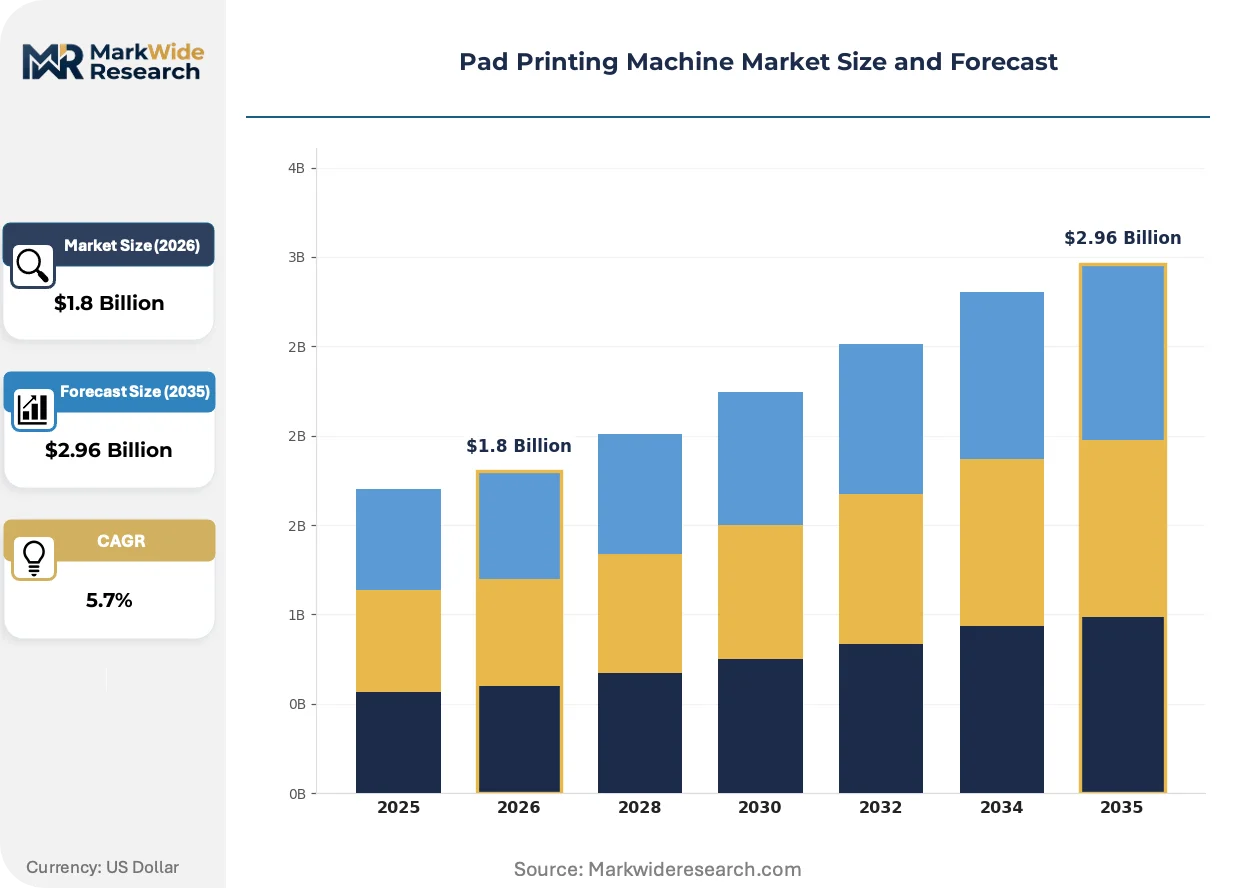
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Conventional, Digital, UV, Water-based Application: Packaging, Automotive Components, Clothing, Electronics End User: Manufacturers, Retailers, Distributors, Service Providers Product Type: Automatic, Semi-automatic, Manual, Customized |
| Companies Covered | Tampoprint AG, Inkcups Now Corporation, Tosh S.R.L., Winon Industrial Co. Ltd., Kent Pad Printer Canada Inc., ITW Trans Tech, Teca-Print AG, Printex, Engineered Printing Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pad Printing Machine Market Strategic Shifts
Digital pad printing architectures are displacing mechanical indexing systems as electronics manufacturers demand lot-size flexibility and real-time print data logging for supply chain traceability.
UV-LED curing modules are rendering obsolete thermal drying tunnels in electronics-focused pad printing lines. Smartphone housing decorators in South Korea and Taiwan are retrofitting existing pneumatic frames with UV-LED attachments to compress cycle times from 8 seconds to 3 seconds per print. This retrofit pattern is rendering obsolete the traditional distinction between "digital" and "conventional" equipment categories.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and other solvent carriers are forcing reformulation of pad printing inks across European automotive supply chains. The industrial consequence is a 40% reduction in available ink chemistries for legacy equipment, pushing decorators toward UV-curable or water-based system upgrades. German automotive component suppliers are responding fastest, with tier-two decorators in Bavaria and Baden-Württemberg accelerating replacement schedules.
After-sales service unbundling is disrupting traditional equipment-plus-maintenance bundling in North American job shops. Mid-sized decorators in Michigan and Ohio are procuring pad printing machines through capital leases while sourcing ink formulation support and pad replacement through separate regional distributors. This purchasing fragmentation is most visible in automotive aftermarket parts marking, where decorators prioritize localized technical response over OEM brand loyalty.
Pad Printing Machine Market Segmentation
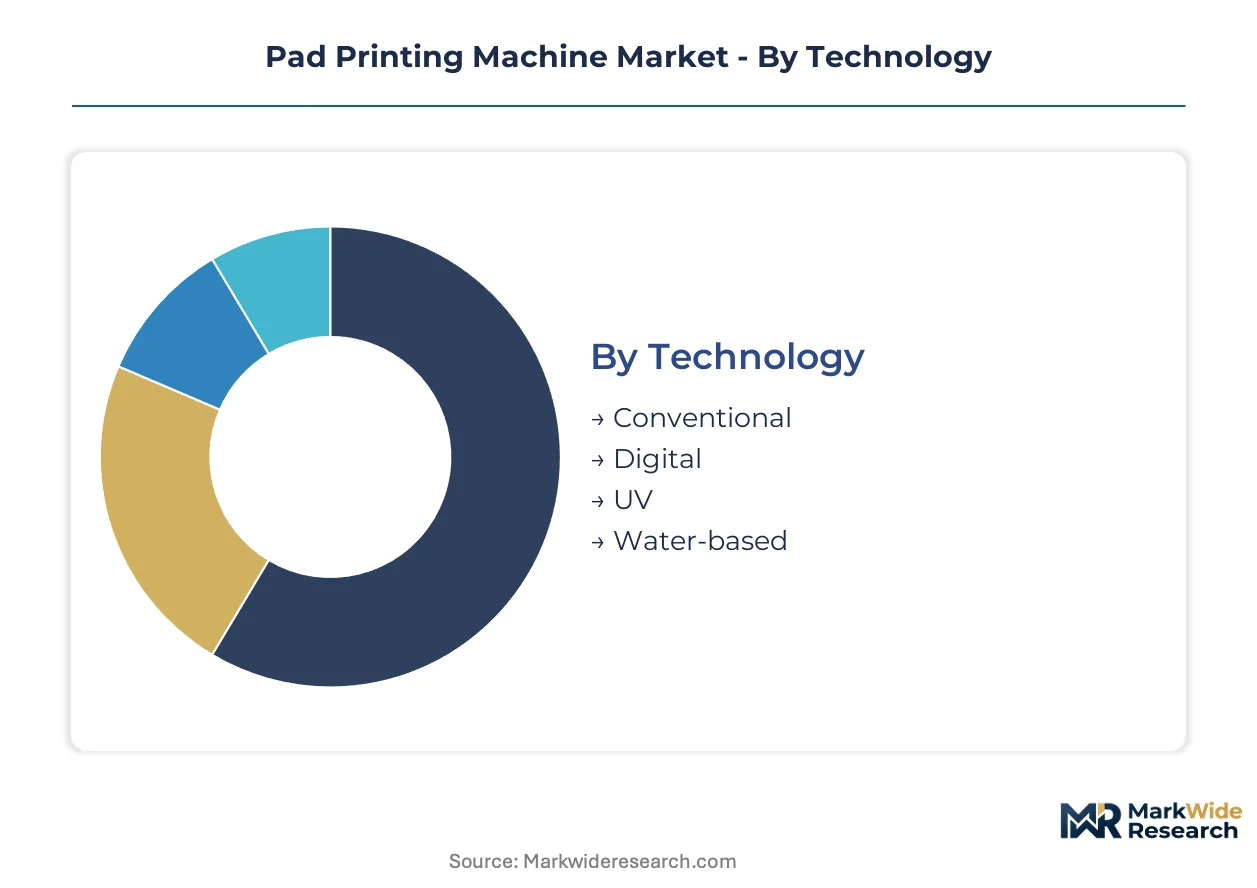
Pad printing machine segmentation reveals how technology maturity, application specificity, and operational scale fragment procurement patterns across automotive traceability mandates and electronics miniaturization requirements. Equipment buyers prioritize different performance attributes depending on whether they serve regulated medical device serialization or high-volume consumer packaging runs.
Technology:
Mature pneumatic architectures coexist with emerging digital and sustainable ink systems as regulatory pressure on solvent emissions intensifies across multiple geographies.
- Conventional:Pneumatically actuated systems with mechanical indexing dominate installed base volumes due to lower capital thresholds and established technician familiarity. Tier-two automotive suppliers in Germany retain these systems for non-critical component marking where REACH compliance deadlines remain distant.
- Digital:Servo-driven architectures with real-time print data logging capture electronics manufacturing demand in China's Yangtze River Delta, where lot-size flexibility and supply chain traceability requirements from Apple and Samsung suppliers mandate programmable repeatability. These systems compress setup times from hours to minutes for curved smartphone housing production.
- UV:UV-LED curing modules integrated with pad printing frames reduce cycle times from 8 seconds to 3 seconds per print, attracting South Korean and Taiwanese smartphone housing decorators seeking throughput gains without full system replacement.
- Water-based:Native water-based ink compatibility addresses China's GB standards for volatile organic compound emissions, creating specification advantages for equipment OEMs targeting domestic Chinese manufacturers facing MEE enforcement.
Conventional systems retain volume leadership among legacy installed base; digital architectures hold the steepest expansion curve as electronics traceability requirements harden.
Application:
Cost tier differentiation separates precision-regulated applications from high-volume decorative runs with minimal compliance burden.
- Packaging:High-speed decoration of cosmetic containers and promotional items emphasizes throughput over micron-level precision, with job shops prioritizing semi-automatic configurations for batch flexibility.
- Automotive Components:Permanent part identification under REACH and JIS standards demands 40-micron resolution capability and solvent-resistant ink durability, pulling investment toward UV-cured systems in German and Japanese OEM supply chains.
- Clothing:Tagless label printing on elastic fabrics requires specialized pad compounds and lower Shore A hardness specifications, concentrating demand among Southeast Asian garment manufacturing clusters.
- Electronics:Curved device housing decoration in China's contract manufacturing corridor specifies high-precision equipment with automated vision alignment, with decorators serving Apple and Samsung suppliers commanding premium positioning.
Automotive components command premium pricing tiers; electronics applications generate the steepest technology upgrade velocity.
End User:
Customer type determines procurement channel preference, with integrated manufacturers diverging from decentralized service networks in aftermarket support expectations.
- Manufacturers:Tier-one automotive and electronics producers specify integrated print-to-cure workflows with robotic handling, consolidating vendor relationships around system-level performance guarantees.
- Retailers:In-house decoration of private-label merchandise drives demand for compact semi-automatic units with rapid changeover capability across seasonal product lines.
- Distributors:Equipment resale and regional ink formulation support unbundle traditional OEM service bundles, particularly visible in North American job shop procurement fragmentation.
- Service Providers:Contract decorators in Vietnam and Indonesia electronics corridors operate on capital lease structures, prioritizing localized technical response over brand loyalty.
Manufacturers concentrate spending on integrated systems; service providers exhibit the fastest procurement volume expansion in underpenetrated Southeast Asian markets.
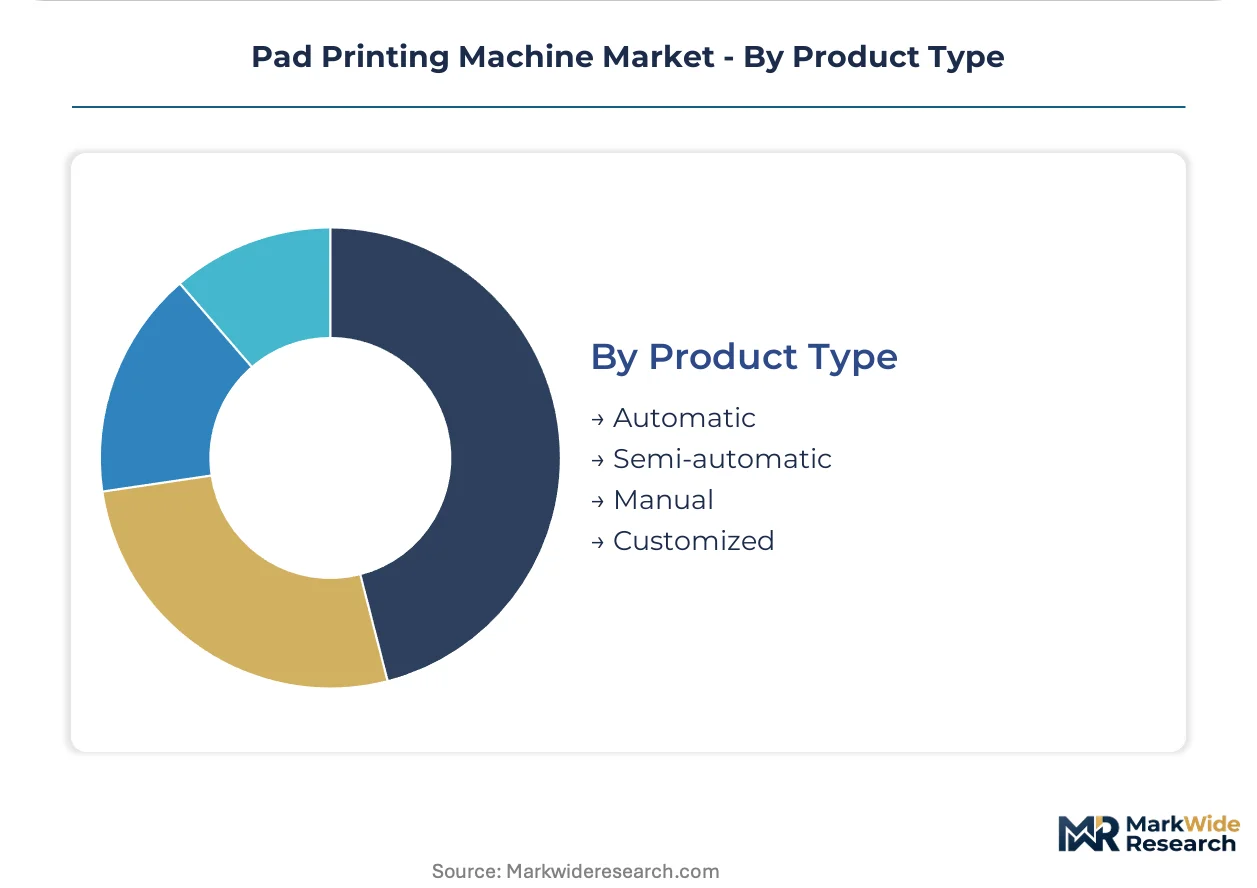
Product Type:
Automation level stratifies accessibility, with mid-tier configurations balancing throughput and capital commitment for job shop economics.
- Automatic:Fully automated lines with inline curing and robotic substrate handling serve high-volume automotive tier-one plants where labor cost arbitrage justifies capital intensity.
- Semi-automatic:Operator-fed systems with programmable print heads occupy the largest margin pool, balancing throughput flexibility with capital accessibility for job shops serving mixed automotive and packaging clients.
- Manual:Entry-level benchtop units address prototype and short-run decoration in educational institutions and startup decorators, with minimal regulatory compliance requirements.
- Customized:Application-specific configurations for medical device serialization or aerospace component marking incorporate specialized pad geometries and cleanroom-compatible materials.
Semi-automatic configurations anchor revenue concentration; automatic systems climb fastest as automotive traceability mandates accelerate replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement of GB standards for volatile organic compound emissions anchors Chinese demand for water-based pad printing systems. REACH chemical restrictions and FDA UDI requirements simultaneously reshape equipment specifications across European and North American medical device corridors.
China
Electronics miniaturization in the Yangtze River Delta pulls high-precision equipment demand from Apple and Samsung suppliers. GB standards enforced by MEE mandate VOC emission reductions, forcing domestic manufacturers toward water-based ink compatibility. Contract decorators in Suzhou and Shenzhen operate dense clusters of servo-driven systems for curved smartphone housing production.
Germany
Automotive traceability mandates under REACH force OEM component decorators to upgrade pad printing capacity for permanent part identification. KBA oversight of supply chain compliance extends to tier-two decorators in Bavaria and Baden-Württemberg. Tier-two suppliers accelerate replacement schedules as Annex XVII restrictions contract solvent ink availability by 40%.
United States
OSHA permissible exposure limits reshape ink formulation roadmaps and ventilation specifications for installed equipment. FDA UDI requirements expand pad printing adoption for surgical instrument and implant marking. Michigan and Ohio job shops fragment procurement through capital leases and unbundled regional distributor relationships.
Japan
JIS standards drive OEM component decorators to expand pad printing capacity for permanent part identification. METI oversight of manufacturing quality standards extends to automotive supply chain documentation. Automotive component decorators concentrate capacity expansion in Nagoya and Osaka industrial corridors.
South Korea
Smartphone housing decorators retrofit existing pneumatic frames with UV-LED attachments to compress cycle times. MFDS medical device regulations expand precision marking requirements for surgical instruments. Seoul and Suwon electronics manufacturing clusters drive fastest adoption of UV-cured digital pad systems.
Pad Printing Machine Market Competitive Environment
Swiss-engineering heritage specialists and North American service-density providers split the market along premium positioning versus localized support vectors. The vendor base concentrates among European precision fabricators and Asia-Pacific volume manufacturers. Three archetypes dominate: engineering-driven premium specialists, regional service-network operators, and integrated workflow-system providers. Competitive moves center on geographic expansion through distributor partnerships and technology licensing for UV-cured digital architectures.
Among Swiss-engineering-driven specialists, Tampoprint AG and Teca-Print AG exemplify premium-tier positioning anchored by precision heritage. ITW Trans Tech occupies a position within the integrated-systems archetype, representing workflow convergence strategies. Inkcups Now Corporation sits within the North American service-density vector, exemplifying localized technical response models.
| Leading Market Players |
|---|
| Tampoprint AG |
| Inkcups Now Corporation |
| Tosh S.R.L. |
| Winon Industrial Co. Ltd. |
| Kent Pad Printer Canada Inc. |
| ITW Trans Tech |
| Teca-Print AG |
| Printex |
| Engineered Printing Solutions |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta freight corridor's container cost dynamics transmit directly into pad pricing power for German and Japanese silicone suppliers while forcing downstream differentiation between configured-to-order UV-cured systems and standard pneumatic equipment.
Pricing Analysis
The customization-premium spread separates servo-driven digital architectures from conventional pneumatic frames by a factor reflecting automation density and traceability certification tiers. Three-tier pricing structure across premium, standard, and economy levels aligns with CE marking complexity and regional ventilation specification bundles. Cost compression in mid-tier semi-automatic configurations is intensifying because contract decorators in Southeast Asia prioritize capital accessibility over OEM brand loyalty. Job shops serving mixed automotive and packaging clients exhibit highest price sensitivity; tier-one automotive plants demonstrate lowest sensitivity due to integrated workflow performance guarantees.
Supply Chain Analysis
Extended payment terms from Japanese and German chemical suppliers anchor working capital structures for silicone pad procurement across the equipment manufacturing base. Specialized 60–90 Shore A silicone manufacturing concentrates in Japan, Germany, and select Swiss chemical suppliers, creating input dependencies for flexible pad compounds and UV-curable ink formulations. Single-source vulnerability runs through photoinitiator supply for UV-LED curing modules. Distribution runs through Southeast Asian distributor networks that unbundle traditional OEM service bundles for mid-sized decorators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pad printing machine market is exiting a cyclical trough driven by automotive traceability mandate acceleration across REACH and JIS jurisdictions, with replacement demand compressing traditional equipment lifecycles.
For Market Incumbents: Pre-empt fiber laser substitution in aerospace and high-volume automotive by embedding UV-cured digital architectures with real-time print data logging as standard configurations. Deepen backward integration into silicone pad compounds to offset Japanese and German supplier price volatility. Anchor tier-one automotive relationships through integrated print-to-cure workflow performance guarantees that contract decorators cannot replicate.
For New Entrants and Emerging Players: Vietnam and Indonesia electronics assembly corridors remain underpenetrated by precision pad printing relative to China saturation, offering white-space entry with water-based ink compatible systems aligned to MEE enforcement patterns. Target contract decorators operating on capital lease structures who prioritize localized technical response over legacy OEM relationships. Enter through regional ink formulation partnerships that fragment incumbent service bundles.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized pad printing divisions lacking UV-cured digital capabilities. Long-term viability rests on equipment OEMs capturing recurring revenue from ink formulation and pad replacement rather than transactional machine sales. Watch for acceleration in tier-two automotive supplier replacement schedules as Annex XVII solvent restrictions harden.
| Strategic Initiative | Industry Significance |
|---|---|
| UV-LED Retrofit Module Development | South Korean smartphone housing decorators compress cycle times from 8 seconds to 3 seconds without full system replacement. |
| Water-Based Ink System Architecture | Domestic Chinese manufacturers facing MEE enforcement gain specification advantages in GB standards compliance. |
| Southeast Asian Distributor Partnership | Vietnam and Indonesia electronics corridors access precision pad printing capacity previously concentrated in China. |
| Integrated Print-to-Cure Workflow | Tier-one automotive suppliers consolidate vendor relationships around robotic handling and inline curing performance. |
| Silicone Pad Compound Backward Integration | Equipment OEMs reduce exposure to Japanese and German chemical supplier price volatility. |
Study Parameters
The analysis maps pneumatic, digital, UV-cured, and water-based ink system architectures, each validated through equipment OEM product managers, contract decorator operations directors, automotive tier-one supplier procurement leads, and regional ink distributor technical specialists. Primary interview insights triangulate against customs trade data for pad printing equipment imports, SEC filings from diversified industrial conglomerates with printing divisions, MEE enforcement notices on GB standard compliance, and REACH Annex XVII regulatory updates. Bottom-up installed base estimates and top-down market sizing converge through cross-validation across the analysis window.
The assumption-set framing holds REACH and OSHA exposure limit enforcement trajectories as fixed while varying electronics miniaturization velocity and automotive traceability mandate compliance deadlines across geographies. Segmentation dimensions modeled include technology maturity, application specificity, automation level, and end-user procurement channel preference. CAGRs derive from replacement cycle compression analysis and technology transition elasticity estimates. Forecast inputs incorporate silicone pad input price volatility indices and UV-LED curing module adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by mid-cap specialists or accelerated fiber laser substitution in automotive would shift outcomes. Macroeconomic contraction in electronics contract manufacturing, regulatory divergence extending multi-standard certification timelines, or breakthrough water-based ink performance eliminating UV-cured advantages would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Mexico Print Label Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Laser Coders Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Flex Banner Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Czech Republic Printing Label Market