
 North America Thermal Transfer Overprinter Market | 2026-2036
North America Thermal Transfer Overprinter Market Size, Share, and Industry Trends Forecast 2026-2036
North America Thermal Transfer Overprinter Market Analytics
High-resolution 300 dpi specification tiers is bifurcating the competitive landscape as food and pharmaceutical packagers demand GS1-compliant barcodes. Domino Printing Sciences plc leverages its European R&D base to sustain technology leadership in North American clean-room installations. Videojet Technologies, Inc. anchors its position through extensive direct service networks across the United States and Canada. ITW Diagraph differentiates via specialized integration with form-fill-seal packaging machinery common in dairy and snack operations.
A thermal transfer overprinter employs a heated printhead to melt wax or resin-based ink from a ribbon onto a substrate, producing permanent marks resistant to moisture, solvents, and abrasion at speeds exceeding 600 mm per second. The technology serves primarily to apply variable data—batch numbers, expiration dates, and serialized barcodes—onto flexible packaging films, labels, and corrugated cases in continuous production environments. Industrial printers dominate installed base value due to their integration with high-throughput packaging lines, while high-speed printers represent the fastest-expanding product category as e-commerce fulfillment centers demand rapid throughput for variable box labeling. The food and beverage end-user segment commands the largest share of replacement ribbon and printhead consumables, though pharmaceuticals generates superior margin pools driven by FDA-mandated serialization requirements for track-and-trace compliance.
FDA enforcement of the Drug Supply Chain Security Act and FSMA traceability rules directly shapes equipment upgrade cycles across pharmaceutical and food processing facilities. OSHA machine guarding standards and NFPA electrical safety codes in hazardous-area chemical packaging plants further constrain supplier certification requirements. The EPA's evolving VOC regulations for solvent-based marking alternatives indirectly accelerate thermal transfer adoption as a clean marking technology. Stakeholders must monitor pending FDA food traceability rulemakings and state-level extended producer responsibility legislation in California and New York to anticipate compliance-driven replacement demand.
Market Dynamics
FDA traceability mandates under FSMA and DSCSA are compressing equipment replacement cycles as packagers abandon legacy inkjet systems for thermal transfer compliance. The regulatory pressure intersects with ribbon chemistry advances to reshape competitive positioning across food, pharmaceutical, and chemical verticals.
Growth Catalysts
- FDA Food Safety Modernization Act:Lot code and expiration date mandates force dairy and snack processors to upgrade marking equipment. Form-fill-seal integration requirements accelerate thermal transfer adoption over continuous inkjet alternatives.
- Pharmaceutical serialization:Track-and-trace compliance under DSCSA drives replacement demand at contract packaging organizations. High-resolution 300 dpi specifications become mandatory for GS1-compliant barcodes.
- Midwest manufacturing corridor concentration:Illinois, Ohio, and Michigan food processing clusters generate concentrated equipment demand. Proximity to OEM service networks reduces downtime risk for high-throughput lines.
Market Restraints
- Resin ribbon cost volatility:Petroleum-derived thermal transfer ribbons face input cost pressure from crude price swings. Food packagers operating on thin margins resist per-unit marking cost increases.
- Printhead supply concentration:Precision ceramic heating element production concentrates among Asian component suppliers. Lead time volatility constrains North American printer OEM output planning.
- Laser marking substitution:Fiber laser systems compete for corrugated case applications with lower consumable requirements. E-commerce fulfillment centers pilot laser for high-volume box serialization.
Strategic Opportunities
- Canadian cannabis packaging:Health Canada track-and-trace mandates create new demand for serialized labeling on flexible pouches. Provincial distribution monopolies standardize equipment specifications.
- Wax-resin hybrid ribbon chemistry:Advances in multi-layer coating technology enable single-ribbon solutions across film and paper substrates. Reduced SKU complexity attracts mid-size converters.
- Direct-to-consumer food subscription:Meal kit and specialty food shippers require variable data printing for personalized batch tracking. Regional fulfillment centers outside traditional manufacturing hubs need compact printer footprints.
Industry Challenges
- Electrical technician scarcity:NFPA 79 compliance and hazardous-area certification requirements strain field service capacity. Printer OEMs compete for qualified installation and maintenance personnel.
- Legacy PLC integration complexity:Brownfield packaging lines running proprietary control architectures resist seamless thermal transfer printer communication. Custom middleware development extends deployment timelines.
- Clean-room certification timelines:Pharmaceutical installations require ISO 14644 validation that delays production ramp. Documentation burden extends project completion by 8-14 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Thermal Transfer Overprinter Market |
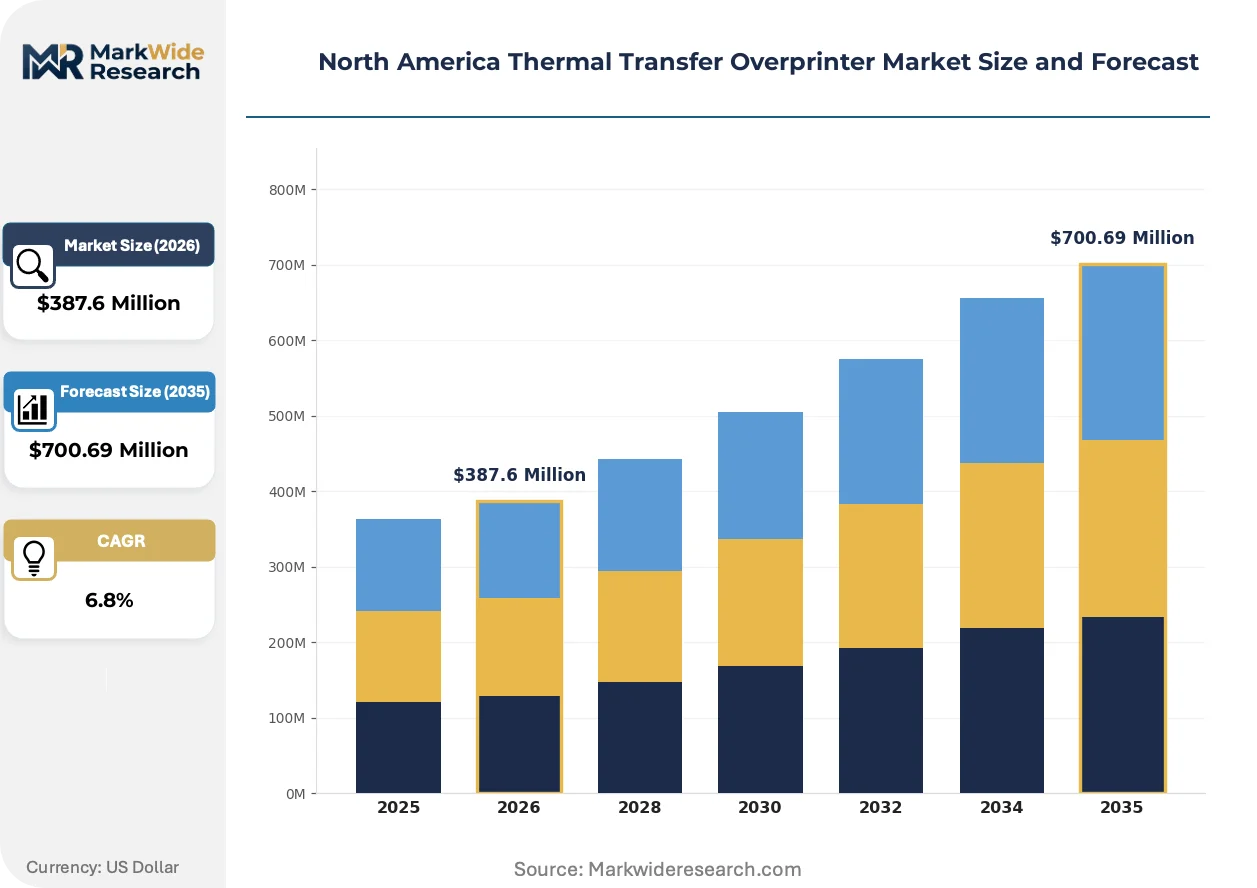
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Printers, Industrial Printers, Portable Printers, High-Speed Printers End User: Food & Beverage, Pharmaceuticals, Electronics, Consumer Goods Technology: Direct Thermal, Thermal Transfer, Full Color, Hybrid Technology Operating Environment: Indoor, Outdoor, Hazardous Area, Clean Room |
| Companies Covered | ID Technology, LLC, EDM Corporation, Domino Printing Sciences plc, Videojet Technologies, Inc., ITW Diagraph, Hitachi Industrial Equipment Marking Solutions Inc., Koenig & Bauer Coding GmbH, MULTIVAC, Squid Ink, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Thermal Transfer Overprinter Market Evolving Landscape
Thermal transfer technology is fragmenting across performance tiers as end-use requirements diverge. Ribbon chemistry, printhead architecture, and connectivity protocols are evolving in parallel to serve distinct compliance and throughput demands.
Near-edge printhead architecture is fragmenting the competitive landscape between 53mm and 107mm print width specifications. Pharmaceutical contract packagers adopt narrower formats for blister foil serialization at 300 dpi. The technology is fragmenting equipment vendor portfolios into specialized clean-room and industrial-grade product lines with incompatible ribbon supplies.
EPA VOC regulations for solvent-based marking alternatives indirectly accelerate thermal transfer adoption in chemical packaging facilities. OSHA machine guarding standards and NFPA electrical safety codes constrain supplier certification requirements for hazardous-area installations. Food processors in California and New York monitor pending state extended producer responsibility legislation for compliance-driven replacement timing.
Service contract unbundling is reshaping how packagers procure maintenance and consumables. Large food and beverage manufacturers separate printer hardware acquisition from managed print service agreements. The Midwest manufacturing corridor shows the strongest concentration of third-party service providers competing against OEM direct service networks.
North America Thermal Transfer Overprinter Market Segmentation
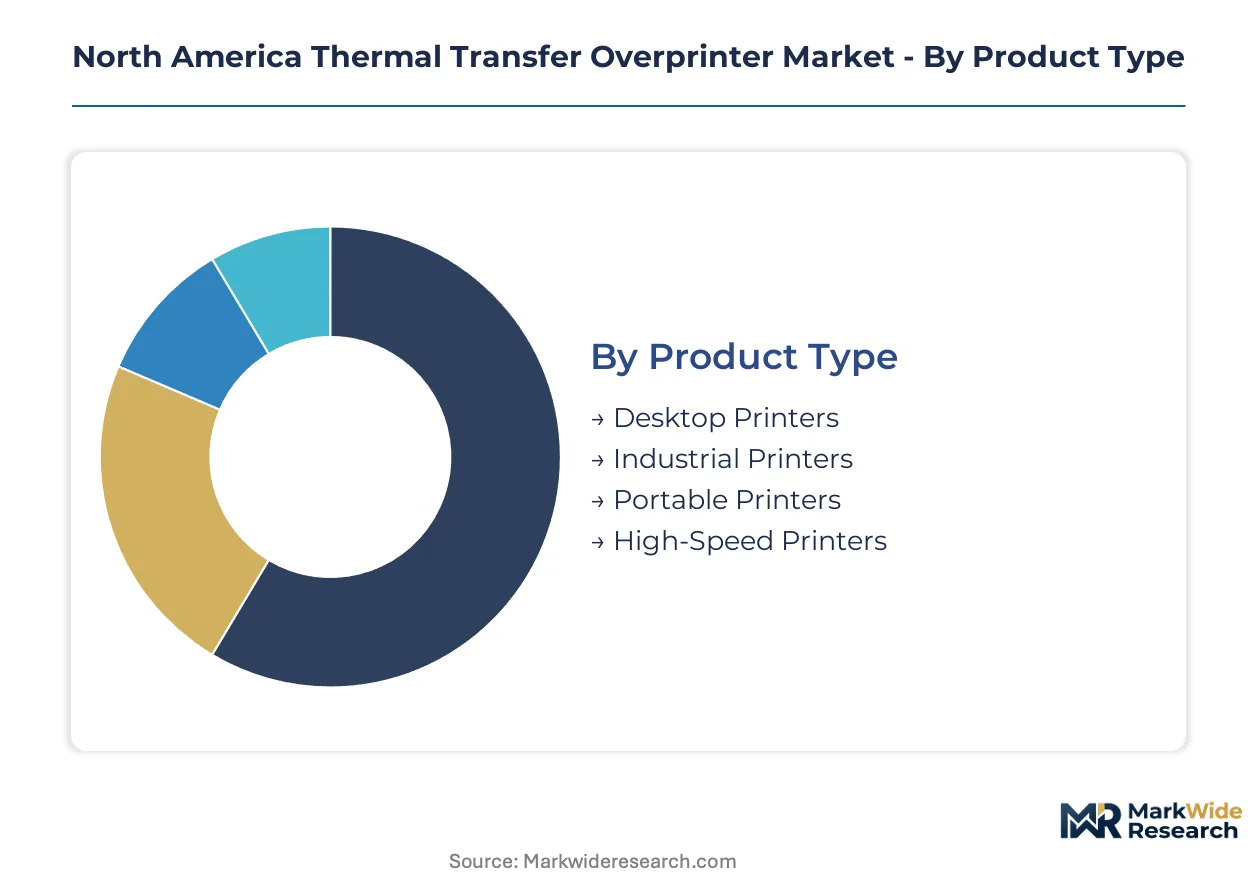
Thermal transfer overprinter segmentation reflects divergent margin economics across equipment tiers and compliance environments. Packagers configure procurement strategies around ribbon chemistry, printhead resolution, and integration complexity rather than hardware cost alone.
Product Type:
Industrial printers command the largest consumable revenue pools due to continuous high-volume deployment in dairy and snack operations.
- Industrial Printers:These systems integrate with form-fill-seal packaging machinery at speeds exceeding 600 mm per second. Midwest manufacturing corridors in Illinois, Ohio, and Michigan concentrate replacement demand for resin ribbons and ceramic printheads.
- High-Speed Printers:E-commerce fulfillment centers deploy these for variable box serialization with rapid throughput requirements. FDA track-and-trace mandates for pharmaceutical distribution are accelerating specifications for 300 dpi resolution and GS1-compliant barcode output.
- Desktop Printers:Regional meal kit fulfillment operations outside traditional manufacturing hubs favor compact footprints for personalized batch tracking.
- Portable Printers:Field service applications and mobile inventory management drive limited adoption in chemical packaging yards.
Industrial printers hold installed capacity. High-speed printers are rotating up the share rankings.
End User:
Application-specific compliance burdens create tiered pricing power across verticals.
- Food & Beverage:Dairy processors and snack manufacturers generate the highest ribbon consumption volumes. FSMA lot code and expiration date mandates force upgrades from legacy inkjet systems, though thin operating margins resist per-unit marking cost increases.
- Pharmaceuticals:Contract packaging organizations face DSCSA serialization deadlines requiring ISO 14644 clean-room validation. Documentation burdens extend project timelines by 8-14 weeks, but superior margin pools reward compliant equipment vendors.
- Electronics:Component traceability for counterfeit prevention drives modest demand in Mexican maquiladora operations.
- Consumer Goods:Personal care and household product labeling shows substitution pressure from laser marking for corrugated applications.
Food & Beverage anchors ribbon volume. Pharmaceuticals is climbing the fastest on value per installed unit.
Technology:
Print mechanism selection determines substrate compatibility and mark permanence in regulated environments.
- Thermal Transfer:Heated printheads melt wax or resin-based ink onto flexible films, labels, and corrugated cases with permanent moisture and abrasion resistance. FDA and EPA regulatory pressure favors this chemistry over solvent-based alternatives in food and chemical packaging.
- Direct Thermal:Chemical-coated substrates activate without ribbons, reducing consumable logistics for short-life applications like shipping labels.
- Full Color:Process ribbon sets enable brand-compliant graphics on premium food pouches with limited production scale.
- Hybrid Technology:Dual-mode systems switch between direct and transfer modes for converters serving mixed substrate portfolios.
Thermal Transfer dominates compliance-driven replacements. Hybrid Technology is gaining share fastest among mid-size converters seeking SKU reduction.
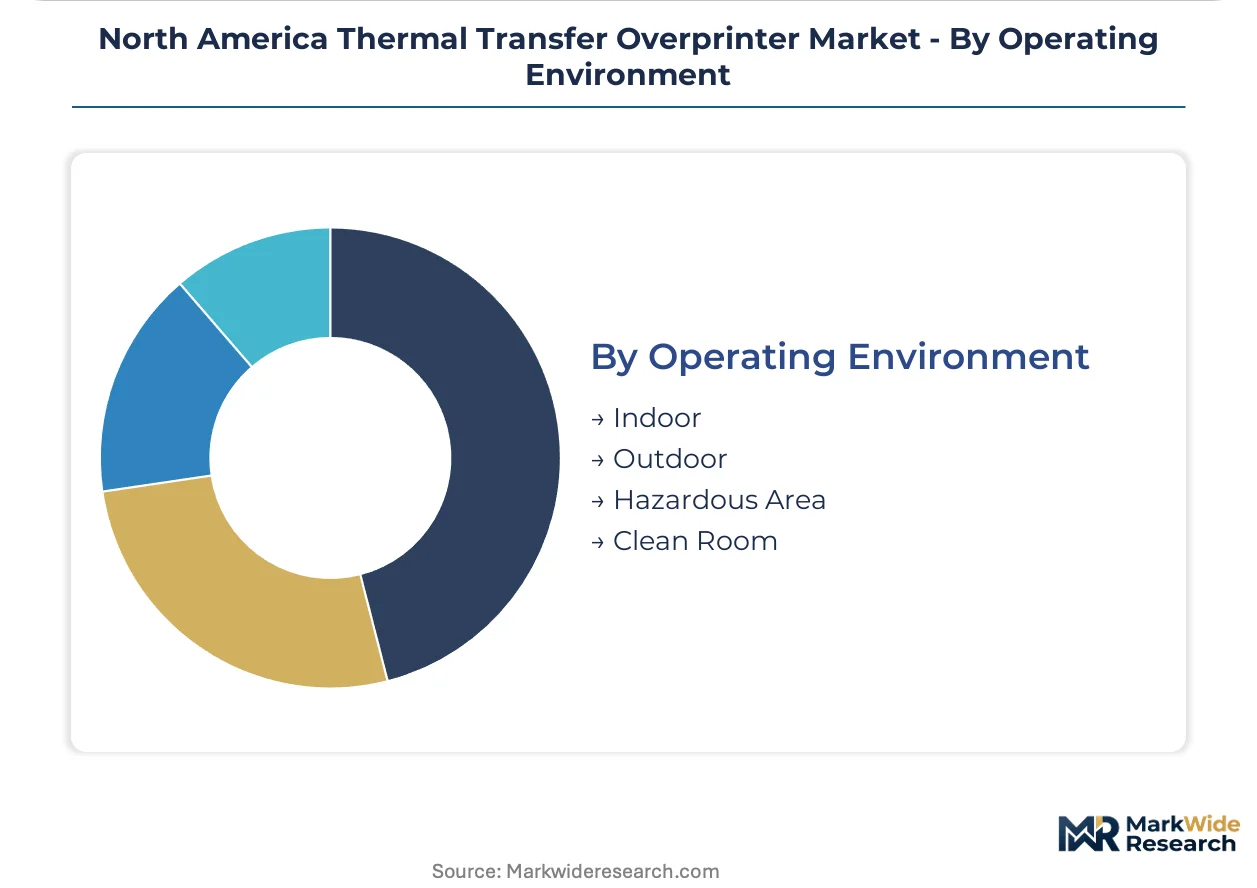
Operating Environment:
Certification requirements stratify supplier capabilities and field service economics.
- Indoor:Standard manufacturing floors represent the baseline installation category with minimal regulatory overlay.
- Clean Room:Pharmaceutical blister foil and medical device packaging demand ISO 14644 validation. Domino Printing Sciences and Videojet maintain specialized product lines with incompatible ribbon supplies for this segment.
- Hazardous Area:Chemical packaging plants in Texas and Louisiana require NFPA electrical safety codes and OSHA machine guarding standards that constrain supplier certification.
- Outdoor:Limited agricultural and construction material tagging applications face weathering durability requirements.
Indoor environments hold installed base. Clean Room is rotating up the share rankings on project value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision ceramic heating element production concentrates among Asian component suppliers, constraining North American printer OEM output planning. The Midwest manufacturing corridor spanning Illinois, Ohio, and Michigan anchors equipment demand. Regional procurement strategies diverge based on proximity to OEM service networks and state-level regulatory pressures.
United States
Food and beverage packaging lines across the Midwest and Southeast expand adoption to meet FDA traceability mandates for lot codes and expiration dates. The FDA's evolving Food Safety Modernization Act requirements pressure converters to upgrade from legacy inkjet systems. Illinois, Ohio, and Michigan food processing clusters generate concentrated equipment demand with proximity to OEM service networks reducing downtime risk.
Canada
Health Canada track-and-trace mandates for cannabis packaging create new demand for serialized labeling on flexible pouches. Provincial distribution monopolies standardize equipment specifications across Ontario, Quebec, and British Columbia. Clean-room installations in pharmaceutical contract packaging organizations face ISO 14644 validation timelines extending project completion.
Mexico
Component traceability for counterfeit prevention drives modest thermal transfer demand in electronics maquiladora operations near Tijuana and Ciudad Juárez. Mexican food processors serving US export markets adopt FDA-compliant marking equipment to maintain market access. Northern border states concentrate equipment installations aligned with cross-border supply chain requirements.
North America Thermal Transfer Overprinter Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the North American thermal transfer overprinter market. The vendor base stratifies into three tiers: European-headquartered specialists with clean-room certification depth, diversified industrial conglomerates with direct service network scale, and regional integrators focused on form-fill-seal machinery partnerships. Dominant competitive moves include strategic partnerships with packaging OEMs and geographic expansion through third-party service contract unbundling.
Among European-headquartered specialists, Domino Printing Sciences plc and Koenig & Bauer Coding GmbH occupy positions emphasizing pharmaceutical clean-room compliance and high-resolution printhead architecture. Videojet Technologies, Inc. anchors the diversified industrial tier with extensive direct service networks across the United States and Canada. ITW Diagraph exemplifies the machinery integration archetype through specialized positioning with form-fill-seal packaging lines common in dairy and snack operations.
| Leading Market Players |
|---|
| ID Technology, LLC |
| EDM Corporation |
| Domino Printing Sciences plc |
| Videojet Technologies, Inc. |
| ITW Diagraph |
| Hitachi Industrial Equipment Marking Solutions Inc. |
| Koenig & Bauer Coding GmbH |
| MULTIVAC |
| Squid Ink |
| Others |
Value Network & Pricing Analysis
FDA Food Safety Modernization Act compliance gates both supplier qualification and price differentiation simultaneously, forcing ribbon chemistry vendors to invest in food-contact certifications that separate premium resin formulations from commodity wax alternatives. Equipment OEMs pass these certification costs downstream while competing for pharmaceutical clean-room installations where ISO 14644 validation commands substantial pricing premiums over standard industrial configurations.
Pricing Analysis
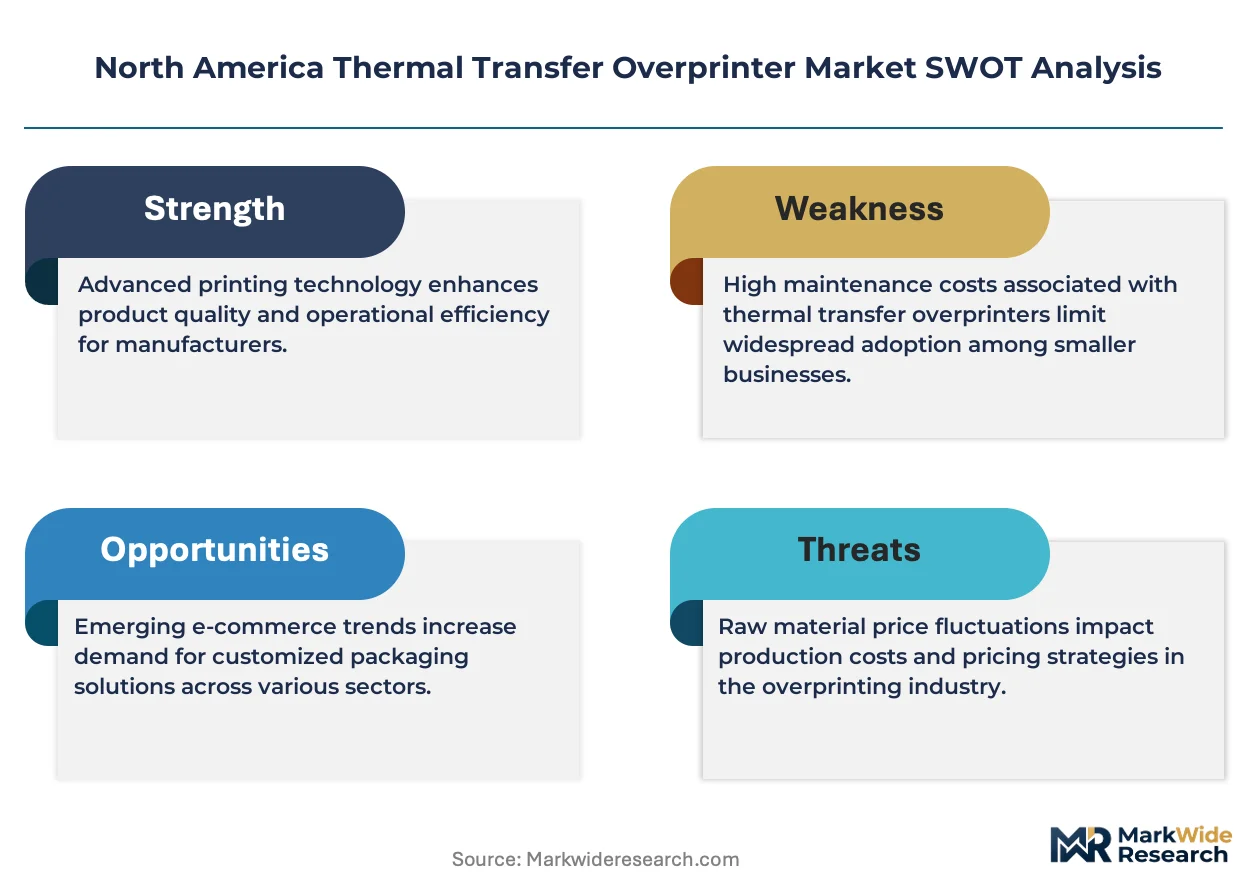
FDA Food Safety Modernization Act dictates the pricing tier structure across the North American thermal transfer overprinter market, separating pharmaceutical-grade clean-room systems from standard food-processing configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with pharmaceutical contract packagers showing least price sensitivity due to DSCSA compliance deadlines while dairy processors resist per-unit marking cost increases. Cost compression in resin ribbon supply is intensifying because petroleum-derived input volatility strains converter margins. Food and beverage manufacturers operating thin margin profiles demonstrate highest price sensitivity, particularly in Midwest manufacturing corridors where volume procurement negotiations concentrate leverage.
Supply Chain Analysis
Just-in-time ribbon replenishment dominates food and beverage operations where Midwest manufacturing corridors maintain proximity to OEM distribution hubs, while pharmaceutical contract packagers prefer strategic stockpiles of certified clean-room consumables to mitigate ISO 14644 validation delays. Precision ceramic heating element production concentrates in Japan, South Korea, and Taiwan, constraining North American printer OEM output planning. Raw material dependencies center on petroleum-derived resin coatings, precision-engineered ceramics, and specialty wax formulations. Single-source vulnerability in Asian component supply creates structural risk for printhead availability. Distribution runs through direct OEM service networks competing against third-party providers across Illinois, Ohio, and Michigan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America thermal transfer overprinter market sits in cyclical recovery as FDA enforcement waves for DSCSA and FSMA traceability mandates compress equipment replacement cycles. Regulatory compliance deadlines create predictable demand pulses that favor prepared suppliers.
For Market Incumbents: Secure captive supply agreements for precision ceramic heating elements to insulate against Asian component lead time volatility. Deepen backward integration into resin ribbon coating capacity to defend margin position against petroleum input cost swings. Fiber laser substitution for corrugated case applications threatens industrial printer installed base in e-commerce fulfillment centers. For New Entrants and Emerging Players: ISO 14644 clean-room certification fast-track opens pharmaceutical contract packaging where incumbent capacity constraints extend project timelines. Canadian cannabis packaging under Health Canada mandates represents most penetrable geography with standardized provincial specifications. Target meal kit fulfillment centers outside traditional manufacturing hubs with compact desktop printer footprints and personalized batch tracking software bundles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed packaging machinery integrators lacking thermal transfer printer technology depth. Five-to-ten year viability hinges on regulatory compliance tailwinds persisting through FDA food traceability rulemakings. Acquisition target archetype includes regional service providers with Midwest manufacturing corridor density. Signal to watch is California and New York extended producer responsibility legislation crossing implementation thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Room Certification Investment | ISO 14644 validation capability unlocks pharmaceutical contract packaging with superior margin pools. |
| Resin Ribbon Chemistry R&D | Wax-resin hybrid formulations reduce SKU complexity for mid-size converters serving mixed substrates. |
| Form-Fill-Seal Machinery Integration | Specialized partnerships with dairy and snack OEMs anchor recurring consumable revenue streams. |
| Third-Party Service Network Expansion | Unbundled maintenance contracts compete against Videojet direct service density in Midwest corridors. |
| Canadian Cannabis Market Entry | Health Canada track-and-trace mandates create serialized labeling demand with provincial standardization. |
Research Methodology
The analysis maps industrial printer, high-speed printer, desktop printer, and portable printer segments, each validated through packaging line engineers, maintenance directors at food processing facilities, pharmaceutical contract packaging procurement leads, and aftermarket service heads. Primary interviews with these stakeholders combined trade data from U.S. Census Bureau machinery imports, FDA warning letter databases for compliance-driven replacement timing, and SEC filings from diversified industrial conglomerates. Secondary sources included OSHA machine guarding enforcement records, NFPA electrical safety code adoption timelines, and state-level extended producer responsibility legislation trackers. Bottom-up equipment unit estimates triangulated against top-down consumable revenue pools.
Consistency checks validated volume and value outputs against external benchmarks including regional manufacturing employment data, packaging machinery shipment indices, and ribbon chemistry patent filings across the analysis window. Segmentation dimensions modeled include product type, end-user vertical, printhead resolution tier, operating environment certification, and geographic manufacturing cluster. CAGRs derived from regression analysis of historical replacement cycles overlaid with regulatory deadline impacts. Industry-specific forecast inputs encompassed FDA food traceability rulemaking progression and resin ribbon petroleum input cost indices.
Decision-makers should treat outputs as directional under assumptions of continued FDA enforcement intensity and stable Asian component supply; material deviation would warrant model refresh. Forecasts reflect base-case regulatory timelines and commodity input stability assumptions. Ribbon cost volatility, printhead supply disruption, or laser marking substitution acceleration constitute specific risk factors. Revision becomes warranted when Health Canada cannabis mandate expansion or state EPR legislation crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Digital Label Printers Market
Packaging Printing
Printed Boxes Market
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Soft Signage Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
North America Print Label Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Global Printing for Packaging Market
Packaging Printing
Label Printing Machines Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Flex Banner Market