
 Transient Analysis Software Market | 2026-2036
Transient Analysis Software Market Size, Share, and Industry Trends Forecast 2026-2036
Transient Analysis Software Market Analysis
Direct enterprise licensing is fragmenting as vendors introduce subscription tiers and cloud-native delivery. Ansys Inc. leverages extensive multiphysics integration to anchor high-end aerospace contracts. Dassault Systèmes competes through its 3DEXPERIENCE platform, which extends simulation workflows into collaborative design environments. MathWorks Inc. specializes in MATLAB-based transient toolkits that dominate academic and research institutions.
Transient analysis software computes time-domain responses of electrical, mechanical, and thermal systems to sudden perturbations, typically resolving dynamics at microsecond-to-millisecond granularity using numerical integration methods. Engineers deploy these tools to predict equipment stress, stability margins, and failure sequences before physical prototyping. Simulation tools command the largest revenue share among product types, though monitoring solutions embedded with edge analytics represent the fastest-expanding margin pool. Cloud computing deployments accelerate fastest among technology categories, while on-premises installations retain preference in defense and classified energy applications where data sovereignty constrains migration.
FDA software validation guidelines, EU Cybersecurity Act certification requirements, and NERC CIP reliability standards collectively elevate compliance costs for vendors serving critical infrastructure operators. The EU AI Act introduces additional scrutiny for autonomous diagnostic features embedded within predictive maintenance modules. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as platform consolidation reshapes procurement bargaining power.
Market Dynamics
Cloud-native delivery architectures are fragmenting traditional perpetual licensing models across the transient analysis software sector, forcing incumbents to rebuild revenue recognition frameworks around consumption-based metering and hybrid deployment topologies.
Growth Catalysts
- IEEE 1547 Interconnection Standards:North American power utilities must validate inverter transient responses against revised grid codes, mandating software procurement for compliance verification.
- Electric Vehicle Development Pipelines:Automotive OEMs in Germany embed real-time electromechanical simulation into battery management system design cycles.
- Edge Analytics Integration:Monitoring solutions now embed diagnostic algorithms directly at substations, expanding addressable hardware-software bundles.
Market Restraints
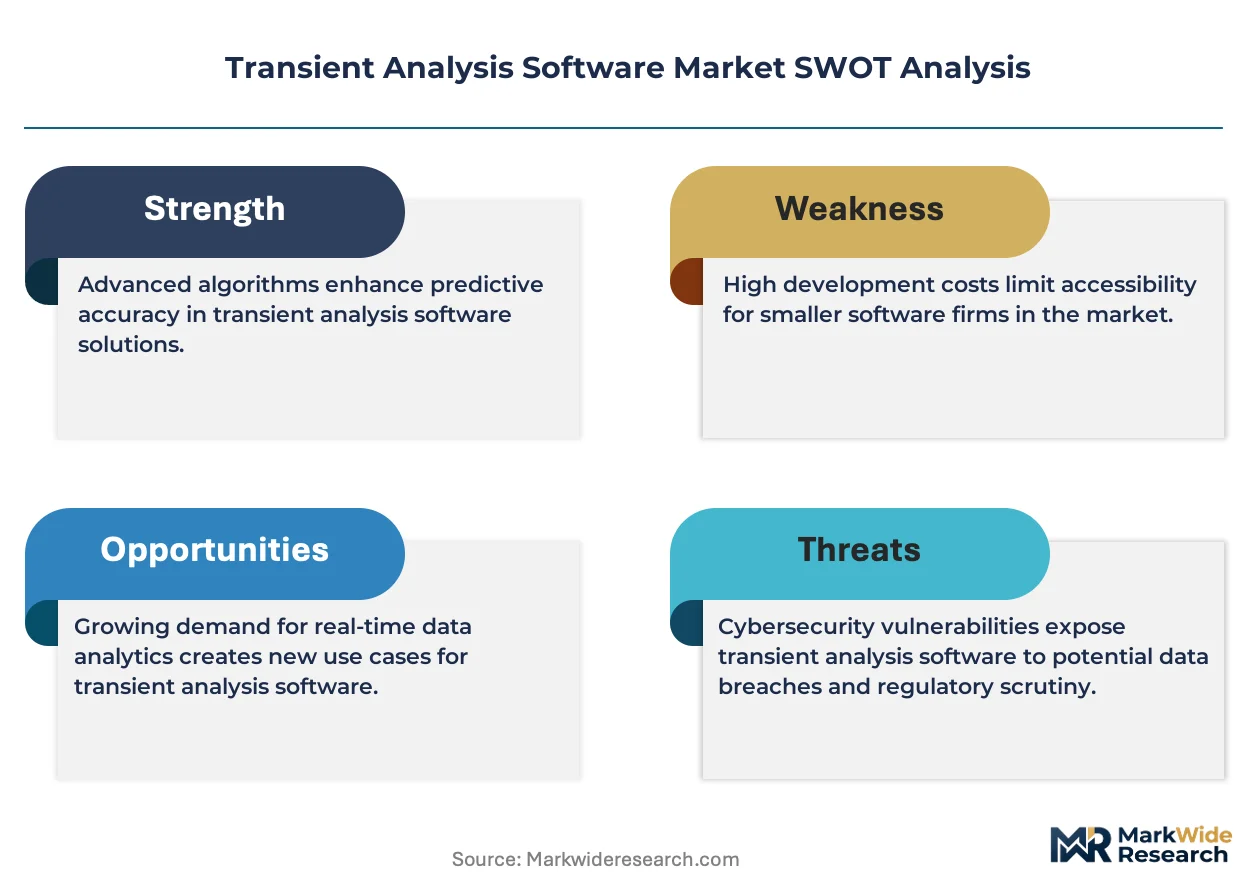
- Specialized Talent Scarcity:Numerical methods expertise for multiphysics coupling commands premium compensation, inflating implementation costs.
- Defense Sector Data Sovereignty:Classified energy applications in restricted facilities block cloud migration, bifurcating vendor R&D investment.
- Open-Source Solver Proliferation:Community-developed integration libraries erode pricing power for basic time-domain analysis modules.
Strategic Opportunities
- EU AI Act Diagnostic Modules:Autonomous predictive maintenance features face new conformity assessment pathways, creating first-mover certification advantages.
- Digital Twin Convergence:Coupling transient solvers with 3DEXPERIENCE-style collaborative environments opens aerospace system-of-systems contracts.
- India CEA Grid Modernization:Central Electricity Authority mandates for renewable integration drive software adoption among state transmission utilities.
Industry Challenges
- Multiphysics Coupling Expertise:Electromechanical-thermal co-simulation requires rare cross-domain competency, constraining project scalability.
- Legacy SCADA Integration:Decades-old utility control systems resist API standardization, extending deployment timelines.
- NERC CIP Compliance Burden:Critical infrastructure protection documentation adds 6-12 month procurement cycles for reliability-sensitive buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transient Analysis Software Market |
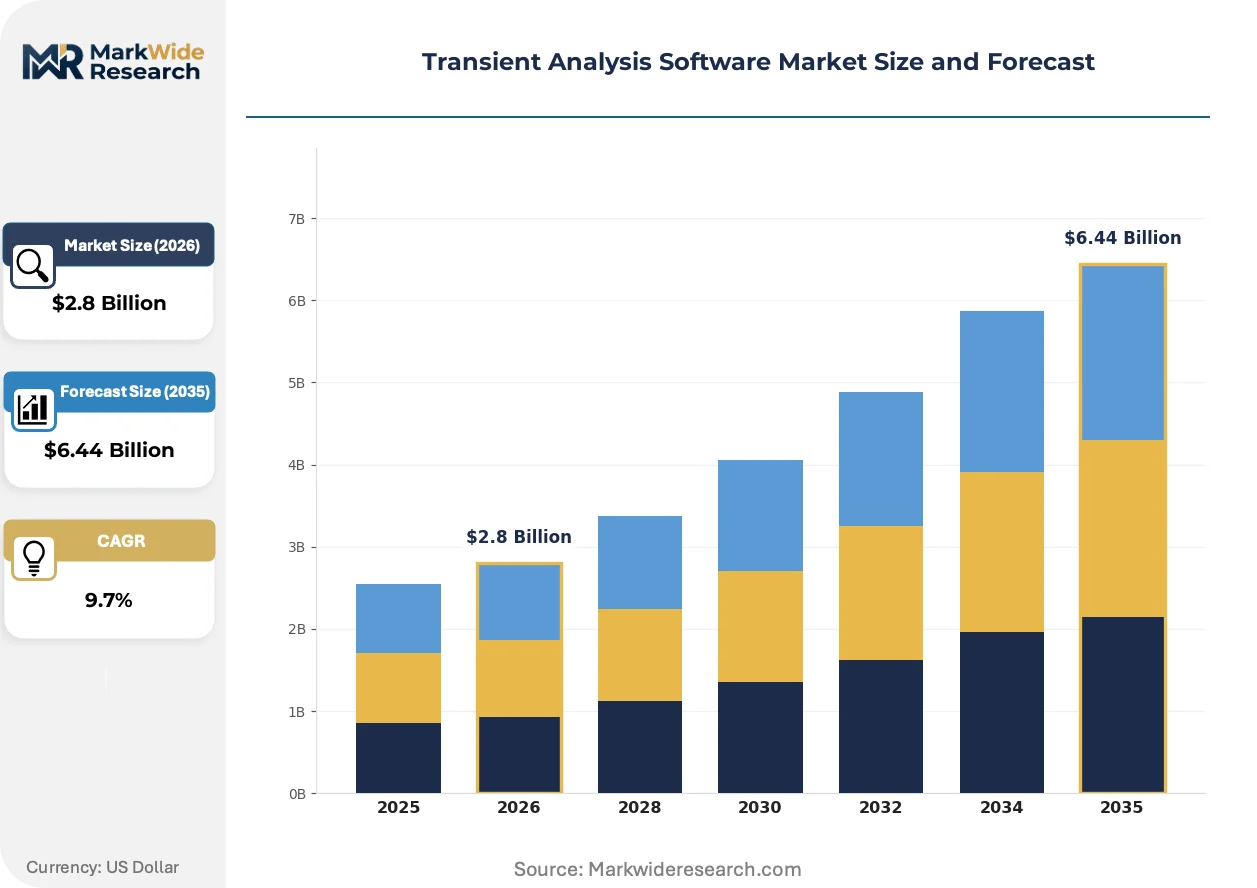
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Tools, Data Analysis Software, Monitoring Solutions, Visualization Platforms End User: Aerospace, Automotive, Energy, Manufacturing Technology: Cloud Computing, On-Premises, Hybrid Model, Embedded Systems Application: Research & Development, Performance Testing, Product Design, Educational Purposes |
| Companies Covered | Ansys Inc., Dassault Systèmes, Siemens Digital Industries Software, Altair Engineering Inc., Autodesk Inc., MathWorks Inc., Rockwell Automation Inc., Bentley Systems Incorporated, ESI Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transient Analysis Software Market Emerging Trajectories
Computational architectures and procurement frameworks are simultaneously transforming how transient analysis capabilities reach end-users, compressing traditional sales cycles while expanding functional boundaries.
GPU-accelerated time-domain solvers exploit parallel processing architectures to resolve microsecond-scale electromechanical transients in minutes rather than hours. Power electronics manufacturers in automotive and renewable sectors adopt these tools for design-of-experiments workflows. Deterministic simulation speed is rendering obsolete the hardware-in-the-loop testing rigs that previously dominated validation protocols.
EU Cybersecurity Act certification requirements now mandate third-party evaluation for software used in critical energy infrastructure. Vendors must submit transient analysis platforms to accredited conformity assessment bodies before EU member state deployment. German TSOs and French distribution operators currently face the steepest compliance timelines, with certification backlogs extending commercial launch windows.
Consumption-based licensing is displacing perpetual enterprise agreements across mid-market engineering departments. Subscription tiers tied to core-hour utilization allow smaller consultancies to access solver capacity previously reserved for capital-intensive procurement. This pattern concentrates in North American power sector consultancies serving municipal utilities with constrained software budgets.
Transient Analysis Software Market Segmentation
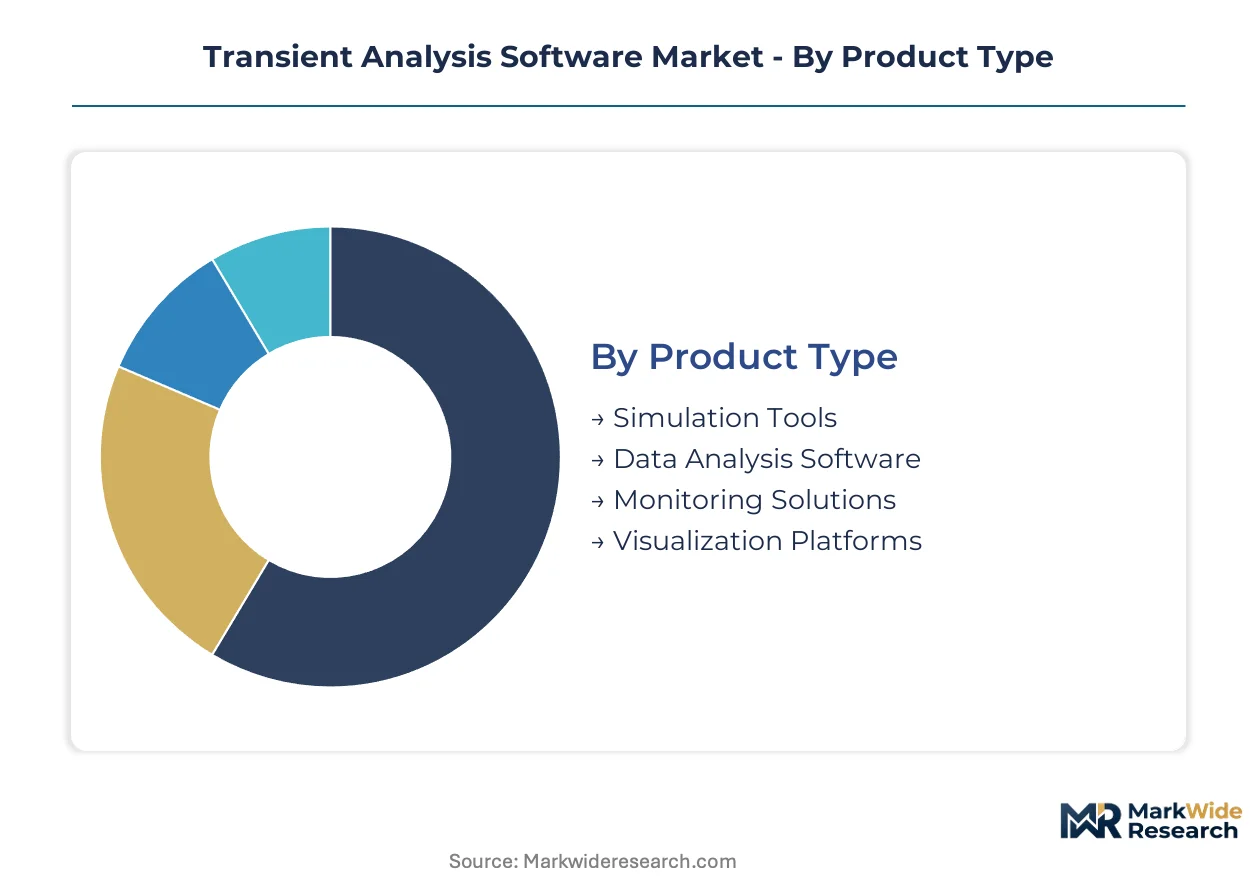
Transient analysis software serves sharply divergent operational requirements across product development, grid operations, and academic research. Segment boundaries reflect fundamental trade-offs between computational intensity, deployment flexibility, and regulatory compliance burdens.
Product Type:
Engineering teams select tools based on where they sit in the design-to-deployment lifecycle, from early-stage modeling through operational monitoring.
- Simulation Tools:Numerical integration engines resolve microsecond-scale electromechanical transients using finite element and circuit-based methods. Automotive battery management system designers in Germany deploy these for inverter switching validation under IEEE 1547 grid code requirements.
- Data Analysis Software:Post-processing suites extract stability margins and failure sequences from time-series outputs. Energy sector consultants in North America favor subscription-tier access to manage municipal utility procurement constraints.
- Monitoring Solutions:Edge-embedded diagnostic platforms now bundle hardware-software packages for substation deployment.
- Visualization Platforms:3D rendering environments integrate with collaborative design systems for aerospace system-of-systems contracts.
Established volume favors simulation tools; emerging adoption favors monitoring solutions.
End User:
Cost tiers stratify sharply between capital-intensive OEM engineering centers and budget-constrained consultancies.
- Aerospace:System-of-systems contracts demand multiphysics coupling across electromechanical, thermal, and structural domains. Dassault Systèmes anchors this segment through 3DEXPERIENCE platform integration for high-end contracts.
- Automotive:Real-time electromechanical simulation pipelines dominate electric vehicle development cycles. German OEMs embed transient solvers directly into battery management system design workflows.
- Energy:North American power grid utilities modernize aging infrastructure under revised interconnection standards. Cloud migration accelerates fastest here despite defense-sector data sovereignty constraints.
- Manufacturing:Process equipment stress analysis commands mid-market subscription licensing.
Defense procurement concentration favors aerospace; steepest expansion trajectory favors automotive.
Technology:
Customer type determines deployment topology—enterprise engineering departments versus distributed operational technology teams.
- Cloud Computing:GPU-accelerated solvers exploit parallel architectures to compress electromechanical transient resolution from hours to minutes. Consumption-based metering expands access for smaller consultancies previously locked out of capital-intensive procurement.
- On-Premises:Classified energy applications and defense facilities retain perpetual licensing due to data sovereignty requirements. NERC CIP compliance documentation extends procurement cycles substantially.
- Hybrid Model:Burst capacity for design-of-experiments workflows couples local preprocessing with cloud solver execution.
- Embedded Systems:Deterministic algorithms deploy directly at substations for autonomous diagnostic functions now facing EU AI Act conformity assessment.
Legacy preference favors on-premises; cloud-native delivery is displacing traditional perpetual licensing fastest.
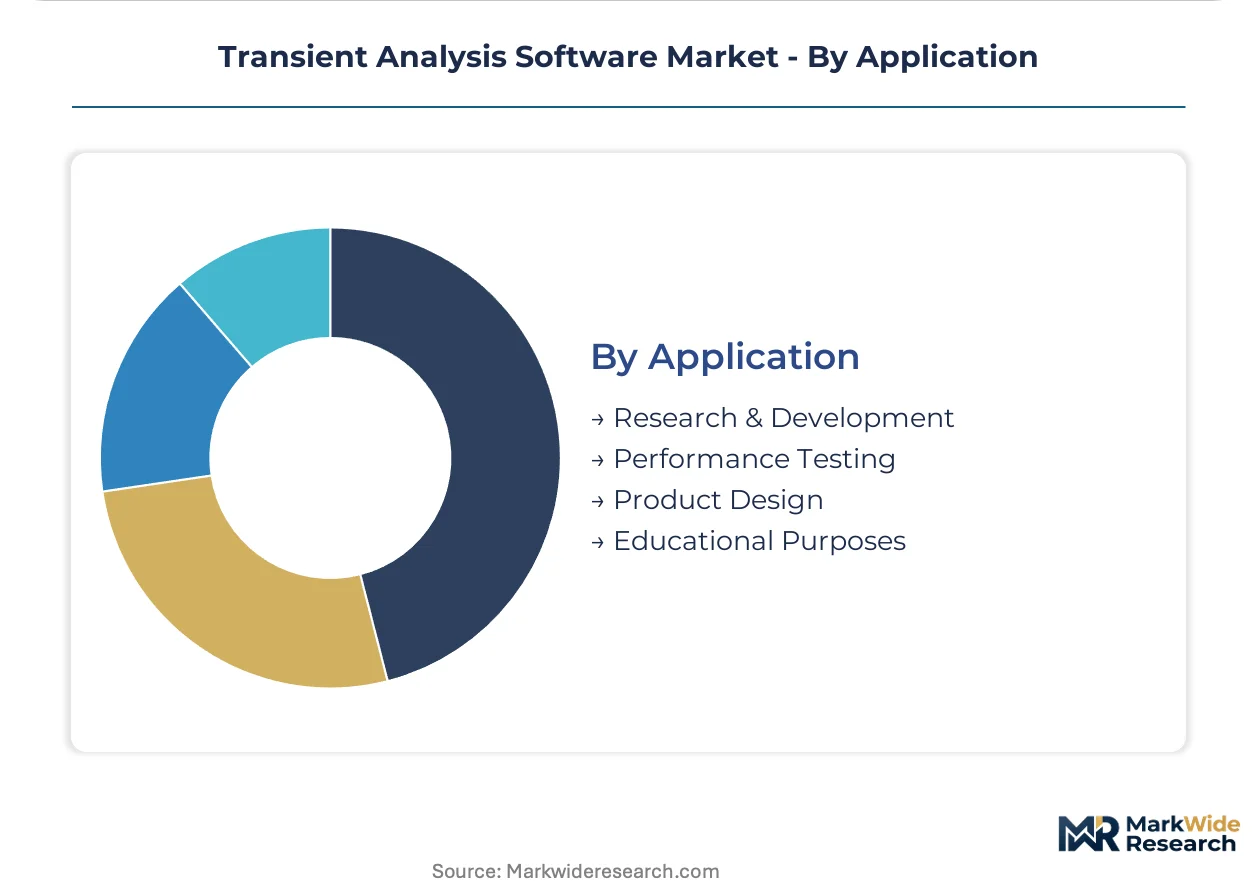
Application:
Maturity gradients separate established research workflows from emerging operational technology integration.
- Research & Development:MATLAB-based toolkits dominate academic and government laboratory procurement. MathWorks anchors this segment through institutional licensing networks.
- Performance Testing:Hardware-in-the-loop validation protocols face displacement from GPU-accelerated deterministic simulation speed improvements.
- Product Design:Multiphysics coupling requirements constrain project scalability due to rare cross-domain expertise.
- Educational Purposes:Open-source solver proliferation erodes pricing power for basic time-domain analysis modules in university settings.
Institutional entrenchment favors research and development; product design gains share fastest as digital twin convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pacific DC Intertie transmission corridor underwrites United States demand as West Coast utilities modernize aging infrastructure for renewable integration. Grid modernization mandates reshape procurement across multiple geographies.
United States
FERC Order 2023 interconnection reforms and NERC CIP reliability standards drive software procurement among regional transmission organizations. The California ISO and PJM Interconnection deploy transient solvers for inverter-based resource validation. Austin and Denver energy consultancies specialize in municipal utility compliance workflows.
Germany
Automotive OEMs embed real-time electromechanical simulation into electric vehicle battery management system design. The EU Cybersecurity Act mandates third-party certification for critical energy infrastructure software. Stuttgart and Munich engineering clusters concentrate development pipelines for power electronics manufacturers.
China
State Grid Corporation's ultra-high voltage transmission expansion requires transient stability analysis for multi-infeed HVDC systems. MIIT standards for smart grid equipment interoperability shape domestic vendor procurement. Yangtze River Delta manufacturing hubs integrate simulation tools into power converter design cycles.
India
CEA mandates for renewable integration drive adoption among state transmission utilities facing voltage stability challenges. The PLI scheme for advanced chemistry cell manufacturing attracts electrochemical simulation investment. Bengaluru and Hyderabad software development centers build domestic solver capabilities for grid operators.
Japan
METI carbon neutrality roadmaps accelerate offshore wind interconnection studies requiring electromagnetic transient analysis. JIS standards for power system protection equipment elevate compliance requirements for imported software. Tokyo and Nagoya engineering consultancies serve nuclear restart safety assessment workflows.
Transient Analysis Software Market Vendor Landscape
On the supply side, the industry is consolidating around platform ecosystems that bundle multiphysics solvers with collaborative design environments. Three archetypes dominate: integrated engineering software conglomerates, specialized simulation toolkits, and automation-hardware vendors extending into digital twins. M&A activity concentrates on GPU-accelerated solver startups and cloud-native deployment specialists. Strategic partnerships between software vendors and hyperscale cloud providers reshape delivery economics.
Within the integrated platform tier, Ansys Inc., Dassault Systèmes, and MathWorks Inc. occupy anchor positions representing distinct technical legacies. Ansys exemplifies the multiphysics convergence archetype through extensive solver integration. Dassault Systèmes represents collaborative environment expansion into aerospace system-of-systems contracts. MathWorks anchors academic and research institution procurement through institutional licensing networks for MATLAB-based toolkits.
| Leading Market Players |
|---|
| Ansys Inc. |
| Dassault Systèmes |
| Siemens Digital Industries Software |
| Altair Engineering Inc. |
| Autodesk Inc. |
| MathWorks Inc. |
| Rockwell Automation Inc. |
| Bentley Systems Incorporated |
| ESI Group |
| Others |
Supply Flow & Price Mechanics
The Pacific DC Intertie transmission corridor's freight economics compress margin structures for hardware-software bundle vendors serving West Coast utilities, concentrating pricing power among solver developers with captive GPU cloud capacity while forcing tiered differentiation across municipal, enterprise, and defense procurement segments.
Pricing Analysis
Volume-discount tiering structures stratify across three performance levels: premium perpetual licenses for aerospace system-of-systems contracts, standard subscription tiers for automotive OEM electromechanical pipelines, and economy SaaS metering for North American municipal utility consultancies. Price differentiation hinges on certification grade—EU Cybersecurity Act and NERC CIP compliance documentation adds substantial cost—and volume scale, with core-hour consumption models expanding access for smaller engineering departments. Pricing pressure stems from open-source solver proliferation eroding basic time-domain module margins. Municipal utility consultancies exhibit highest price sensitivity; defense-sector buyers with data sovereignty constraints show lowest.
Supply Chain Analysis
Upstream feedstock for GPU-accelerated solver capacity draws from Taiwan Semiconductor Manufacturing for advanced node chips, South Korea's SK Hynix for HBM memory stacks, and NVIDIA's domestic packaging facilities. Raw material dependencies center on rare earth elements for power electronics substrates, high-purity silicon for semiconductor fabrication, and specialized cooling fluids for data center infrastructure. Single-source vulnerability concentrates in advanced GPU foundry capacity. Distribution runs through hyperscale cloud provider marketplaces and direct enterprise sales teams serving defense and classified energy facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transient analysis software sits in early-cycle expansion as IEEE 1547 interconnection reforms and EU AI Act diagnostic module requirements create compliance-driven procurement tailwinds across North American and European power utilities.
For Market Incumbents: Pre-empt open-source solver erosion by embedding proprietary multiphysics coupling IP into cloud-native platforms with consumption-based metering. Anchor high-end aerospace contracts through 3DEXPERIENCE-style collaborative environment integration. Invest in EU Cybersecurity Act pre-certification to capture German TSO and French distribution operator procurement windows ahead of compliance backlogs.
For New Entrants and Emerging Players: Build out GPU-accelerated deterministic simulation capabilities targeting mid-market automotive battery management system designers in Germany's Stuttgart and Munich clusters. White-space concentration sits in edge-embedded diagnostic platforms for Indian state transmission utilities facing CEA renewable integration mandates. Go-to-market through hyperscale cloud marketplace listings to bypass capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: Carve-out targets emerge from industrial automation conglomerates divesting non-core simulation assets; mid-cap solver specialists with captive GPU optimization IP command strategic scarcity value. Long-term viability favors platforms with hybrid deployment topology supporting both cloud-native delivery and air-gapped defense installations. Watch for inflection in India CEA enforcement intensity as renewable penetration thresholds trigger mandatory stability analysis procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Ansys Inc. anchors aerospace contracts through multiphysics solver convergence with collaborative design environments. |
| Acquisition of Specialist Firm | GPU-accelerated solver startups with deterministic electromechanical capabilities attract automation-hardware vendor interest. |
| Strategic Partnership | MathWorks Inc. extends MATLAB-based toolkit reach through hyperscale cloud provider marketplace distribution. |
| Geographic Expansion | Dassault Systèmes targets Indian state transmission utilities through Bengaluru engineering center localization. |
| Product Launch | EU AI Act-compliant autonomous diagnostic modules create first-mover certification advantages for predictive maintenance vendors. |
Methodological Framework
Operator-level perspectives from utility planning officers, automotive battery management system engineers, power electronics procurement leads, and hyperscale cloud platform engineers anchored the qualitative base. Primary interviews combined with secondary validation from FERC Order 2023 filings, IEEE 1547 revision documentation, EU Cybersecurity Act conformity assessment records, and CEA grid modernization circulars. Bottom-up solver deployment counts triangulated against top-down addressable spend estimates across aerospace, automotive, energy, and manufacturing verticals.
Scenario-bracketing framed projections across the analysis window, modeling deployment model segmentation by cloud-native, on-premises, hybrid, and embedded topologies alongside organization size tiers and regional regulatory clusters. CAGRs derived from solver capacity expansion curves, cloud marketplace transaction velocity, and compliance mandate enforcement timelines. Forecast inputs incorporated GPU compute cost decline trajectories and NERC CIP procurement cycle duration assumptions.
Stress conditions across hyperscaler GPU availability, EU AI Act certification backlog duration, and open-source solver feature parity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding IEEE 1547 enforcement intensity and India PLI scheme continuation. Cross-checking against hyperscale cloud provider capex disclosures and utility R&D expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Video Editing Software Market
Software & Services
Email Optimization Software Market
Software & Services
Software Market
Software & Services
Output Management Software Market
Software & Services
Procurement Software Market
Software & Services
Global Business Software and Service Market
Software & Services
Stock Media Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Enterprise Search Software Market
Software & Services
Global Auto Dealer Software Market
Software & Services
Over-The-Air Software Update Market
Software & Services
Global Integration Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Sales Gamification Software Market
Software & Services
Asia-Pacific IT Services Market