
 Global Electrical Computer-Aided Design (ECAD) Market | 2026-2036
Global Electrical Computer-Aided Design (ECAD) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrical Computer-Aided Design (ECAD) Market Foresight
Buyer concentration among semiconductor developers and aerospace engineers is consolidating around vendors offering unified PCB design and signal integrity analysis workflows. Cadence Design Systems leverages deep integration between its analog and digital design suites to anchor relationships with tier-one chipmakers. Siemens EDA sustains competitive positioning through manufacturing-scale partnerships that bridge design data directly into fabrication workflows. Synopsys differentiates by extending silicon-proven IP libraries into ECAD environments, reducing validation cycles for complex multi-domain projects.
Electrical Computer-Aided Design (ECAD) denotes software systems that generate, modify, analyze, and document electrical schematics, printed circuit board layouts, and wiring harness geometries using parameterized component libraries and constraint-driven routing engines operating at sub-micron tolerances. These tools serve the primary industrial purpose of compressing development cycles while ensuring electromagnetic compatibility and manufacturability across increasingly dense electronic assemblies. Cloud-based platforms now lead technology adoption as distributed engineering teams demand concurrent access to centralized design repositories, while desktop solutions retain dominance in defense and classified aerospace programs where air-gapped security protocols prevail. Within applications, PCB design occupies the largest revenue pool due to universal deployment across consumer electronics and telecommunications infrastructure, whereas fiber optic networks represent the fastest-expanding segment driven by data center interconnect upgrades and 5G backhaul expansion.
The EU AI Act and CE marking frameworks in Europe, alongside FDA software validation requirements for medical device electronics in the United States, are elevating traceability and auditability standards within ECAD tool specifications. These regulatory pressures compel vendors to embed automated documentation pipelines and version-controlled approval workflows directly into design environments rather than treating compliance as a post-process overlay. Stakeholders must monitor how emerging cybersecurity certification schemes for connected industrial equipment reshape library component sourcing and cross-border collaboration protocols.
Market Dynamics
Semiconductor developers are compressing design cycles through multi-domain system modeling, forcing ECAD vendors to unify analog, digital, and thermal analysis within single environments rather than permitting tool fragmentation across engineering handoffs.
Growth Catalysts
- EU AI Act compliance mandates:The EU AI Act and CE marking requirements are compelling vendors to embed automated documentation pipelines and version-controlled approval workflows directly into design environments, eliminating post-process compliance overlays.
- Data center interconnect upgrades:Fiber optic networks represent the fastest-expanding application segment as 5G backhaul expansion and hyperscale facility construction drive demand for signal integrity tools operating at terabit speeds.
- German automotive electronics clusters:Engineering concentration around Stuttgart and Munich anchors premium tool procurement, with tier-one suppliers mandating ECAD platforms capable of ISO 26262 functional safety traceability.
Market Restraints
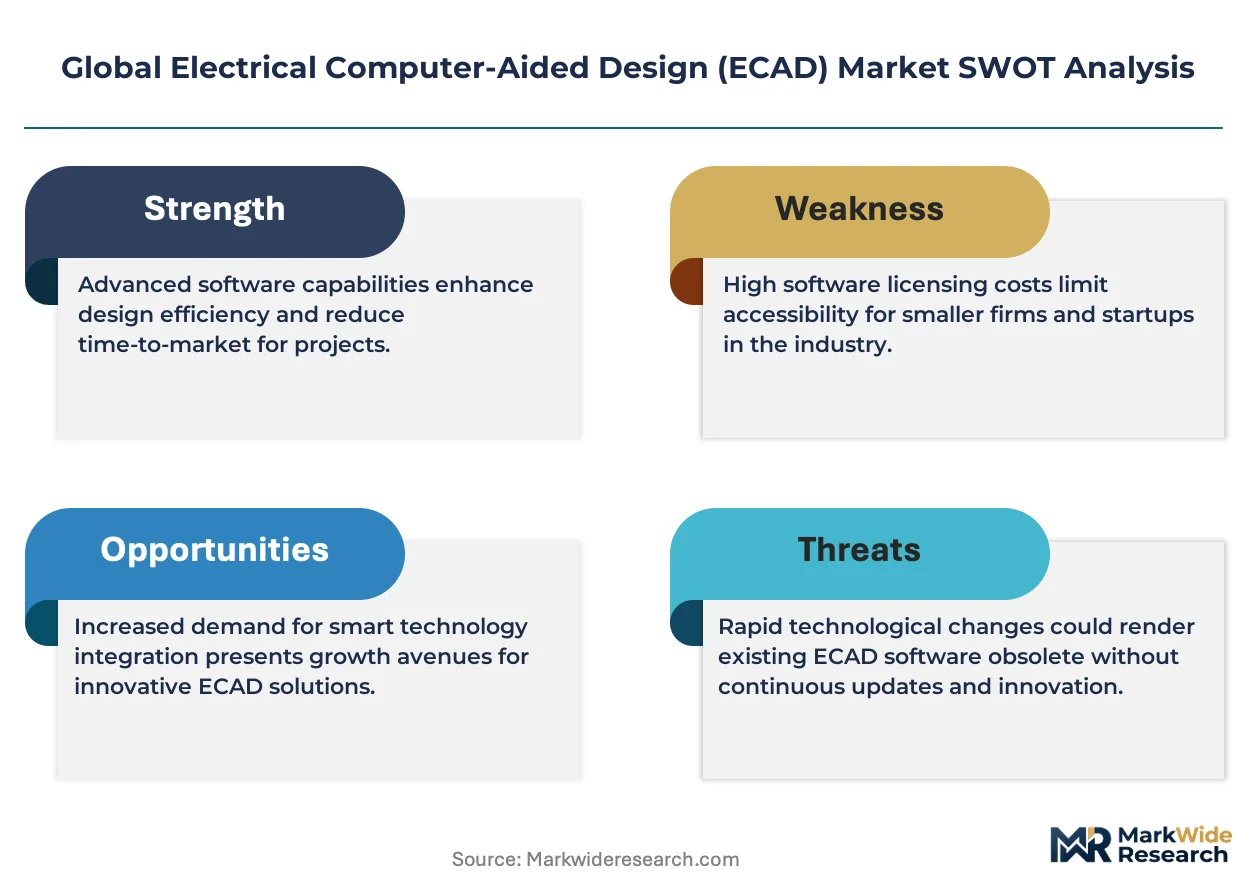
- Specialized talent scarcity:Electromagnetic compatibility simulation expertise concentrates among aging engineers in Germany and Japan, constraining deployment velocity for advanced constraint-driven routing engines.
- Cloud security protocols:Defense and classified aerospace programs in the United States enforce air-gapped security requirements that block cloud-based platform adoption, segmenting the market between secure desktop and commercial cloud workflows.
- Legacy library incompatibility:Decades of proprietary component formats across Siemens EDA, Cadence, and Synopsys environments create friction when consolidating design data from acquired engineering teams or supplier networks.
Strategic Opportunities
- India electronics manufacturing expansion:Production-linked incentive schemes and semiconductor fabrication investments in Gujarat and Tamil Nadu are generating first-time ECAD demand among domestic contract manufacturers previously dependent on offshore design services.
- Digital twin convergence:Integration between ECAD layouts and manufacturing execution systems is expanding into real-time thermal monitoring, enabling predictive maintenance for high-reliability industrial controllers.
- FDA software validation pathways:Streamlined premarket submission frameworks for medical device electronics are reducing compliance timeline uncertainty, encouraging venture investment in diagnostic imaging and patient monitoring hardware startups.
Industry Challenges
- Cross-functional simulation expertise:Chip-package-board co-design requires engineers fluent in both semiconductor physics and mechanical thermal analysis, a combination rarely cultivated in traditional electrical engineering curricula.
- IP licensing fragmentation:Silicon-proven libraries from multiple vendors carry conflicting usage restrictions that complicate multi-source procurement strategies for complex system-on-module designs.
- Supply chain provenance verification:Cybersecurity certification schemes for connected industrial equipment are reshaping component sourcing protocols, requiring traceable documentation from library creation through fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrical Computer-Aided Design (ECAD) Market |
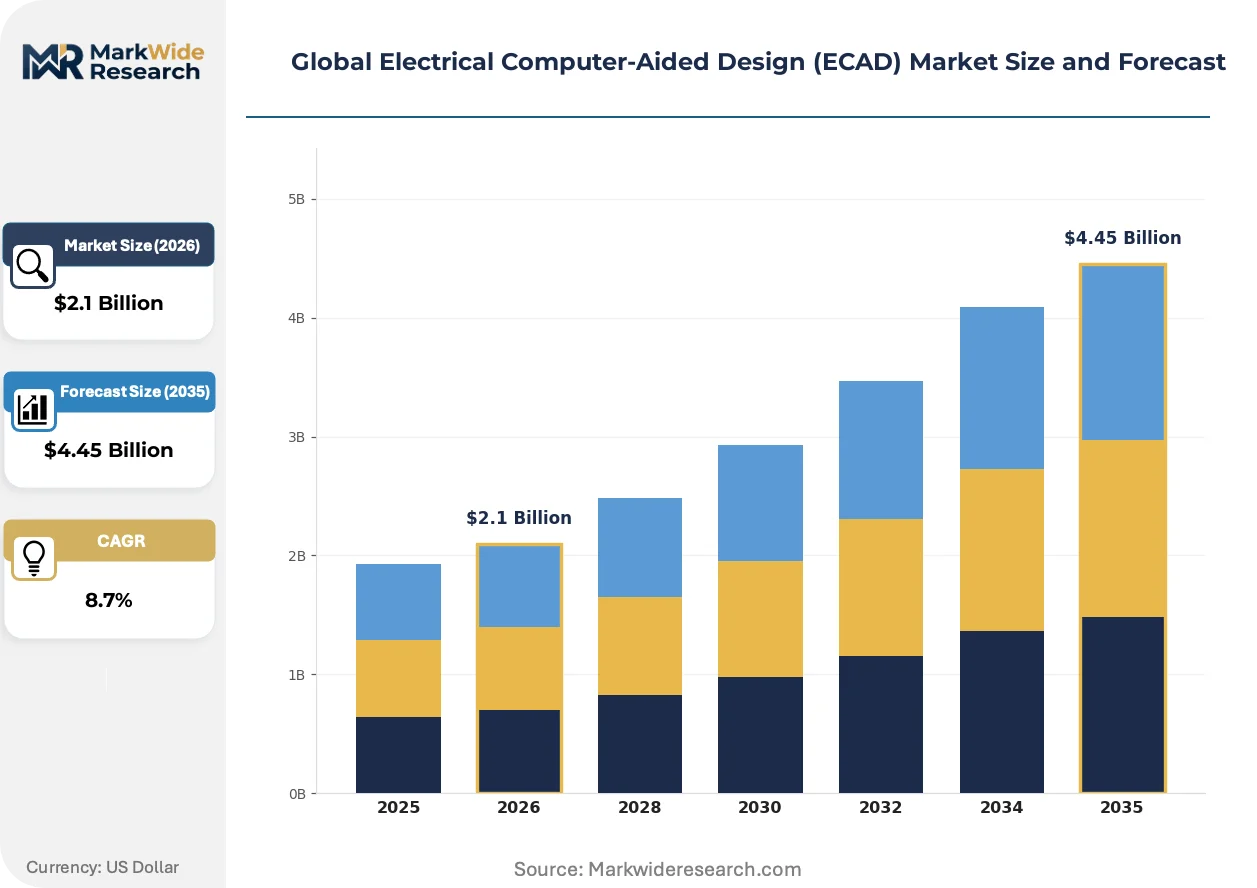
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Tools, Design Templates, Simulation Modules, Analysis Software, Configuration Packages Technology: Cloud-Based Platforms, Desktop Solutions, Hybrid Environments, SaaS Applications, On-Premise Systems Application: PCB Design, Wiring Harness Engineering, Multi-Domain System Modeling, Signal Integrity Analysis, Fiber Optic Networks End User: Electronics Manufacturers, Aerospace Engineers, Telecommunication Firms, Consumer Electronics, Semiconductor Developers |
| Companies Covered | Altium, Keysight Technologies, Cadence Design Systems, Aldec, ANSYS, Synopsys, Zuken, Pulsic, Siemens EDA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrical Computer-Aided Design (ECAD) Market Shifts & Advancements
Cloud-native architectures are displacing monolithic desktop installations as distributed engineering teams demand concurrent access to centralized design repositories, while regulatory traceability requirements reshape how compliance documentation is generated and archived.
Constraint-driven routing engines with machine learning-assisted pathfinding are expanding into high-density interconnect designs previously requiring manual intervention. Automotive tier-one suppliers in Germany and Japan are adopting these tools at accelerated pace to meet functional safety deadlines. This capability compression is collapsing the boundary between schematic capture and manufacturing-ready layout, reducing engineering revision cycles.
REACH substance restrictions and RoHS amendments in Europe are forcing component library updates to flag restricted materials before they enter production workflows. Industrial consequence includes mandatory supplier requalification for aerospace and medical device segments. Medical electronics manufacturers in Ireland and Switzerland are responding by integrating automated material declaration parsers directly into part selection interfaces.
Subscription licensing models are displacing perpetual seat purchases among mid-market electronics firms, particularly in South Korea and Taiwan where contract manufacturers prioritize operational expenditure flexibility over capital deployment. Channel disruption is most visible among value-added distributors who previously bundled training and support with one-time software sales, now pivoting toward implementation consulting and managed cloud hosting services.
Global Electrical Computer-Aided Design (ECAD) Market Segmentation
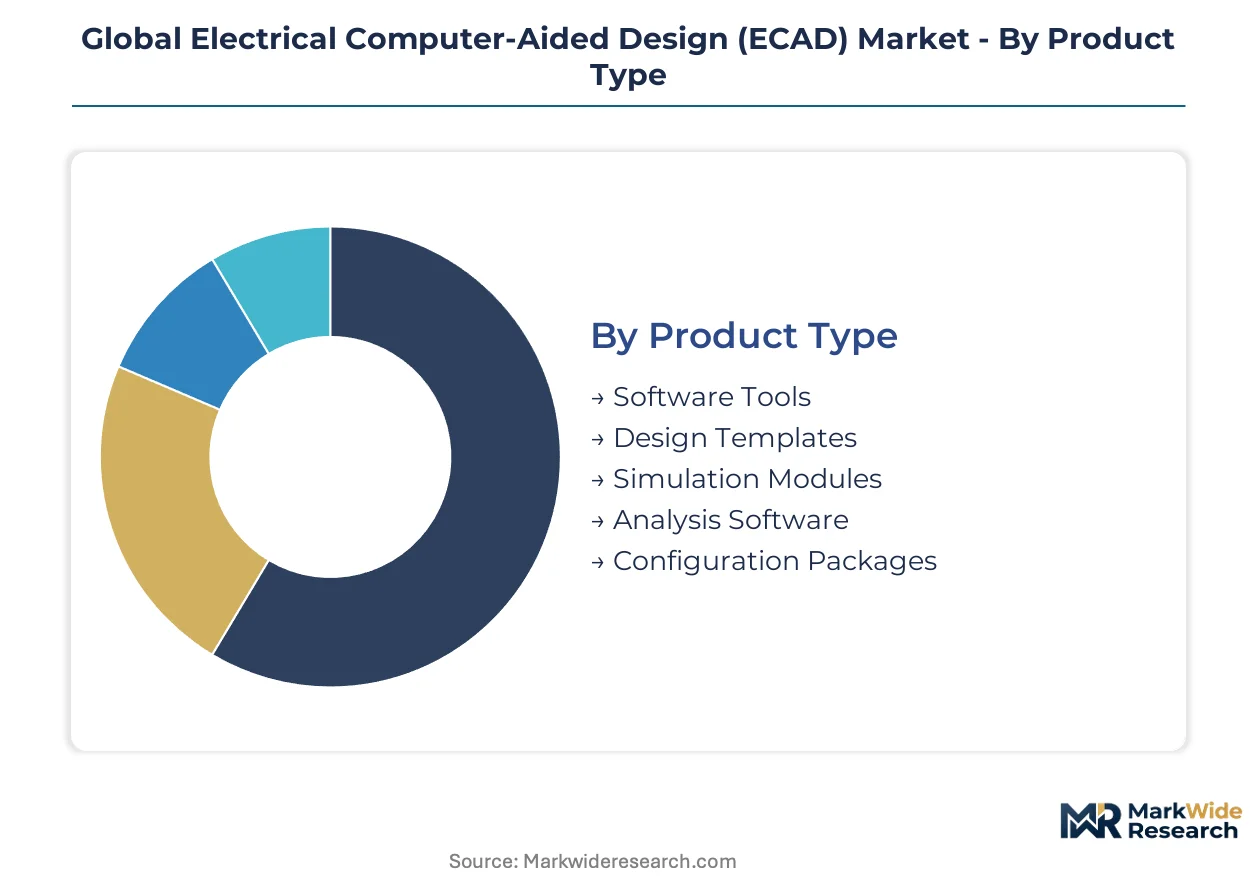
ECAD market segmentation reveals how tool architectures align with divergent security protocols, collaboration models, and regulatory traceability requirements across defense, automotive, and consumer electronics verticals. Understanding these divides clarifies why cloud-native platforms penetrate commercial segments while air-gapped desktops retain aerospace dominance.
Product Type:
Standalone software modules serve discrete engineering functions, whereas integrated suites embed compliance documentation and version control for regulated industries.
- Software Tools:Core schematic capture and PCB layout environments with parameterized component libraries and constraint-driven routing engines. Demand concentrates among semiconductor developers in Taiwan and South Korea compressing analog-digital integration cycles. Cadence and Synopsys anchor procurement through silicon-proven IP integration.
- Simulation Modules:Electromagnetic compatibility and thermal analysis engines operating at sub-micron tolerances. German automotive electronics clusters around Stuttgart drive premium adoption for ISO 26262 functional safety validation.
- Design Templates:Pre-configured project frameworks accelerating schematic development for common circuit topologies.
- Analysis Software:Signal integrity and power distribution verification tools for high-speed interconnect designs.
- Configuration Packages:Bundled tool suites with customized library sets and enterprise workflow integration.
Volume placements concentrate in Software Tools; the faster expansion belongs to Simulation Modules.
Technology:
Deployment architecture determines accessibility for distributed teams versus security isolation for classified programs, with cost structures shifting from capital expenditure to operational models.
- Cloud-Based Platforms:Centralized repositories enabling concurrent engineering access with automated backup and version control. Contract manufacturers in Vietnam and Mexico adopt these for operational expenditure flexibility under production-linked incentive schemes.
- Desktop Solutions:Air-gapped installations meeting NHTSA and FAA security protocols for defense electronics. United States aerospace programs in California and Texas mandate these for ITAR-controlled designs.
- Hybrid Environments:Mixed deployments bridging on-premise security with cloud collaboration for non-classified subsystems.
- SaaS Applications:Subscription-licensed browser tools reducing upfront capital deployment for mid-market firms.
- On-Premise Systems:Enterprise-hosted servers with internal security governance for medical device manufacturers facing FDA software validation requirements.
Revenue weight sits with Cloud-Based Platforms; Desktop Solutions retain the highest per-seat pricing.
Application:
Functional use cases span from universal PCB development to specialized fiber optic infrastructure, with complexity thresholds dictating tool sophistication and compliance depth.
- PCB Design:Universal printed circuit board development across consumer electronics and telecommunications infrastructure. Electronics manufacturers in Shenzhen and Bangalore generate sustained volume for schematic-to-layout workflows.
- Fiber Optic Networks:Signal integrity tools for terabit-speed data center interconnect and 5G backhaul expansion. Hyperscale facility construction in Ireland and the Netherlands drives the steepest expansion trajectory.
- Wiring Harness Engineering:Automotive and aerospace electrical distribution system design with mechanical integration constraints.
- Multi-Domain System Modeling:Unified thermal, electrical, and mechanical analysis for chip-package-board co-design.
- Signal Integrity Analysis:High-speed digital verification for memory interfaces and serial links in server and networking equipment.
Deployment scale favors PCB Design; fiber optic applications are climbing the fastest.
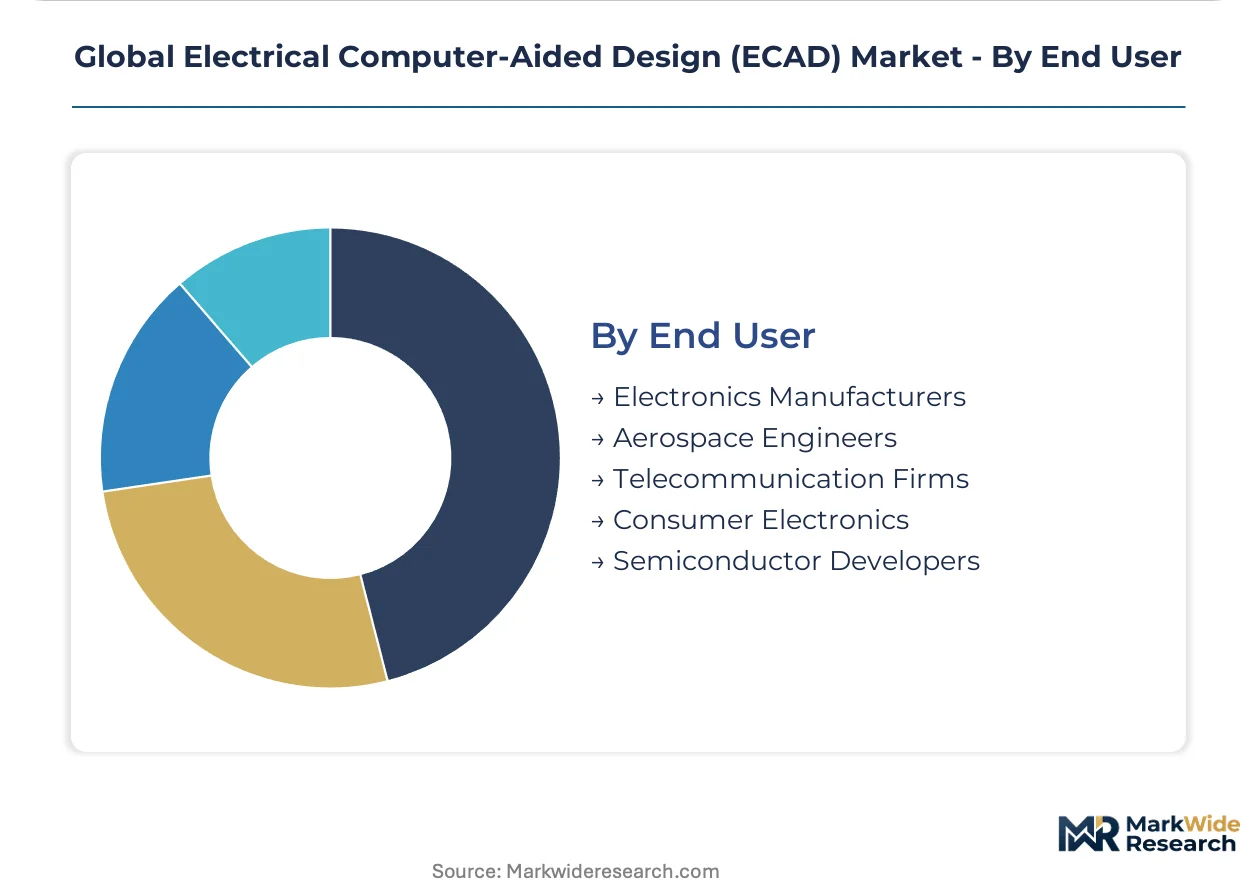
End User:
Customer archetypes range from high-volume contract manufacturers to safety-critical system developers, with procurement authority and compliance burden varying sharply.
- Semiconductor Developers:Tier-one chipmakers requiring unified analog-digital-thermal environments for multi-domain system modeling. TSMC and Samsung Foundry procurement standards dictate tool selection across their design ecosystem partners.
- Aerospace Engineers:Defense and commercial aviation specialists mandating traceability documentation for FAA certification. Engineering teams in Toulouse and Seattle prioritize tools with embedded configuration management.
- Electronics Manufacturers:Contract assembly firms serving consumer and industrial equipment markets with cost-optimized tool selections.
- Telecommunication Firms:Network equipment vendors integrating ECAD with manufacturing execution systems for base station and router production.
- Consumer Electronics:Smartphone and wearable device developers prioritizing rapid iteration cycles and component miniaturization.
Procurement volume aggregates in Electronics Manufacturers; Semiconductor Developers command the highest per-license investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication investments and automotive electronics engineering clusters concentrate procurement authority across Germany, the United States, South Korea, Taiwan, and India. Each geography shapes distinct compliance and deployment requirements for ECAD vendors.
Germany
Automotive tier-one suppliers around Stuttgart and Munich mandate ISO 26262 functional safety traceability in ECAD procurement. The EU AI Act and CE marking frameworks compel embedded documentation pipelines. Engineering concentration in Baden-Württemberg drives premium tool adoption for multi-domain system modeling.
United States
Defense electronics programs in California and Texas enforce air-gapped security protocols blocking cloud adoption. The FDA software validation requirements for medical device electronics elevate auditability standards. Aerospace engineering clusters in Seattle and Southern California prioritize configuration management integration.
South Korea
Contract manufacturers prioritize operational expenditure flexibility through subscription licensing models. Samsung Foundry procurement standards dictate tool selection across the domestic design ecosystem. Seoul Capital Area electronics firms compress analog-digital integration cycles.
Taiwan
TSMC and its ecosystem partners anchor high-volume ECAD demand for advanced node chip design. The concentration of semiconductor developers drives unified environment requirements. Hsinchu Science Park engineering teams mandate silicon-proven IP integration.
India
Production-linked incentive schemes and fabrication investments in Gujarat and Tamil Nadu generate first-time domestic demand. BIS standards and import substitution policies reshape procurement patterns. Bangalore and Hyderabad electronics manufacturing clusters transition from offshore design dependence to captive ECAD deployment.
Global Electrical Computer-Aided Design (ECAD) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and mid-market subscription penetration. The vendor base clusters around three archetypes: integrated suite providers with manufacturing-scale partnerships, specialized simulation module vendors with electromagnetic compatibility depth, and cloud-native challengers targeting distributed engineering teams. Consolidation pressure intensifies as chip-package-board co-design requirements collapse traditional tool boundaries. Dominant competitive moves include strategic partnerships bridging design-to-fabrication workflows and portfolio diversification into thermal analysis and signal integrity modules.
Within the integrated suite tier, Cadence Design Systems and Synopsys exemplify archetypes anchoring tier-one semiconductor relationships through deep analog-digital unification. Siemens EDA occupies a position representing manufacturing-scale partnership models. Among specialized vendors, Zuken sits within the electromagnetic compatibility and constraint-driven routing segment. These three named entities represent distinct competitive vectors: silicon-proven IP integration, fabrication workflow bridging, and high-reliability aerospace specialization.
| Leading Market Players |
|---|
| Altium |
| Keysight Technologies |
| Cadence Design Systems |
| Aldec |
| ANSYS |
| Synopsys |
| Zuken |
| Pulsic |
| Siemens EDA |
| Others |
Supply & Pricing Matrix
German automotive tier-one suppliers mandating ISO 26262 functional safety traceability are compressing procurement timelines for ECAD vendors, forcing supply-side investments in embedded compliance architectures and compressing margins on standard-tier offerings.
Pricing Analysis
Volume concentrates in subscription-licensed SaaS tiers serving contract manufacturers in South Korea and Taiwan, while margin pools sit with perpetual-seat desktop solutions for defense electronics programs in the United States. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification depth and after-sales support bundling. Cost compression in the mid-market SaaS tier is intensifying because production-linked incentive schemes in India and Vietnam are spawning price-sensitive first-time buyers. Electronics manufacturers exhibit the highest price sensitivity, whereas semiconductor developers demonstrate the lowest due to silicon-proven IP integration requirements.
Supply Chain Analysis
Regional distribution centers in Singapore and the Netherlands coordinate hub-and-spoke patterns for cloud-based platform delivery, while air-gapped desktop installations ship direct from development hubs in the United States and Germany. Software development concentrates in the United States, Germany, and India, with component library curation anchored in Japan and Taiwan. The supply chain draws from specialized electromagnetic compatibility simulation expertise, silicon-validated IP repositories, and cloud infrastructure services. Single-source vulnerability in legacy library formats across vendor ecosystems creates consolidation friction when engineering teams merge. Distribution runs through value-added resellers pivoting toward implementation consulting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native architectures are displacing monolithic desktop installations, with machine learning-assisted routing engines replacing manual constraint-driven workflows in high-density interconnect designs.
For Market Incumbents: Lock in tier-one semiconductor relationships by deepening analog-digital-thermal unification within single environments, neutralizing the threat of cloud-native challengers fragmenting procurement authority. Anchor manufacturing-scale partnerships that bridge design data directly into TSMC and Samsung Foundry fabrication workflows, creating switching costs that subscription-based entrants cannot replicate.
For New Entrants and Emerging Players: Value-added distributors with established training relationships present the most viable channel path for penetrating mid-market electronics manufacturers in India and Vietnam. White-space opportunities sit in fiber optic network design tools for hyperscale data center construction in Ireland and the Netherlands, plus SaaS-native compliance documentation for medical device startups facing FDA validation requirements. A freemium schematic capture tier with paywalled simulation modules offers the cleanest go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors specialized electromagnetic compatibility vendors with aging founder-owners in Germany and Japan, where technical talent scarcity constrains organic replication. Long-term viability hinges on chip-package-board co-design capability convergence, making thermal analysis module developers the most defensible acquisition profile. Watch for FDA software validation pathway streamlining as the inflection signal indicating venture capital appetite for diagnostic hardware startups.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies analog, digital, and thermal analysis within Cadence and Synopsys environments, collapsing engineering handoffs. |
| Strategic Partnership | Siemens EDA bridges design data directly into fabrication workflows, locking in automotive tier-one suppliers. |
| Acquisition of Specialist Firm | Consolidates electromagnetic compatibility expertise concentrated among aging German and Japanese engineers. |
| Geographic Expansion | Captures first-time ECAD demand among Indian contract manufacturers under Gujarat and Tamil Nadu incentive schemes. |
| Product Launch | Cloud-native compliance documentation tools address EU AI Act and FDA validation requirements for medical device electronics. |
Research Methodology
Document review covered SEC filings from Cadence, Synopsys, and Siemens EDA, complemented by interviews with ECAD product managers, semiconductor procurement leads at TSMC ecosystem partners, automotive electronics engineers in Stuttgart, and medical device regulatory affairs specialists. Secondary validation drew from FDA software validation guidance documents, EU AI Act compliance frameworks, and hyperscaler data center construction announcements. Bottom-up triangulation across deployment model adoption patterns and top-down reconciliation against semiconductor fabrication investment flows anchored volume estimates.
Segment-level outputs across the analysis window reflect modeled assumptions for cloud versus desktop penetration, subscription versus perpetual license mix, and PCB design versus fiber optic application growth differentials. The analytical framework incorporated technology deployment architecture, end-user industry vertical, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from installed base expansion rates and new license velocity across German automotive, United States defense, and India electronics manufacturing clusters.
Several conditions sit outside the modeled scope, including potential cybersecurity certification scheme disruptions for connected industrial equipment and unforeseen REACH substance restriction amendments affecting component library composition. Forecasts reflect documented assumptions regarding cloud security protocol evolution and legacy library format consolidation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Banking Team Collaboration Software Market
Software & Services
Salon Booking Software Market
Software & Services
Global Online Assessment Software Market
Software & Services
Global Corporate Wellness Software Market
Software & Services
Global Landscape Software Market
Software & Services
Europe Saas-Based SCM Market
Software & Services
Africa Financial Services Software Market
Software & Services
Deck Software Market
Software & Services
Tag Management Software Market
Software & Services
Global Client Portal Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Anti-Plagiarism Software Market
Software & Services
Train Reservation Software Market
Software & Services
Camera Tracking Software Market
Software & Services
Feedback Management Software Market