
 Digital Sculpture Software Market | 2026-2036
Digital Sculpture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Sculpture Software Market Insights
Game developers is repositioning the center of gravity for digital sculpture software demand, pulling toolmakers toward real-time mesh optimization and platform-native export formats. Pixologic anchors the high-end organic sculpting segment with ZBrush's entrenched position in film and collectibles pipelines. Autodesk extends its ecosystem lock-in through Maya and 3ds Max integrations that bridge sculpting into downstream animation workflows. SideFX competes through Houdini's procedural geometry tools that attract technical directors seeking non-destructive sculpting alternatives.
Digital sculpture software comprises specialized applications for manipulating high-resolution polygonal, voxel, or implicit surface models through brush-based, procedural, or algorithmic deformation workflows, typically supporting millions of polygons in real-time viewport interaction. These tools serve primary commercial purposes in entertainment asset creation, industrial design prototyping, and heritage digitization where manual or semi-automated surface manipulation outperforms parametric CAD approaches. Sculpting tools dominate current revenue as the foundational category underpinning all downstream texturing and animation workflows. Cloud-based deployment represents the fastest-expanding structural segment as studios distribute hardware-intensive sculpting workloads to elastic GPU clusters. Perpetual license models retain margin concentration among enterprise film studios with long production cycles that resist subscription cost structures.
The U.S. Copyright Office shapes demand through registration frameworks that protect digital sculptural works, while the EU's GDPR influences cloud deployment architectures for European creative studios handling artist personal data. ISO standards for digital preservation increasingly affect how heritage institutions specify sculpture software for cultural asset documentation. Stakeholders must monitor how generative AI training data policies from regulators and platform holders will reshape artist workflow requirements and software feature roadmaps.
Market Dynamics
Real-time rendering pipelines are compressing traditional sculpt-to-game workflows, forcing toolmakers to rebuild viewport architectures around GPU-native mesh streaming rather than offline subdivision surfaces.
Growth Catalysts
- Cloud GPU Elasticity:Independent artists in Germany and Japan now access workstation-class sculpting through browser-based instances, eliminating hardware CapEx barriers that previously gated entry.
- Heritage Digitization Mandates:ISO 14721-compliant digital preservation frameworks require sub-micron surface capture for museum collections, driving institutional procurement of high-resolution sculpting workstations.
- Real-Time Engine Convergence:Game developers demand native USD and glTF export paths that bridge sculpting directly into Unreal Engine and Unity pipelines without intermediate conversion steps.
Market Restraints
- Compute Cost Volatility:Cloud sculpting workloads depend on NVIDIA A100 and H100 instance availability, where spot pricing swings of 40-60% within quarterly windows destabilize studio operational budgeting.
- Vendor Concentration Risk:Foundational mesh libraries and geometry kernels concentrate among three European and US mathematics software houses, creating single-source fragility for downstream tool developers.
- GDPR Data Residency Friction:EU studios handling artist biometric reference scans for character work face architectural constraints on cross-border cloud storage, complicating distributed production models.
Strategic Opportunities
- Procedural-Sculpting Hybrid Tools:Convergence of signed-distance-field generators with traditional brush workflows opens technical director segments currently served by separate Houdini and ZBrush licenses.
- Indian VFX Studio Expansion:Mumbai and Bengaluru facilities are scaling real-time asset teams for streaming platform originals, creating demand for mid-tier sculpting seats between hobbyist and enterprise tiers.
- US Copyright Registration Modernization:Updated Copyright Office guidance on digital sculptural work deposit formats reduces legal friction for individual artists commercializing 3D-printed collectibles.
Industry Challenges
- Retopology Skill Compression:Automated quad-drawing tools are obsoleting manual retopology specialists faster than training pipelines can redirect talent toward technical art direction.
- Legacy Pipeline Integration:Film studios maintaining 2015-2019 era Maya-Arnold workflows face friction bridging new sculpting exports into validated render farm configurations without full pipeline rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Sculpture Software Market |
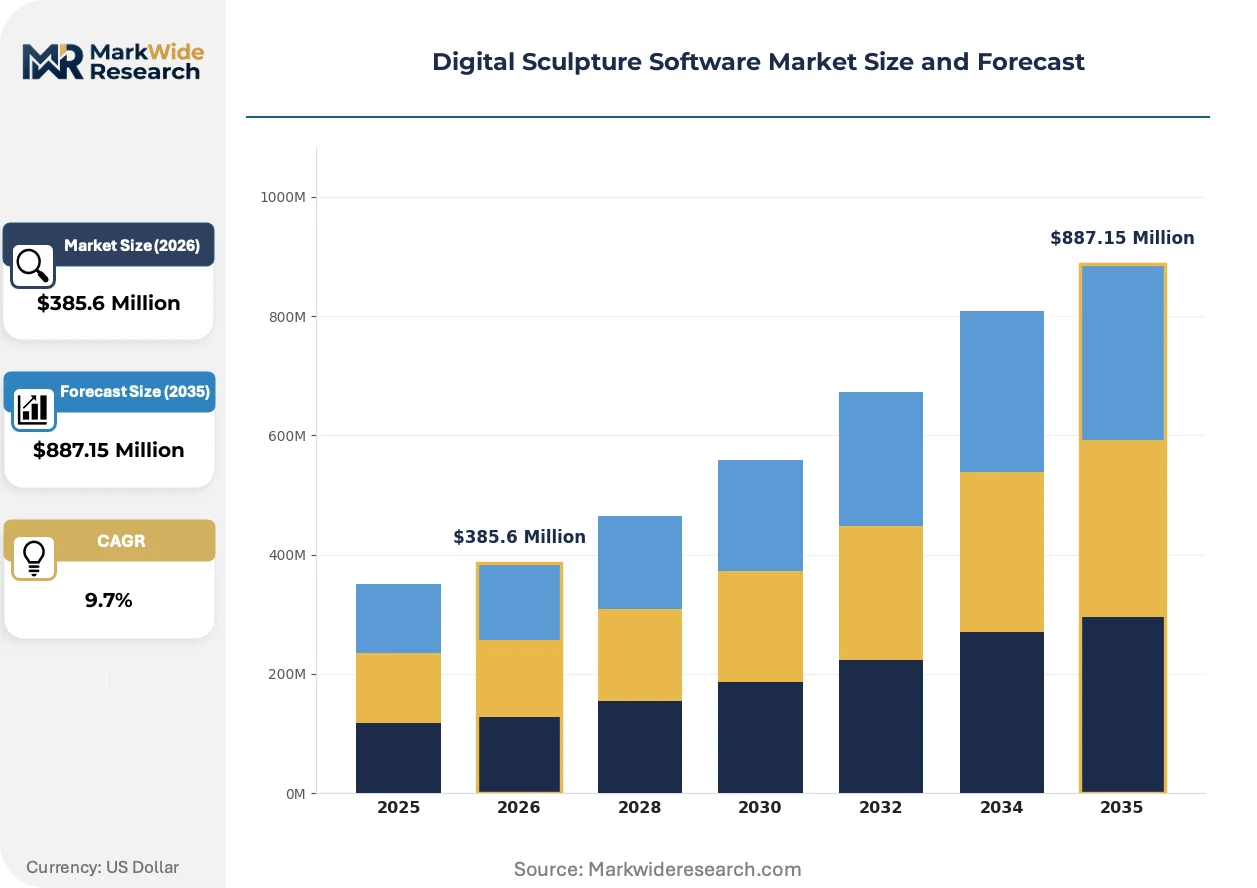
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $887.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sculpting Tools, Texturing Software, Animation Suites, Rendering Engines Deployment: On-Premises, Cloud-Based, Hybrid, Virtual Desktop End User: Artists, Game Developers, Film Studios, Educational Institutions License Model: Subscription, Perpetual, Freeware, Open Source |
| Companies Covered | Pixologic, Autodesk, Maxon Computer, Adobe, Blender Foundation, Corel Corporation, SideFX, Foundry, Nomad Sculpt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Sculpture Software Market Trends and Innovations
Neural surface reconstruction and generative deformation models are rewriting the artist-tool relationship, shifting competitive advantage toward inference-optimized architectures rather than raw polygon throughput.
Volumetric neural radiance fields (NeRFs) and Gaussian splatting techniques are integrating into sculpting viewports as background reference and base-mesh generation sources. Archival digitization teams at heritage institutions adopt these tools for photogrammetric capture workflows. The technology is integrating surface-from-image reconstruction directly into brush-based refinement environments, collapsing previously separate photography and sculpting skill domains.
The EU AI Act's transparency requirements for generative training data are forcing sculpting vendors to document provenance of base meshes used in style-transfer and auto-rigging features. Toolmakers must now implement audit trails for artist-contributed training sets or face exclusion from European commercial deployment. Independent developers are responding by building federated learning architectures that keep source geometry on-device rather than centralized.
Subscription fatigue among freelance character artists is driving preference fragmentation between perpetual-license holdouts and cloud-native entrants. Mid-tier buyers are unbundling maintenance contracts, purchasing core sculpting seats while sourcing retopology and UV tools from specialized competitors. This pattern concentrates in the United States where individual contractor status dominates game and VFX labor markets.
Digital Sculpture Software Market Segmentation
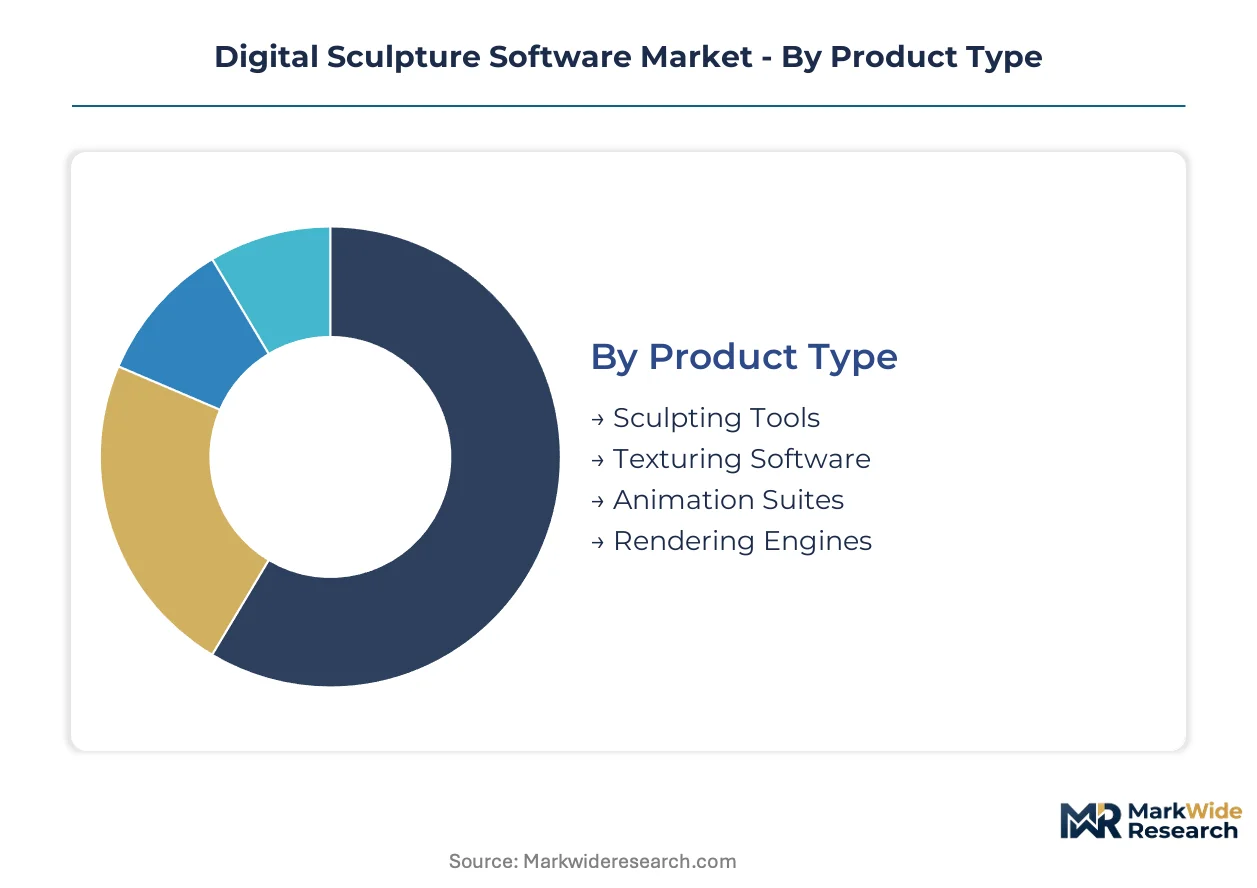
Digital sculpture software vendors configure feature sets and pricing tiers around distinct technical workflows and infrastructure constraints. Segmentation reveals how toolmakers balance specialized sculpting functionality against integrated pipeline demands across varying buyer sophistication levels.
Product Type:
Customization spans brush-engine sophistication and pipeline integration depth, from standalone sculpting environments to full production suites.
- Sculpting Tools:Core applications delivering high-resolution mesh deformation through proprietary brush engines, dynamic subdivision, and voxel-based sculpting. Game developers in the United States drive procurement for real-time viewport performance and direct Unreal Engine export paths. Foundational category capturing majority share as upstream dependency for all downstream asset workflows.
- Texturing Software:Specialized tools for UV unwrapping, procedural material authoring, and hand-painted surface detail. Demand concentrates among character artists in Germany requiring PBR workflow compatibility with Substance Painter pipelines. Fastest-expanding segment as studios unbundle texturing from monolithic suites.
- Animation Suites:Integrated platforms bridging sculpting outputs into rigging, skinning, and keyframe or motion-capture animation. Film studios in Japan prioritize Maya-embedded sculpting for validated render farm compatibility.
- Rendering Engines:GPU-accelerated visualization systems for sculpting viewport feedback and final output generation. Independent artists adopt browser-based instances to eliminate local hardware investment.
Leading the category by volume: Sculpting Tools. Expanding most quickly: Texturing Software.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from operational expenditure models favoring elastic scaling.
- On-Premises:Workstation-class implementations with local GPU arrays for latency-sensitive brush interaction. Enterprise film studios in the United States maintain these configurations for security-controlled IP environments.
- Cloud-Based:Browser-accessible sculpting instances streaming from elastic GPU clusters. Independent artists in Germany and Japan access workstation performance without hardware ownership. Steepest expansion trajectory as spot pricing volatility stabilizes.
- Hybrid:Split configurations caching sensitive assets locally while offloading compute-intensive operations to cloud instances. Mid-tier VFX facilities adopt this architecture for budget flexibility.
- Virtual Desktop:Remotely hosted workstation environments delivering consistent tool versions across distributed teams. Streaming platform content houses deploy for standardized contractor access.
Volume concentration: On-Premises among legacy studios. Fastest climb: Cloud-Based.
End User:
Customer maturity determines feature complexity requirements and support service expectations across the buyer spectrum.
- Artists:Individual practitioners and freelancers requiring affordable seats with shallow learning curves. Subscription fatigue in the United States drives fragmentation between perpetual-license holdouts and cloud-native alternatives.
- Game Developers:Real-time asset teams demanding native USD and glTF export paths without intermediate conversion. Studios in the United States lead procurement for direct Unreal Engine and Unity pipeline bridges.
- Film Studios:Long-cycle production houses with validated Maya-Arnold workflows requiring backward-compatible sculpting exports. Integration friction limits migration speed to newer tool generations.
- Educational Institutions:Universities and training programs sourcing volume-licensed seats for curriculum deployment. Heritage digitization programs at museums specify ISO 14721-compliant preservation capabilities.
Dominant by volume: Game Developers. Gaining share fastest: Educational Institutions.
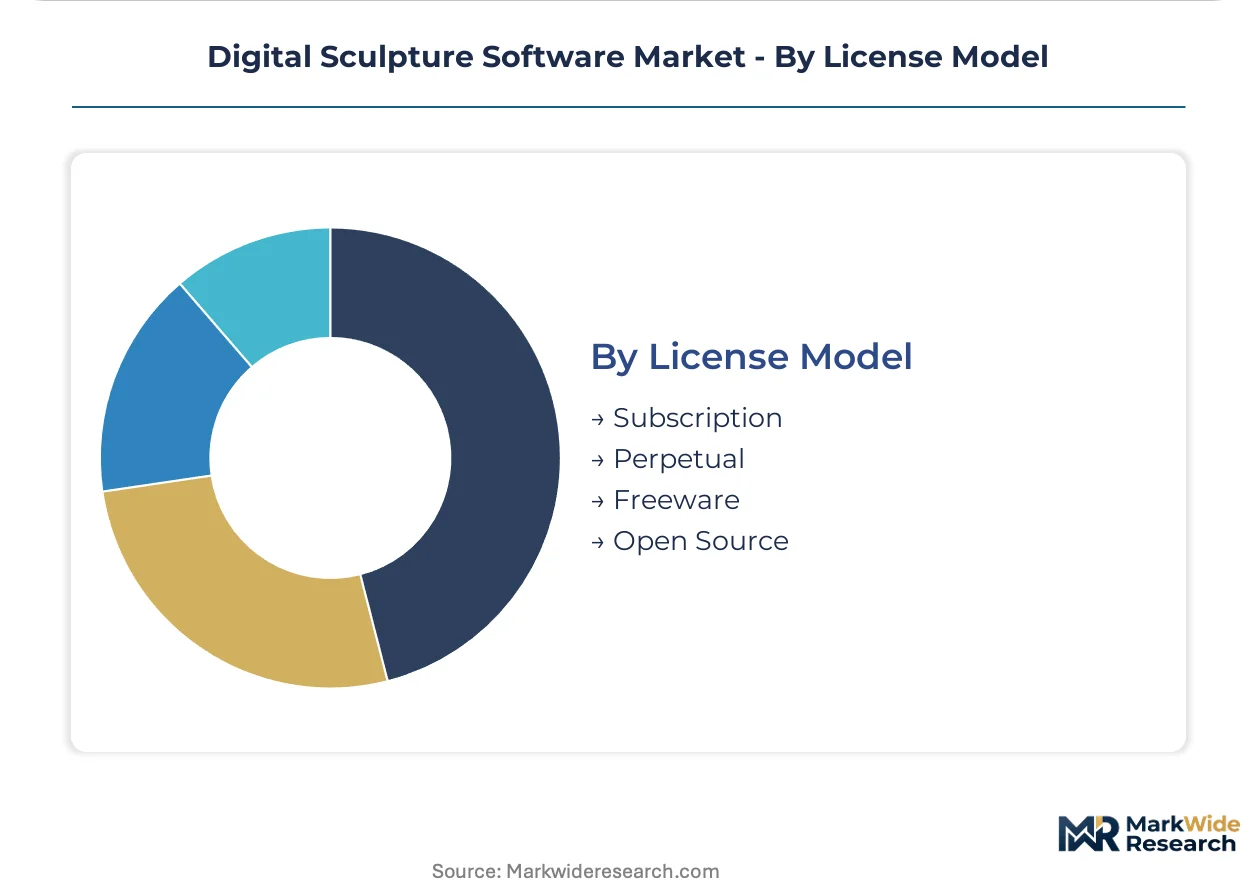
License Model:
Margin structure varies dramatically between recurring revenue streams and upfront perpetual transactions with maintenance attachments.
- Subscription:Monthly or annual recurring access with continuous updates and cloud service integration. Toolmakers favor this model for predictable revenue and reduced version fragmentation.
- Perpetual:One-time purchase with optional maintenance contracts for updates and support. Enterprise film studios in the United States resist subscription economics for multi-year productions. Retains margin concentration among established vendors.
- Freeware:No-cost entry-tier versions with feature limitations or export restrictions. Hobbyist communities and students drive adoption, creating pipeline familiarity that converts to paid tiers.
- Open Source:Community-developed alternatives with transparent codebases and extensible architectures. Technical directors adopt for custom pipeline integration without vendor dependency.
Revenue leadership: Perpetual among enterprise buyers. Subscription climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's Digital Media Tax Credit and Vancouver's Visual Effects Incentive Program concentrate production infrastructure along the Pacific corridor, drawing sculpting software procurement toward facilities serving streaming platform originals.
United States
Game developers in Austin and Los Angeles drive workstation-class sculpting seat procurement for real-time engine pipelines. The US Copyright Office's updated registration guidance for digital sculptural deposits reduces legal friction for individual artists commercializing 3D-printed collectibles. Seattle-area cloud infrastructure providers enable elastic GPU clusters that independent artists access through browser-based sculpting instances.
Germany
Character artists in Berlin and Munich demand PBR workflow compatibility with established material authoring pipelines. The EU's GDPR imposes data residency constraints on cloud storage of artist biometric reference scans, complicating distributed production models. Bavarian VFX studios are adopting hybrid deployment architectures that cache sensitive assets locally while offloading compute-intensive operations to cloud instances.
Japan
Film studios in Tokyo prioritize Maya-embedded sculpting for validated render farm compatibility with long-cycle animation productions. METI's digital content industry support programs subsidize software procurement for heritage digitization initiatives. Osaka-based collectibles manufacturers integrate high-resolution sculpting into 3D-printed figure production for domestic and export markets.
India
Mumbai and Bengaluru facilities are scaling real-time asset teams for streaming platform originals, creating demand for mid-tier sculpting seats between hobbyist and enterprise tiers. The country's national software industry regulator promotes indigenous tool development through production-linked incentive schemes. Hyderabad's emerging VFX cluster is recruiting technical artists capable of bridging sculpting outputs into Unreal Engine pipelines.
United Kingdom
London-based game studios drive procurement for native USD export paths that bridge sculpting directly into Unity pipelines. The UK's Information Commissioner's Office enforces data protection standards affecting cloud deployment choices for studios handling artist personal data. Manchester's growing animation sector is adopting subscription-flexible licensing to accommodate project-based contractor staffing models.
Digital Sculpture Software Market Competitive Landscape
Top-tier vendors anchor the high-end organic sculpting segment, while mid-tier specialists and open-source alternatives fragment the lower tiers. The market structure reflects a tiered concentration where established toolmakers maintain ecosystem lock-in through pipeline integration, while emerging entrants compete on deployment flexibility and pricing accessibility. Three strategic archetypes dominate: proprietary brush-engine specialists, integrated production-suite providers, and community-driven open-source projects. Competitive moves center on cloud-native architecture development and procedural-sculpting hybrid feature expansion.
Within the proprietary specialist tier, Pixologic and SideFX occupy positions defined by technical differentiation in brush-engine sophistication and procedural geometry workflows respectively. Autodesk exemplifies the integrated-suite archetype through its Maya and 3ds Max ecosystem extensions that bridge sculpting into downstream animation pipelines. Blender Foundation represents the open-source alternative, anchoring community-driven development with transparent codebases that technical directors adopt for custom pipeline integration without vendor dependency.
| Leading Market Players |
|---|
| Pixologic |
| Autodesk |
| Maxon Computer |
| Adobe |
| Blender Foundation |
| Corel Corporation |
| SideFX |
| Foundry |
| Nomad Sculpt |
| Others |
Pricing and Supply Chain Analysis
Captive GPU cluster ownership by major cloud providers anchors both supply positioning and pricing power across deployment tiers. Autodesk and Adobe leverage backward integration into render farm infrastructure to defend premium subscription tiers against spot-priced cloud alternatives.
Pricing Analysis
Short lead-time premiums for immediate cloud GPU availability separate enterprise film studio budgets from independent artist spot purchasing. Three-tier pricing structure across premium, standard, and economy levels reflects brush-engine sophistication and pipeline integration depth. Cost compression in mid-tier subscriptions intensifies because unbundled retopology tools fragment former suite economics. Individual freelancers exhibit highest price sensitivity, while multi-year production houses resist subscription conversion.
Supply Chain Analysis
Single-source vulnerability sits with NVIDIA's A100 and H100 silicon allocation for cloud sculpting instances. Geometry kernel libraries concentrate in France, Germany, and the United States, creating concentrated dependency for brush-engine developers. Raw material inputs span high-bandwidth memory modules, specialized foundry capacity, and mathematics software licensing. Tariff exposure on Chinese-manufactured workstation components threatens hardware CapEx planning. Distribution runs through direct vendor portals and hyperscaler marketplaces rather than traditional channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from generative AI feature development is forcing capital-constrained toolmakers toward acquisition or exit. Smaller vendors lacking inference-optimized architectures face margin compression from both cloud-native entrants and suite providers.
For Market Incumbents: Hedge against procedural-sculpting hybrid disruption by acquiring signed-distance-field specialists or building native Houdini-competitive features. Invest in federated learning architectures that satisfy EU AI Act training-data audit requirements. Channel control through Maya and 3ds Max plugin ecosystems remains the priority defensive lever against standalone sculpting entrants.
For New Entrants and Emerging Players: The price-point gap between ZBrush perpetual licenses and Blender's donation model creates white-space for mid-tier browser-native sculpting. Target Indian VFX studios in Mumbai and Bengaluru scaling real-time asset teams without enterprise budget access. Go-to-market through Unreal Engine Marketplace integration bypasses traditional procurement friction.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated production-suite providers seeking sculpting capability fill-ins. Five-to-ten year viability favors vendors with cloud-native architecture and compliance-ready AI feature documentation. Acquisition target archetype: procedural geometry specialists with technical director customer bases. Watch for inflection when ISO 14721 preservation mandates trigger institutional procurement waves.
| Strategic Initiative | Industry Significance |
|---|---|
| Procedural-Sculpting Hybrid Development | SideFX Houdini workflows attract technical directors seeking non-destructive alternatives to brush-only tools. |
| Cloud-Native Architecture Migration | Browser-based GPU streaming eliminates hardware CapEx barriers for independent artists in Germany and Japan. |
| EU AI Act Compliance Investment | Audit trail implementation for training data provenance protects European commercial deployment eligibility. |
| USD and glTF Native Export Integration | Direct Unreal Engine pipeline bridges satisfy game developer demand in Austin and Los Angeles. |
| Heritage Digitization Partnership | ISO 14721-compliant preservation capabilities unlock museum and institutional procurement budgets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with VFX studio technical directors, game engine integration specialists, cloud infrastructure procurement officers, and character art pipeline supervisors combined with secondary validation from SEC filings, EU AI Act implementation guidance, and GPU shipment customs records. Bottom-up seat deployment estimates triangulated against top-down creative industry employment data.
Granularity-level modeling distinguished on-premises, cloud-based, hybrid, and virtual desktop deployments across artist, game developer, film studio, and educational institution end users. Organization size tiers and regional adoption patterns shaped value projections across the analysis window. CAGRs derived from segment-specific growth rate assumptions calibrated to real-time engine pipeline expansion and heritage digitization mandate timelines. Cloud GPU spot pricing volatility and perpetual license maintenance renewal rates served as key forecast sensitivity inputs.
Inputs from US Copyright Office registration databases and EU GDPR implementation case studies were available through the study window; gaps in proprietary vendor seat deployment data introduce uncertainty bands around mid-tier market sizing. Forecasts reflect assumptions about generative AI feature adoption speed and cloud infrastructure spot price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Club Management Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Towing Software Market
Software & Services
Europe Drone Software Market
Software & Services
Anti-Plagiarism for the Education Sector Market
Software & Services
Creative Software Market
Software & Services
Global Healthcare Contract Management Software Market
Software & Services
Proxy Services and Software Market
Software & Services
Saas Based HRM Market
Software & Services
Global Municipal Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Service Scheduling Software Market
Software & Services
Attendance Management Software Market
Software & Services
Global Bug Tracking Software Market
Software & Services
Global VR Game Engine Software Market