
 Global Patient Lateral Transfer Market | 2026-2036
Global Patient Lateral Transfer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Patient Lateral Transfer Market Foresight
Buyer concentration among hospital procurement networks is realigning vendor relationships across the Global Patient Lateral Transfer Market. Arjo leverages its installed base of ceiling lift systems to sustain recurring revenue from maintenance contracts. Stryker competes through integrated bed-to-transfer workflow solutions that anchor its position in perioperative settings. Medline Industries controls distribution scale across North American group purchasing organizations, extending its reach into nursing home chains.
Patient lateral transfer encompasses friction-reducing devices, air-assisted systems, and mechanical slide sheets engineered to move immobile patients between surfaces with force loads below 35 pounds per caregiver. These systems prevent musculoskeletal injuries among healthcare staff while maintaining spinal alignment during bed-to-stretcher movements. Electric systems command premium positioning due to motor-driven weight capacity above 500 pounds and programmable height adjustment, while mechanical systems dominate volume through lower capital requirements and minimal maintenance. Manual systems retain share in home care where power access limits electric adoption, though hybrid configurations are gaining traction in rehabilitation centers seeking flexible deployment.
The FDA enforces safe patient handling standards under OSHA guidelines, compelling hospitals to document injury reduction metrics tied to transfer equipment procurement. The EU Medical Device Regulation (MDR) reclassifies powered lateral transfer devices, extending conformity assessment timelines and raising documentation burdens for manufacturers accessing European markets. Japan's Ministry of Economy, Trade and Industry (METI) promotes robotic patient handling through subsidy programs targeting acute care facilities. Stakeholders must monitor how reimbursement coding for hospital-acquired pressure injuries increasingly ties to transfer quality documentation, reshaping procurement criteria toward sensor-integrated systems that log movement protocols.
Market Dynamics
Hospital procurement networks are consolidating vendor contracts across multi-facility systems, forcing equipment manufacturers to restructure pricing and service models around enterprise-scale agreements rather than individual facility sales.
Growth Catalysts
- OSHA safe patient handling mandates:US hospitals must document injury reduction metrics tied to transfer equipment, compelling capital investment in compliant systems.
- Air-assisted transfer technology:Friction-reducing air mattresses enable single-caregiver transfers for bariatric patients, expanding addressable patient populations.
- Japan METI robotic handling subsidies:Acute care facilities receive direct funding for automated patient positioning equipment, accelerating replacement cycles.
Market Restraints
- Electric motor supply concentration:Brushless DC motor production concentrates in East Asian manufacturing clusters, exposing lead time volatility.
- EU MDR conformity timelines:Powered lateral transfer devices face extended documentation burdens and notified body backlogs, delaying European market access.
- Mechanical slide sheet durability limits:Polyester-based friction-reducing surfaces degrade under repeated laundering, forcing higher replacement frequency than capital equipment.
Strategic Opportunities
- Home care channel expansion:Manual transfer systems with battery-assisted options address power access limitations in residential settings where electric infrastructure is unreliable.
- Sensor-integrated documentation systems:Pressure mapping and movement logging technologies align with reimbursement coding tied to hospital-acquired pressure injury prevention.
- German rehabilitation center hybrid configurations:Flexible mechanical-electric systems serve variable patient mobility levels within single facilities.
Industry Challenges
- Biomedical technician certification gaps:Electric transfer systems require specialized maintenance training that outpaces technical education program output.
- Ceiling lift infrastructure retrofit costs:Older hospital buildings lack structural support for overhead patient handling systems, requiring expensive reinforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Patient Lateral Transfer Market |
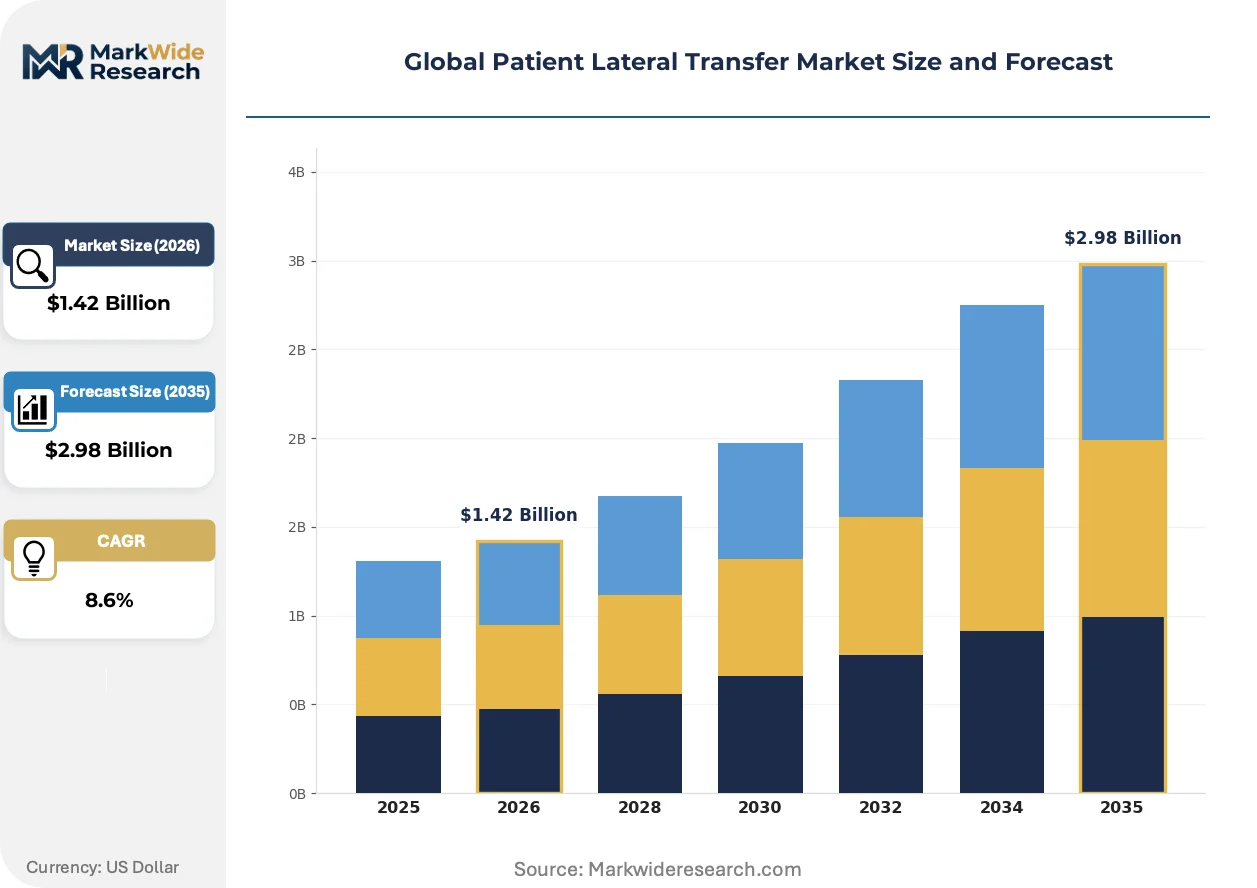
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lateral Transfer Sheets, Transfer Carts, Slings, Lift Equipment End User: Hospitals, Nursing Homes, Rehabilitation Centers, Home Care Technology: Mechanical Systems, Electric Systems, Manual Systems, Hybrid Systems Application: Patient Transfer, Emergency Response, Surgical Assistance, Rehabilitation |
| Companies Covered | Arjo, Stryker, Hill-Rom, Medline Industries, Guldmann, HoverTech International, EZ Way Inc., AliMed, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Patient Lateral Transfer Market Shifts & Advancements
Equipment manufacturers are embedding predictive maintenance capabilities and force-sensing feedback into transfer platforms, transforming capital sales into recurring service relationships while improving patient safety documentation.
Wireless load cell technology is decentralizing weight distribution monitoring across hospital floors. Acute care facilities in the United States deploy these sensors to track caregiver force exposure in real time. The technology is decentralizing risk management from centralized biennial audits to continuous operational oversight.
EU Medical Device Regulation reclassification of powered lateral transfer equipment extends conformity assessment timelines and raises clinical evidence requirements. Manufacturers targeting European markets now allocate additional resources to post-market surveillance systems. Rehabilitation centers and long-term care facilities face delayed product availability as certification backlogs accumulate.
Group purchasing organizations now mandate outcome documentation tied to staff injury reduction. Hospital networks in North America unbundle equipment procurement from training and maintenance contracts, forcing vendors to compete on service metrics rather than capital cost alone. This behavioral shift concentrates supplier relationships among vendors with established clinical education infrastructure.
Global Patient Lateral Transfer Market Segmentation
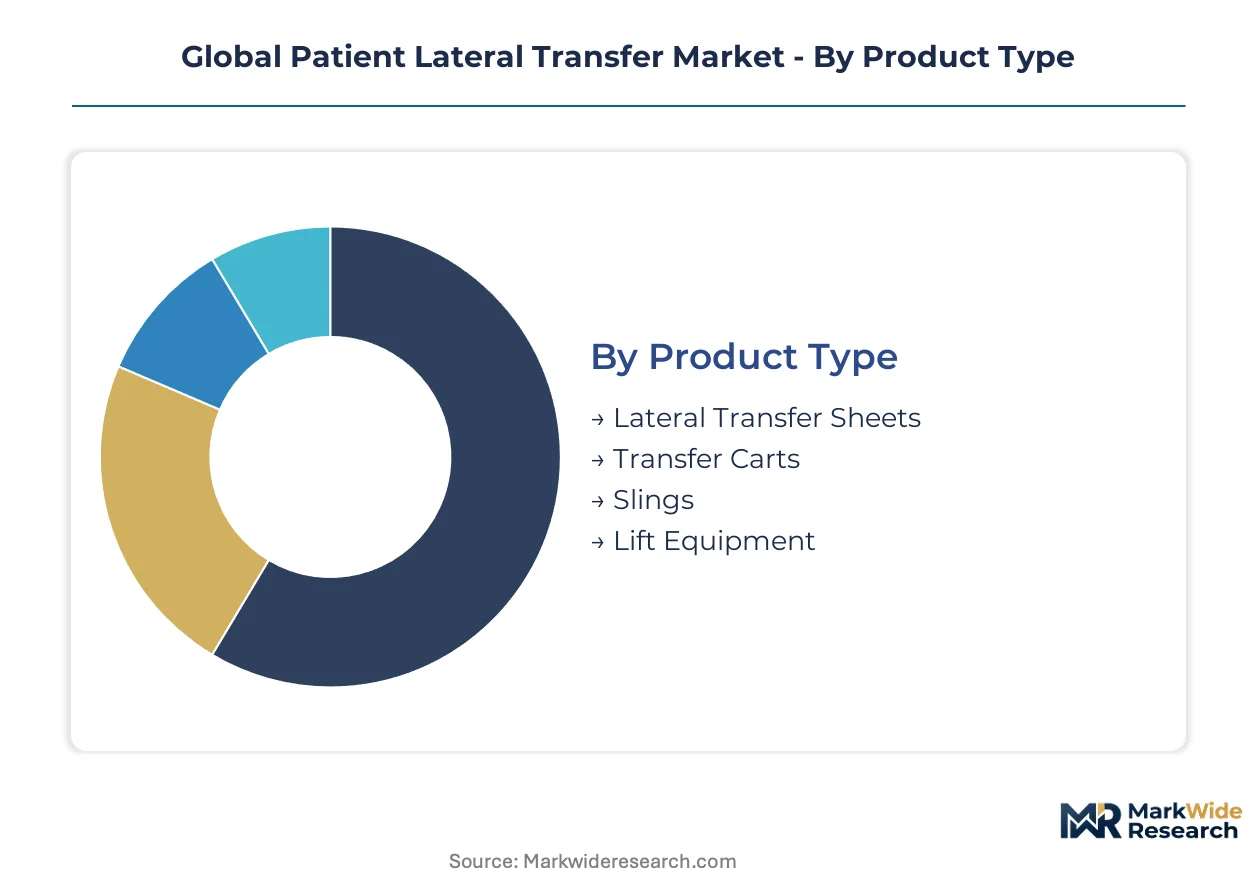
Segmentation in patient lateral transfer equipment reveals divergent capital requirements, clinical workflows, and procurement priorities across healthcare settings. Understanding these divisions exposes where technology investments concentrate and which configurations align with specific facility constraints.
Product Type:
Capital intensity varies sharply across product categories, with installed infrastructure systems demanding the highest upfront investment while consumable sheets require minimal fixed capital but recurring operational expenditure.
- Lateral Transfer Sheets:Friction-reducing fabric or polymer surfaces engineered for single-patient or limited-use applications. Demand concentrates in US acute care networks seeking OSHA-compliant injury reduction documentation, though polyester durability limits under repeated industrial laundering cycles create replacement cost pressure.
- Lift Equipment:Motorized or pneumatic systems with weight capacities exceeding 500 pounds, incorporating programmable height adjustment and force-limiting controls. German rehabilitation centers and Japanese acute care facilities drive procurement through METI subsidy programs and EU MDR conformity pathways, anchoring premium positioning through clinical outcome documentation requirements.
- Transfer Carts:Mobile platforms with integrated sliding surfaces for inter-departmental patient movement. Nursing home chains in North American group purchasing networks favor these for flexible deployment across variable room configurations.
- Slings:Suspension interfaces connecting patients to overhead or mobile lift mechanisms. Home care providers in power-limited residential settings select manual sling configurations for bariatric patient handling.
Most installed capacity flows through Lateral Transfer Sheets. Expansion is steepest in Lift Equipment.
End User:
Procurement sophistication and reimbursement pathways create distinct customer tiers, with hospital networks leveraging enterprise-scale contracts while home care operates through fragmented retail channels.
- Hospitals:Multi-facility systems with consolidated vendor contracts and mandatory safe patient handling compliance documentation. US hospital procurement networks unbundle equipment from training contracts, forcing suppliers to compete on service metrics and injury reduction verification.
- Home Care:Residential settings with unreliable electric infrastructure and non-professional caregivers. Battery-assisted manual systems address power access limitations, though caregiver training gaps constrain technology adoption.
- Nursing Homes:Long-term care facilities with high patient turnover and pressure injury prevention protocols. Group purchasing organization mandates for outcome documentation reshape supplier relationships toward vendors with established clinical education infrastructure.
- Rehabilitation Centers:German facilities particularly favor hybrid mechanical-electric configurations serving variable patient mobility levels within single treatment environments.
Contract volume concentrates in Hospitals. Home Care is gaining share fastest as aging demographics shift care delivery outside institutional settings.
Technology:
Technology selection tracks facility infrastructure maturity, with electric systems requiring dedicated power and maintenance capabilities while manual alternatives serve constrained environments.
- Electric Systems:Motor-driven platforms with programmable control interfaces and sensor-integrated documentation capabilities. Premium positioning reflects brushless DC motor supply concentration in East Asian manufacturing clusters and FDA safe patient handling guideline alignment.
- Mechanical Systems:Friction-reducing or lever-assisted configurations without external power requirements. Volume dominance stems from lower capital thresholds and minimal maintenance demands, particularly in nursing home chains with limited biomedical technician coverage.
- Manual Systems:Basic slide sheets and transfer boards for caregiver-assisted movement. Retains share in home care where power access is unreliable and capital constraints limit equipment acquisition.
- Hybrid Systems:Configurable mechanical-electric platforms allowing facility-level customization. Japanese acute care facilities deploy these through METI robotic handling subsidies, while German rehabilitation centers seek flexible deployment across variable patient populations.
Mechanical Systems carry the largest installed base. Hybrid Systems are climbing the fastest as facilities seek flexible capital deployment.
Application:
Application segmentation maps to clinical workflow intensity and regulatory documentation requirements, with perioperative settings demanding the highest performance specifications.
- Patient Transfer:Routine bed-to-stretcher and surface-to-surface movement in acute care environments. US hospital networks document injury reduction metrics tied to transfer equipment procurement under OSHA guidelines, compelling capital investment in compliant systems.
- Surgical Assistance:Operating room positioning and post-anesthesia transfer requiring spinal alignment maintenance and sterile field preservation. Integrated bed-to-transfer workflow solutions anchor vendor positioning in perioperative settings.
- Emergency Response:Rapid patient movement under time pressure with minimal staff availability. Air-assisted transfer technology enables single-caregiver bariatric patient handling, expanding addressable clinical scenarios.
- Rehabilitation:Progressive mobility protocols requiring adjustable support levels. Pressure mapping and movement logging technologies align with reimbursement coding tied to hospital-acquired pressure injury prevention documentation.
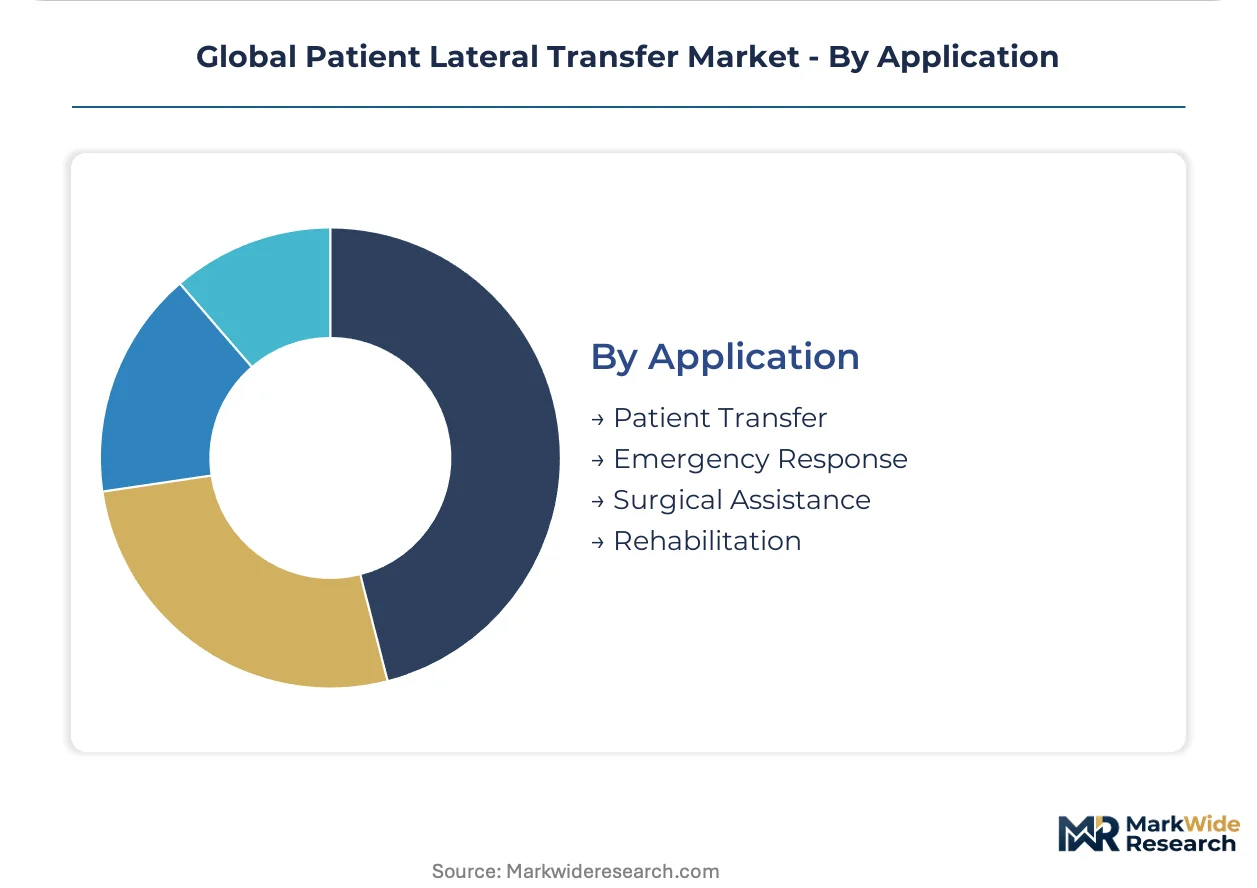
Patient Transfer absorbs the greatest equipment volume. Surgical Assistance commands the steepest expansion trajectory through integrated workflow system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare workforce density and aging demographics anchor demand concentration across the Global Patient Lateral Transfer Market. Acute care infrastructure maturity varies sharply, with procurement sophistication tracking regulatory enforcement intensity and hospital network consolidation patterns.
United States
Hospital procurement networks consolidate vendor contracts across multi-facility systems, forcing equipment manufacturers toward enterprise-scale agreements. OSHA safe patient handling mandates compel capital investment in compliant transfer systems with documented injury reduction metrics. The Greater Boston and Pacific Northwest clusters concentrate biomedical engineering talent developing sensor-integrated documentation platforms.
Germany
Rehabilitation centers drive hybrid mechanical-electric system adoption serving variable patient mobility levels within single facilities. EU Medical Device Regulation reclassification extends conformity assessment timelines for powered lateral transfer devices, delaying product availability. The Baden-Württemberg industrial corridor anchors precision manufacturing clusters supplying brushless DC motor components to equipment fabricators.
Japan
Acute care facilities accelerate replacement cycles through METI robotic handling subsidies targeting automated patient positioning equipment. Aging demographics strain hospital infrastructure, expanding addressable demand for bariatric-capable transfer systems. The Kanto region surrounding Tokyo concentrates medical device distribution networks serving domestic hospital procurement departments.
United Kingdom
National Health Service procurement frameworks unbundle equipment from training contracts, forcing vendors to compete on service metrics and clinical education infrastructure. Pressure injury prevention protocols reshape reimbursement coding toward transfer quality documentation. The Midlands manufacturing belt supplies mechanical slide sheet components to European nursing home chains.
Canada
Provincial health authorities consolidate safe patient handling programs across hospital networks, standardizing equipment specifications toward OSHA-aligned injury reduction targets. Home care expansion strains residential infrastructure with unreliable electric access, favoring battery-assisted manual configurations. Ontario's biomedical technology corridor develops wireless load cell systems for real-time caregiver force monitoring.
Global Patient Lateral Transfer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base clusters around three strategic archetypes: integrated bed-system manufacturers leveraging perioperative workflow relationships, ceiling lift specialists extracting recurring revenue from maintenance contracts, and distribution-scale players controlling group purchasing organization channels. Dominant competitive moves include backward integration into motor component supply and clinical education infrastructure acquisition to anchor service-based revenue streams.
Within the integrated-systems tier, Stryker and Getinge AB occupy positions anchoring perioperative workflow solutions, while Arjo exemplifies the installed-base specialist model extracting recurring maintenance revenue from ceiling lift infrastructure. Medline Industries sits within the distribution-scale archetype, leveraging North American group purchasing organization relationships to extend reach into nursing home procurement networks.
| Leading Market Players |
|---|
| Arjo |
| Stryker |
| Hill-Rom |
| Medline Industries |
| Guldmann |
| HoverTech International |
| EZ Way Inc. |
| AliMed |
| Getinge AB |
| Others |
Supply & Pricing Matrix
Brushless DC motor components originating in East Asian manufacturing clusters cascade through three distinct pricing tiers as they reach hospital procurement networks, with freight consolidation and tariff exposure amplifying cost differentials between premium electric systems and mechanical alternatives.
Pricing Analysis
The bundled-versus-unbundled service split now dominates contract negotiations across North American group purchasing organizations. Equipment vendors compete on service metrics and clinical education infrastructure rather than capital cost alone. Price differentiation hinges on FDA safe patient handling certification tier and volume scale through multi-facility enterprise agreements. Pricing pressure stems from mechanical slide sheet durability limits forcing higher replacement frequency. Home care providers exhibit greatest price sensitivity due to capital constraints, while hospital networks prioritize injury reduction documentation over unit cost.
Supply Chain Analysis
Ocean freight rate volatility from East Asian manufacturing hubs to North American and European distribution centers compresses margins on electric transfer systems with heavy motor assemblies. Brushless DC motor production concentrates in China, South Korea, and Japan, while polyester-based friction-reducing fabrics source from Bangladesh and Vietnam. Supply chain risk centers on single-source vulnerability for specialized motor controllers. Distribution runs through group purchasing organization networks and direct hospital procurement channels, with nursing home chains increasingly served through consolidated vendor contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in sensor-integrated documentation systems and recurring service revenue streams, as unbundled training contracts and predictive maintenance capabilities shift value capture from capital sales toward ongoing relationships.
For Market Incumbents: Deepen backward integration into brushless DC motor supply chains to insulate against East Asian lead time volatility. Anchor defensive positioning through acquisition of clinical education infrastructure, as group purchasing organizations now mandate outcome documentation tied to staff injury reduction. Expand predictive maintenance capabilities to transform capital equipment sales into recurring revenue streams. For New Entrants and Emerging Players: Capture home care channel expansion through battery-assisted manual configurations addressing power access limitations in residential settings. Target German rehabilitation centers with hybrid mechanical-electric systems serving variable patient mobility levels. Pursue go-to-market partnerships with biomedical technician training programs to overcome certification gaps constraining electric system adoption. For Investors and Strategic Acquirers: Roll-up economics work for clinical education infrastructure specialists because hospital procurement networks now unbundle equipment from training contracts and compete on service metrics. Long-term viability favors vendors with installed-base density enabling recurring maintenance revenue. Monitor FDA safe patient handling guideline evolution as inflection indicator for sensor-integrated system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker and Getinge AB anchor perioperative workflow relationships through integrated bed-to-transfer solutions. |
| CE Marking Pathway | EU MDR reclassification extends conformity timelines, favoring manufacturers with established notified body relationships. |
| Software Companion Development | Sensor-integrated documentation platforms align with reimbursement coding tied to pressure injury prevention protocols. |
| Reimbursement Strategy | Outcome-based procurement mandates from group purchasing organizations reshape vendor selection criteria toward service metrics. |
| Backward Integration | Captive supply of brushless DC motors insulates against East Asian manufacturing cluster lead time volatility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary research engaged hospital procurement managers, biomedical engineers, GPO contracts specialists, and clinical education directors across acute care networks in the United States, Germany, and Japan. Secondary validation drew from FDA safe patient handling guidance documents, EU MDR conformity assessment databases, METI subsidy program records, and hospital procurement contract disclosures. Bottom-up equipment shipment tracking and top-down healthcare expenditure analysis provided triangulation across market sizing.
Comparable-period anchoring established baseline reference points from historical procurement cycles through replacement demand modeling. The projection horizon spans product type, end user category, technology tier, and application segment dimensions. CAGRs derive from logistic adoption curve fitting against facility infrastructure maturity indicators. Forecast inputs incorporate OSHA enforcement intensity metrics and METI subsidy program renewal trajectories.
Underlying measurement precision varies by segment; electric system forecasts carry tighter precision than manual alternatives due to concentrated vendor reporting. Forecasts reflect assumptions about regulatory enforcement continuity and subsidy program stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Abdominal Pads Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Therapy Pillow Market