
 Asia-Pacific Hospital Supplies Market | 2026-2036
Asia-Pacific Hospital Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Hospital Supplies Market Outlook
Equipment leasing and pay-per-use arrangements for high-value diagnostic systems is rewriting capital deployment across Asia-Pacific hospital networks. Cardinal Health leverages its distribution scale to anchor procurement contracts with multi-hospital chains across India and Southeast Asia. Becton Dickinson specializes in IV therapy and medication management systems that sustain recurring revenue streams in tertiary settings. 3M dominates infection prevention portfolios, competing on disposable surgical drapes and sterilization assurance technologies.
Asia-Pacific hospital supplies encompass sterile and non-sterile consumables, durable medical equipment, and capital-intensive diagnostic apparatus manufactured to ISO and national pharmacopeia standards, primarily serving acute care delivery and surgical intervention workflows. Surgical instruments and wound care products command established volume positions, while diagnostic equipment captures disproportionate margin pools due to technology refresh cycles and imaging modality upgrades. IV supplies maintain steady replacement demand across hospitals and elderly care facilities, though online distribution channels remain underdeveloped relative to direct sales networks in most country markets.
India's CDSCO and China's NMPA enforce divergent registration pathways for imported medical devices, fragmenting compliance costs for multinational suppliers while accelerating local manufacturing incentives. Japan's PMDA and South Korea's MFDS maintain stringent quality system requirements that filter lower-tier competitors from premium hospital tenders. Stakeholders must monitor regulatory harmonization progress under the ASEAN Medical Device Directive and calibrate manufacturing footprints accordingly.
Market Dynamics
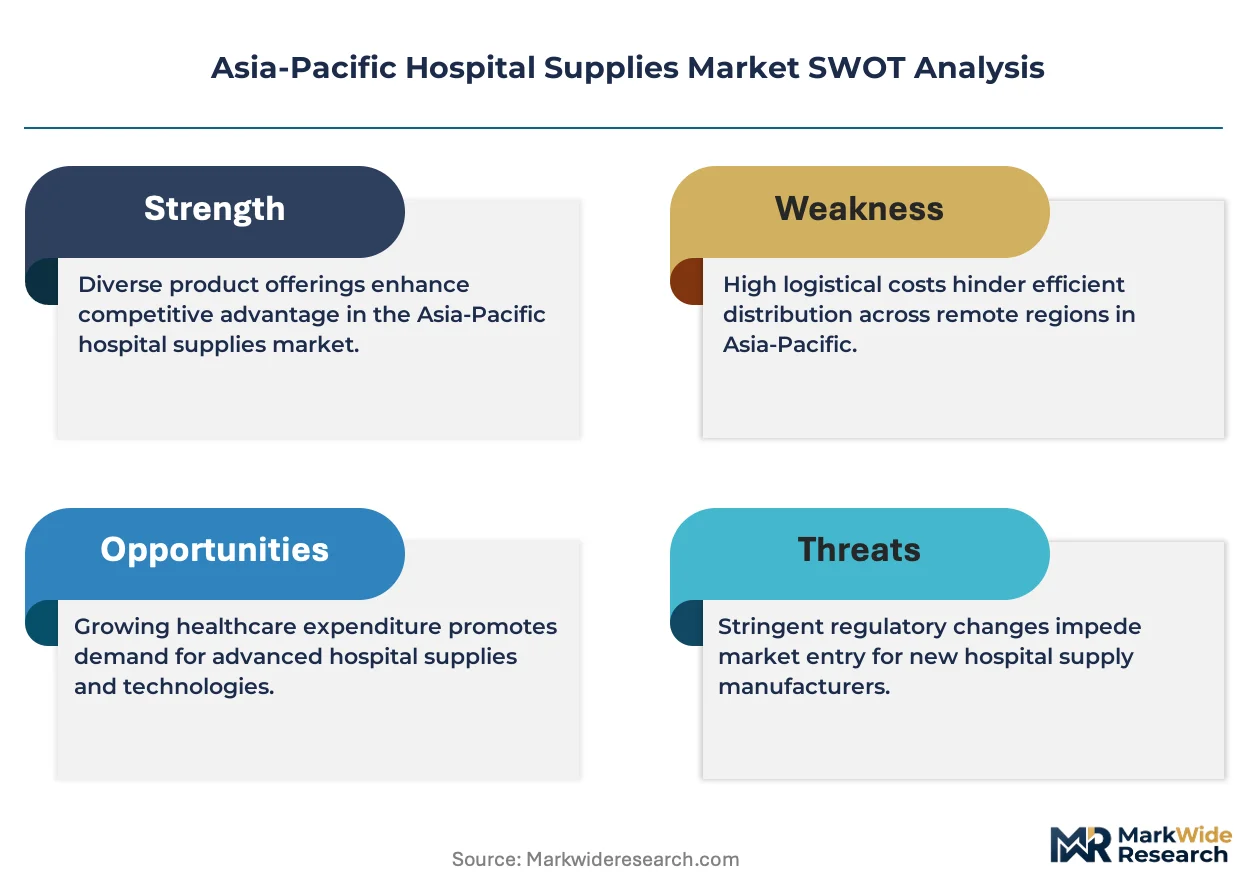
Post-pandemic infection control mandates across India and Southeast Asia are forcing tertiary hospitals to rebuild consumable inventories, while China's NMPA accelerates domestic manufacturing incentives that fragment procurement patterns for multinational suppliers.
Growth Catalysts
- India's PLI scheme for medical devices:The production-linked incentive program redirects capital toward domestic manufacturing hubs, reducing import dependency for sterile consumables and surgical instruments.
- Tier-one city hospital expansion:China's metropolitan corridors in Beijing, Shanghai, and Guangzhou are scaling bed capacity and surgical throughput, driving concentrated demand for advanced wound care and IV therapy systems.
- ASEAN Medical Device Directive harmonization:Regulatory convergence across Thailand, Vietnam, and Indonesia is streamlining market entry for standardized product portfolios, lowering compliance fragmentation costs.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene price swings squeeze margins for disposable surgical drapes and sterilization packaging manufacturers.
- Single-source sterilization services:Gamma and ethylene oxide sterilization capacity concentrates in Thailand and Malaysia, creating geographic vulnerability for just-in-time supply chains.
- Japan PMDA quality system requirements:Stringent documentation and audit protocols filter lower-tier competitors from premium hospital tenders, limiting vendor pool diversity.
Strategic Opportunities
- Vietnam's underpenetrated provincial hospitals:Secondary and tertiary facilities outside Hanoi and Ho Chi Minh City lack consistent supply of advanced infection prevention consumables.
- Equipment-as-a-service models:Pay-per-use arrangements for diagnostic imaging systems are rewriting capital deployment across capital-constrained hospital networks in Indonesia and the Philippines.
- South Korea MFDS fast-track pathways:Expedited review for AI-enabled diagnostic equipment creates regulatory tailwind for smart infusion pumps and automated medication management systems.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993-compliant laboratory services face bottlenecks in India and Southeast Asia, extending product launch timelines for novel materials.
- Legacy ERP integration:Hospital information systems in China's tier-two cities require costly middleware to connect with automated supply chain platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Hospital Supplies Market |
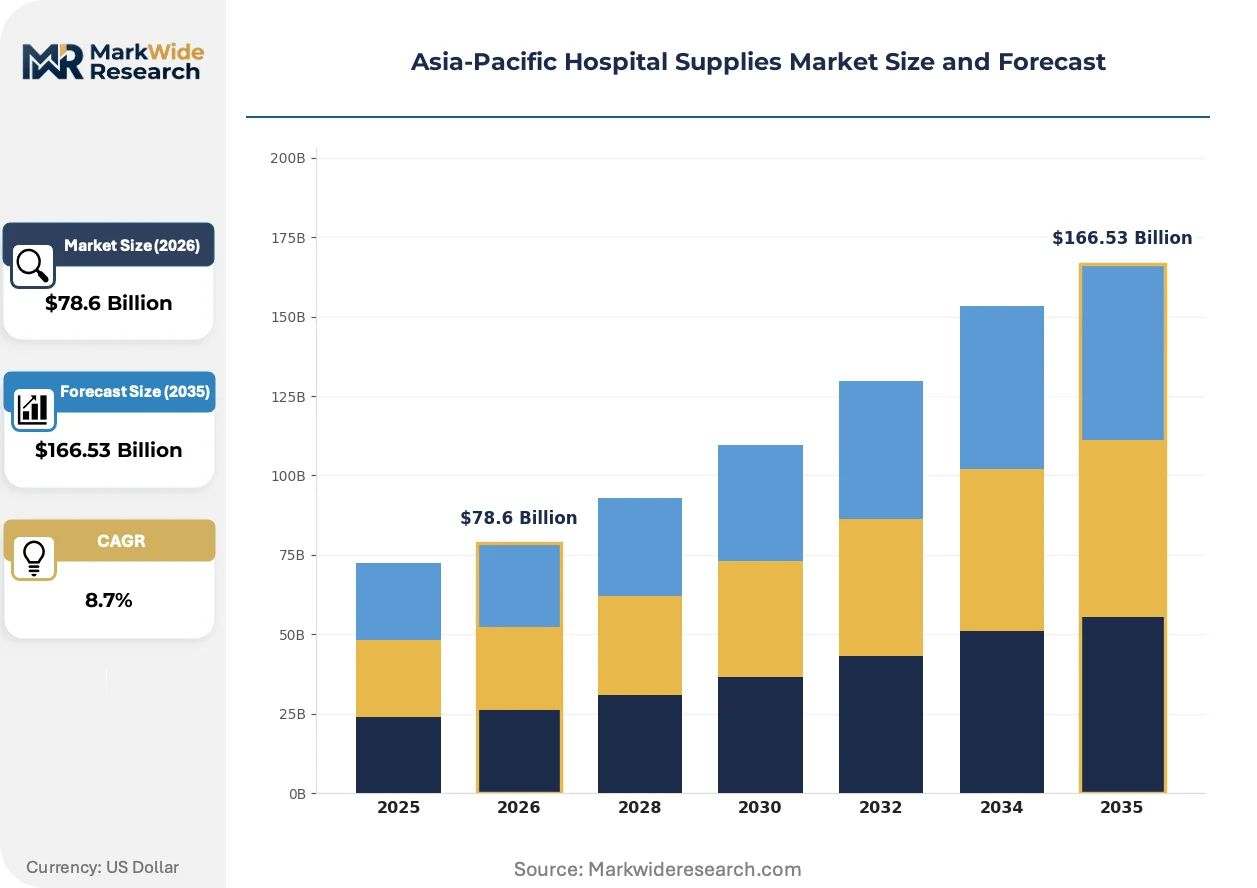
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $166.53 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Equipment, IV Supplies, Wound Care Products End User: Hospitals, Clinics, Elderly Care Facilities, Rehabilitation Centers Delivery Mode: Online Distribution, Direct Sales, Wholesalers, Retail Outlets Application: Emergency Care, General Surgery, Outpatient Procedures, Infection Control |
| Companies Covered | 3M, Cardinal Health, Medtronic, Boston Scientific, B. Braun, Becton Dickinson, Johnson & Johnson, GE Healthcare, Kimberly-Clark, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Hospital Supplies Market Strategic Shifts
Digital inventory management and sterilization assurance technologies are compressing working capital cycles across Asia-Pacific hospital networks, while regulatory divergence between CDSCO and NMPA pathways forces suppliers to maintain parallel compliance infrastructures.
Sterilization assurance technologies incorporating real-time biological indicator monitoring are collapsing the verification timeline for surgical pack release. Tertiary hospitals in Singapore and Australia's major metropolitan centers are adopting these systems to eliminate quarantine holds. This compression is enabling same-day surgical scheduling that was previously impossible under traditional incubation-based protocols.
China's NMPA has tightened clinical evidence requirements for imported Class III medical devices, mandating local trial data that previously accepted foreign studies. Domestic manufacturers in Shenzhen and Suzhou are capturing market share from established suppliers unable to meet accelerated documentation timelines. Korean and Japanese device makers with existing China clinical infrastructure are expanding registration teams to defend positioning.
Group purchasing organizations are consolidating procurement authority across India's multi-hospital chains, displacing fragmented individual hospital negotiations. Apollo, Max, and Fortis networks are centralizing sourcing decisions for high-volume consumables, extracting volume-tier pricing from distributors. This concentration is most visible in Delhi-Mumbai-Bangalore corridors where chain penetration exceeds independent facility purchasing power.
Asia-Pacific Hospital Supplies Market Segmentation
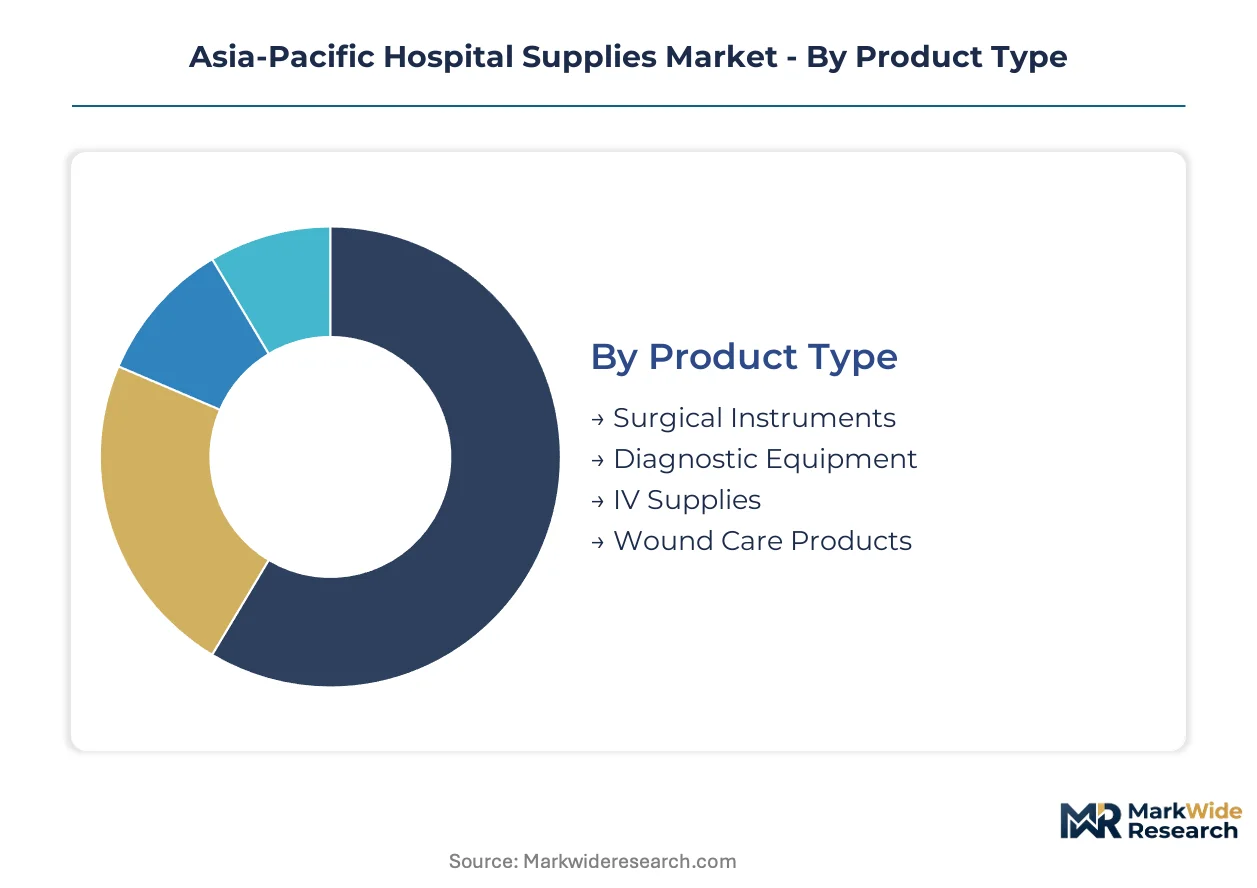
Hospital supplies in Asia-Pacific span acute intervention workflows, chronic disease management, and post-pandemic infection protocols that reshape procurement priorities across facility tiers. Segmentation reveals how capital-intensive diagnostics concentrate margin pools while consumables sustain replacement revenue across India's PLI-backed manufacturing hubs and China's tier-one hospital corridors.
Product Type:
Use-case spectrum spans sterile consumables for routine intervention through capital equipment requiring technology refresh cycles.
- Surgical Instruments:Stainless steel and polymer-composite instruments manufactured to ISO 13485 standards serve open and minimally invasive procedures. India's domestic production under PLI incentives is displacing German and Japanese imports in Delhi-Mumbai procurement corridors.
- Diagnostic Equipment:MRI, CT, and ultrasound systems with AI-enabled imaging software command premium positioning. China's NMPA local trial mandates favor Shenzhen and Suzhou manufacturers with established clinical infrastructure.
- IV Supplies:Infusion sets, catheters, and fluid management systems maintain steady replacement schedules across tertiary and elderly care networks.
- Wound Care Products:Advanced dressings incorporating antimicrobial silver and hydrocolloid substrates address diabetic and post-surgical patient populations.
Established volume favors surgical instruments; emerging adoption favors diagnostic equipment with embedded AI capabilities.
End User:
Customer type stratification reflects acuity levels, reimbursement frameworks, and procurement centralization intensity.
- Hospitals:Tertiary facilities with 500+ beds drive concentrated demand for infection control consumables and capital diagnostics. India's Apollo, Max, and Fortis chains are consolidating GPO authority across Delhi-Mumbai-Bangalore corridors.
- Clinics:Outpatient and specialty clinics prioritize portable diagnostic devices and rapid-turn consumables with minimal inventory carrying costs.
- Elderly Care Facilities:Japan's aging demographic and China's expanding eldercare infrastructure sustain IV therapy and pressure ulcer prevention product demand.
- Rehabilitation Centers:Post-acute facilities in South Korea and Australia require durable mobility aids and wound management systems for long-stay patients.
Procurement scale concentrates in hospitals; patient volume expansion is climbing the fastest in elderly care facilities.
Delivery Mode:
Supply concentration varies by channel maturity, with direct sales networks dominating high-value transactions.
- Direct Sales:Capital equipment and high-volume consumable contracts route through manufacturer representatives serving multi-hospital chains. Cardinal Health leverages distribution scale to anchor procurement agreements across India and Southeast Asia.
- Online Distribution:E-procurement platforms remain underdeveloped relative to direct channels, though tier-two Chinese hospitals are piloting automated reorder systems.
- Wholesalers:Regional distributors manage inventory for provincial facilities outside Vietnam's Hanoi and Ho Chi Minh City corridors.
- Retail Outlets:Pharmacies and medical supply stores serve home healthcare and small clinic segments with limited warehousing capacity.
Channel control favors direct sales for premium tiers; digital penetration is gaining share fastest in China's secondary markets.
Application:
Clinical workflow segmentation aligns with reimbursement intensity and regulatory scrutiny levels.
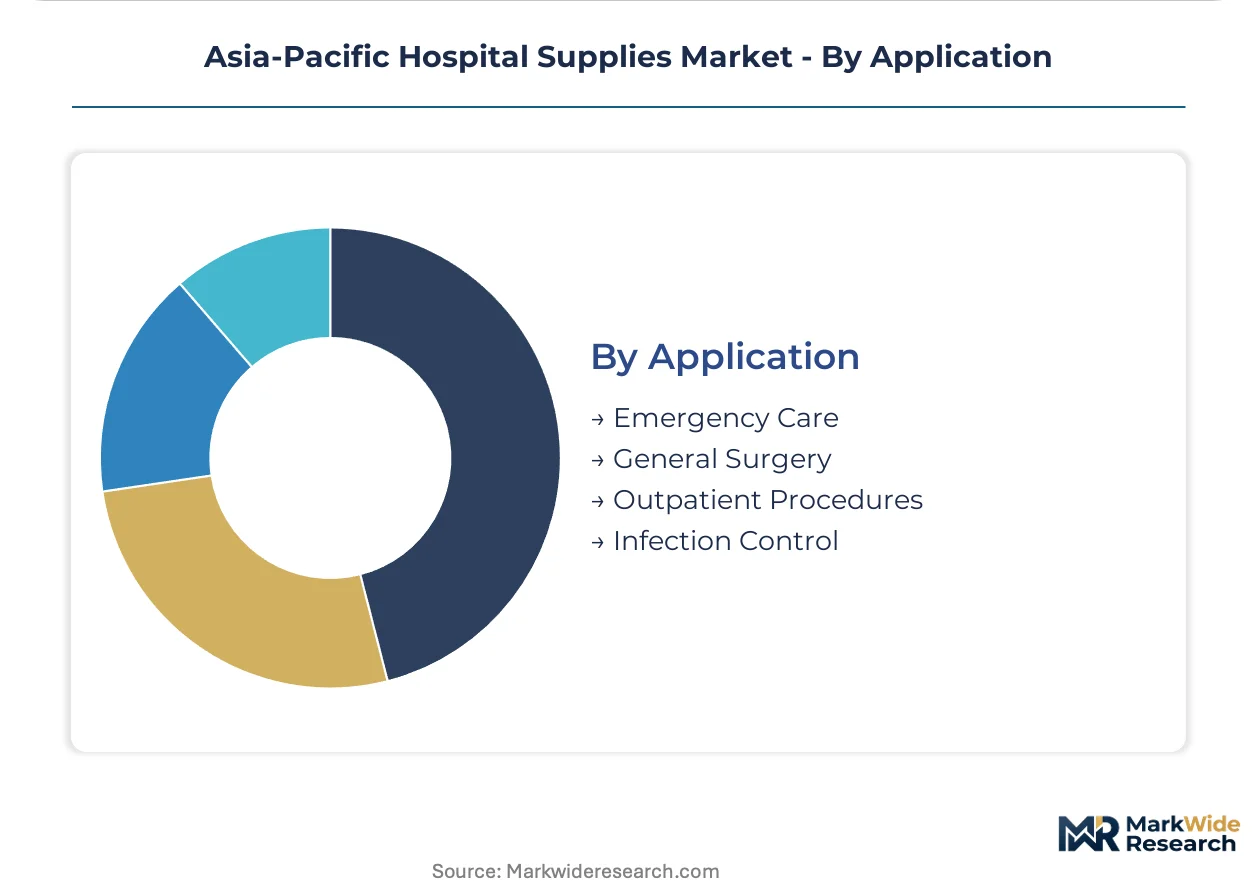
- Infection Control:Sterile drapes, sterilization packaging, and biological indicator systems address post-pandemic preparedness mandates. 3M dominates disposable surgical drape portfolios competing on sterilization assurance technologies.
- General Surgery:Laparoscopic and open procedure consumables sustain high-throughput utilization in China's Beijing-Shanghai-Guangzhou hospital clusters.
- Emergency Care:Trauma kits, airway management devices, and rapid-infusion systems serve accident and emergency departments with unpredictable demand spikes.
- Outpatient Procedures:Ambulatory surgical centers in South Korea and Singapore require compact instrument sets and same-day discharge wound care protocols.
Regulatory priority favors infection control; procedural volume expansion is steepest in outpatient settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-hospital chains and tertiary procurement networks concentrate purchasing power across metropolitan corridors, while divergent regulatory pathways force suppliers to maintain parallel compliance infrastructures across national boundaries.
China
NMPA's tightened clinical evidence requirements for imported Class III devices mandate local trial data that domestic Shenzhen and Suzhou manufacturers leverage to capture share from established suppliers. Tier-one cities Beijing, Shanghai, and Guangzhou scale bed capacity and surgical throughput, driving concentrated demand for advanced wound care systems. Domestic production hubs in the Yangtze River Delta accelerate manufacturing of sterile consumables under national dual carbon goals.
India
Apollo, Max, and Fortis multi-hospital chains consolidate group purchasing organization authority across Delhi-Mumbai-Bangalore corridors, extracting volume-tier pricing from distributors. CDSCO registration pathways for imported medical devices fragment compliance costs while the PLI scheme redirects capital toward domestic manufacturing hubs for surgical instruments. Gujarat and Maharashtra production clusters displace German and Japanese imports in high-volume consumable categories.
Japan
PMDA quality system requirements with stringent documentation and audit protocols filter lower-tier competitors from premium hospital tenders, limiting vendor pool diversity for sterile drapes and IV therapy systems. METI standards support domestic manufacturing of advanced diagnostic equipment. Kanto region hospitals around Tokyo anchor demand for infection prevention portfolios with embedded sterilization assurance technologies.
South Korea
MFDS fast-track pathways for AI-enabled diagnostic equipment create regulatory tailwind for smart infusion pumps and automated medication management systems. Seoul Capital Area hospitals drive procurement of capital-intensive imaging systems with embedded AI software. Busan-Ulsan manufacturing clusters supply regional export markets with ISO 13485-certified surgical instruments.
Vietnam
Secondary and tertiary facilities outside Hanoi and Ho Chi Minh City corridors lack consistent supply of advanced infection prevention consumables, creating penetration opportunities for distributors. Provincial hospital networks operate through regional wholesalers with limited warehousing capacity. Central Vietnam manufacturing zones under ASEAN Medical Device Directive harmonization attract contract sterilization services investment.
Asia-Pacific Hospital Supplies Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement networks, producing a tiered structure where distribution scale anchors multi-hospital contracts against technology-driven recurring revenue models. The vendor base separates into three strategic archetypes: diversified health conglomerates with cross-portfolio bundling power, sterile consumable specialists with infection prevention focus, and diagnostic equipment manufacturers with technology refresh cycles. Competitive moves concentrate on strategic partnerships with group purchasing organizations and backward integration into sterilization services to reduce geographic supply vulnerability.
Among diversified health conglomerates, 3M and Cardinal Health occupy positions that exemplify contrasting scale advantages. 3M represents the product-specialist archetype with concentrated infection prevention portfolios competing on disposable surgical drapes and sterilization assurance technologies. Cardinal Health anchors the channel-control vector, leveraging distribution scale to secure procurement contracts with multi-hospital chains across India and Southeast Asia. Becton Dickinson sits within the recurring-revenue tier, specializing in IV therapy and medication management systems that sustain steady replacement demand in tertiary settings.
| Leading Market Players |
|---|
| 3M |
| Cardinal Health |
| Medtronic |
| Boston Scientific |
| B. Braun |
| Becton Dickinson |
| Johnson & Johnson |
| GE Healthcare |
| Kimberly-Clark |
| Others |
Value Chain & Pricing Dynamics
Thailand's gamma and ethylene oxide sterilization clusters anchor regional supply capacity, creating pricing leverage for consumable manufacturers serving India's Apollo-Fortis procurement networks and China's tier-one hospital corridors. Polypropylene feedstock volatility from Southeast Asian petrochemical hubs feeds directly into margin compression for disposable surgical drape producers competing on sterilization assurance technologies.
Pricing Analysis
Certification level (ISO 13485/CE/FDA-grade) creates the primary spread between premium and standard tiers in Asia-Pacific hospital supply contracts. Three-tier pricing structure across premium, standard, and economy levels dominates procurement negotiations, with CDSCO and NMPA registration status acting as secondary price escalators. Cost compression in standard-grade consumables is intensifying because India's PLI-backed domestic manufacturers undercut imported equivalents on Delhi-Mumbai tenders. Tier-two provincial hospitals in Vietnam and Indonesia exhibit highest price sensitivity, while Singapore's tertiary facilities prioritize sterilization assurance over unit cost.
Supply Chain Analysis
Petrochemical feedstock from Thailand, Malaysia, and South Korea feeds into polypropylene and polyethylene resin production for sterile packaging and surgical drape substrates. Raw material dependencies center on propylene monomer, medical-grade polymer additives, and ethylene oxide sterilization gases. Single-source sterilization capacity concentration in Bangkok and Kuala Lumpur corridors creates geographic vulnerability for just-in-time supply chains serving India's multi-hospital chains. Distribution runs through Cardinal Health's regional hubs and B. Braun's country-level subsidiaries, with direct sales networks controlling premium diagnostic equipment flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific hospital supplies function as a service-attach opportunity where sterilization assurance subscriptions and equipment-as-a-service contracts expand faster than capital hardware sales. Recurring revenue from biological indicator monitoring systems and pay-per-use diagnostic arrangements outpaces transactional consumable growth across Indonesia and Philippine hospital networks.
For Market Incumbents: Harden sterilization service backward integration to capture margin pools currently leaking to third-party gamma and ethylene oxide providers in Thailand and Malaysia. Anchor procurement contracts with India's consolidating GPO networks before PLI-backed domestic manufacturers achieve CDSCO registration parity on high-volume consumables. Defend positioning by embedding AI-enabled inventory management software into IV therapy system deployments, creating switching costs that filter price-only competitors from Apollo-Fortis tenders. For New Entrants and Emerging Players: Pursue Vietnam's underpenetrated provincial hospital tier outside Hanoi and Ho Chi Minh City corridors, where regional wholesalers lack consistent supply of advanced infection prevention consumables. Target secondary cities in China's tier-two hospital expansion zones, where legacy ERP systems require middleware partnerships rather than full platform displacement. Enter through sterilization assurance technology licensing rather than capital-intensive manufacturing, leveraging MFDS fast-track pathways for AI-enabled diagnostic companions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sterilization assurance specialists with embedded software recurring revenue over commodity consumable manufacturers facing PLI-driven price erosion. Long-term viability through the next refresh cycle hinges on regulatory moats—CDSCO and NMPA registration infrastructure that domestic challengers cannot replicate within standard investment horizons. Acquisition targets should demonstrate established China clinical trial capabilities or India GPO contract anchoring. Monitor ASEAN Medical Device Directive harmonization progress as the inflection signal for cross-border scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Sterilization Service Backward Integration | Captures margin pools from Thailand's concentrated gamma and ethylene oxide providers serving India procurement networks. |
| AI-Enabled Inventory Management Development | Creates switching costs in China's tier-two hospitals with legacy ERP middleware requirements. |
| CDSCO Fast-Track Registration Investment | Accelerates market entry before PLI-backed domestic manufacturers achieve parity on surgical instruments. |
| Equipment-as-a-Service Model Deployment | Rewrites capital deployment for Indonesia and Philippine hospitals constrained by procurement budgets. |
| ASEAN Medical Device Directive Harmonization Alignment | Streamlines compliance costs across Thailand, Vietnam, and Indonesia procurement corridors. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital procurement committee members, biomedical engineering directors, GPO contracts managers, and sterile consumable manufacturing executives. Secondary validation drew from CDSCO registration databases, NMPA clinical trial filings, hospital procurement contract disclosures, ASEAN Medical Device Directive implementation timelines, and customs trade data on polymer resin imports. Bottom-up facility-level demand modeling and top-down macro health expenditure triangulation anchored volume estimates.
Calibration against historical CAGRs from parallel medical device categories and cross-referencing with national health infrastructure investment plans shaped trajectory assumptions across the analysis window. Segmentation dimensions spanned product type (surgical instruments, diagnostic equipment, IV supplies, wound care), end user (hospitals, clinics, elderly care, rehabilitation), delivery mode (direct sales, online, wholesale, retail), and application workflow (infection control, general surgery, emergency care, outpatient). CAGRs derived from fitted growth curves applied to base-year sizing, with NMPA registration velocity and PLI scheme disbursement pacing as key forecast inputs.
Sensitivities concentrate around NMPA regulatory tightening timelines, PLI scheme extension decisions, and petrochemical feedstock price volatility. Forecasts embed assumptions regarding ASEAN harmonization progress and sterilization capacity expansion in Thailand-Malaysia corridors. Cross-checking against national health expenditure statistics and hospital bed capacity expansion plans from China's tier-one cities and India's metropolitan corridors is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Abdominal Pads Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market