
 Stretcher Accessories Market | 2026-2036
Stretcher Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Stretcher Accessories Market Analytics
Premium stretcher accessories built from antimicrobial-coated aluminum and custom-molded foam is decoupling from commodity polyester straps and basic nylon carriers on specification sheets and procurement criteria. Stryker Corporation leverages its integrated hospital bed and stretcher ecosystem to bundle accessories under long-term service contracts. Hill-Rom Holdings anchors its position through dedicated emergency department retrofit programs that specify proprietary rail and hook geometries.
Stretcher accessories comprise patient restraint straps, transfer carriers, positioning pads, and mounting hooks engineered to interface with stretcher rail systems, gurney frames, and wheelchair platforms; specifications typically address load ratings, biocompatibility per ISO 10993, and flame resistance under NFPA 701 or equivalent textile standards. The accessories serve to secure patients during transport, prevent falls, and enable safe lateral transfers in acute care and pre-hospital settings. Pads manufactured from viscoelastic and high-density foam formulations command margin premiums over basic polyester and nylon straps, which face price compression from commoditized Asian supply. Aluminum rail-compatible hooks and quick-release carriers represent the fastest-expanding compatibility segment as electric stretcher adoption rises in tertiary hospitals.
FDA device regulations govern patient restraint classification and biocompatibility documentation for accessories contacting skin or mucous membranes, while ISO 13485 quality management standards shape supplier qualification protocols for original equipment manufacturers. The EU Medical Device Regulation imposes additional clinical evaluation requirements on accessories classified as Class I reusable surgical instruments, tightening market access for non-European producers. Stakeholders must monitor evolving FDA guidance on software-integrated stretcher systems, as sensor-enabled accessories could trigger premarket notification requirements that reshape competitive entry barriers.
Market Dynamics
Electric stretcher adoption in tertiary hospitals is forcing accessory manufacturers to redesign rail-compatible hooks and quick-release carriers for automated load-bearing systems, compressing development cycles and recalibrating load-rating specifications.
Growth Catalysts
- Emergency medical protocol tightening:Ambulance services across the United States are expanding procurement of patient restraint systems to meet updated pre-hospital care standards.
- ISO 10993 biocompatibility mandates:Skin-contact accessories must now document material safety testing, elevating specification barriers for premium foam and coated aluminum products.
- Antimicrobial material innovation:Viscoelastic foam formulations with integrated silver-ion coatings are displacing basic polyester straps in hospital capital expenditure decisions.
Market Restraints
- Commoditized Asian supply:Basic nylon straps and polyester carriers from concentrated manufacturing clusters in China and Vietnam are compressing margins on entry-level accessories.
- EU MDR clinical evaluation requirements:Accessories classified as Class I reusable surgical instruments face tightened market access and extended documentation timelines for non-European producers.
- Aluminum price volatility:Rail-compatible hook production depends on aerospace-grade aluminum feedstock subject to tariff and energy-cost fluctuations.
Strategic Opportunities
- Sensor-enabled accessory integration:Weight-distribution pads with embedded pressure sensors are converging with electric stretcher control systems to enable real-time patient monitoring.
- Long-term service contract bundling:Hospital bed and stretcher ecosystem providers are unbundling accessory procurement from equipment leases, creating recurring revenue channels.
- Emergency department retrofit programs:Proprietary rail and hook geometries specified in dedicated infrastructure upgrades lock in accessory compatibility for decade-long replacement cycles.
Industry Challenges
- ISO 13485 supplier qualification complexity:Original equipment manufacturers demand documented quality management systems that stretch mid-tier foam fabricators beyond current capabilities.
- Legacy stretcher fleet incompatibility:Electric stretcher accessories must maintain backward compatibility with manual gurney rail geometries, multiplying SKU complexity and inventory carrying costs.
- FDA software-integrated device guidance uncertainty:Sensor-enabled accessories risk triggering premarket notification requirements that reshape competitive entry barriers before formal rulemaking concludes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretcher Accessories Market |
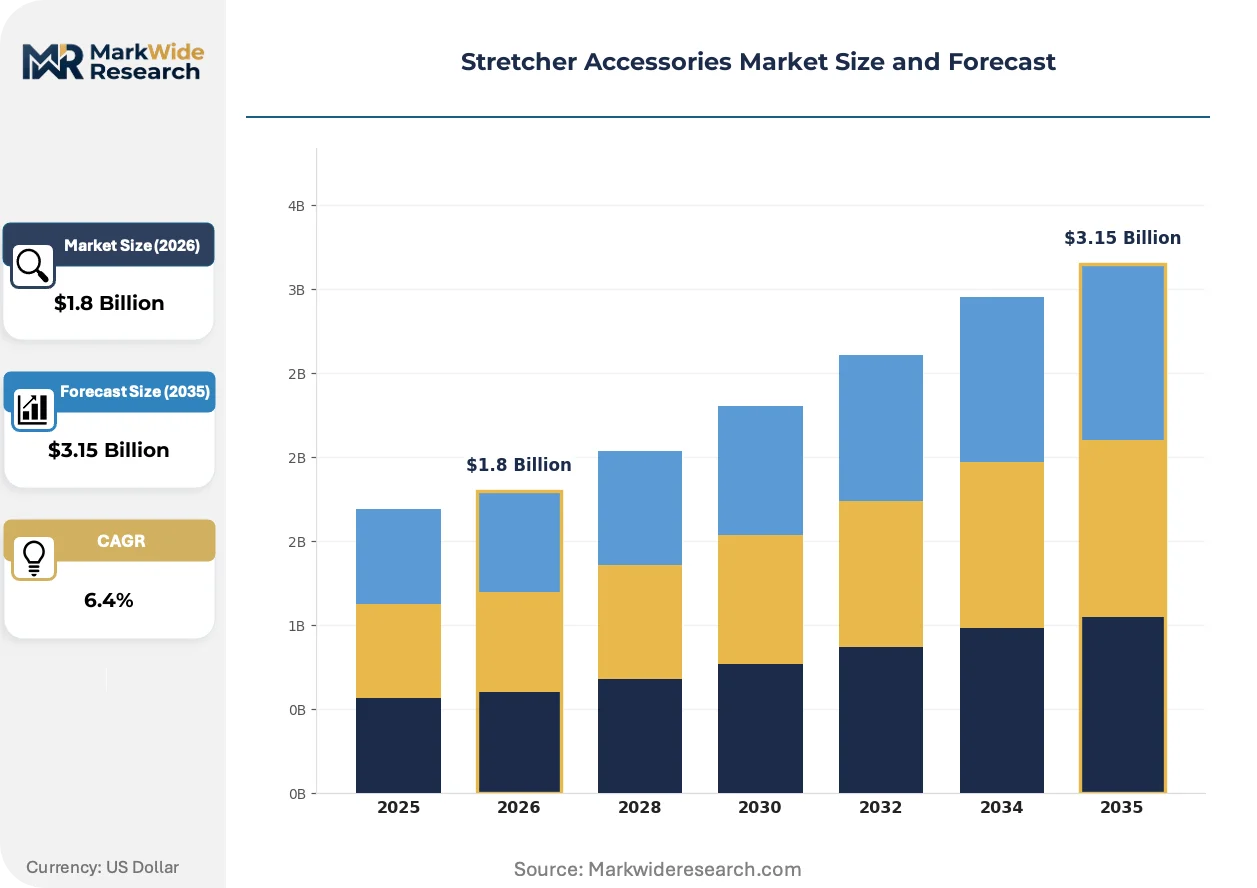
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straps, Carriers, Pads, Hooks Material: Polyester, Nylon, Aluminum, Foam End User: Hospitals, Ambulance Services, Fire Departments, Military Compatibility: Manual Stretchers, Electric Stretchers, Wheelchairs, Gurneys |
| Companies Covered | Stryker Corporation, Invacare Corporation, Getinge Group, Hill-Rom Holdings, Etac AB, Permobil AB, DJO Global, Sunrise Medical, Stiegelmeyer & Co. GMBH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretcher Accessories Market Evolving Landscape
Material science advances and regulatory precision are elevating specification requirements while procurement consolidation favors integrated ecosystem providers over standalone accessory vendors.
Antimicrobial-coated aluminum rail systems are converging with custom-molded viscoelastic foam positioning pads to create premium accessory bundles that command specification priority on hospital procurement sheets. Tertiary hospitals with electric stretcher fleets are specifying these integrated systems for lateral transfer safety and pressure-ulcer prevention. This convergence is compressing demand for commodity polyester straps and basic nylon carriers into price-sensitive secondary markets.
The FDA's updated device classification rules for patient handling equipment are pressuring manufacturers toward comprehensive biocompatibility testing and traceability documentation for all skin-contact accessories. Industrial consequence includes extended product development timelines and elevated regulatory affairs staffing requirements. Small and mid-tier foam fabricators without in-house biocompatibility testing capabilities are outsourcing to third-party laboratories, adding cost layers that disadvantage non-integrated competitors.
Hospital procurement departments are consolidating stretcher accessory purchasing under long-term equipment service contracts rather than standalone capital expenditure cycles. This shift disintermediates traditional medical supply distributors and channels volume directly to stretcher original equipment manufacturers with captive accessory lines. The United States exhibits this pattern most visibly, where hospital system consolidation has concentrated buying power among integrated delivery networks negotiating enterprise-wide agreements.
Stretcher Accessories Market Segmentation
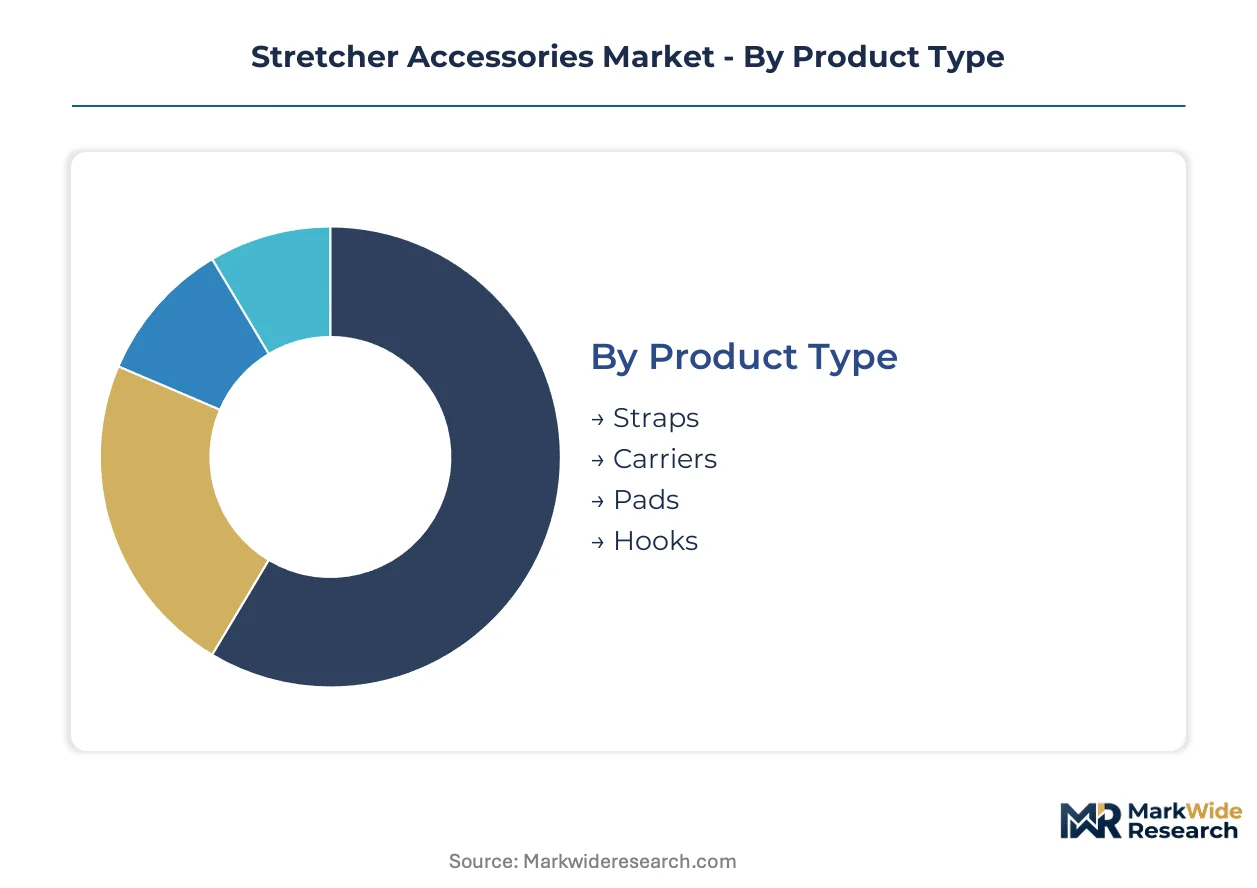
Stretcher accessories fragment across four distinct taxonomies that reshape procurement patterns and margin structures. Product type and material composition determine specification priority on hospital capital expenditure sheets, while end-user category and stretcher compatibility govern distribution channel selection and replacement cycle timing.
Product Type:
Customization intensity varies sharply across this category, with patient-specific molding capabilities at one extreme and commodity interchangeability at the other.
- Pads:Viscoelastic and high-density foam formulations with antimicrobial silver-ion coatings command specification priority in tertiary hospital procurement. Demand concentrates in United States emergency departments where pressure-ulcer prevention protocols drive capital allocation toward molded positioning surfaces.
- Hooks:Rail-compatible aluminum quick-release mechanisms engineered for electric stretcher load-bearing systems represent the steepest expansion trajectory as automated patient handling spreads. United States hospital retrofit programs specify proprietary geometries that lock in decade-long replacement cycles.
- Straps:Basic polyester and nylon patient restraint systems face margin compression from commoditized Asian supply clusters.
- Carriers:Transfer platforms designed for lateral patient movement between stretcher and bed frames.
Leading the category by volume: Straps. Growing fastest: Hooks.
Material:
Cost tier stratification separates aerospace-grade feedstocks from commodity textile inputs, with biocompatibility documentation requirements widening the specification gap.
- Foam:Custom-molded viscoelastic formulations with integrated antimicrobial coatings displace basic alternatives in premium hospital contracts. ISO 10993 skin-contact documentation requirements elevate barriers for mid-tier fabricators lacking in-house testing capabilities.
- Aluminum:Aerospace-grade rail-compatible hooks and mounting hardware depend on tariff-vulnerable feedstock subject to energy-cost volatility. United States electric stretcher adoption forces redesign cycles for automated load-bearing specifications.
- Polyester:Commodity textile straps from concentrated Chinese and Vietnamese manufacturing clusters.
- Nylon:Basic carrier and restraint webbing facing price compression in secondary markets.
Dominating procurement value: Foam. Expanding most quickly: Aluminum.
End User:
Application urgency determines specification tolerance, with pre-hospital emergency protocols demanding rapid-deployment compatibility against inpatient care's precision requirements.
- Hospitals:Tertiary care facilities with electric stretcher fleets specify integrated antimicrobial pad and aluminum hook bundles under long-term service contracts. United States hospital system consolidation channels volume through integrated delivery network enterprise agreements.
- Ambulance Services:Pre-hospital emergency medical protocol tightening drives patient restraint system procurement across United States municipal and private fleets.
- Fire Departments:Rapid-extrication scenarios require backward-compatible hook geometries spanning legacy manual and modern electric stretcher rails.
- Military:Field-deployable accessories prioritizing durability and multi-platform compatibility.
Commanding largest procurement volume: Hospitals. Gaining share fastest: Ambulance Services.
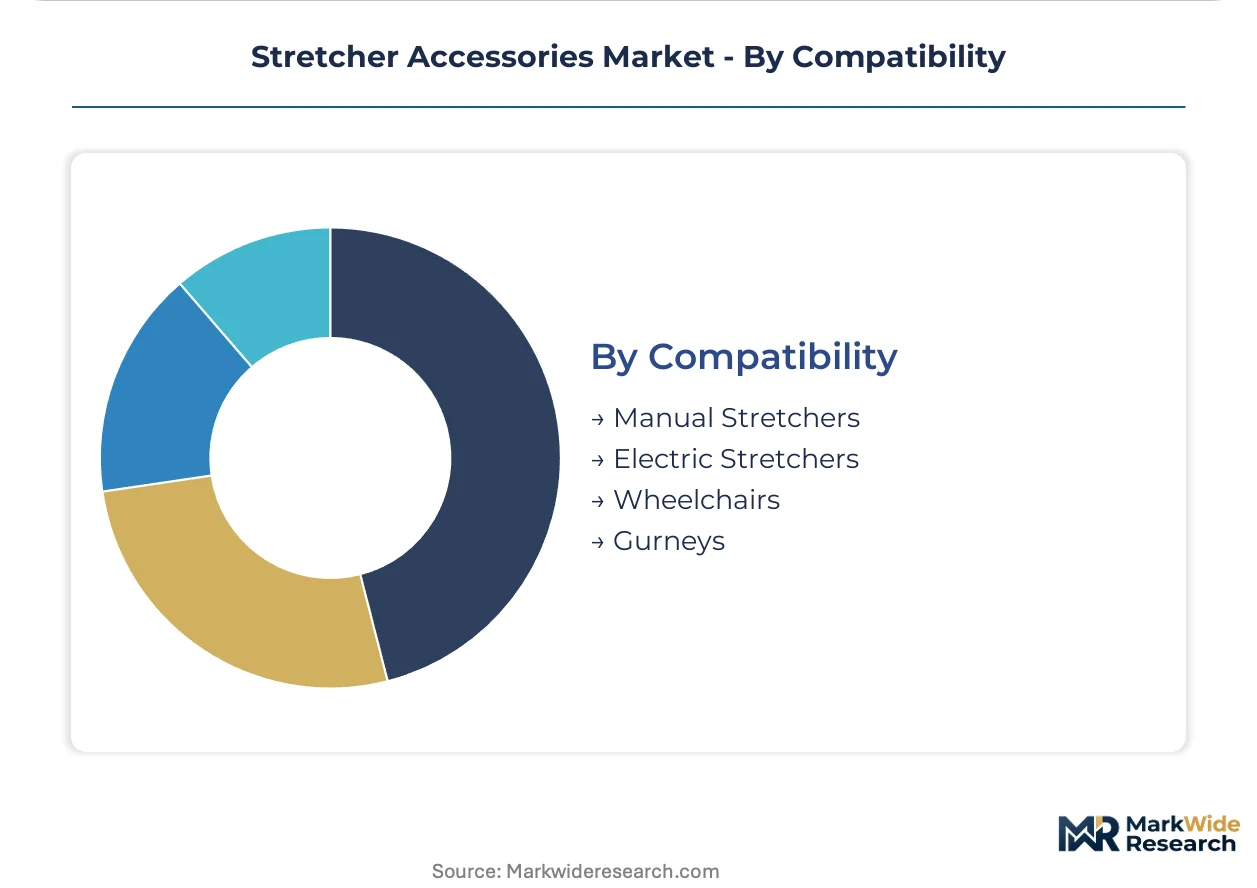
Compatibility:
Technology maturity separates legacy manual systems from sensor-integrated electric platforms, with backward compatibility requirements multiplying SKU complexity.
- Electric Stretchers:Automated load-bearing systems with embedded control interfaces demand redesigned rail-compatible hooks and quick-release carriers. FDA software-integrated device guidance uncertainty creates regulatory risk for sensor-enabled weight-distribution pads.
- Manual Stretchers:Legacy gurney rail geometries persist in secondary markets and developing facility infrastructure, forcing accessory manufacturers to maintain dual compatibility specifications.
- Wheelchairs:Transfer and positioning accessories for bariatric and standard mobility platforms.
- Gurneys:Basic transport frames in cost-constrained settings.
Highest replacement cycle value: Electric Stretchers. Widest installed base: Manual Stretchers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American stretcher accessory demand through its dense cluster of hospital system headquarters and medical device engineering centers. Tertiary hospitals across the metropolitan statistical area specify antimicrobial aluminum rail systems under integrated service contracts. This procurement concentration ripples through distributor networks serving the Upper Midwest emergency medical corridor.
United States
Hospital capital expenditure on emergency department infrastructure drives specification of premium foam positioning pads and electric stretcher-compatible hooks. FDA device classification rules for patient handling equipment mandate biocompatibility documentation and traceability systems. The Minneapolis-St. Paul corridor concentrates engineering talent for rail geometry design, while Texas Medical Center hospitals in Houston pilot sensor-enabled weight-distribution accessories.
Germany
Baden-Württemberg's medical technology cluster advances ISO 13485-certified accessory production for export markets. EU Medical Device Regulation clinical evaluation requirements filter market access for Class I reusable surgical instruments. Stuttgart-based engineering firms specialize in aluminum quick-release mechanisms for automated load-bearing systems, supplying tertiary hospitals across Bavaria and North Rhine-Westphalia.
China
Concentrated manufacturing in Zhejiang and Jiangsu provinces supplies commodity polyester straps and nylon carriers to price-sensitive secondary markets. NMPA medical device registration requirements tighten for skin-contact accessories entering domestic hospital procurement channels. Suzhou's industrial park hosts foam fabricators upgrading antimicrobial coating capabilities to meet ISO 10993 documentation standards for export contracts.
Japan
Tokyo's integrated delivery networks specify proprietary rail geometries under decade-long equipment service agreements. PMDA quality management standards shape supplier qualification protocols for stretcher original equipment manufacturers. Osaka-based metal fabricators engineer aerospace-grade aluminum hooks for electric stretcher fleets in Kansai region tertiary hospitals.
United Kingdom
NHS procurement consolidation channels stretcher accessory volume through national framework agreements favoring integrated ecosystem providers. MHRA medical device regulations align with EU MDR documentation timelines for post-Brexit market access. London's teaching hospitals specify custom-molded viscoelastic pads for pressure-ulcer prevention protocols, driving premium segment demand.
Stretcher Accessories Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the stretcher accessories market. Integrated hospital bed and stretcher manufacturers control specification channels through captive accessory lines and long-term service contracts. Three archetypes dominate: ecosystem-integrated original equipment manufacturers, specialized foam and metal fabricators, and commoditized Asian textile suppliers. Competitive positioning hardens through proprietary rail geometry specifications and backward integration into antimicrobial material formulation.
Among ecosystem-integrated manufacturers, Stryker Corporation and Hill-Rom Holdings exemplify the service-contract bundling archetype that locks hospital procurement into decade-long replacement cycles. Etac AB represents the specialized European fabricator segment navigating EU MDR clinical evaluation requirements. These three anchors illustrate how regulatory documentation capabilities and captive distribution channels separate premium-tier positioning from commodity price competition.
| Leading Market Players |
|---|
| Stryker Corporation |
| Invacare Corporation |
| Getinge Group |
| Hill-Rom Holdings |
| Etac AB |
| Permobil AB |
| DJO Global |
| Sunrise Medical |
| Stiegelmeyer & Co. GMBH |
| Others |
Value Network & Pricing Analysis
Aerospace-grade aluminum LME price volatility cascades through stretcher accessory manufacturing, compressing margins on rail-compatible hooks while antimicrobial foam formulations absorb cost pass-through in premium hospital contracts. Commodity polyester and nylon feedstock from Asian textile clusters anchors economy-tier pricing, creating divergence between specification-grade and price-sensitive procurement channels.
Pricing Analysis
Outcome-based pricing tied to pressure-ulcer prevention protocols anchors premium tier valuations for antimicrobial-coated viscoelastic pads. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-documented foam products from basic polyester straps and uncoated nylon carriers. Cost compression in commodity straps intensifies because concentrated Vietnamese and Chinese manufacturing clusters flood secondary markets. Ambulance services exhibit highest price sensitivity due to municipal budget constraints, while tertiary hospital IDNs prioritize specification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates in United States hospital procurement are reshaping sourcing toward North American aluminum fabricators and ISO 13485-certified foam molders. Supply concentrates in Zhejiang and Jiangsu provinces for commodity textiles, Baden-Württemberg for precision aluminum mechanisms, and Minnesota for integrated pad-and-hook bundles. Raw material dependencies draw from aerospace-grade aluminum feedstock, silver-ion antimicrobial additives, and high-density polyurethane foam precursors. Tariff exposure on Chinese textile imports presents structural risk for economy-tier distributors. Distribution runs through stretcher OEM captive channels and GPO-negotiated framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stretcher accessories market is becoming a vertical-integration race as players pursue backward integration into antimicrobial material formulation to escape commodity price compression.
For Market Incumbents: Anchor specification control through proprietary rail geometry patents that lock hospital systems into decade-long replacement cycles. Deepen captive foam fabrication capabilities to secure ISO 10993 documentation in-house, reducing third-party laboratory dependence. Defend against Asian textile suppliers by bundling accessories under long-term equipment service contracts that disintermediate traditional distributors.
For New Entrants and Emerging Players: Capture ambulance service procurement channels where emergency medical protocol tightening outpaces incumbent coverage. Target municipal fleet retrofit programs in United States secondary markets where price sensitivity exceeds brand loyalty. Pursue white-label manufacturing partnerships with stretcher OEMs seeking to unbundle accessory lines without captive production investment.
For Investors and Strategic Acquirers: The window for entry favors specialized foam fabricators with antimicrobial coating capabilities and documented ISO 13485 quality systems. Long-term viability hinges on regulatory documentation moats widening under FDA device classification evolution and EU MDR clinical evaluation requirements. Watch for FDA software-integrated device guidance finalization as inflection indicator for sensor-enabled accessory valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Biocompatibility Certification | FDA device classification rules mandate skin-contact documentation for premium market access. |
| Antimicrobial Material Backward Integration | In-house silver-ion coating capabilities reduce third-party laboratory cost layers. |
| Electric Stretcher Compatibility Redesign | Automated load-bearing specifications force rail-compatible hook development cycles. |
| Long-term Service Contract Bundling | Hospital IDN consolidation channels volume through integrated equipment agreements. |
| Sensor-Enabled Accessory Development | Pressure-distribution pads with embedded monitoring converge with stretcher control systems. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across hospital procurement managers, biomedical engineers, GPO contracts specialists, and ambulance fleet operations directors. FDA 510(k) submissions, EU MDR technical documentation, ISO 13485 audit reports, and hospital capital expenditure databases provided segmentation baselines. Bottom-up product-type volume estimates triangulated against top-down end-user spending patterns.
Data-stream reconciliation across electric stretcher adoption curves, antimicrobial material cost indices, and regulatory timeline projections shaped the analytical framework across the analysis window. Segmentation dimensions modeled include product type, material composition, end-user category, and stretcher compatibility tier. CAGRs derived from elasticity-adjusted replacement cycle timing and hospital capital expenditure allocation patterns. Aluminum price volatility coefficients and biocompatibility testing backlog durations informed scenario-weighted outputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA software-integrated device guidance timing and EU MDR enforcement consistency. Forecasts reflect documented assumptions regarding electric stretcher penetration rates and ISO 10993 certification backlog resolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Abdominal Pads Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Self Inflating Bag Market