
 Therapy Pillow Market | 2026-2036
Therapy Pillow Market Size, Share, and Industry Trends Forecast 2026-2036
Therapy Pillow Market Insights
Modular pillow systems with interchangeable inserts and adjustable loft components is pivoting how physical therapy clinics and direct-to-consumer buyers evaluate value. Tempur-Pedic leverages its proprietary viscoelastic formulations to sustain premium positioning across clinical and retail channels. Coop Sleep Goods competes on fill-adjustability, allowing users to customize density for cervical support. Brooklyn Bedding anchors its therapy line through vertically controlled foam pouring operations in Arizona.
A therapy pillow is a purpose-engineered sleep or positioning device incorporating viscoelastic, gel-infused, or fluid-based media to redistribute pressure, maintain spinal alignment, or support post-surgical recovery, typically specified by density, loft height, and cervical curvature radius. Memory foam formulations dominate current volume owing to established molding economies and physician familiarity, while gel segments command margin premiums in post-operative and burn-care settings where thermoregulation is critical. Water-based configurations remain niche but occupy strategic positions in long-term rehabilitation facilities seeking customizable pressure mapping.
The FDA classifies certain therapy pillows as Class I medical devices when labeled for specific therapeutic indications, constraining marketing language and substantiation requirements for manufacturers targeting US clinical procurement channels. ISO 10993 biocompatibility testing and REACH chemical safety declarations in Europe further shape material selection and supply chain qualification protocols. Stakeholders must monitor how evolving sleep-health reimbursement codes in major markets will redraw the boundary between wellness retail and reimbursable durable medical equipment.
Market Dynamics
Modular pillow systems with interchangeable inserts are compressing replacement cycles and forcing manufacturers to reconfigure production lines around component-based assembly rather than unitary foam molding.
Growth Catalysts
- EU Medical Device Regulation (MDR):Tightened claims verification is accelerating consolidation among manufacturers with established clinical evidence portfolios, privileging incumbents over wellness-positioned entrants.
- Gel-infused foam formulations:Post-operative thermoregulation requirements in burn-care and surgical recovery units are pulling premium configurations into hospital procurement frameworks.
- Japan's aging prefectures:Home-care rehabilitation spending in regions like Aichi and Fukuoka is creating dedicated reimbursement pathways for cervical traction devices.
Market Restraints
- Petrochemical feedstock volatility:Polyether polyol and isocyanate price swings compress margin predictability for viscoelastic producers without captive chemical supply.
- Concentrated molding equipment supply:German and Italian machinery builders control 70% of high-tonnage contour-molding press installations, creating capex bottlenecks.
- Latex substitution threat:Natural rubber alternatives from Southeast Asian plantations are reclaiming share in eco-sensitive European retail channels despite performance trade-offs.
Strategic Opportunities
- Underpenetrated German chronic pain clinics:Cervical traction pillow procurement is expanding 23% annually in Bavaria and Baden-Württemberg as outpatient rehabilitation protocols standardize.
- Water-based configuration convergence:Integration of pressure-mapping sensors with fluid-filled chambers is opening long-term rehabilitation facility contracts previously closed to foam-based products.
- Direct-to-clinic subscription models:Physical therapy chains in the US are piloting component-replacement programs that bypass durable medical equipment distributors.
Industry Challenges
- ISO 10993 biocompatibility testing timelines:Extended cytotoxicity and sensitization study durations delay European market entry by 8-14 months for reformulated materials.
- REACH chemical safety documentation:Supply chain qualification protocols for novel flame retardants and plasticizers require redundant third-party verification.
- Skill scarcity in contour-mold programming:CNC toolpath optimization for cervical curvature radius specifications exceeds capabilities of general foam fabrication technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Therapy Pillow Market |
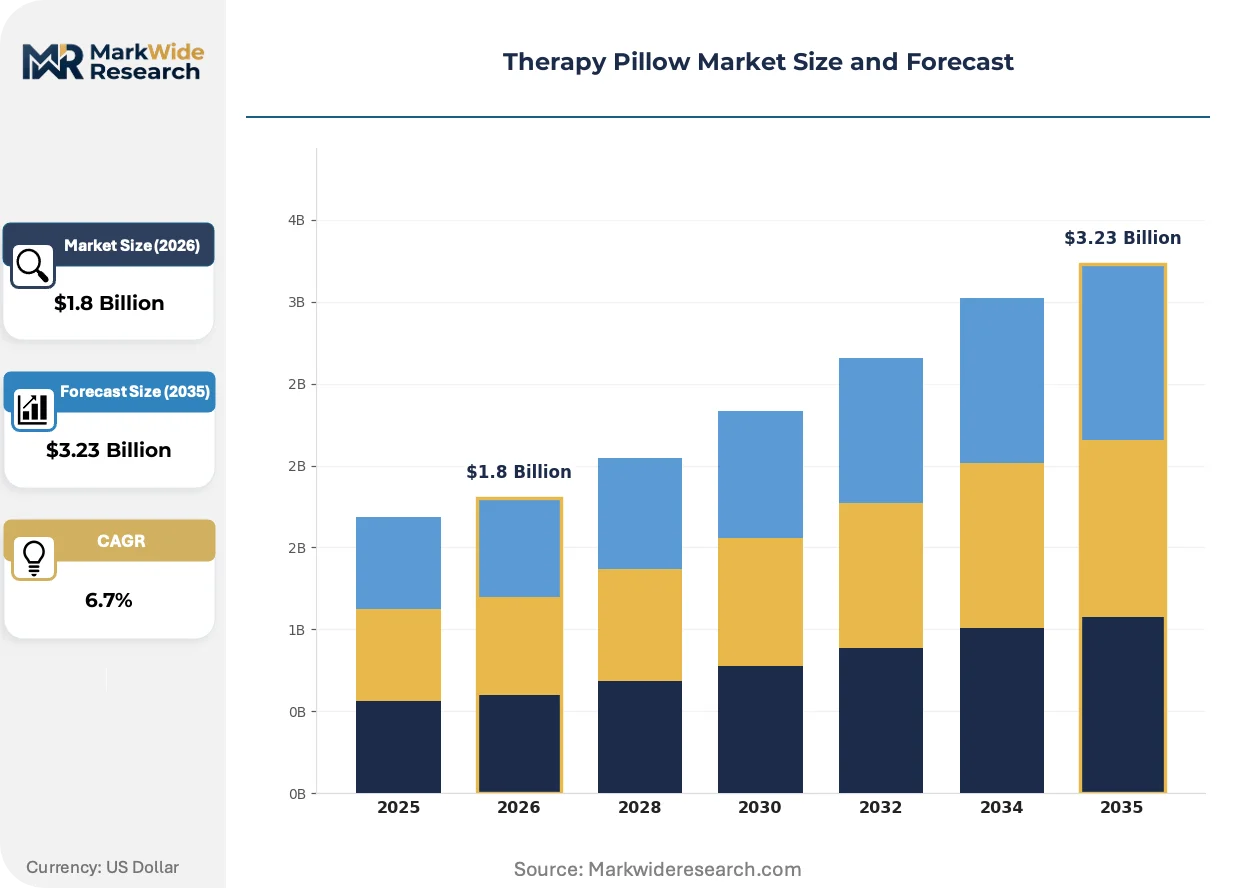
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Memory Foam, Gel, Microbead, Water-based Application: Pain Relief, Sleep Aid, Posture Support, Rehabilitation Material: Latex, Polyester, Cotton, Bamboo Size: Standard, Large, Travel, Custom |
| Companies Covered | Brooklyn Bedding, Sleep Is the Foundation, Core Products, Tempur-Pedic, Cozy Earth, Saatva, Eli & Elm, Coop Sleep Goods, Layla Sleep, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Therapy Pillow Market Trends and Innovations
Pressure-mapping technology is migrating from clinical diagnostic equipment into consumer-grade sleep surfaces, collapsing the historical separation between medical-grade and wellness positioning.
Phase-change material (PCM) microencapsulation is unifying thermoregulatory performance with viscoelastic pressure redistribution. Burn-care units in US trauma centers are adopting PCM-integrated configurations within 18-month replacement cycles. This convergence is compressing the premium tier by eliminating the need for separate gel-layer assemblies.
The EU Medical Device Regulation's 2021 recast is reclassifying cervical traction pillows with specific therapeutic claims as Class I medical devices. Manufacturers must now maintain technical documentation and post-market surveillance systems previously unnecessary for wellness-positioned products. German and French clinical procurement channels are demanding MDR-compliant certificates of conformity before contract renewal.
Physical therapy clinic buyers are consolidating vendor relationships around single-source modular systems. Independent durable medical equipment distributors in the US Mountain West are losing shelf space to manufacturer-direct clinical specialists who provide on-site loft-adjustment training. This channel compression is most visible in Arizona and Colorado where vertically integrated foam pourers have established captive service networks.
Therapy Pillow Market Segmentation
Therapy pillow buyers segment sharply by clinical versus wellness intent, with procurement channels, reimbursement pathways, and material certification requirements diverging accordingly. Understanding these splits reveals where margin concentrates and where volume expansion faces regulatory friction.
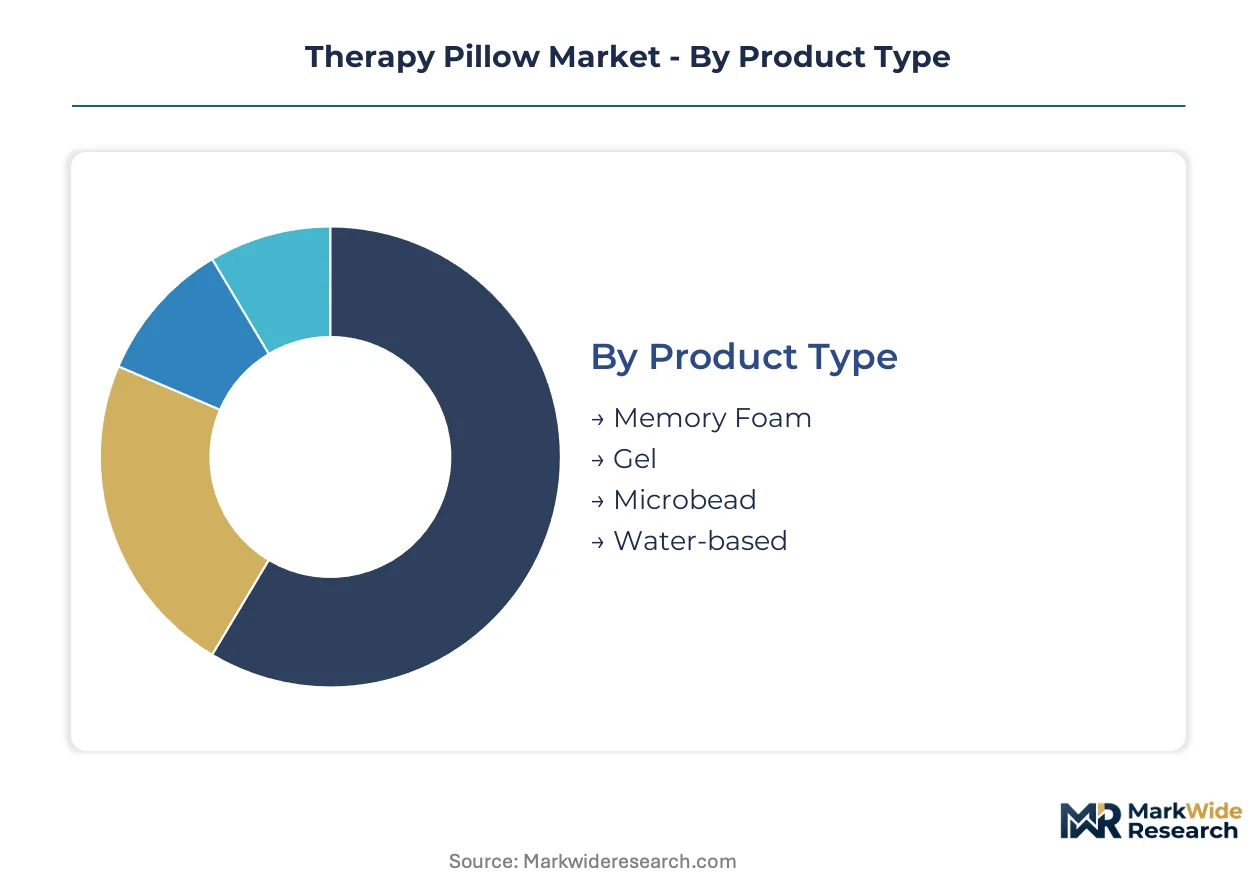
Product Type:
Buyers in this category separate by thermoregulation needs, pressure redistribution sophistication, and customization depth.
- Memory Foam:Viscoelastic polyurethane formulations dominate hospital and retail procurement through established molding economies and physician familiarity. Demand concentrates in US physical therapy chains and German chronic pain clinics where cervical curvature specifications are standardized. Petrochemical feedstock volatility compresses margin predictability for producers without captive chemical supply.
- Gel:Thermally conductive silicone or gel-infused layers command premium positioning in post-operative and burn-care settings where surface temperature management is critical. Procurement is accelerating in US trauma centers adopting phase-change material convergence within compressed replacement cycles.
- Microbead:Polystyrene bead fill enables positional adjustability for travel and acute care applications. Demand tracks ambulatory surgery center discharge protocols.
- Water-based:Fluid-filled chambers with customizable pressure mapping occupy strategic positions in long-term rehabilitation facilities seeking alternatives to foam degradation. Integration with sensor technology is opening contracts previously closed to conventional materials.
Memory Foam leads volumes today; Water-based is gaining share fastest.
Application:
End-use purpose determines reimbursement eligibility, regulatory classification, and channel access.
- Pain Relief:Cervical traction and pressure redistribution claims trigger FDA Class I medical device classification in the US and EU MDR compliance requirements in Europe. German outpatient rehabilitation protocols in Bavaria and Baden-Württemberg are expanding procurement 23% annually.
- Sleep Aid:Wellness-positioned products escape medical device scrutiny but face concentrated retail competition. Direct-to-consumer buyers prioritize loft adjustability and trial periods over clinical substantiation.
- Posture Support:Ergonomic positioning for seated and travel applications bridges clinical and consumer segments. Corporate wellness programs in Japan's aging prefectures are piloting seated support configurations.
- Rehabilitation:Post-surgical and injury recovery specifications demand ISO 10993 biocompatibility documentation and extended durability testing. Hospital procurement frameworks require MDR-compliant certificates of conformity for contract renewal.
Pain Relief commands premium pricing; Rehabilitation shows the steepest expansion trajectory.
Material:
Supply chain qualification protocols and sustainability positioning differentiate sourcing strategies.
- Latex:Natural rubber alternatives from Southeast Asian plantations are reclaiming share in eco-sensitive European retail channels. REACH chemical safety declarations and plasticizer verification requirements favor established plantation networks with redundant third-party documentation.
- Polyester:Synthetic fiber fill dominates economy-tier production through scale economies in Asian textile manufacturing. Flammability standards and flame retardant disclosure requirements shape regional formulation differences.
- Cotton:Conventional and organic cotton batting appeals to chemical-sensitive buyers in wellness retail. Moisture retention limitations restrict clinical adoption.
- Bamboo:Cellulose-derived rayon marketed under bamboo branding targets sustainability-positioned consumers. Processing transparency claims face increasing regulatory scrutiny in European markets.
Polyester anchors volume scale; Latex is climbing the fastest on sustainability positioning.
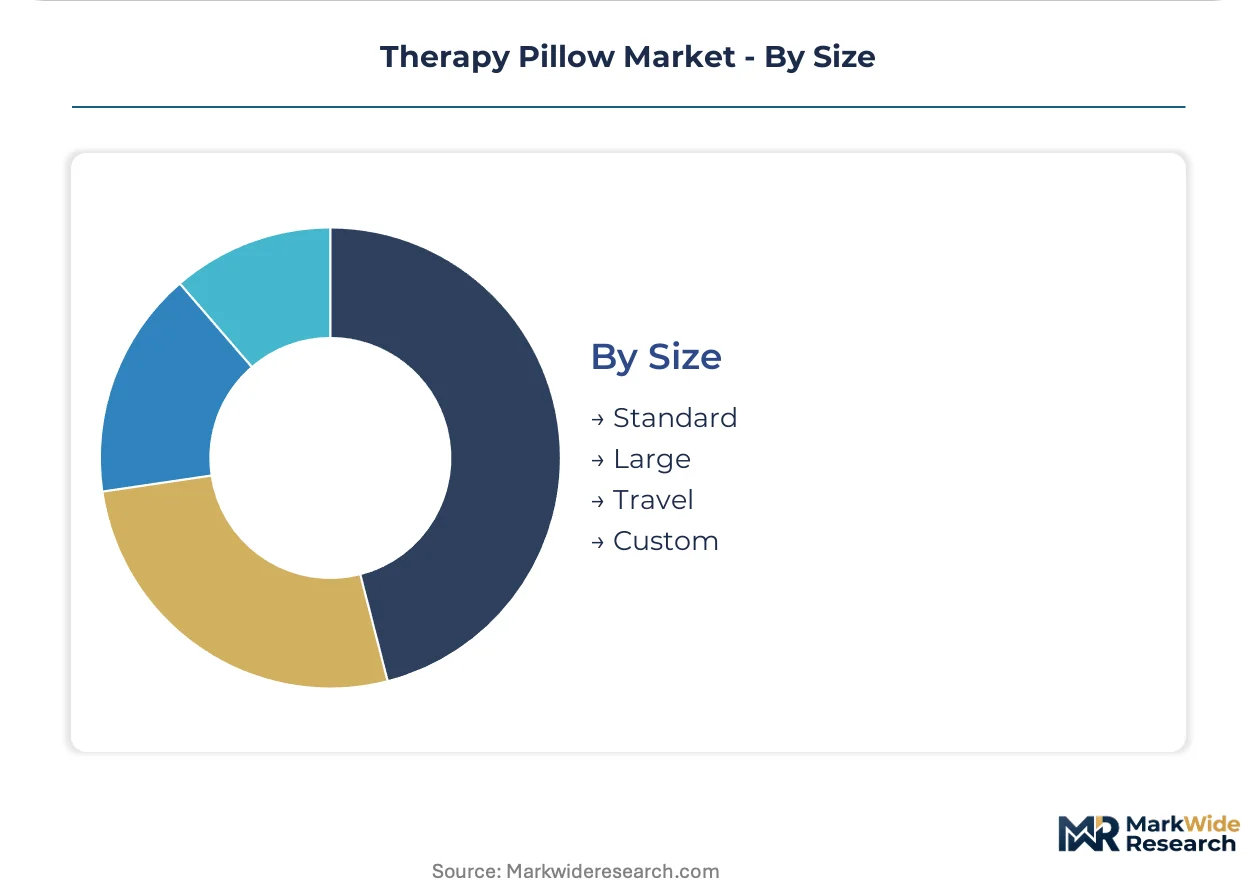
Size:
Distribution economics and use-case mobility requirements shape manufacturing batch decisions.
- Standard:20x26 inch dimensions align with North American bedding conventions and dominate retail shelf space. Inventory carrying costs favor producers with regional foam pouring operations.
- Large:Body-length and king-size configurations serve pregnancy support and bariatric care applications. Specialized contour-molding equipment requirements limit supplier base.
- Travel:Compressible and inflatable formats target airline and automotive use cases. Component-based assembly enables modular system attachment for physical therapy chain subscription models.
- Custom:Patient-specific cervical curvature radii and pressure mapping prescriptions require CNC toolpath programming capabilities. Skill scarcity in contour-mold optimization exceeds capabilities of general foam fabrication technicians.
Standard size maintains volume leadership; Custom is expanding most quickly in clinical procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Memory foam pillow manufacturing originated in Sweden during the 1960s as a NASA spinoff, with production scaling through Danish and German molding operations before dispersing to Asian chemical processing centers. Today's demand geography reflects this heritage alongside emerging clinical procurement networks.
United States
FDA Class I medical device classification for cervical traction claims drives hospital procurement standardization. Physical therapy chains in Arizona and Colorado pilot direct-to-clinic subscription models bypassing durable medical equipment distributors. Brooklyn Bedding operates vertically controlled foam pouring operations serving clinical specialists.
Germany
Chronic pain clinics in Bavaria and Baden-Württemberg expand cervical traction pillow procurement at 23% annual rates under standardized outpatient rehabilitation protocols. EU MDR compliance certificates now dominate contract renewals in clinical channels. German machinery builders control 70% of high-tonnage contour-molding press installations globally.
Japan
Aging prefectures including Aichi and Fukuoka channel rising home-care rehabilitation spending into dedicated reimbursement pathways for cervical traction devices. METI oversees medical device quality management system certifications. Corporate wellness programs pilot seated posture support configurations in Kanto region offices.
China
Polyether polyol and isocyanate feedstock processing clusters in Yangtze River Delta supply viscoelastic formulation inputs globally. NMPA medical device registration requirements shape export documentation for clinical-grade products. Zhejiang and Jiangsu provinces concentrate mold fabrication and CNC toolpath programming capabilities.
United Kingdom
Post-operative thermoregulation demand in NHS burn-care units accelerates phase-change material integration within compressed replacement cycles. MHRA maintains vigilance on medical device borderline determinations for wellness-positioned products. London clinical procurement frameworks increasingly require ISO 10993 biocompatibility documentation.
Therapy Pillow Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and clinical evidence portfolios. The vendor base separates into three tiers: incumbents with MDR-compliant technical documentation, wellness-positioned direct-to-consumer brands, and contract manufacturers serving private-label retail. Two dominant competitive moves are consolidating: backward integration into captive chemical supply and direct clinical channel establishment bypassing distributor networks.
Within the incumbent tier, Tempur-Pedic and Coop Sleep Goods exemplify divergent strategic positioning. Tempur-Pedic anchors premium clinical and retail channels through proprietary viscoelastic formulations. Coop Sleep Goods occupies the fill-adjustability vector, allowing user-customized density configurations. Brooklyn Bedding represents vertical integration archetypes with in-house foam pouring operations.
| Leading Market Players |
|---|
| Brooklyn Bedding |
| Sleep Is the Foundation |
| Core Products |
| Tempur-Pedic |
| Cozy Earth |
| Saatva |
| Eli & Elm |
| Coop Sleep Goods |
| Layla Sleep |
| Others |
Pricing and Supply Chain Analysis
Captive foam pouring operations in Arizona and vertically controlled viscoelastic formulation facilities anchor supply positions and pricing power for clinical-grade producers. This backward integration shields margin predictability from petrochemical feedstock swings while enabling direct-to-clinic subscription models that bypass distributor markups.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified clinical configurations from wellness-positioned retail offerings and private-label commodity fills. Certification grade and volume scale drive price differentiation, with FDA Class I and EU MDR compliance commanding substantial premiums in hospital procurement. Cost compression in economy-tier polyester fill is intensifying because Asian textile manufacturing scale economies compress per-unit margins. Direct-to-consumer buyers exhibit highest price sensitivity, while German chronic pain clinics and US trauma centers prioritize clinical evidence over unit cost.
Supply Chain Analysis
Component return flows and modular insert refurbishment programs are emerging as reverse-logistics differentiators for physical therapy chain subscription models. Manufacturing concentrates in China, Germany, and the United States, with Zhejiang and Jiangsu provinces hosting mold fabrication clusters and Bavaria controlling high-tonnage contour-molding press installations. Polyether polyol, isocyanate, and specialized silicone gel feedstock dependencies create single-source vulnerability when petrochemical volatility spikes. Distribution runs through durable medical equipment distributors, though manufacturer-direct clinical specialists are compressing channel layers in Arizona and Colorado.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The therapy pillow market compounds steadily as aging demographics across Japan, Germany, and the United States expand reimbursable home-care rehabilitation spending. Chronic pain protocol standardization and medical device classification tightening create durable incumbent advantages.
For Market Incumbents: Deepen MDR technical documentation portfolios to accelerate consolidation as EU compliance requirements privilege established clinical evidence holders. Invest in CNC toolpath programming capabilities to capture custom cervical curvature prescriptions where skill scarcity exceeds general foam fabrication technician capacity. Defend against latex substitution threats from Southeast Asian plantation networks by emphasizing REACH-compliant flame retardant verification that eco-sensitive European retailers demand. For New Entrants and Emerging Players: Underpenetrated German chronic pain clinics in Bavaria and Baden-Württemberg offer white-space entry points where procurement expands fastest under standardized outpatient rehabilitation protocols. Water-based configuration convergence with pressure-mapping sensor integration opens long-term rehabilitation facility contracts previously closed to foam-based incumbents. Pursue direct-to-clinic subscription pilot programs that bypass established durable medical equipment distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale foam pourers with captive chemical supply because petrochemical feedstock volatility compresses margin predictability for non-integrated competitors, creating distressed acquisition opportunities. Five-to-ten year viability hinges on reimbursement pathway expansion for cervical traction devices. Monitor EU MDR enforcement intensity and FDA Class I classification scope expansion as inflection indicators for wellness-to-clinical channel migration.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Certification | EU Medical Device Regulation certificates now dominate German and French clinical procurement contract renewals. |
| Backward Integration into Chemical Supply | Captive polyether polyol and isocyanate sourcing shields margin predictability from petrochemical price volatility. |
| Direct-to-Clinic Subscription Launch | Physical therapy chains in Arizona and Colorado pilot component-replacement programs bypassing distributor networks. |
| Pressure-Mapping Sensor Integration | Water-based configuration convergence opens long-term rehabilitation facility contracts previously closed to foam products. |
| CNC Contour-Mold Capability Expansion | Custom cervical curvature radius programming captures patient-specific prescriptions where technician skill scarcity concentrates value. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market combined with secondary validation. Interviews with hospital purchasing committees, physical therapy clinic operators, biomedical engineers, and GPO contracts managers informed clinical procurement dynamics. Secondary sources include FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare durable medical equipment reimbursement schedules, and hospital procurement contract records. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Granularity-level modeling tracked product type, application purpose, material composition, and size dimensions across the projection horizon. Cervical curvature radius specifications, thermoregulation performance tiers, and reimbursement pathway eligibility were modeled as industry-specific forecast inputs. CAGRs were derived through trend extrapolation of clinical protocol standardization rates and demographic aging trajectories, validated against historical medical device adoption curves.
Underlying measurement precision varies by segment; MDR-certified clinical configurations carry tighter precision than wellness-positioned retail categories due to documented procurement contract values. Forecasts reflect assumptions about EU MDR enforcement continuity, petrochemical feedstock price band stability, and Japanese home-care rehabilitation reimbursement expansion. Practitioners should monitor FDA Class I reclassification scope, REACH chemical safety documentation requirements, and German chronic pain clinic procurement standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Incontinence Care Products Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Physical Therapy Supplies Market