
 Incontinence Care Products Market | 2026-2036
Incontinence Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Incontinence Care Products Market Analysis
Modular sizing and gender-specific absorbency tiers is decoupling bulk institutional purchasing from standardized SKUs, forcing manufacturers to support smaller, customized orders. Essity AB leverages its European tissue infrastructure to sustain private-label flexibility across pharmacy chains. Kimberly-Clark Corporation anchors North American retail shelf presence through club-store exclusivity on premium protective underwear. Ontex Group competes via specialized European production of economy-tier adult diapers for long-term care tenders.
Incontinence care products encompass absorbent hygiene articles engineered with superabsorbent polymer cores, acquisition distribution layers, and breathable textile-backsheet composites designed to manage urinary or fecal leakage in individuals with reduced bladder or bowel control. Manufacturing employs hot-melt adhesive bonding and elastic strand application to achieve fluid retention capacities exceeding one liter while maintaining skin-surface dryness below relative humidity thresholds. Adult diapers retain the largest volume share across product types, though protective underwear captures expanding margin pools as ambulatory users reject stigma-associated bulk. Home care dominates end-user demand structurally, while long-term care facilities impose economy-tier pricing pressure through centralized procurement contracts that offset higher per-unit clinical specifications.
FDA 510(k) clearance requirements govern medical-grade absorbency claims in the United States, while EU MDR reclassification pressures manufacturers to demonstrate clinical performance data for products marketed with therapeutic skin-health benefits. ECHA REACH compliance on SAP chemical constituents further constrains formulation flexibility for suppliers targeting European retail channels. Stakeholders must monitor how reimbursement code revisions in Medicare and national health systems reclassify premium products from discretionary retail purchases to reimbursed durable medical equipment, reshaping channel economics and brand investment priorities.
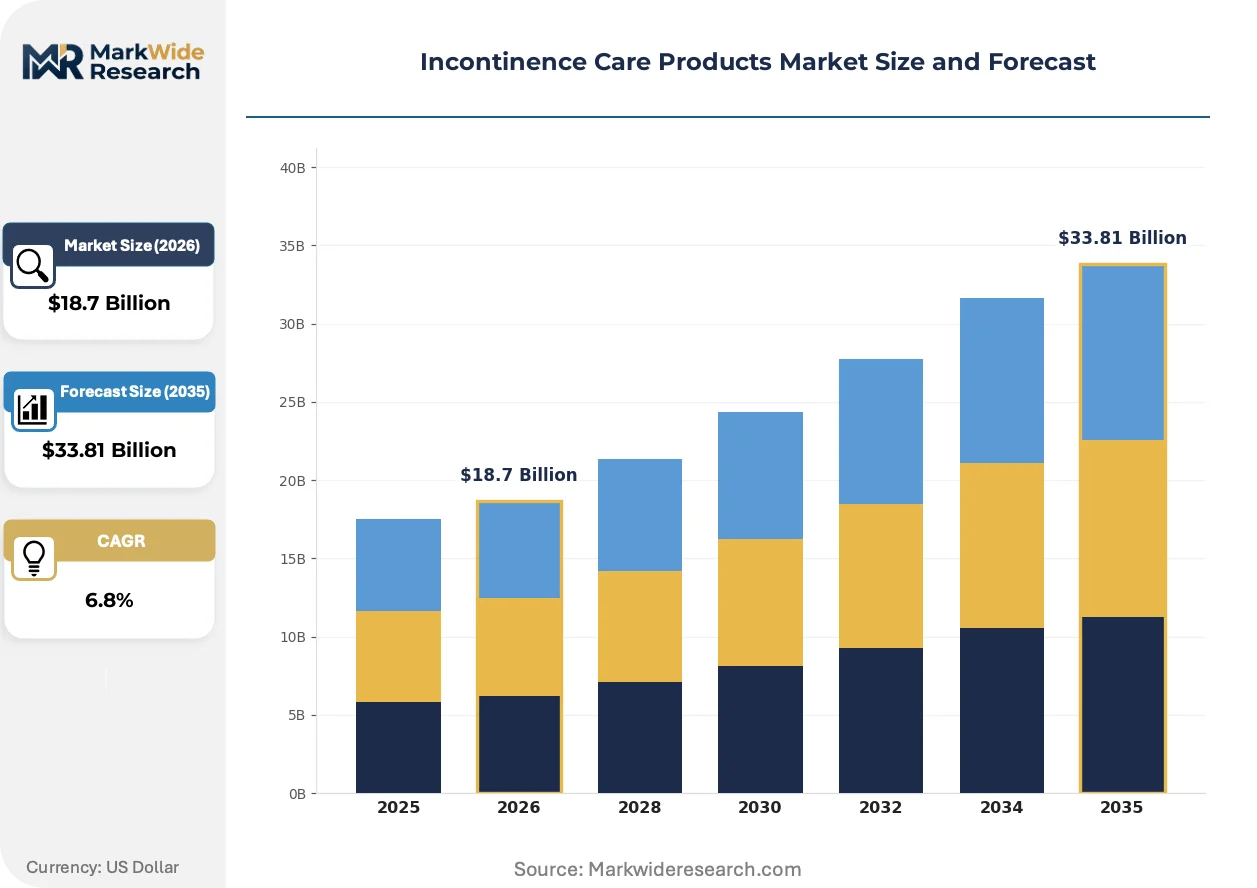
Market Dynamics
The EU Green Deal's waste-reduction mandates are forcing procurement officers across German home care networks to abandon single-use underpads, compressing margins for manufacturers locked into disposable supply chains while opening volume pathways for reusable textile systems.
Growth Catalysts
- Japan's METI dignity standards:Elderly care facilities in Tokyo and Osaka now mandate premium absorbency tiers with skin-moisture monitoring, accelerating replacement cycles for basic products.
- Superabsorbent polymer chemistry advances:Cross-linked sodium polyacrylate formulations now retain fluid volumes exceeding one liter at relative humidity thresholds below skin-damage thresholds, expanding clinical indications.
- Medicare reimbursement code revisions:CMS reclassification of protective underwear as durable medical equipment in select states shifts channel economics toward pharmacy benefit managers.
Market Restraints
- Petrochemical feedstock volatility:Propylene and acrylic acid price swings directly compress superabsorbent polymer input costs, squeezing formulation margins for mid-tier producers.
- ECHA REACH compliance burdens:Registration, evaluation, and authorization constraints on SAP chemical constituents force European suppliers into costly third-party toxicology testing.
- Reusable textile substitution:German home care agencies now specify washable underpad contracts with three-year lifecycles, threatening volume for disposable brief manufacturers.
Strategic Opportunities
- India's geriatric care infrastructure gap:Underpenetrated rural districts lack absorbent hygiene distribution, creating white space for pharmacy-chain direct-to-patient models.
- Gender-specific absorbency engineering:Anatomically contoured products for female stress incontinence command margin premiums in Japanese retail channels.
- EU MDR clinical data requirements:Therapeutic skin-health claims now demand documented performance evidence, advantaging manufacturers with existing dermatological trial portfolios.
Industry Challenges
- Hot-melt adhesive formulation expertise:Elastic strand bonding engineers with medical-grade hygiene experience command scarcity premiums, constraining production scale-up.
- FDA 510(k) clearance timelines:Medical-grade absorbency claims require premarket notification reviews averaging 180 days, delaying product launches.
- Legacy SKU proliferation:Modular sizing demands fragment order volumes, forcing manufacturers to reconfigure production lines for smaller batch runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incontinence Care Products Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Pads, Protective Underwear, Adult Diapers, Bed Mats End User: Hospitals, Home Care, Long-term Care Facilities, Rehabilitation Centers Distribution Channel: Pharmacies, Online Retail, Supermarkets, Specialty Stores Price Tier: Economy, Mid-range, Premium, Luxury |
| Companies Covered | Essity AB, Kimberly-Clark Corporation, Procter & Gamble, Unicharm Corporation, Ontex Group, Paul Hartmann AG, Coloplast A/S, First Quality Enterprises, Abena A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incontinence Care Products Market Emerging Trajectories
Absorbent hygiene engineering is pivoting from commodity bulk toward precision performance, with textile-backsheet composites and moisture-sensing layers displacing legacy plastic-backed designs in premium segments.
Breathable textile-backsheet laminates are integrating hydrophobic microporous membranes with cotton-feel spunbond layers, enabling vapor transmission rates that reduce dermatitis incidence. Japanese long-term care chains now specify these materials for ambulatory residents with intact skin integrity. The technology is integrating clinical outcomes data into procurement scorecards, compressing commodity brief volumes.
EU MDR reclassification of incontinence products with therapeutic claims demands clinical performance documentation previously reserved for medical devices. Manufacturers marketing skin-health benefits must now submit biocompatibility testing under notified body supervision. German pharmacy wholesalers are consolidating supplier lists to those with MDR technical file completion, filtering out smaller private-label competitors.
Home care agencies in Berlin and Hamburg are consolidating purchasing through centralized tender platforms that specify total-cost-of-ownership metrics including waste disposal fees. Club-store exclusivity arrangements in North American retail are losing ground to direct-to-patient subscription models with auto-replenishment algorithms. The shift is most visible in Japan, where METI-certified dignity standards now require product disposal convenience features that subscription services bundle with scheduled delivery.
Incontinence Care Products Market Segmentation
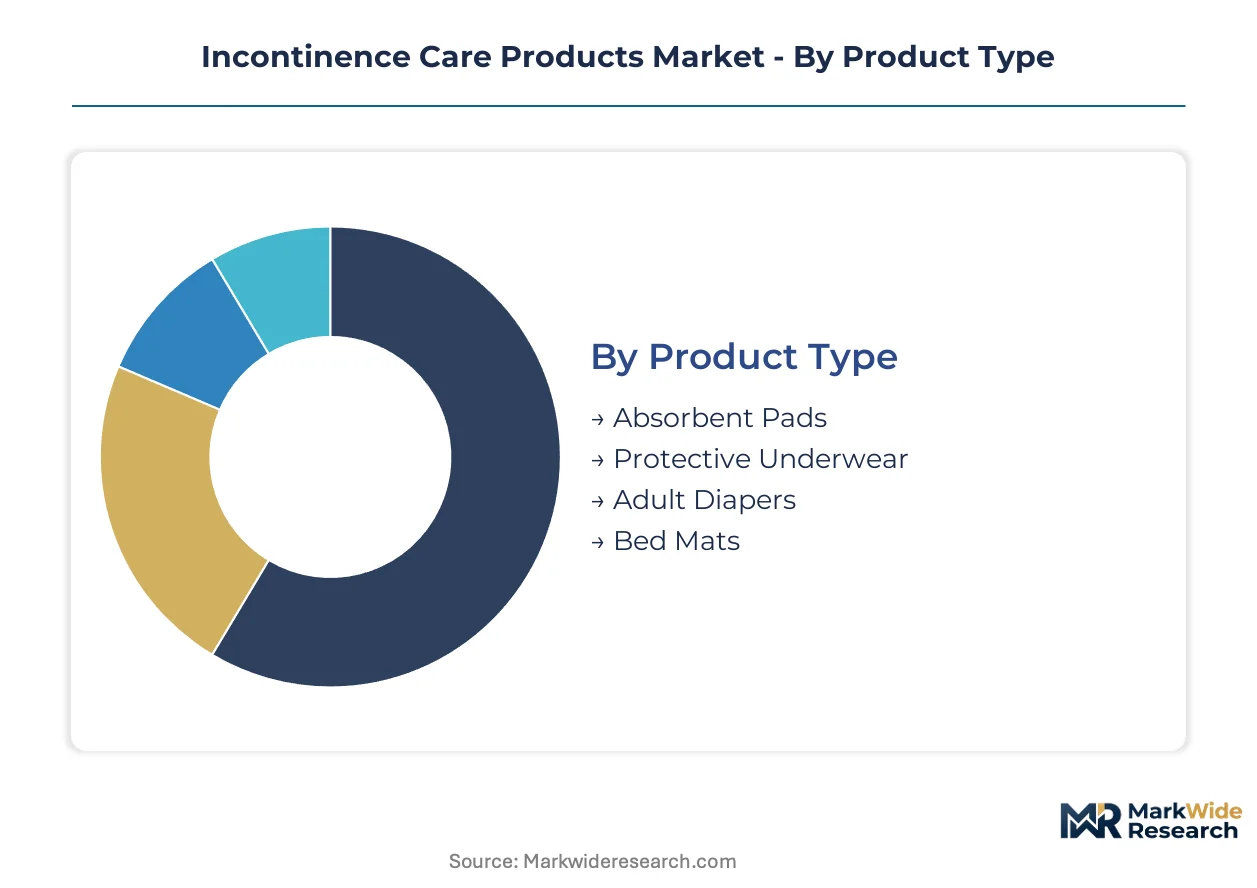
Product architecture in incontinence care fragments across absorbency performance, skin-contact materials, and disposal convenience. Manufacturers must balance SKU proliferation against production line economics as procurement shifts toward modular specifications.
Product Type:
Capital intensity escalates with superabsorbent polymer loading and textile-backsheet lamination complexity.
- Absorbent Pads:Thin-profile cores with acquisition distribution layers target light-to-moderate leakage. German home care agencies specify these for ambulatory clients under EU Green Deal waste-reduction protocols.
- Protective Underwear:Pull-up designs with elastic strand waistbands and breathable textile-backsheet composites command margin premiums. Japanese retail channels absorb volume as METI dignity standards displace tab-style briefs for mobile elderly users.
- Adult Diapers:Tape-tab configurations with high-density SAP cores retain institutional purchasing concentration. Long-term care facilities in Berlin and Hamburg impose economy-tier pricing through centralized tender platforms.
- Bed Mats:Multi-layer underpads with waterproof backsheet laminates address nocturnal protection. Reusable textile variants gain procurement share as German networks abandon single-use alternatives.
Adult diapers absorb the bulk of installed capacity; protective underwear is expanding most quickly.
End User:
Clinical specification intensity varies sharply across care settings, dictating formulation and certification requirements.
- Hospitals:Medical-grade absorbency with FDA 510(k) clearance governs acute care procurement. Skin-moisture monitoring layers penetrate Tokyo and Osaka facilities under METI guidelines.
- Home Care:Dispersed demand across pharmacy and subscription channels concentrates in Japan's direct-to-patient models with auto-replenishment algorithms.
- Long-term Care Facilities:Centralized purchasing through tender platforms in Germany compresses margins while demanding total-cost-of-ownership metrics including waste disposal.
- Rehabilitation Centers:Transitional care settings specify mid-tier performance with disposal convenience features for patient dignity protocols.
Hospitals maintain the steepest specification thresholds; home care channels are gaining share fastest.
Distribution Channel:
Channel economics restructure as reimbursement code revisions shift products from discretionary retail to durable medical equipment.
- Pharmacies:Pharmacy benefit manager consolidation in select US states reclassifies protective underwear under Medicare reimbursement. German pharmacy wholesalers filter suppliers by EU MDR technical file completion.
- Online Retail:Direct-to-patient subscription models with auto-replenishment algorithms displace club-store exclusivity in North America.
- Supermarkets:Mass retail shelves concentrate economy-tier volume with private-label penetration across European chains.
- Specialty Stores:Medical supply outlets with fitting services capture premium-tier margin pools for anatomically contoured products.
Pharmacies retain the largest reimbursement-accessible volume; online retail is climbing the fastest.
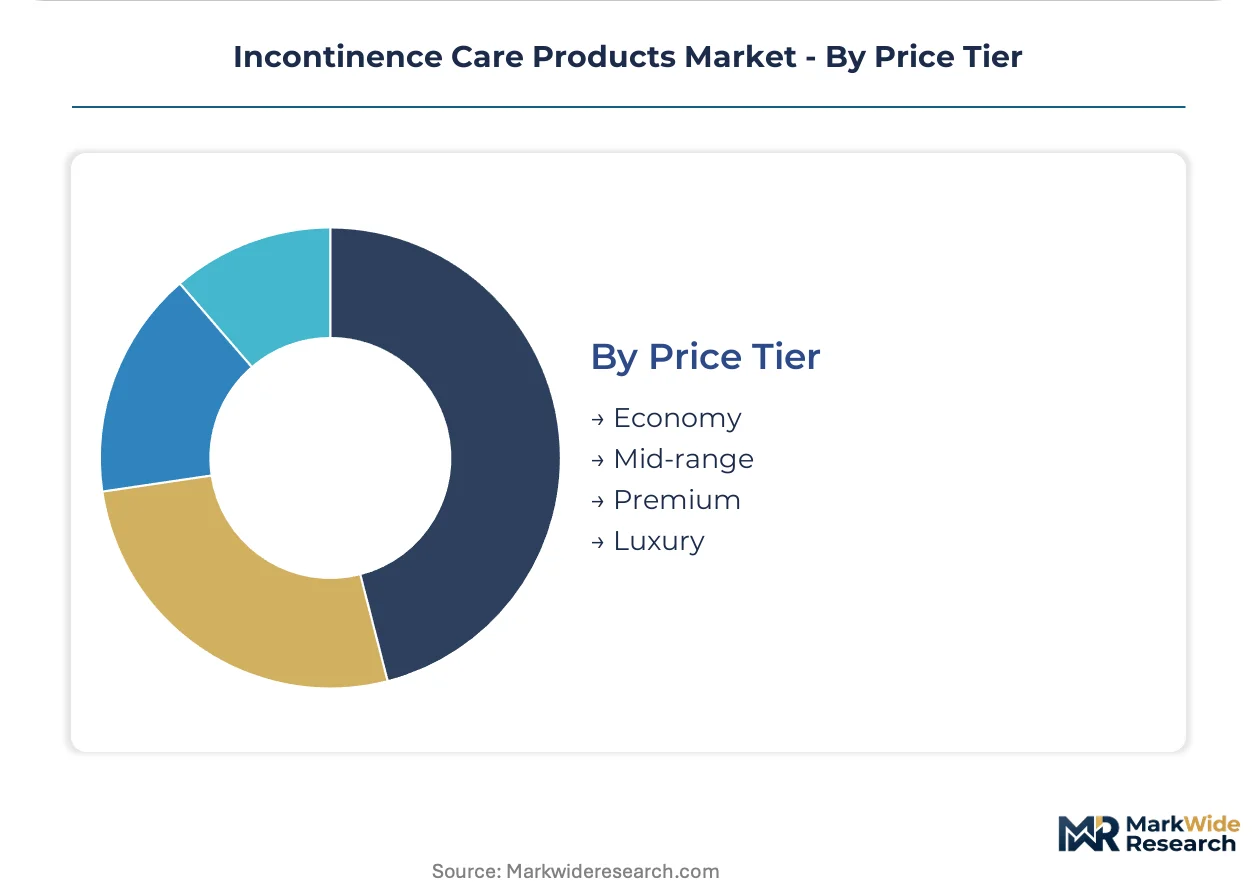
Price Tier:
Raw material volatility in petrochemical feedstocks compresses formulation margins most severely at economy levels.
- Economy:Basic SAP cores with plastic-backsheet construction face substitution pressure from reusable textile systems in German procurement.
- Mid-range:Breathable textile-backsheet laminates with cotton-feel spunbond layers penetrate Japanese long-term care chains for residents with intact skin integrity.
- Premium:Moisture-sensing layers and dermatitis-reduction claims require EU MDR clinical performance documentation under notified body supervision.
- Luxury:Gender-specific absorbency engineering with anatomical contouring commands margin premiums in Japanese retail channels for female stress incontinence.
Economy tiers absorb the bulk of institutional volume; premium segments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Western Europe and East Asia while consumption growth accelerates across aging populations in Japan, Germany, and the United States. Superabsorbent polymer supply chains anchor production in Belgium and South Korea, creating trade flows toward deficit markets.
Japan
Tokyo and Osaka facilities drive premium product uptake under METI dignity standards mandating skin-moisture monitoring layers. The Ministry of Economy, Trade and Industry enforces elderly care protocols that accelerate replacement cycles for basic absorbency tiers. Kanto region procurement networks consolidate purchasing through subscription models with auto-replenishment algorithms.
Germany
EU Green Deal waste-reduction mandates compress disposable underpad volumes as Berlin and Hamburg home care agencies specify reusable textile systems with three-year lifecycles. ECHA REACH compliance on SAP chemical constituents constrains formulation flexibility for suppliers targeting pharmacy wholesale channels. North Rhine-Westphalia hosts manufacturing clusters serving centralized tender platforms across long-term care networks.
United States
Medicare reimbursement code revisions in select states reclassify protective underwear as durable medical equipment, shifting channel economics toward pharmacy benefit managers. FDA 510(k) clearance requirements govern medical-grade absorbency claims, delaying product launches through premarket notification reviews. Southeast distribution hubs concentrate club-store exclusivity arrangements for premium protective underwear.
India
Rural districts present underpenetrated white space for pharmacy-chain direct-to-patient models addressing geriatric care infrastructure gaps. The country's national pharmaceutical regulator oversees medical device classifications that influence import licensing for absorbent hygiene articles. Maharashtra and Gujarat distribution networks expand coverage into tier-2 cities with economy-tier product portfolios.
South Korea
Domestic superabsorbent polymer production supports export-oriented manufacturing serving Japanese and Southeast Asian demand. MFDS medical device regulations align with international standards for products marketed with therapeutic skin-health benefits. Seoul Capital Area logistics hubs facilitate just-in-time delivery to long-term care procurement platforms.
Incontinence Care Products Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered pricing strata, creating a bifurcated structure where scale advantages clash with customization agility. The vendor base organizes around three archetypes: tissue and hygiene conglomerates leveraging cross-category infrastructure, medical device specialists with clinical certification expertise, and private-label manufacturers serving pharmacy and retail chains. Consolidation pressures intensify as centralized procurement contracts demand total-cost-of-ownership metrics, while modular sizing requirements fragment order volumes toward flexible production systems.
Within the European infrastructure tier, Essity AB and Ontex Group occupy positions anchored by continental manufacturing networks and tissue industry heritage. Paul Hartmann AG exemplifies the medical-device specialist archetype with clinical-grade certification capabilities. Among North American conglomerates, Kimberly-Clark Corporation represents scale-driven retail shelf presence through established club-store relationships.
| Leading Market Players |
|---|
| Essity AB |
| Kimberly-Clark Corporation |
| Procter & Gamble |
| Unicharm Corporation |
| Ontex Group |
| Paul Hartmann AG |
| Coloplast A/S |
| First Quality Enterprises |
| Abena A/S |
| Others |
Supply Flow & Price Mechanics
Propylene and acrylic acid price indices cascade through superabsorbent polymer formulations, compressing margins at economy tiers while forcing premium segments to absorb volatility through textile-backsheet substitution and subscription bundling. German home care procurement officers now weight total-cost-of-ownership metrics including waste disposal fees, redirecting volume toward reusable textile systems with extended lifecycles.
Pricing Analysis
Margin tightening in economy tiers reflects petrochemical feedstock volatility and reusable textile substitution pressure from EU Green Deal procurement mandates. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and skin-moisture monitoring capability. Cost compression accelerates as long-term care facilities consolidate purchasing through centralized tender platforms. Institutional buyers exhibit highest price sensitivity; Japanese retail channels for gender-specific absorbency engineering show lowest.
Supply Chain Analysis
Regional distribution centers in Belgium, South Korea, and Germany anchor hub-and-spoke patterns serving deficit markets across aging populations. Superabsorbent polymer production draws from propylene and acrylic acid feedstocks concentrated in petrochemical clusters. Single-source vulnerability in SAP chemical constituents threatens formulation flexibility under ECHA REACH compliance. Distribution runs through pharmacy wholesale channels and direct-to-patient subscription platforms with auto-replenishment algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incontinence care has become a vertical-integration race, with manufacturers pursuing backward integration into superabsorbent polymer production to escape petrochemical price volatility and secure formulation flexibility under tightening EU chemical regulations.
For Market Incumbents: Extend clinical certification portfolios to capture EU MDR reclassification premiums, while consolidating production flexibility for modular sizing demands. Reusable textile substitution from German home care networks threatens disposable volume; backward integration into SAP production secures margin control against propylene and acrylic acid volatility. For New Entrants and Emerging Players: Launch via pharmacy-chain direct-to-patient models in India's underpenetrated rural districts, bypassing legacy distribution infrastructure. White space concentrates in tier-2 city geriatric care gaps and economy-tier institutional tenders where centralized procurement has filtered out smaller competitors lacking MDR technical files. For Investors and Strategic Acquirers: Distressed-cycle entries favor European private-label manufacturers with existing notified body relationships and dermatological trial portfolios. Long-term viability hinges on regulatory certification durability rather than brand equity alone. Watch for Medicare reimbursement code revisions reclassifying protective underwear as durable medical equipment as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical File Completion | Filters supplier lists at German pharmacy wholesalers consolidating procurement. |
| Backward Integration into SAP Production | Captures margin control over superabsorbent polymer input costs. |
| Direct-to-Patient Subscription Launch | Displaces club-store exclusivity with auto-replenishment algorithms in North America. |
| Reusable Textile System Development | Captures EU Green Deal procurement mandates abandoning single-use underpads. |
| Gender-Specific Absorbency Engineering | Commands margin premiums in Japanese retail channels for female stress incontinence. |
Methodological Framework
Independent corroboration across procurement officers at German home care networks, pharmacy benefit managers in select US states, and biomedical engineers at Japanese long-term care facilities underwrites the qualitative findings. Secondary validation draws from FDA 510(k) clearance databases, ECHA REACH registration filings, and METI elderly dignity standard protocols. Bottom-up demand modeling triangulates against top-down macroeconomic anchors across the analysis window.
Historical reference periods spanning pre-pandemic baseline through post-regulatory reclassification phases anchor the projection horizon. Segmentation dimensions include product architecture, end-user care setting, distribution channel reimbursement access, and regional regulatory cluster. CAGRs derive from iterative convergence of demand-side penetration curves and supply-side capacity constraints. Forecast inputs incorporate superabsorbent polymer chemistry advances and Medicare reimbursement code revision schedules.
Petrochemical price volatility, EU MDR implementation delays, and reusable textile substitution acceleration are the dominant revision risks. Forecasts reflect documented assumptions on regulatory timelines and procurement consolidation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Shoe Cover Market
Patient Care Supplies
Ice Packs for Pain Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Abdominal Pads Market