
 US Pressure Ulcer Prevention Market | 2026-2036
US Pressure Ulcer Prevention Market Size, Share, and Industry Trends Forecast 2026-2036
US Pressure Ulcer Prevention Market Insights
Domestic foam converters and medical textile suppliers is repositioning capacity toward pressure-redistributing surfaces as hospital procurement committees tighten technical specifications. Stryker leverages its integrated manufacturing footprint across Midwest production facilities to sustain margin control on high-specification alternating air mattresses. Cardinal Health competes through distribution density, anchoring same-day fulfillment networks that reach rural critical access hospitals. Medline Industries differentiates via private-label skin care protocols bundled with support surface contracts, occupying a sticky position in group purchasing organization portfolios.
Pressure ulcer prevention encompasses engineered surfaces, positioning systems, and topical interventions designed to redistribute tissue load below capillary closure pressure, typically maintaining interface pressures under 32 mmHg to preserve perfusion. Silicone-coated multilayer foam composites and low-air-loss technologies dominate acute care specification sheets, where patient immobility duration exceeds six hours. Support surfaces command the largest product type volume pool, though wound care dressings capture disproportionate margin in home care channels where reimbursement shifts toward episode-based billing. Long-term care facilities represent the fastest-growing application segment as post-acute operators face CMS Star Rating pressure on skin integrity metrics, while direct sales channels retain dominance in hospital contracts despite online platform penetration in smaller nursing home accounts.
FDA 510(k) clearance requirements for powered support surfaces shape product development timelines and clinical evidence burdens for manufacturers seeking acute care placement. CMS Hospital-Acquired Condition Reduction Program penalties and state-level Medicaid managed care quality withholds create dual compliance pressure that elevates procurement standards in skilled nursing facilities. OSHA safe patient handling guidelines intersect with pressure ulcer protocols, reinforcing demand for mechanical lift-compatible positioning devices. Stakeholders must monitor how CMS prospective payment system refinements for post-acute care redistribute volume between institutional and home-based settings.
Market Dynamics
CMS Hospital-Acquired Condition Reduction Program penalties are compressing reimbursement timelines and forcing acute care systems to front-load capital expenditure on powered support surfaces before penalty exposure materializes. This structural pressure is redistributing procurement authority toward clinical engineering departments and away from traditional materials management.
Growth Catalysts
- Medicaid managed care quality withholds:State-level contracts in Texas and Florida now tie 3-5% of capitated payments to skin integrity outcomes, compelling skilled nursing operators to upgrade mattress fleets ahead of contract renewals.
- Silicone-coated multilayer foam:This material stack delivers sustained pressure redistribution below 30 mmHg interface thresholds, displacing standard gel overlays in immobility protocols exceeding six hours.
- Southeastern demographic concentration:Aging population density across Florida, Georgia, and the Carolinas overlaps with for-profit long-term care chain expansion, creating localized demand surges for dynamic support surfaces.
Market Restraints
- Polyether polyurethane foam supply concentration:Three domestic chemical producers control 70%+ of medical-grade foam precursor supply, exposing converters to input cost volatility when petrochemical feedstocks spike.
- FDA 510(k) clinical evidence burdens:Powered support surface clearances require pressure mapping studies and adverse event documentation that extend development timelines 18-24 months beyond unpowered alternatives.
- Mechanical lift compatibility constraints:OSHA safe patient handling guidelines mandate clearance specifications that legacy bed frames cannot accommodate, forcing capital-intensive fleet replacements.
Strategic Opportunities
- Rural critical access hospital penetration:Same-day fulfillment networks anchored in distribution density now reach facilities below 25 beds, opening addressable volume previously captured by durable medical equipment rental.
- Episode-based home care billing:CMS prospective payment system refinements for post-acute care create bundled reimbursement incentives for wound care dressings paired with support surface rentals in discharge planning.
- AI-enabled pressure mapping convergence:Sensor-embedded mattress systems that feed predictive algorithms for tissue perfusion risk are attracting pilot deployments in academic medical centers seeking population health data assets.
Industry Challenges
- Clinical evidence generation capacity:Manufacturers lack sufficient biostatistician and health economist staffing to execute concurrent 510(k) submissions and real-world evidence studies demanded by hospital value analysis committees.
- Legacy fleet integration complexity:Powered surface controls must interface with existing nurse call systems and electronic health record platforms, requiring IT security reviews that stall procurement cycles 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pressure Ulcer Prevention Market |
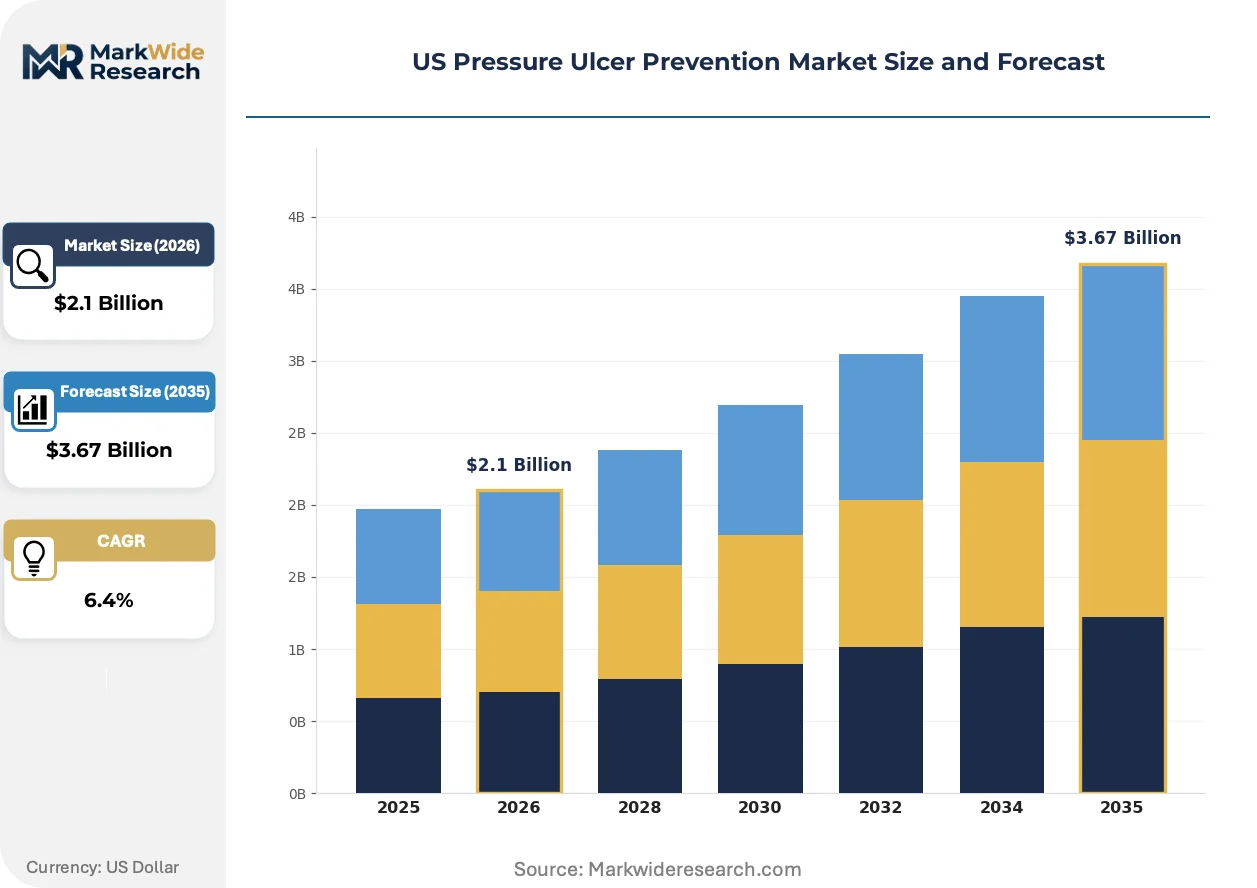
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Support Surfaces, Pressure Relief Cushions, Positioning Devices, Wound Care Dressings, Skin Care Products Application: Acute Care, Long-Term Care, Home Care, Rehabilitation Centers, Palliative Care End User: Hospitals, Nursing Homes, Home Healthcare Agencies, Skilled Nursing Facilities, Outpatient Clinics Distribution Channel: Direct Sales, Online Platforms, Medical Distributors, Pharmacies, Specialty Stores |
| Companies Covered | Medline Industries, Cardinal Health, Stryker, 3M, Integra LifeSciences, Baxter, Agiliti Health, Arjo, Invacare Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pressure Ulcer Prevention Market Trends and Innovations
Technology convergence between sensor hardware and predictive analytics is redefining how support surfaces generate clinical value beyond passive pressure redistribution. This shift is elevating procurement criteria from capital equipment specifications to data infrastructure compatibility.
Alternating air mattress systems with embedded capacitive pressure sensors are consolidating technical specifications across acute care procurement committees. Hospital systems in California and New York are mandating these configurations for all ICU and step-down unit purchases. The technology is consolidating vendor rosters by disqualifying manufacturers lacking integrated sensor-to-EMR connectivity.
CMS Star Rating methodology revisions now weight skin integrity metrics at 15% of overall facility scoring, up from 10% in prior measurement periods. Skilled nursing operators in Florida and Texas are responding by accelerating mattress replacement cycles from seven-year to four-year intervals. This regulatory recalibration is compressing secondary market availability for refurbished powered surfaces.
Group purchasing organization portfolios are unbundling support surface contracts from skin care protocol licensing. Medline Industries and Cardinal Health are competing to anchor these bundles, but independent nursing home chains are resisting exclusive arrangements. This purchasing behavior shift is most visible in the Southeast, where for-profit operators maintain direct relationships with foam converters to preserve pricing leverage.
US Pressure Ulcer Prevention Market Segmentation
Procurement committees in acute care and long-term care settings apply divergent technical specifications and reimbursement logics to pressure ulcer prevention investments. Segmentation reveals how product mix, care setting, and channel structure reshape competitive positioning across the value chain.
Product Type:
Hospital capital budgets prioritize interface pressure performance and FDA clearance status over unit cost when evaluating engineered surfaces.
- Support Surfaces:Alternating air mattresses and low-air-loss systems maintain tissue perfusion below 30 mmHg through active pressure redistribution. Demand concentrates in Texas and Florida skilled nursing facilities where CMS Star Rating pressure on skin integrity metrics accelerates fleet replacement cycles.
- Pressure Relief Cushions:Silicone-coated multilayer foam composites displace standard gel overlays in immobility protocols exceeding six hours. Acute care systems in California and New York now mandate sensor-embedded configurations for ICU and step-down unit purchases.
- Positioning Devices:Mechanical lift-compatible wedges and heel-offloading boots address OSHA safe patient handling guidelines in hospitals retrofitting legacy bed frames.
- Wound Care Dressings:Advanced hydrocolloid and foam dressings capture disproportionate margin in home care channels where reimbursement shifts toward episode-based billing.
- Skin Care Products:Barrier creams and moisture management protocols bundle with support surface contracts through group purchasing organization portfolios.
Support Surfaces leads on scale; Wound Care Dressings leads on momentum.
Application:
Care setting determines whether procurement emphasizes capital equipment longevity or consumable replenishment velocity.
- Acute Care:Hospital systems front-load expenditure on powered support surfaces before CMS Hospital-Acquired Condition Reduction Program penalty exposure materializes. Clinical engineering departments now control specification authority previously held by materials management.
- Long-Term Care:For-profit chains across the Southeastern US expand mattress procurement as state-level Medicaid managed care contracts tie capitated payments to skin integrity outcomes.
- Home Care:Discharge planning integrates support surface rentals with wound care dressings under CMS prospective payment system refinements for post-acute care.
- Rehabilitation Centers:Patient mobility transition protocols demand hybrid surface configurations supporting both pressure redistribution and early mobilization.
- Palliative Care:Comfort-focused positioning systems prioritize shear reduction over active pressure modulation in end-of-life settings.
Acute Care dominates current procurement volume; Long-Term Care is expanding most quickly.
End User:
Facility scale and reimbursement structure fragment buying behavior across institutional and community-based settings.
- Hospitals:Academic medical centers pilot AI-enabled pressure mapping systems that feed predictive algorithms for tissue perfusion risk, seeking population health data assets beyond passive surface functionality.
- Nursing Homes:Independent operators in the Southeast resist exclusive group purchasing arrangements, maintaining direct relationships with foam converters to preserve pricing leverage.
- Home Healthcare Agencies:Episode-based billing incentives drive bundled procurement of dressings and rental surfaces for post-discharge monitoring.
- Skilled Nursing Facilities:CMS Star Rating methodology revisions compress mattress replacement cycles from seven-year to four-year intervals.
- Outpatient Clinics:Limited capital budgets favor pressure relief cushions over powered surfaces for procedural immobility under two hours.
Skilled Nursing Facilities anchor replacement demand; Home Healthcare Agencies show steepest expansion trajectory.
Distribution Channel:
Fulfillment speed and technical service capabilities separate channel winners in fragmented geography.
- Direct Sales:Hospital contracts retain dominance through clinical specialist teams who navigate IT security reviews for EMR-integrated sensor systems.
- Online Platforms:Smaller nursing home accounts below 50 beds migrate to digital procurement for standardized cushion and dressing replenishment.
- Medical Distributors:Same-day fulfillment networks anchored in distribution density now reach rural critical access hospitals below 25 beds.
- Pharmacies:Community retail channels capture home care dressing sales through Medicare Part B durable medical equipment billing.
- Specialty Stores:Direct-to-consumer positioning aids serve family caregivers managing palliative care at home.
Direct Sales commands contract value; Online Platforms gains share fastest in sub-scale accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in pressure ulcer prevention concentrates manufacturing capacity in states with lower compliance-cost burdens while demand clusters where CMS penalty exposure is most acute. Production migrates toward jurisdictions with streamlined FDA 510(k) review timelines and favorable state-level medical device tax treatment.
Southeast
Florida and Georgia skilled nursing facilities accelerate mattress replacement cycles as CMS Star Rating methodology revisions elevate skin integrity metrics. State Medicaid managed care contracts in Florida tie capitated payments to pressure ulcer outcomes, compelling fleet upgrades ahead of renewals. For-profit long-term care chains concentrate procurement authority in Tampa and Orlando metropolitan clusters.
Southwest
Texas nursing homes expand dynamic support surface procurement under tightened CMS Hospital-Acquired Condition Reduction Program enforcement. The state's Medicaid managed care quality withholds now capture 3-5% of payments contingent on skin integrity performance. Houston and Dallas medical device distribution hubs anchor same-day fulfillment networks reaching rural critical access hospitals.
West
California academic medical centers pilot AI-enabled pressure mapping systems with embedded sensor-to-EMR connectivity. OSHA safe patient handling guidelines in the state mandate mechanical lift-compatible bed configurations that accelerate legacy fleet retirement. Los Angeles and San Francisco procurement committees now require powered surface specifications for all ICU and step-down unit purchases.
Midwest
Illinois and Ohio manufacturing corridors host integrated foam conversion facilities supplying silicone-coated multilayer composites to acute care systems. Stryker leverages Midwest production footprints to sustain margin control on high-specification alternating air mattresses. Chicago distribution density enables rapid replenishment of wound care dressings to post-acute operators across the Great Lakes region.
Northeast
New York hospital systems front-load capital expenditure on powered support surfaces before penalty exposure materializes under CMS prospective payment system refinements. Boston academic medical centers seek population health data assets through sensor-embedded mattress pilots. The Northeast corridor's aging demographic density sustains demand for home care channel wound care dressings under episode-based billing structures.
US Pressure Ulcer Prevention Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sensor-embedded and AI-enabled surface configurations. The market structure stratifies across three tiers: integrated manufacturers with captive foam conversion, distribution-heavy intermediaries with GPO anchoring positions, and specialized surface technology developers. Two dominant competitive moves define current positioning: backward integration into medical-grade foam precursor supply and bundling of skin care protocols with support surface contracts.
Within the integrated manufacturing tier, Stryker and Medline Industries exemplify divergent scale strategies. Stryker anchors a position through Midwest production footprint concentration and clinical engineering department relationships. Medline Industries occupies a sticky position in group purchasing organization portfolios through private-label skin care protocol bundling. Cardinal Health represents the distribution-density archetype, anchoring same-day fulfillment networks that reach rural critical access hospitals below 25 beds.
| Leading Market Players |
|---|
| Medline Industries |
| Cardinal Health |
| Stryker |
| 3M |
| Integra LifeSciences |
| Baxter |
| Agiliti Health |
| Arjo |
| Invacare Corporation |
| Others |
Pricing and Supply Chain Analysis
Biomedical engineer concentration across Midwest manufacturing corridors feeds labor-cost differentials that widen pricing-tier spreads between integrated producers and distribution-dependent competitors. FDA 510(k) clearance complexity amplifies these spreads by embedding 18-24 month development timelines into premium-tier cost structures.
Pricing Analysis
Distributor margin layers compress as Cardinal Health and regional intermediaries compete on same-day fulfillment density to rural critical access hospitals. Three-tier pricing structure across premium, standard, and economy levels separates sensor-embedded alternating air systems from basic low-air-loss configurations and refurbished legacy surfaces. Pricing pressure stems from Medicaid managed care quality withholds that force skilled nursing operators toward mid-tier specifications despite clinical preference for advanced features. Independent nursing home chains in the Southeast exhibit highest price sensitivity, while academic medical centers prioritize IT integration and data infrastructure compatibility over unit cost.
Supply Chain Analysis
Workforce availability in Illinois and Ohio chemical processing corridors anchors domestic foam conversion capacity, though polyether polyurethane precursor production concentrates among three petrochemical suppliers. Medical-grade foam composites draw from silicone coating specialists in the Midwest and textile weaving operations in the Carolinas. Single-source vulnerability in petrochemical feedstock supply exposes converters to input cost volatility when oil price shocks transmit through polymer markets. Distribution runs through hospital-centric direct sales for powered surfaces and GPO-anchored networks for consumable replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US pressure ulcer prevention market functions as a stable compounder, with CMS penalty structures and demographic aging providing durable demand visibility across replacement cycles.
For Market Incumbents: Extend sensor-to-EMR connectivity capabilities to defend against AI-enabled pressure mapping entrants. Deepen backward integration into silicone-coated foam precursor supply to offset petrochemical cost volatility. Anchor group purchasing organization portfolios through bundled skin care protocol licensing that raises switching costs for skilled nursing operators. For New Entrants and Emerging Players: Launch via online platforms targeting sub-50-bed nursing home accounts that resist exclusive GPO arrangements. Penetrate rural critical access hospitals below 25 beds through same-day fulfillment partnerships with regional distributors. Develop mechanical lift-compatible positioning devices that address OSHA compliance gaps in legacy hospital bed fleets. For Investors and Strategic Acquirers: Medical device conglomerates with post-acute care footprints are the most active acquirer in this space, seeking sensor-embedded surface developers to fill technology gaps. Target mid-scale foam converters with FDA 510(k) clearance capabilities and established clinical engineering relationships. Watch CMS Star Rating methodology revisions as the signal indicating replacement cycle compression and fleet upgrade acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Investment | Powered support surfaces require pressure mapping studies that extend development timelines beyond unpowered alternatives. |
| Sensor-to-EMR Integration Development | Hospital procurement committees in California and New York now mandate embedded connectivity for ICU purchases. |
| Medicaid Managed Care Contracting | Texas and Florida operators face 3-5% capitated payment withholds tied to skin integrity outcomes. |
| Silicone-Coated Foam Backward Integration | Midwest production footprints sustain margin control against distribution-heavy competitors. |
| AI-Enabled Pressure Mapping Pilot Deployment | Academic medical centers seek population health data assets beyond passive surface functionality. |
Research Methodology
Coverage spans the Southeast, Southwest, Midwest, West, and Northeast, with primary inputs from each region's skilled nursing operator clusters and hospital procurement committees. The approach combines structured interviews with biomedical engineers, GPO contracts managers, clinical engineering directors, and foam converter operations heads with secondary validation against FDA 510(k) databases, CMS Medicare cost reports, and hospital procurement system records. Bottom-up facility-level demand modeling triangulates against top-down reimbursement flow analysis.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation dimensions include product type, care setting, facility scale, and distribution channel structure, with regional regulatory cluster as an additional modeled layer. CAGRs derive from replacement cycle compression analysis, demographic projection alignment, and reimbursement policy trajectory assessment. Forecast inputs incorporate Medicaid managed care penetration rates and CMS Star Rating methodology weighting changes.
Several conditions sit outside the modeled scope, including federal healthcare program restructuring, novel antimicrobial surface technologies, and cross-border manufacturing relocation. Forecasts reflect assumptions regarding continued CMS penalty enforcement and petrochemical supply stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Global Incontinence and Ostomy Care Product Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Patient Identification Wristbands Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Disposable Incontinence Products (Dips) Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Abdominal Pads Market