
 Japan Mobile Biometrics Market | 2026-2036
Japan Mobile Biometrics Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Mobile Biometrics Market Insights
The capability gap between integrated hardware-software developers and component-only suppliers is collapsing. NEC Corporation leverages its domestic semiconductor fabrication partnerships to sustain end-to-end biometric module production. Fujitsu Limited anchors government identity contracts through its palm-vein authentication lineage. Mofiria Corporation specializes in compact finger-vein sensors for embedded mobile devices, occupying a defensible niche against larger module vendors.
Japan mobile biometrics encompasses physiological and behavioral identity verification systems deployed on smartphones, tablets, and wearable endpoints, typically incorporating capacitive fingerprint sensors, structured-light facial mapping arrays, or infrared iris cameras operating at 940 nanometers for liveness detection. These systems authenticate users for financial transactions, facility access, and citizen services by matching live biometric samples against encrypted templates stored in secure enclaves or distributed ledgers. Fingerprint recognition dominates current shipment volumes due to mature CMOS sensor costs and established consumer familiarity, while facial recognition grows fastest among younger demographics accustomed to FaceID-style interactions. Voice recognition lags in enterprise adoption because ambient noise sensitivity limits its reliability for high-assurance mobile payments, though machine learning-based anti-spoofing models are narrowing this performance gap.
METI's digital transformation guidelines, PMDA's medical device software standards for biometric health applications, and JIS authentication frameworks collectively shape product certification requirements and procurement eligibility for government contracts. Vendors must navigate overlapping compliance obligations where biometric data encryption standards intersect with telecommunications equipment regulations. Stakeholders should monitor how forthcoming amendments to Japan's Act on Protection of Personal Information reshape cloud-based template storage architectures and cross-border data handling protocols.
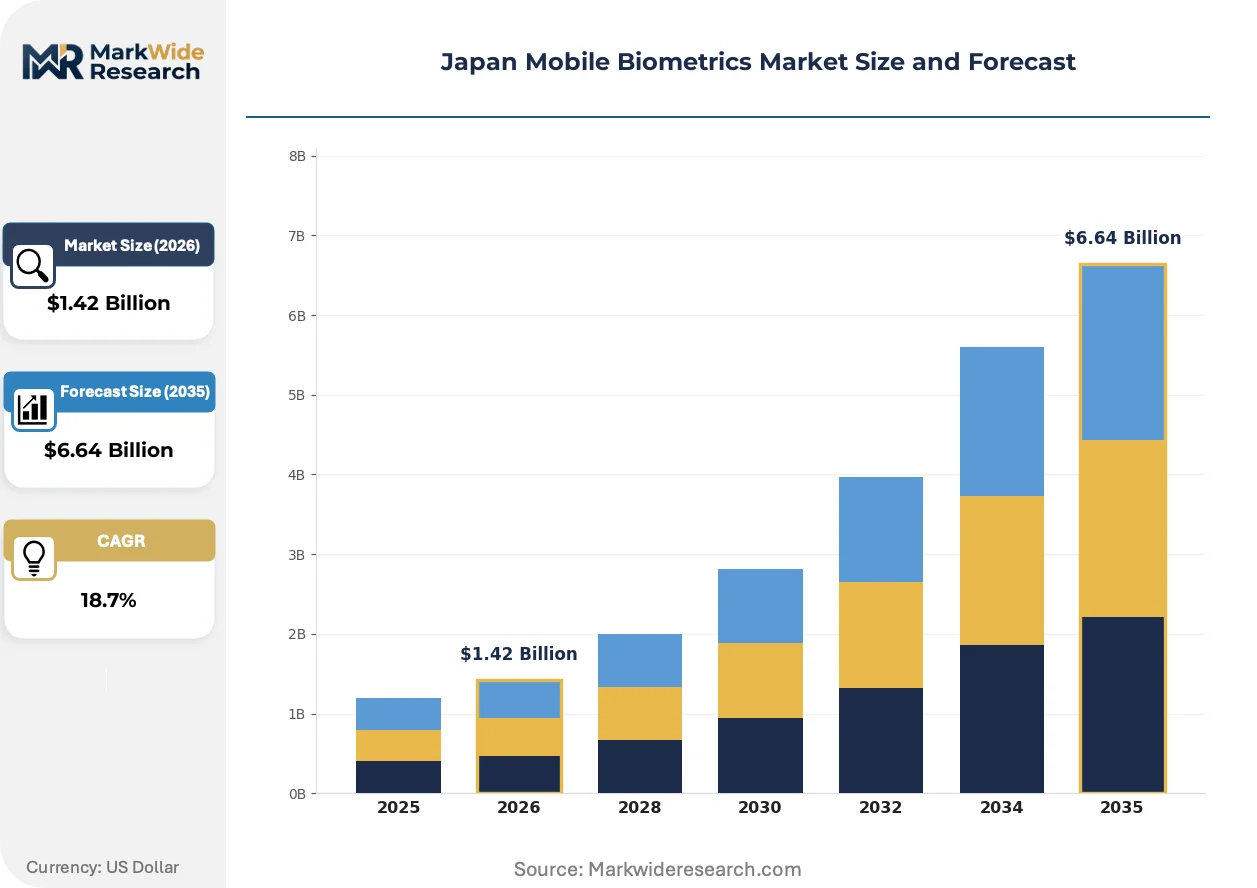
Market Dynamics
METI's digital identity infrastructure mandates and the F-Gas Regulation's pressure on biometric cloud cooling are compressing vendor margins while accelerating sensor deployment timelines across Japan's financial corridor.
Growth Catalysts
- METI Digital Transformation Guidelines:Government procurement rules now mandate biometric authentication for citizen service portals, forcing municipal IT upgrades in Tokyo, Osaka, and Nagoya.
- CMOS Sensor Cost Maturation:Domestic semiconductor fabrication partnerships have collapsed fingerprint module pricing, enabling tier-two banks to deploy mobile banking authentication.
- Kanto Government-Corridor Concentration:Municipal digital ID pilots in Saitama, Chiba, and Kanagawa prefectures are driving concentrated sensor procurement volumes.
Market Restraints
- Secure Enclave Input Concentration:Taiwan-based foundries dominate the advanced packaging required for liveness-detection chipsets, exposing Japanese vendors to geopolitical supply interruption.
- JIS Certification Friction:Overlapping biometric data encryption standards and telecommunications equipment regulations create 14-18 month product approval timelines.
- Behavioral Biometric Substitution:Keystroke dynamics and gait analysis from wearable OEMs threaten to displace physiological sensors in low-assurance applications.
Strategic Opportunities
- Kansai Underpenetration:Kyoto and Hyogo prefectures lag Tokyo in municipal digital ID deployment, creating whitespace for vendor expansion.
- Healthcare Convergence:PMDA medical device software standards for biometric health monitoring are opening patient authentication applications in hospital networks.
- Palm-Vein Channel Innovation:Contactless biometric ATMs in convenience store chains are creating new distribution pathways beyond traditional bank procurement.
Industry Challenges
- Embedded Systems Talent Gap:Shortage of engineers skilled in 940-nanometer infrared camera integration with secure enclaves is extending R&D cycles.
- Legacy Core Banking Integration:Mainframe authentication protocols at regional banks require costly middleware development for biometric API compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Mobile Biometrics Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerprint Recognition, Facial Recognition, Iris Recognition, Voice Recognition Application: Mobile Payments, Access Control, Identity Verification, Law Enforcement End User: Retail, Financial Institutions, Government, Healthcare Technology: Biometric Sensors, Software Solutions, Machine Learning, Data Encryption |
| Companies Covered | NEC Corporation, Fujitsu Limited, Mofiria Corporation, Japan Computer Vision Corp., Towa Corporation, Nuance Communications, HID Global Corporation, Aware Inc., Suprema Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Mobile Biometrics Market Trends and Innovations
Sensor fusion architectures and liveness-detection algorithms are redrawing competitive boundaries between hardware-integrated and software-only vendors in Japan's authentication supply base.
Multimodal biometric systems combining fingerprint and facial recognition is fragmenting the historically dominant single-sensor market. Tier-one financial institutions in Tokyo are deploying these fused architectures for high-value transaction verification. The technology is fragmenting procurement patterns as buyers demand interoperable modules rather than proprietary end-to-end stacks.
METI's forthcoming amendments to the Act on Protection of Personal Information will mandate encrypted template storage within domestic cloud infrastructure. This policy shift is forcing biometric service providers to re-architect distributed ledger implementations. Healthcare and government verticals are accelerating compliance investments ahead of enforcement.
Bank procurement teams are consolidating vendor relationships around full-stack authentication providers capable of JIS certification, sensor supply, and cloud middleware. Regional banks in Tohoku and Hokkaido are abandoning point-solution purchasing in favor of multi-year service contracts. The shift is most visible among second-tier financial institutions seeking to offload compliance liability to integrated platform vendors.
Japan Mobile Biometrics Market Segmentation
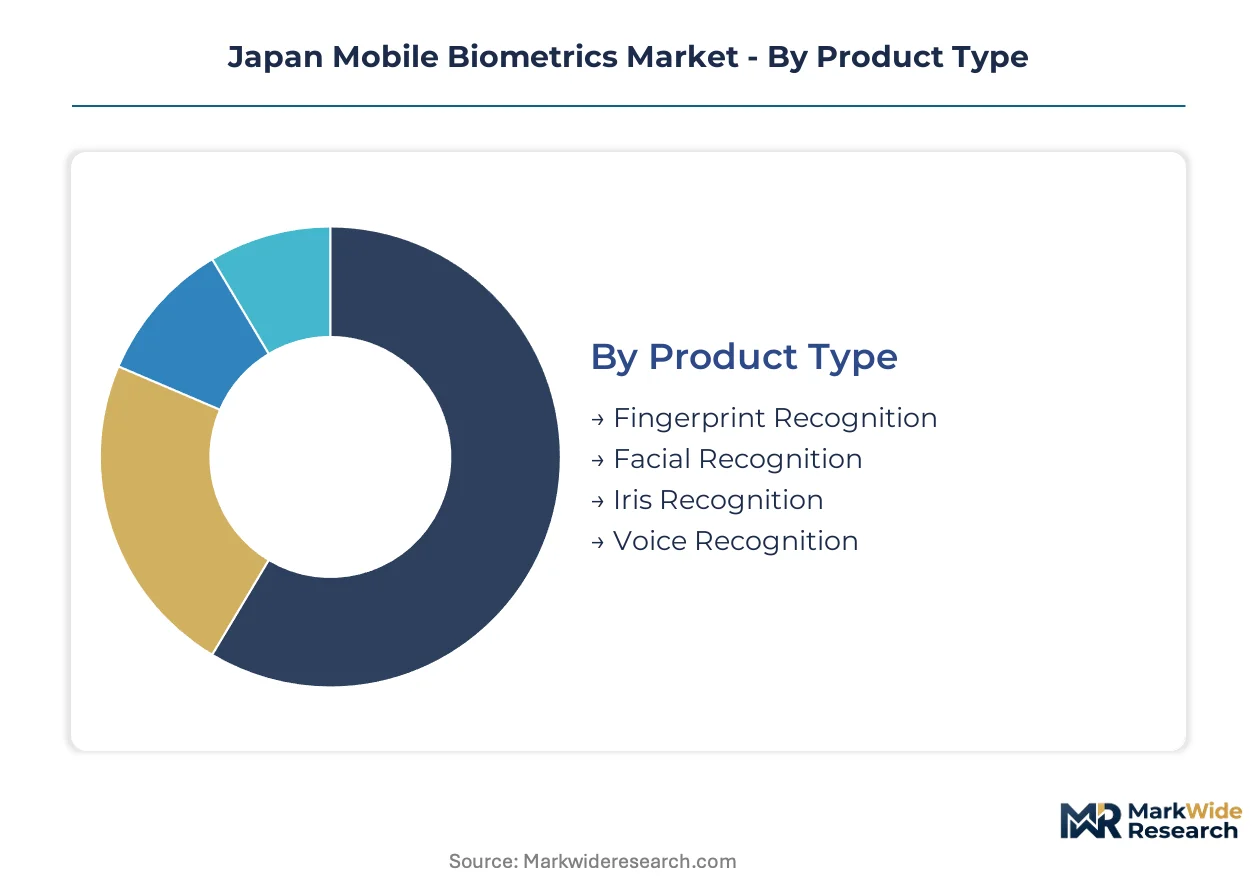
Japan's mobile biometrics market fragments across four critical dimensions where substitution pressures and regulatory compliance reshape procurement priorities. Vendors must align sensor specifications with METI's digital identity mandates while navigating distinct performance requirements across financial, government, and healthcare verticals.
Product Type:
Facial recognition modules face the strongest substitution threat from behavioral biometrics, while fingerprint sensors defend their installed base through cost maturation and consumer habituation.
- Fingerprint Recognition:Capacitive CMOS sensors operating at 508 pixels per inch resolution dominate current shipment volumes through established consumer familiarity and collapsed module pricing from domestic semiconductor partnerships. Regional banks in Tohoku deploy these for mobile banking authentication where transaction values remain below multimodal verification thresholds.
- Facial Recognition:Structured-light mapping arrays with 940-nanometer infrared projection enable liveness detection against presentation attacks. Younger demographics in Tokyo and Osaka drive fastest adoption through FaceID-style interaction expectations, though ambient lighting variability constrains outdoor reliability.
- Iris Recognition:Near-infrared cameras capture unique stromal patterns with lower false acceptance rates than facial alternatives. Airport and port authority deployments in Kansai favor this modality for high-assurance traveler verification.
- Voice Recognition:Machine learning-based speaker verification models struggle with ambient noise sensitivity in enterprise settings. Keystroke dynamics from wearable OEMs threaten displacement in low-assurance mobile payment scenarios.
Fingerprint recognition retains volume leadership; facial recognition holds the steepest expansion curve.
Application:
Cost tier stratification separates premium multimodal deployments from economy single-sensor implementations across Japan's authentication value chain.
- Mobile Payments:Financial institutions in Tokyo's government-corridor demand fused fingerprint-facial architectures for transactions exceeding regulatory thresholds. METI procurement rules mandate biometric authentication for citizen service portals, compressing deployment timelines.
- Access Control:Corporate facility deployments in Osaka prioritize contactless modalities to reduce surface transmission concerns. Palm-vein sensors at convenience store ATMs create novel distribution pathways beyond traditional bank procurement.
- Identity Verification:Municipal digital ID pilots in Saitama, Chiba, and Kanagawa prefectures concentrate sensor procurement volumes. JIS certification friction extends product approval timelines to 14-18 months.
- Law Enforcement:Forensic mobile biometric units require specialized liveness-detection chipsets with secure enclave integration. Taiwan-based foundry concentration exposes supply interruption risks.
Mobile payments command the highest certification investment; identity verification applications expand most quickly across municipal deployments.
End User:
Government procurement anchors premium pricing tiers through compliance-heavy contract structures, while retail volume scales through standardized module specifications.
- Financial Institutions:Tier-one banks in Tokyo consolidate vendor relationships around full-stack providers capable of JIS certification, sensor supply, and cloud middleware. Second-tier institutions in Hokkaido abandon point-solution purchasing for multi-year service contracts.
- Government:METI digital transformation guidelines force municipal IT upgrades across Kanto's government-corridor. Encrypted template storage mandates within domestic cloud infrastructure re-architect distributed ledger implementations.
- Healthcare:PMDA medical device software standards for biometric health monitoring open patient authentication applications in hospital networks. Nagoya and Kyoto medical centers pilot palm-vein verification for pharmaceutical dispensing.
- Retail:Convenience store chains drive contactless biometric ATM deployment through palm-vein channel innovation. Standardized fingerprint modules satisfy entry-level loss-prevention requirements.
Financial institutions sustain the largest compliance-driven procurement; healthcare verticals climb fastest on regulatory convergence with medical device frameworks.
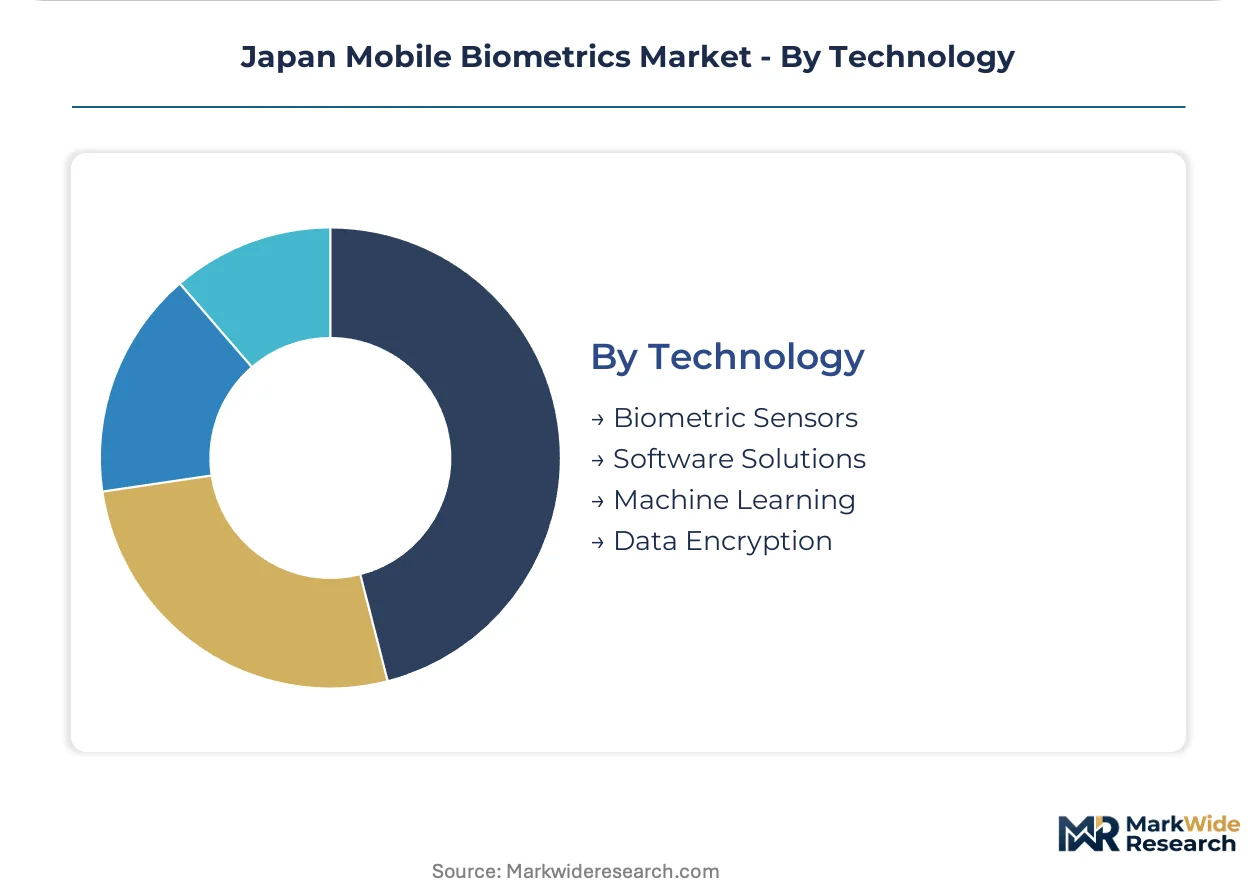
Technology:
Supply concentration in advanced packaging for liveness-detection chipsets creates margin pressure across hardware-integrated versus software-only vendor strategies.
- Biometric Sensors:Capacitive fingerprint modules and structured-light facial arrays constitute the hardware foundation. Domestic semiconductor fabrication partnerships enable NEC Corporation's end-to-end biometric module production.
- Software Solutions:Template matching algorithms and secure enclave middleware differentiate integrated platform vendors. Regional banks seek to offload compliance liability through multi-year service contracts.
- Machine Learning:Anti-spoofing models narrow the performance gap for voice recognition in noisy environments. Embedded systems talent scarcity extends R&D cycles for 940-nanometer infrared camera integration.
- Data Encryption:AES-256 template protection and distributed ledger architectures face reconfiguration under forthcoming Act on Protection of Personal Information amendments. Cross-border data handling protocols require architectural revision.
Biometric sensors retain hardware revenue concentration; machine learning capabilities differentiate fastest among software-only entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional demand elasticity diverges sharply across Japan's prefectural hierarchy. Tokyo's financial institutions absorb premium pricing for multimodal authentication suites, while regional banks in Tohoku and Hokkaido prioritize cost-optimized fingerprint modules. Municipal procurement timelines compress as METI digital transformation deadlines approach.
Kanto/Tokyo
Tier-one financial institutions in Tokyo's government-corridor drive concentrated demand for fused fingerprint-facial architectures. METI procurement rules mandate biometric authentication for citizen service portals, accelerating municipal IT upgrades across Saitama, Chiba, and Kanagawa prefectures. Shinjuku and Marunouchi banking clusters deploy these systems for high-value transaction verification exceeding regulatory thresholds.
Kansai/Osaka
Corporate facility deployments in Osaka prioritize contactless modalities to reduce surface transmission concerns. Palm-vein sensors at convenience store ATMs create novel distribution pathways beyond traditional bank procurement. Kyoto and Hyogo prefectures lag Tokyo in municipal digital ID deployment, generating whitespace for vendor expansion into underpenetrated municipal contracts.
Chubu/Nagoya
Medical centers in Nagoya pilot palm-vein verification for pharmaceutical dispensing under PMDA medical device software standards. Healthcare convergence with biometric health monitoring opens patient authentication applications in hospital networks. Toyota's industrial corridor generates secondary demand for workforce access control systems.
Kyushu
Regional banks in Fukuoka adopt cost-optimized fingerprint modules as CMOS sensor pricing collapses from domestic semiconductor partnerships. Airport and port authority deployments favor iris recognition for high-assurance traveler verification. Second-tier financial institutions abandon point-solution purchasing for multi-year service contracts.
Hokkaido
Remote banking infrastructure in Hokkaido faces legacy core banking integration challenges requiring costly middleware development. Sparse population density limits municipal digital ID pilot scale, compressing procurement volumes. Regional institutions seek to offload compliance liability to integrated platform vendors capable of JIS certification.
Japan Mobile Biometrics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Japan's mobile biometrics supply base. NEC Corporation and Fujitsu Limited anchor the upper tier through end-to-end production capabilities and government identity contract lineage. Mofiria Corporation occupies a defensible niche among compact sensor specialists. Competitive dynamics center on JIS certification velocity and domestic cloud infrastructure partnerships rather than price alone.
Within the integrated hardware-software tier, NEC Corporation leverages domestic semiconductor fabrication partnerships to sustain biometric module production. Fujitsu Limited anchors government identity contracts through established authentication lineage. Mofiria Corporation exemplifies the specialist archetype, occupying compact finger-vein sensor niches against larger module vendors. These three entities represent the competitive spectrum from full-stack platforms to embedded component suppliers.
| Leading Market Players |
|---|
| NEC Corporation |
| Fujitsu Limited |
| Mofiria Corporation |
| Japan Computer Vision Corp. |
| Towa Corporation |
| Nuance Communications |
| HID Global Corporation |
| Aware Inc. |
| Suprema Inc. |
| Others |
Pricing and Supply Chain Analysis
Fourteen-to-eighteen-month JIS certification timelines compress procurement cycles and amplify pricing power for integrated platform vendors capable of bundling sensor supply with compliance liability transfer. This lead-time structure concentrates buyer preference around full-stack providers while squeezing margins for component-only suppliers competing on module cost alone.
Pricing Analysis
Multi-year service contracts now drive lifetime value as regional banks in Hokkaido and Tohoku abandon point-solution purchasing. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified multimodal suites from single-sensor modules and commodity fingerprint components. Price differentiation hinges on certification grade and after-sales middleware support. Cost compression in economy tiers intensifies because CMOS sensor pricing collapsed from domestic semiconductor partnerships. Second-tier financial institutions exhibit highest price sensitivity; tier-one Tokyo banks prioritize compliance bundling over unit cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate sensor procurement as municipal digital ID pilots compress deployment timelines across Kanto prefectures. Taiwan, South Korea, and Japan anchor advanced packaging for liveness-detection chipsets with 940-nanometer infrared capabilities. Raw material dependencies center on CMOS wafers, structured-light projection arrays, and secure enclave processors. Single-source vulnerability in Taiwan-based foundries exposes Japanese vendors to geopolitical supply interruption. Distribution runs through integrated platform vendors capable of JIS certification rather than direct component sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through JIS certification creates switching costs that lock financial institutions into multi-year vendor relationships.
For Market Incumbents: Fortify government identity contract lineage through accelerated PMDA medical device software certification for healthcare convergence applications. Deepen backward integration into 940-nanometer infrared camera production to offset Taiwan foundry concentration risk. Channel control over palm-vein ATM distribution networks in convenience store chains limits specialist sensor displacement.
For New Entrants and Emerging Players: Cloud middleware integration for legacy core banking systems represents the most penetrable service-layer gap as regional banks seek to offload compliance liability. Target Hokkaido and Tohoku prefectures where sparse municipal digital ID pilot scale has compressed incumbent presence. Partner with domestic semiconductor fabricators for captive CMOS sensor supply as a go-to-market anchor against integrated platform pricing.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because METI digital transformation guidelines and forthcoming Act on Protection of Personal Information amendments continuously re-certify incumbent advantages. Acquisition candidates should demonstrate JIS certification velocity and domestic cloud infrastructure partnerships rather than pure sensor innovation. Watch for enforcement timing of encrypted template storage mandates as the signal triggering consolidation waves among non-compliant service providers.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Medical Device Certification | Opens hospital network patient authentication applications under biometric health monitoring standards. |
| Domestic Cloud Infrastructure Partnership | Positions vendors for METI-mandated encrypted template storage requirements ahead of enforcement. |
| Palm-Vein Channel Expansion | Creates convenience store ATM distribution pathways beyond traditional tier-one bank procurement. |
| Legacy Core Banking Middleware Development | Captures regional bank demand for biometric API compatibility with mainframe authentication protocols. |
| CMOS Sensor Backward Integration | Reduces Taiwan foundry exposure while collapsing module costs for tier-two financial institution penetration. |
Research Methodology
A spread of perspectives from biometric platform engineering directors, regional bank IT procurement managers, METI policy officers, and JIS certification auditors converged on the working assumptions. Primary interviews combined with secondary validation against METI digital transformation guidelines, PMDA medical device software standards, JIS authentication framework documentation, and domestic semiconductor partnership disclosures. Bottom-up sensor shipment estimates triangulated with top-down financial institution IT spending analysis.
Segmentation dimensions modeled include biometric modality type, application vertical, end-user institution tier, and technology layer across hardware sensors, software solutions, machine learning capabilities, and data encryption architectures. CAGRs were derived from installation base growth rates, replacement cycle compression, and regulatory mandate enforcement schedules. Industry-specific forecast inputs incorporated municipal digital ID pilot expansion timelines and CMOS sensor cost maturation curves from domestic fabrication partnerships.
Forecasts assume regulatory continuity in METI digital identity infrastructure mandates and PMDA medical device software standards; material policy shifts would require re-modeling. Supply interruption scenarios from Taiwan foundry concentration and amendments to Japan's Act on Protection of Personal Information represent primary revision triggers. Revision becomes warranted when JIS certification friction extends beyond current fourteen-to-eighteen-month baselines or when behavioral biometric substitution rates in low-assurance applications cross threshold displacement levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Security Software
Europe User Provisioning Market
Security Software
Italy Endpoint Detection and Response Market
Security Software
Keystroke Dynamics Market
Security Software
Global Reputation Protection Software Market
Security Software
Device-Embedded Biometric Authentication Market
Security Software
Sound Masking Systems Market
Security Software
SSL Inspection Solution Market
Security Software
Global Email Verification Tools Market
Security Software
IAM Security Services Market
Security Software
Bot Mitigation Market
Security Software
Global Optical Encryption Market
Security Software
Global Insider Threat Management ITM Software Market
Security Software
Online Background Check Market
Security Software
Global Security Operation Center As a Service Market
Security Software
Mobile Security Market
Security Software
Asia Pacific Anti Money Laundering Solutions Market