
 Elastomeric Connectors Market | 2026-2036
Elastomeric Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Elastomeric Connectors Market Foresight
Multi-source procurement for conductive elastomer compounds is restructuring supply relationships across the connector industry. TE Connectivity leverages captive silicone compounding capabilities to secure formulation consistency for automotive clients. Molex sustains geographic dominance in Asia-Pacific through localized molding operations and regional distribution hubs. Amphenol differentiates via aerospace-certified product lines that meet stringent outgassing and temperature-cycle specifications.
Elastomeric connectors are compression-molded or liquid-injection-molded assemblies comprising conductive particle-filled silicone or EPDM matrices that maintain electrical continuity under mechanical deflection, thermal cycling, and environmental sealing requirements. Their primary purpose is to replace rigid pin-and-socket interfaces in applications demanding compliance to irregular surfaces, vibration damping, or hermetic sealing. Cable connectors and sensor connectors represent the most mature revenue pools, while power connectors for electrified drivetrains capture the fastest expansion trajectory as voltage ratings climb. Silicone dominates material selection for high-temperature applications, though EPDM competes aggressively in cost-sensitive industrial segments where fluid resistance takes priority over thermal range.
FDA regulations govern biocompatible elastomeric connectors in medical device applications, while EPA oversight affects volatile organic compound emissions from solvent-based adhesive bonding processes. RoHS and REACH frameworks in Europe restrict hazardous substance content and mandate substance-of-concern disclosure across the supply chain, directly influencing material qualification timelines and supplier certification requirements. Stakeholders must monitor evolving battery-electric vehicle platform architectures, as pack-level voltage escalation and thermal management integration will redefine connector specification thresholds faster than incumbent test standards can adapt.
Market Dynamics
Automotive electrification programs are compressing qualification timelines for vibration-resistant interconnects while REACH and RoHS compliance in Europe tightens material specifications across the conductive elastomer supply chain.
Growth Catalysts
- 800V platform proliferation:Battery-electric vehicle architectures demand higher voltage-rated elastomeric connectors with enhanced thermal cycling endurance, pulling silicone formulations into powertrain applications.
- REACH substance disclosure mandates:European material qualification requirements accelerate supplier consolidation toward compounders with established certification databases and pre-qualified conductive particle suppliers.
- Precision manufacturing clusters:Germany's industrial corridor concentrates procurement of high-reliability connector assemblies for medical imaging and semiconductor test equipment.
Market Restraints
- Silver flake cost volatility:Conductive filler prices fluctuate with precious metals markets, compressing margins for standard-grade product lines and forcing reformulation toward nickel-graphite alternatives.
- Asian molding concentration:Liquid injection molding capacity clusters in coastal China and South Korea, creating geographic supply risk for North American and European OEMs seeking regional sourcing.
- Thermal range trade-offs:EPDM formulations sacrifice high-temperature performance for fluid resistance, limiting adoption in under-hood automotive segments where silicone dominates despite higher cost.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor and mobile device production create localized demand for elastomeric test socket connectors and display interconnects.
- Solid-state battery integration:Next-generation cell architectures require compression-sealed interconnects with improved cycle life, opening specification windows for advanced silicone-fluorocarbon hybrids.
- Direct OEM compounding partnerships:Tier-one suppliers bypass distributor networks to secure captive formulation development, locking in volume commitments and technical collaboration.
Industry Challenges
- Multi-physics simulation expertise:Concurrent electrical-thermal-mechanical modeling of particle-filled elastomers requires specialized finite element analysts, creating talent scarcity in connector design teams.
- Automotive PPAP timeline compression:Production part approval process documentation for new electrified platforms demands 40% faster completion than historical ICE programs, straining quality engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Elastomeric Connectors Market |
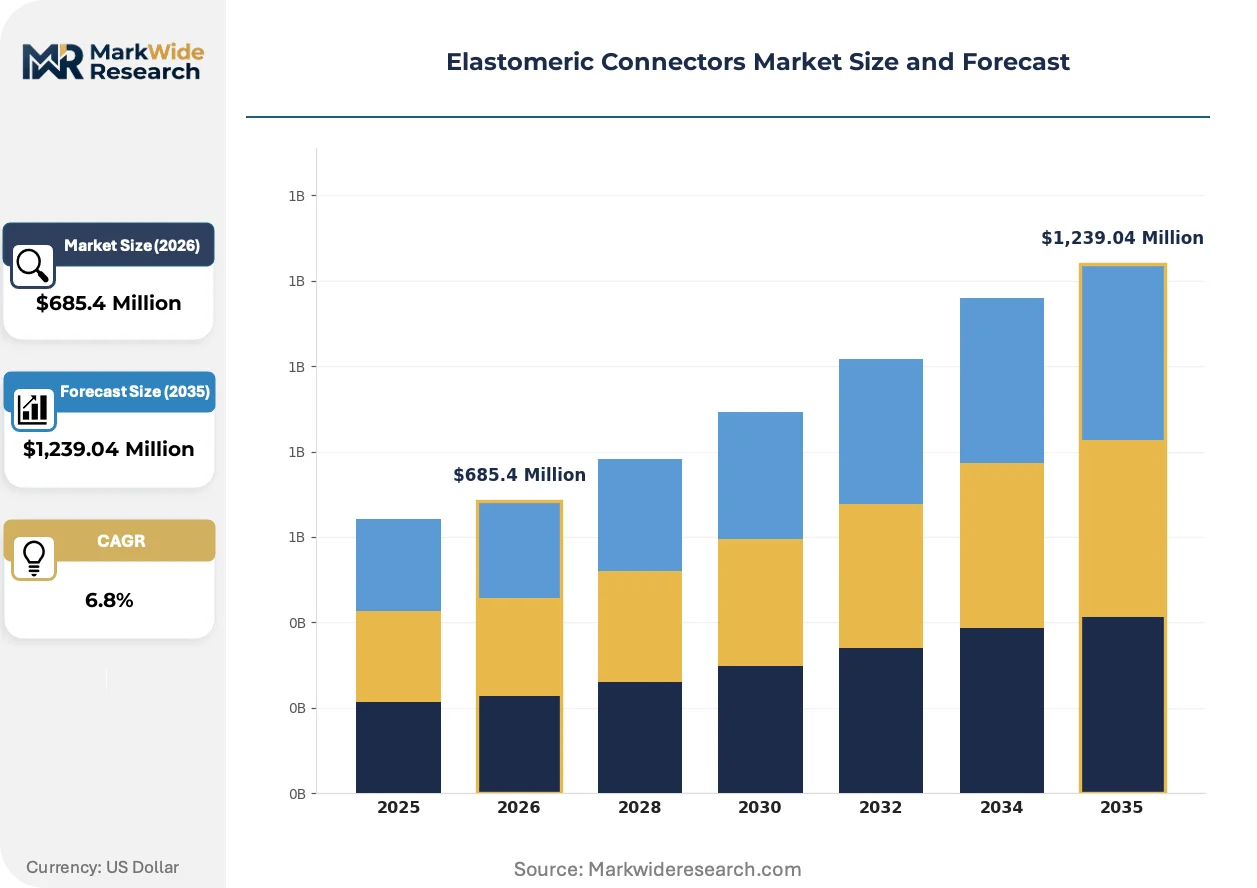
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,239.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Junction Boxes, Cable Connectors, Sensor Connectors, Power Connectors End User: Automotive, Aerospace, Electrical, Industrial Application: Data Transmission, Power Distribution, Signal Interfacing, Control Systems Material: Silicone, Neoprene, EPDM, Polyurethane |
| Companies Covered | TE Connectivity, Molex, Amphenol, Samtec, 3M, DuPont, Dow, Shenzhen Changmai Technology, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Elastomeric Connectors Market Shifts & Advancements
Conductive particle dispersion technologies and automated molding controls are compressing performance variance while regulatory substance tracking digitizes supply chain transparency requirements.
Self-assembling monolayer surface treatments on silver-coated glass spheres is unifying electrical conductivity and environmental sealing within single-material solutions. Tier-one automotive suppliers are qualifying these enhanced fillers for battery management system connectors ahead of 2025 platform launches. The technology is unifying previously separate EMI shielding and compression seal functions, reducing part count in compact electronic modules.
EU F-Gas Regulation phase-down schedules are accelerating transition toward aqueous-based adhesive bonding processes for elastomeric connector assembly. Industrial consequence includes capital equipment replacement across European molding facilities and reformulation of solvent-based primers. Medical device manufacturers in Germany and Switzerland are responding fastest, driven by MDR documentation requirements for process validation.
Consolidated supplier scorecards now weight carbon footprint disclosure alongside technical performance, compressing vendor lists to compounders with verified Scope 3 data. Tier-two automotive suppliers are replacing fragmented regional sourcing with single-source global contracts backed by certified LCA documentation. This behavioral shift is most visible in German industrial procurement, where CSRD reporting obligations cascade through supply tiers.
Elastomeric Connectors Market Segmentation
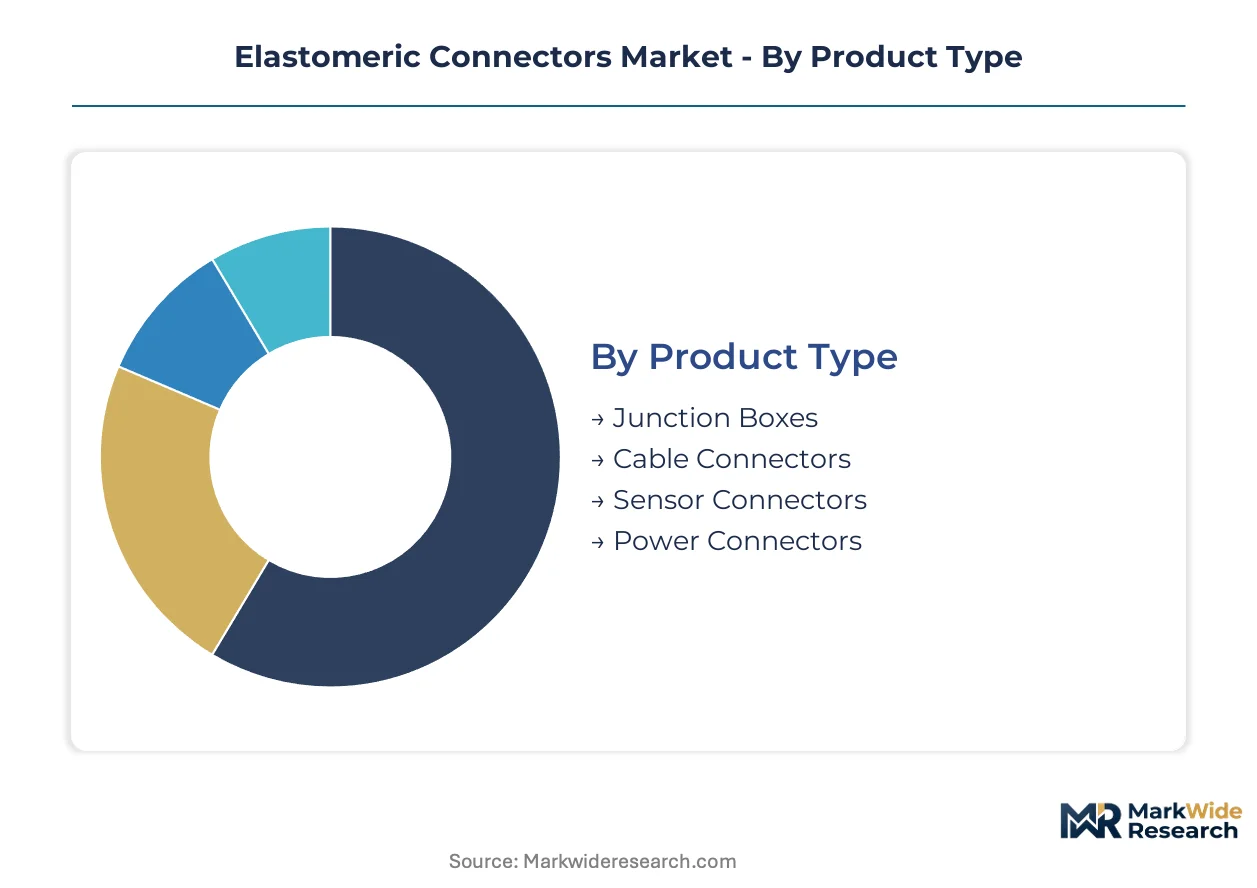
Elastomeric connector procurement varies sharply by technical specification and end-use severity, with capital deployment favoring segments qualified for electrified automotive and aerospace platforms. Material selection and voltage rating thresholds create divergent margin profiles across product categories.
Product Type:
Power connectors and cable connectors demand the heaviest upfront tooling investment due to multi-cavity molding infrastructure and high-voltage validation chambers.
- Power Connectors:Compression-molded assemblies with silver-coated particle fillers rated for 800V battery-electric vehicle architectures. Procurement concentrates among German and South Korean automotive tier-ones as platform voltages escalate.
- Cable Connectors:Liquid-injection-molded interconnects with integrated strain relief for harness assemblies. Demand clusters in precision manufacturing corridors where vibration damping and hermetic sealing specifications converge.
- Sensor Connectors:Miniature elastomeric interfaces for MEMS and pressure transducer applications in industrial automation.
- Junction Boxes:Multi-port compression seals for power distribution nodes in commercial electrical infrastructure.
Power connectors absorb the bulk of installed capacity; cable connectors are expanding most quickly.
End User:
Customer qualification timelines stretch longest in aerospace and automotive, compressing supplier margins through extended engineering change cycles.
- Automotive:Battery management system and inverter interconnects requiring thermal cycling endurance from -40°C to 150°C. Procurement accelerates in Germany's industrial corridor where electrification programs tighten vibration resistance specifications.
- Aerospace:Outgassing-certified silicone formulations for avionics modules and satellite payload interfaces. REACH substance disclosure mandates in Europe extend material qualification timelines for conductive particle suppliers.
- Industrial:Fluid-resistant EPDM connectors for process control equipment in chemical processing environments.
- Electrical:Compression-sealed junction assemblies for grid infrastructure and renewable energy installations.
Automotive procurement commands the largest compound development budgets; aerospace maintains the steepest expansion trajectory.
Application:
Power distribution applications carry the highest liability exposure, driving insurance and testing costs above signal-level interconnect categories.
- Power Distribution:High-current elastomeric busbar interfaces for battery pack and charging module integration. Demand concentrates where 800V architectures displace legacy 400V systems in premium electric vehicle segments.
- Data Transmission:Low-insertion-force connectors for high-speed signal integrity in semiconductor test equipment. Precision manufacturing clusters in Germany and Switzerland specify these for medical imaging and wafer probe applications.
- Signal Interfacing:Sensor-to-controller elastomeric bridges for industrial IoT and automation networks.
- Control Systems:Hermetically sealed feedback loop connectors for process automation and robotics.
Power distribution claims the dominant share of formulation R&D spending; data transmission is climbing the fastest.
Material:
Silicone compounding requires the most sophisticated process control infrastructure, with platinum-cure systems demanding cleanroom molding environments.
- Silicone:Platinum-cured conductive formulations with glass transition temperatures below -50°C for aerospace and under-hood automotive applications. REACH and RoHS compliance in Europe restricts filler chemistry options, consolidating procurement toward pre-certified compounders.
- EPDM:Sulfur-cured matrices with ethylene-propylene base polymers for fluid-resistant industrial connectors. Cost-sensitive procurement in electrical infrastructure favors EPDM where thermal range requirements remain moderate.
- Neoprene:Chloroprene-based formulations balancing oil resistance and mechanical durability for heavy equipment.
- Polyurethane:Castable elastomer systems for abrasion-resistant connectors in mobile machinery and robotics.
Silicone dominates high-reliability specification volumes; EPDM is gaining share fastest in cost-optimized industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver flake supply from Mexican mining districts and South Korean smelters anchors conductive filler procurement for connector compounders serving automotive and industrial demand centers.
Germany
Battery-electric vehicle platform launches by BMW and Volkswagen pull 800V-rated silicone connectors into powertrain procurement. REACH substance disclosure mandates through ECHA consolidate supplier qualification toward pre-certified compounders. Stuttgart and Munich industrial corridors concentrate precision manufacturing demand for medical imaging and semiconductor test equipment.
China
Domestic EV production exceeding eight million units annually compresses qualification timelines for vibration-resistant interconnects. MIIT standards for automotive electrical safety tighten material traceability requirements across the supply chain. Yangtze River Delta molding clusters in Jiangsu and Zhejiang provinces supply liquid-injection-molded cable connectors for regional harness assemblers.
United States
IRA production tax credits for domestic battery cell manufacturing expand demand for compression-sealed power distribution connectors. EPA oversight of volatile organic compound emissions affects solvent-based adhesive bonding processes in Midwest molding facilities. Detroit-area automotive tier-ones specify thermal cycling endurance from -40°C to 150°C for under-hood applications.
South Korea
Hyundai-Kia electrification programs specify silicone-fluorocarbon hybrid formulations for next-generation battery architectures. MFDS biocompatibility frameworks govern medical device connector applications in Seoul medical technology clusters. Busan-Ulsan coastal manufacturing zones concentrate liquid injection molding capacity for export-oriented harness suppliers.
India
PLI scheme incentives for semiconductor and mobile device production create localized demand for elastomeric test socket connectors. BIS certification requirements for electrical safety extend material qualification timelines for imported conductive compounds. Karnataka and Tamil Nadu electronics manufacturing corridors attract display interconnect procurement from domestic EMS providers.
Elastomeric Connectors Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and molding scale, producing a tiered structure where captive compounding capabilities separate premium suppliers from distributors. The vendor base clusters around three strategic archetypes: integrated material-compound-connector manufacturers, specialized molding houses sourcing formulated resins, and regional distributors qualifying third-party products. Dominant competitive moves include backward integration into conductive particle supply and geographic expansion through licensing agreements with local molders.
Within the integrated manufacturing tier, TE Connectivity and Molex exemplify archetypes of material-compound-connector vertical control, while Amphenol occupies a position emphasizing aerospace-certified product lines. These three anchors represent divergent strategic postures: captive silicone compounding for automotive consistency, Asia-Pacific localized molding networks, and high-reliability specification leadership respectively.
| Leading Market Players |
|---|
| TE Connectivity |
| Molex |
| Amphenol |
| Samtec |
| 3M |
| DuPont |
| Dow |
| Shenzhen Changmai Technology |
| ABB |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialty compounders anchor conductive elastomer supply, translating fragmented molding capacity into disciplined pricing tiers that reward captive formulation capabilities and penalize distributor-dependent suppliers.
Pricing Analysis
Warranty-backed qualification support is bundled into premium-tier automotive contracts while standard industrial connectors ship with limited technical coverage. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified silicone formulations from automotive-grade EPDM and commodity cable interconnects. Price differentiation stems from REACH pre-certification status and volume scale commitments, with German automotive tier-ones showing lowest sensitivity due to platform-lock-in effects. Cost compression in standard-grade EPDM segments is intensifying because nickel-graphite reformulation shifts expose compounders to raw material qualification delays.
Supply Chain Analysis
Silver-coated glass sphere supply rests on Japanese specialty chemical producers and South Korean smelter operations, creating geographic concentration risk for conductive filler procurement. Conductive particle compounding draws from German industrial corridor expertise, Chinese Yangtze River Delta molding clusters, and South Korean liquid injection capacity. Raw material dependencies span platinum-cure silicone systems, sulfur-cured EPDM base polymers, and precious metal-coated filler particles. Single-source vulnerability in aerospace-certified silicone formulations exposes tier-two suppliers to ECHA substance disclosure delays. Distribution runs through authorized distributor networks for standard products and direct OEM partnerships for platform-locked automotive specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Conductive elastomer compounding capacity is tightening faster than molding scale-up, propping pricing power with pre-certified suppliers who own formulation IP.
For Market Incumbents: Acquire captive conductive particle supply agreements to lock in silver flake and nickel-graphite sourcing ahead of qualification timeline compression. Defensive consolidation toward German precision manufacturing clusters and South Korean automotive tier-ones insulates against EPDM substitution threats from fluid-resistant industrial segments. Certification investment in REACH and RoHS pre-qualified compound databases extends pricing power as European disclosure mandates cascade through supply tiers. For New Entrants and Emerging Players: Enter via Indian electronics manufacturing corridors where PLI scheme incentives for semiconductor and mobile device production outpace localized elastomeric connector supply. White-space targets cluster in test socket connectors for domestic EMS providers and display interconnects for Karnataka and Tamil Nadu manufacturing zones. A technical partnership with established German compounders accelerates BIS certification timelines and bypasses fragmented distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap molding houses with dormant automotive qualification capabilities in coastal China and South Korea. Long-term viability hinges on 800V platform proliferation sustaining silicone formulation premiums against EPDM cost competition. Watch for solid-state battery architecture announcements as inflection signals for compression-sealed interconnect specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Conductive Particle Supply | Captive silver flake sourcing secures formulation consistency for automotive clients facing REACH disclosure mandates. |
| Platinum-Cure Silicone Capacity Expansion | Cleanroom molding infrastructure in Germany's industrial corridor captures aerospace and medical imaging procurement. |
| Direct OEM Compounding Partnerships | Bypassing distributor networks locks in volume commitments from BMW and Volkswagen electrification programs. |
| REACH Pre-Certification Database Investment | ECHA substance disclosure compliance accelerates supplier qualification timelines for European automotive tier-ones. |
| Aqueous-Based Adhesive Bonding Transition | EU F-Gas Regulation compliance replaces solvent-based primers in European molding facilities serving medical device manufacturers. |
Research Methodology
Independent corroboration across Tier 1 supplier procurement directors, conductive compounder technical R&D leads, and automotive platform engineers underwrites the qualitative findings. Primary interviews with liquid injection molding operators, distributor channel partners, and ECHA regulatory affairs specialists combined with secondary validation from SEC filings, MIIT automotive safety standards, and customs trade data. Bottom-up triangulation across product type, material grade, and end-use severity dimensions converged with top-down macroeconomic and regulatory scenario analysis.
Rate-of-change decomposition across the analysis window isolates volume effects from mix-shift and pricing dynamics in conductive elastomer procurement. Segmentation dimensions modeled include connector product type, base polymer chemistry, voltage rating tier, and regional manufacturing cluster. CAGRs were derived from fitted growth curves calibrated to automotive electrification program announcements and industrial automation capital expenditure patterns. Forecast inputs incorporated battery-electric vehicle platform voltage escalation timelines and precision manufacturing equipment procurement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under silver price volatility and REACH substance restriction expansion. Forecasts reflect assumptions about automotive qualification timeline compression and EPDM-silicone substitution elasticities in industrial segments. Battery pack architecture shifts and EU F-Gas Regulation enforcement intensity warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passive And Interconnecting Electronic Components
Wirewound Resistor Market
Passive And Interconnecting Electronic Components
Pcs and Laptops MLCC Market
Passive And Interconnecting Electronic Components
Discrete Diodes Market
Passive And Interconnecting Electronic Components
Copper Busbar and Profiles Market
Passive And Interconnecting Electronic Components
Interconnects and Passive Components Market
Passive And Interconnecting Electronic Components
Through Hole Resistor Market
Passive And Interconnecting Electronic Components
Ceramic Insulator Market
Passive And Interconnecting Electronic Components
Through-Hole Passive Components Market
Passive And Interconnecting Electronic Components
Active and Passive Electronic Components Market
Passive And Interconnecting Electronic Components
Chip Resistor Market
Passive And Interconnecting Electronic Components
Passive and Interconnecting Electronic Components Market
Passive And Interconnecting Electronic Components
Electrical Wiring Interconnection System (EWIS) Market
Passive And Interconnecting Electronic Components
Copper Clad Laminate for Consumer Electronics Market
Passive And Interconnecting Electronic Components
Thick Film Resistor Market
Passive And Interconnecting Electronic Components
Multilayer Ceramic Capacitor Market
Passive And Interconnecting Electronic Components
United Kingdom MLCC Market