
 Spargers Market | 2026-2036
Spargers Market Size, Share, and Industry Trends Forecast 2026-2036
Spargers Market Analytics
Asset-light leasing models for high-purity gas dispersion equipment are reshaping competitive entry barriers in the spargers sector. MOTT leverages its porous metal expertise to anchor premium positioning in bioreactor applications. Porvair Filtration Group sustains cross-sector reach through membrane and sintered product diversification. ELMRIDGE Jet Apparatus specializes in custom jet-type configurations for niche chemical processing demands.
A sparger is a device that introduces gas into liquid through porous media, nozzles, or perforated tubes, typically operating at bubble sizes between 0.5 and 500 microns depending on pore rating and gas pressure differential. It serves to maximize gas-liquid contact area for oxygen transfer, carbonation, stripping, or chemical reaction acceleration across industrial bioprocessing and environmental systems. Stainless steel spargers dominate pharmaceutical and food-grade installations where steam-in-place validation and repeated autoclaving cycles are mandatory. Ceramic spargers are gaining traction in corrosive chemical environments where thermal shock resistance and inertness outweigh metallic alternatives. Subsurface configurations lead wastewater treatment volumes, while floating designs address variable-level aquaculture ponds.
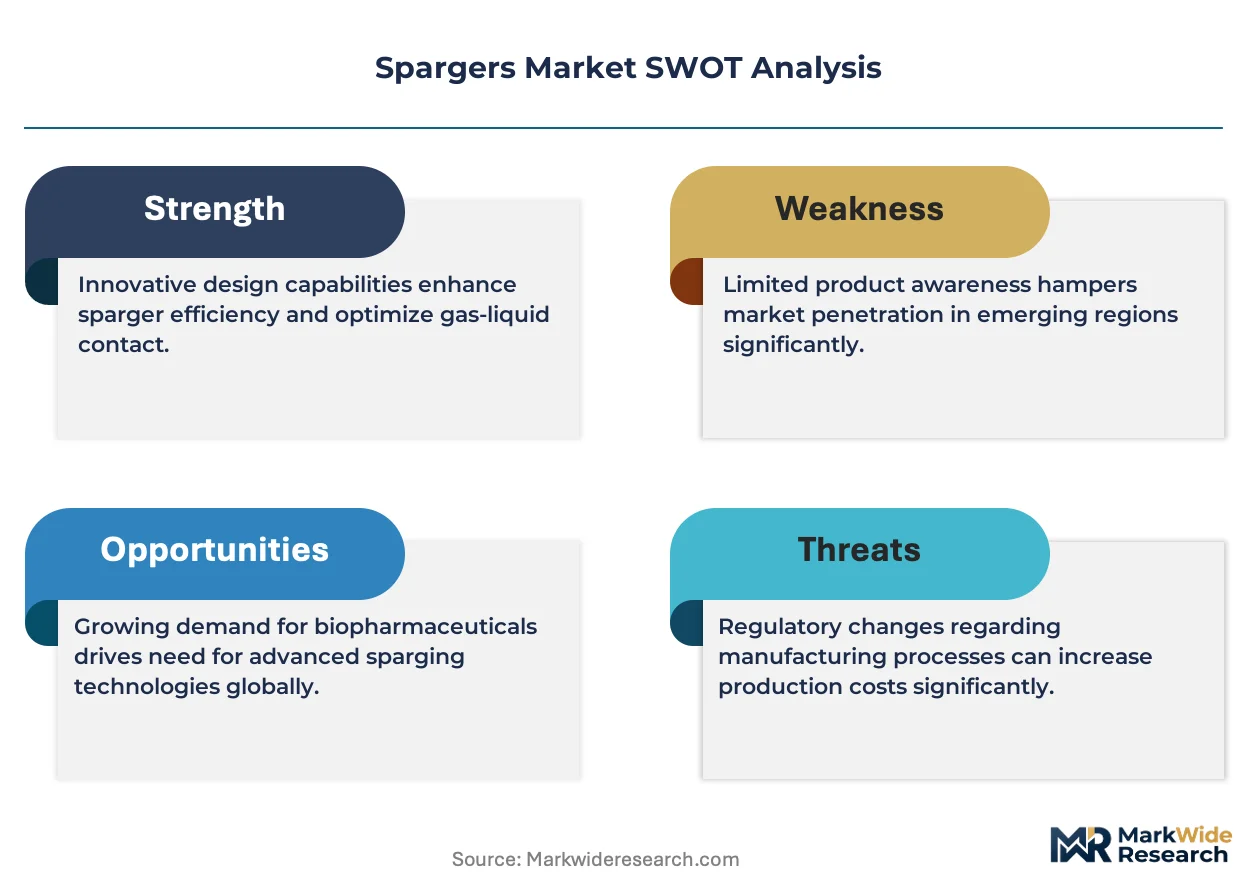
FDA sterilization guidelines and EMA Annex 1 revisions on aseptic manufacturing directly elevate documentation and material traceability requirements for sparger suppliers serving injectable drug producers. EPA effluent standards in the United States and REACH substance restrictions in Europe channel demand toward corrosion-resistant ceramic and certified stainless steel constructions over commodity plastics. Stakeholders must weigh material certification costs against lifecycle durability when specifying spargers for regulated environments.
Market Dynamics
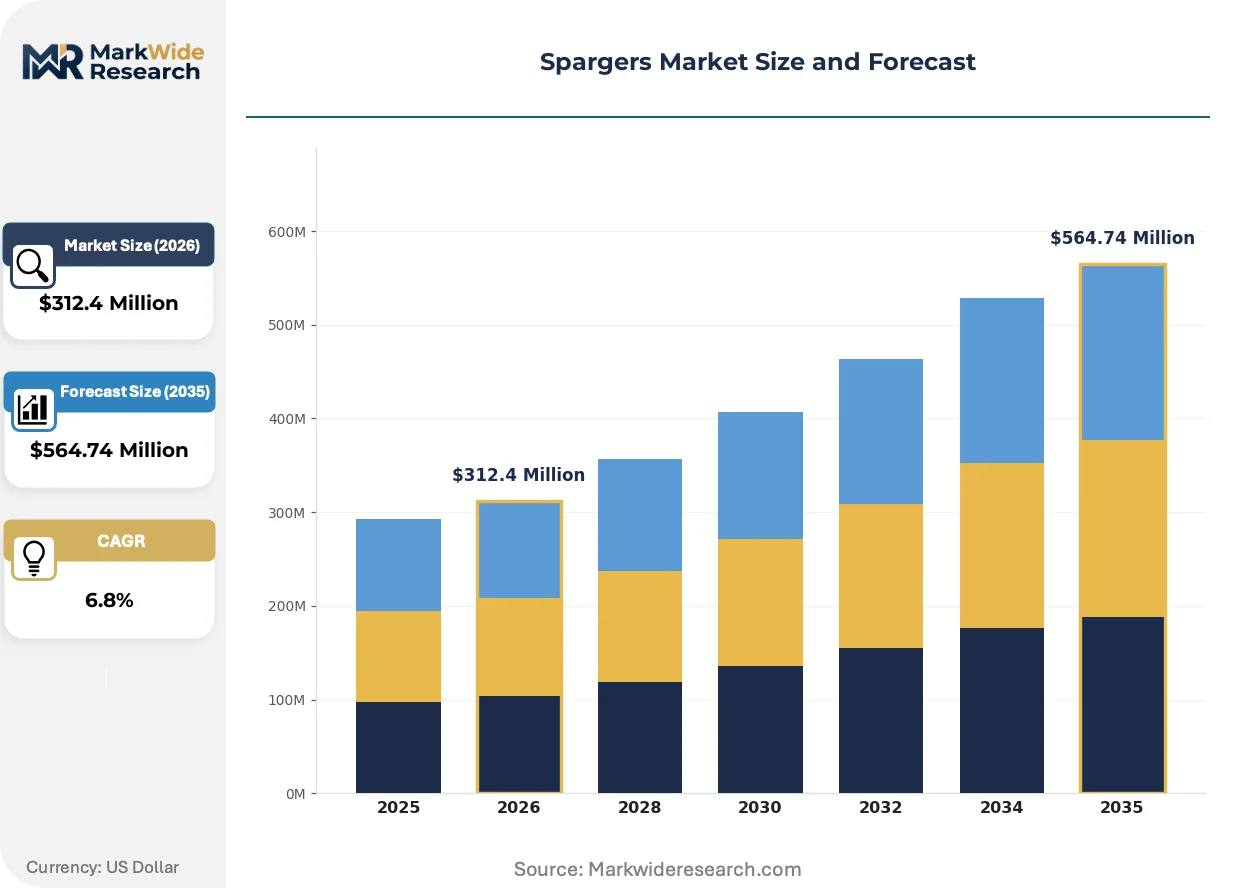
Biopharmaceutical fermentation scale-up and tightening FDA and EMA sterilization mandates are compressing material qualification timelines while elevating stainless steel and ceramic specifications across sparger procurement cycles.
Growth Catalysts
- FDA sterilization guidelines:Steam-in-place validation requirements for injectable drug manufacturing are mandating porous metal sparger upgrades across US bioprocessing facilities.
- Biopharmaceutical fermentation:Cell culture expansion in single-use bioreactors is pulling demand for high-purity gas dispersion equipment in Germany and India.
- Ceramic material advances:Thermal shock-resistant alumina formulations are opening corrosive chemical processing applications previously closed to metallic alternatives.
Market Restraints
- Specialized sintered metal supply concentration:Premium porous stainless steel feedstock production concentrates among a limited supplier base in Western Europe.
- REACH substance restrictions:Nickel alloy traceability documentation adds compliance layers that extend European procurement cycles by several quarters.
- Commodity plastic substitution ceiling:Polypropylene spargers face disqualification from pharmaceutical-grade installations due to autoclave temperature limitations.
Strategic Opportunities
- India biotechnology corridor:CDSCO-aligned manufacturing investments in Hyderabad and Bengaluru are creating demand for certified sparger infrastructure.
- Carbon capture solvent regeneration:Amine-based post-combustion capture systems require corrosion-resistant ceramic spargers for oxidative degradation control.
- Leasing model penetration:Asset-light equipment-as-a-service structures are lowering entry barriers for mid-scale fermentation operators in North America.
Industry Challenges
- Material certification timelines:FDA Master File documentation and EMA Annex 1 compliance validation extend supplier qualification periods beyond standard procurement windows.
- Cross-contamination protocol integration:Multi-product bioprocessing facilities face complex changeover procedures when deploying shared sparger infrastructure across different cell lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spargers Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Subsurface, Floating, Airlift, Mechanical Application: Wastewater Treatment, Fermentation, Aquaculture, Chemical Processing Material: Stainless Steel, Plastic, Glass, Ceramic End User: Food & Beverage, Pharmaceuticals, Biotechnology, Energy |
| Companies Covered | MOTT, Porvair Filtration Group, ELMRIDGE Jet Apparatus, GKN plc, Eriez Manufacturing Co, Tfi Filtration (India) Private Limited, Sentry Equipment Corp, CoorsTek, Saint-Gobain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spargers Market Evolving Landscape
Material science breakthroughs and regulatory documentation automation are compressing sparger development cycles while reshaping competitive differentiation around traceability rather than pore geometry alone.
Additive manufacturing of porous metal structures is enabling gradient density configurations that optimize bubble size distribution across variable gas flow rates. Biopharmaceutical equipment suppliers in Switzerland and Massachusetts are piloting these geometries for perfusion bioreactor applications. Laser-sintered titanium spargers with tunable porosity profiles are rendering obsolete conventional fixed-pore sintered tubes in high-value cell culture installations.
EMA Annex 1 revisions on aseptic manufacturing are mandating automated documentation systems for critical equipment traceability. Sparger suppliers must now integrate digital batch records and material genealogy tracking into their quality management systems. European injectable drug producers are prioritizing vendors with pre-validated electronic submission packages to compress regulatory filing timelines.
Service unbundling is separating sparger supply from installation validation and lifecycle maintenance contracts. Contract manufacturing organizations in Ireland and Singapore are sourcing hardware from specialized fabricators while retaining third-party commissioning agents for steam-in-place qualification. This bifurcation is compressing margins for full-service incumbents while opening margin pools for niche validation specialists in established pharmaceutical manufacturing clusters.
Spargers Market Segmentation
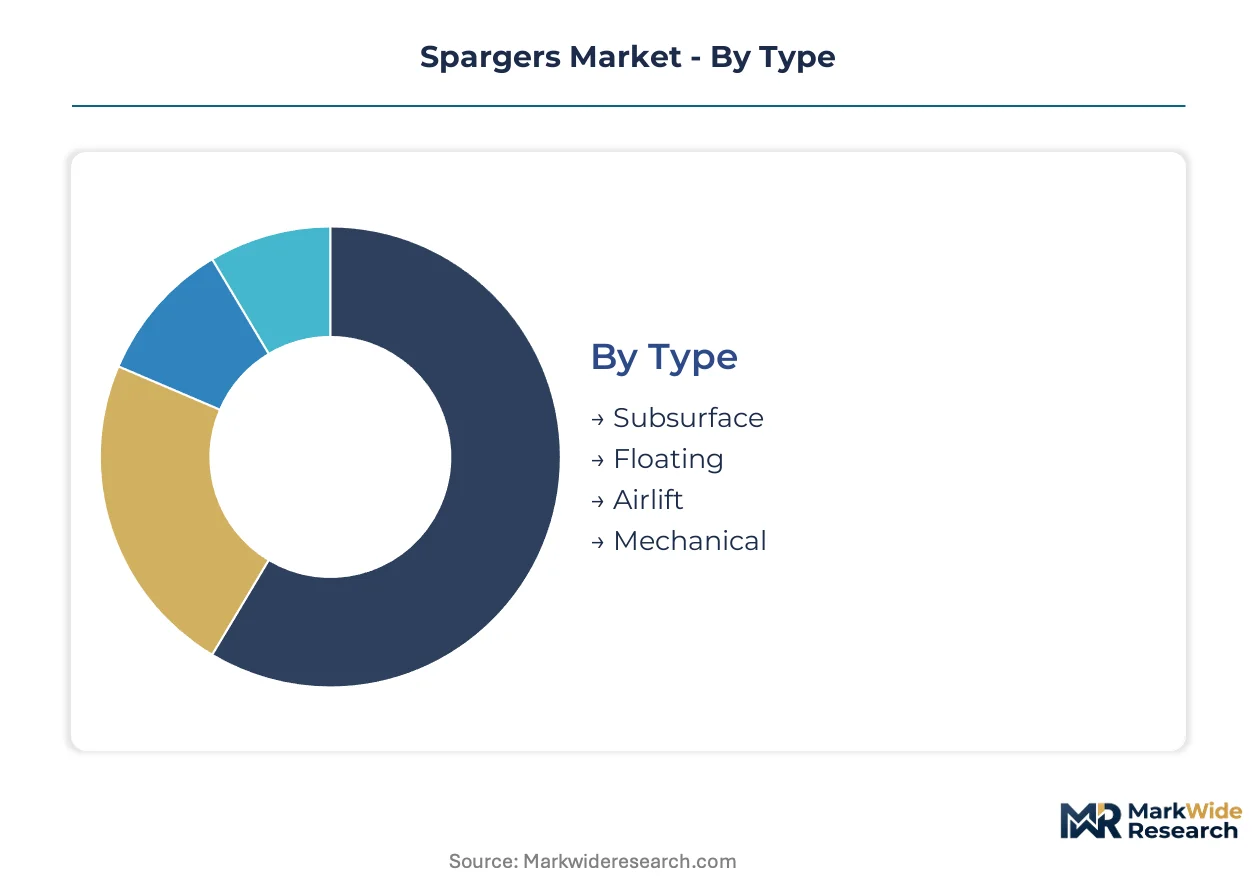
Sparger procurement patterns diverge sharply across installation geometry, material durability requirements, and regulatory exposure levels. Each segmentation axis carries distinct margin structures and qualification timelines that reshape vendor positioning strategies.
Type:
Mature configurations dominate installed base volumes while emerging geometries capture greenfield bioprocessing investments.
- Subsurface:Fixed-position porous tube or disc assemblies mounted at vessel base for maximum gas-liquid contact efficiency. Municipal wastewater plants in Germany and industrial fermentation facilities in India specify these for oxygen transfer coefficient optimization under variable organic loads.
- Floating:Buoyant assemblies that self-adjust to liquid level fluctuations in open aquaculture ponds and lagoon-based treatment systems. Shrimp farming operations across Andhra Pradesh and Tamil Nadu deploy floating configurations to maintain aeration during monsoon-driven level variations.
- Airlift:Draft tube configurations that harness gas injection for simultaneous mixing and mass transfer. Cell culture bioreactors leverage airlift geometries to eliminate mechanical seal contamination risks in aseptic mammalian cell lines.
- Mechanical:Motor-driven impeller-sparger hybrid systems for high-shear gas dispersion in viscous chemical slurries. Petrochemical solvent extraction units specify mechanical types where bubble coalescence suppression demands exceed passive diffusion limits.
Subsurface configurations retain volume leadership; floating designs hold the steepest expansion curve in aquaculture-intensive geographies.
Application:
Cost tier stratification separates commodity municipal installations from premium pharmaceutical-grade systems with documentation burdens.
- Wastewater Treatment:Activated sludge basins and anaerobic digesters deploy coarse-bubble and fine-bubble spargers for biological oxygen demand reduction. EPA effluent compliance deadlines in the United States are accelerating membrane bioreactor retrofits with integrated fine-pore ceramic sparger banks.
- Fermentation:Bioreactor oxygen transfer systems for antibiotic, enzyme, and therapeutic protein production. EMA Annex 1 steam-in-place validation requirements are disqualifying polypropylene spargers from mammalian cell culture applications across Swiss and Irish contract manufacturing facilities.
- Aquaculture:Pond and raceway aeration for intensive shrimp and finfish production. India's coastal aquaculture zones are substituting paddlewheel aerators with energy-efficient fine-bubble subsurface systems to reduce power costs.
- Chemical Processing:Hydrogenation reactors, oxidation vessels, and stripping columns requiring corrosion-resistant gas dispersion. Alumina ceramic spargers are displacing hastelloy alternatives in bromine-handling circuits where halide stress cracking destroys metallic components.
Wastewater treatment commands the largest installed base; fermentation applications deliver the highest unit margins through certification premiums.
Material:
Supply concentration in sintered metal feedstock creates procurement bottlenecks that favor vertically integrated stainless steel fabricators.
- Stainless Steel:Sintered 316L porous metal structures with steam-in-place compatibility and autoclave durability. FDA Master File documentation and material 3.1 certificates are mandatory for injectable drug manufacturing spargers supplied to Massachusetts and North Carolina bioclusters.
- Plastic:Polypropylene and PVDF injection-molded or sintered configurations for ambient-temperature chemical processing. REACH substance restrictions on phthalate plasticizers are narrowing European qualification pathways for polymer spargers in food-contact applications.
- Glass:Borosilicate fritted discs for laboratory-scale bioreactors and analytical applications. Academic research institutions and early-stage cell therapy developers specify glass spargers where single-use disposability outweighs capital equipment durability.
- Ceramic:Alumina and silicon carbide formulations for thermal shock resistance and extreme pH environments. Carbon capture amine regeneration systems are specifying alumina spargers to withstand oxidative degradation conditions that attack metallic alternatives.
Stainless steel retains pharmaceutical procurement dominance; ceramic formulations are climbing the fastest in corrosive chemical and carbon capture deployments.
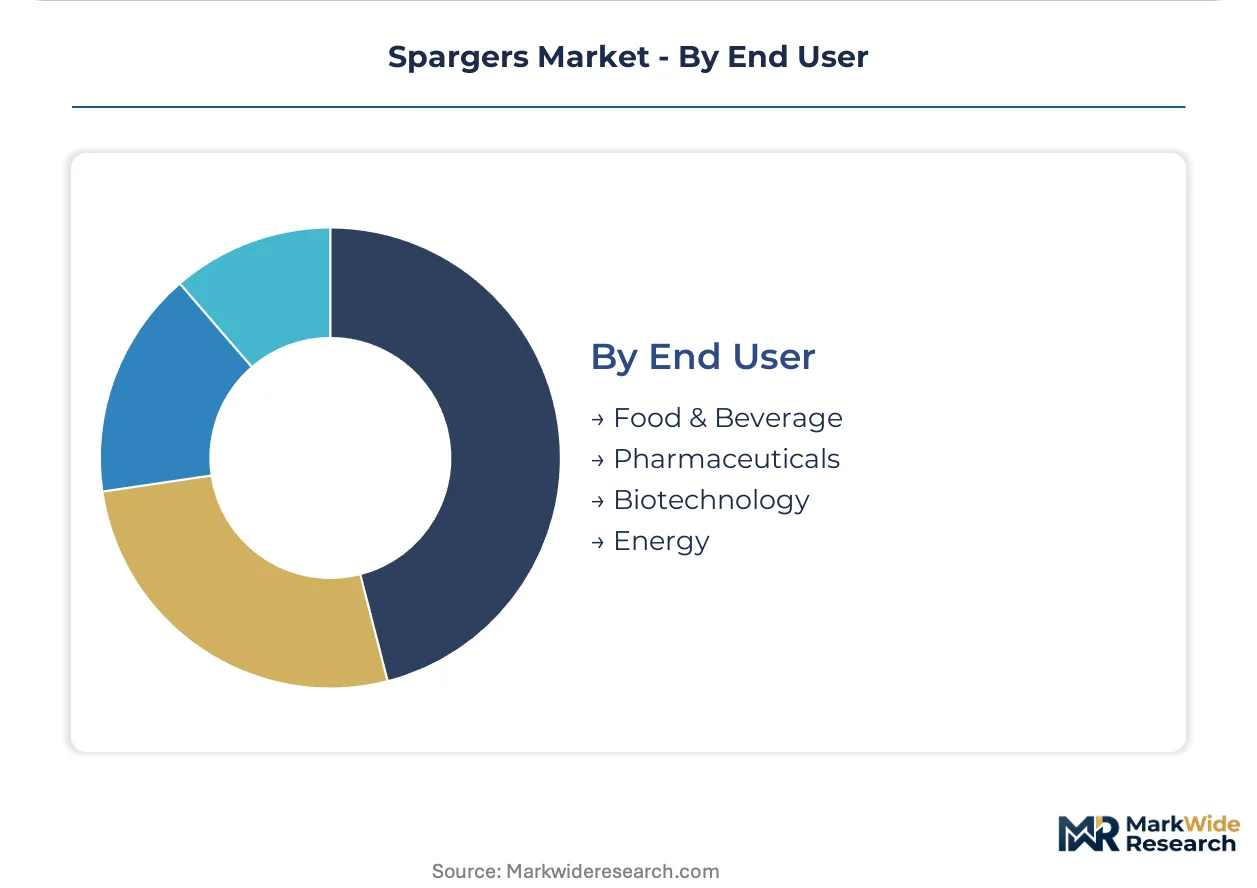
End User:
Customer type fragmentation separates price-sensitive municipal buyers from quality-system-intensive life science purchasers with extended validation cycles.
- Food & Beverage:Carbonation systems for soft drinks, beer brewing aeration, and dairy processing. FSSAI hygiene mandates and 3A sanitary standards are driving stainless steel upgrades in Indian dairy cooperatives and European craft brewing expansions.
- Pharmaceuticals:Aseptic manufacturing for injectables, vaccines, and biologics requiring complete material traceability. CDSCO manufacturing investments in Hyderabad's Genome Valley are pulling certified sparger infrastructure into Indian sterile fill-finish facilities.
- Biotechnology:Cell and gene therapy production, microbial fermentation, and perfusion culture systems. Massachusetts and Switzerland contract development organizations are piloting additively manufactured titanium spargers with gradient porosity for perfusion bioreactor optimization.
- Energy:Hydrogen electrolysis, fuel cell humidification, and carbon capture solvent regeneration. Post-combustion capture installations in the United States and Netherlands are specifying corrosion-resistant ceramic spargers for amine-based CO2 separation systems.
Pharmaceutical end users anchor premium pricing; energy sector procurement is expanding most quickly behind carbon capture deployment timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade procurement concentrates in mature biomanufacturing corridors, while chemical processing and aquaculture expansion pull demand toward emerging industrial clusters with evolving regulatory frameworks.
United States
FDA sterilization guidelines for injectable drug manufacturing are mandating porous metal sparger upgrades across Massachusetts and North Carolina bioclusters. EPA effluent standards are accelerating membrane bioreactor retrofits with integrated ceramic sparger banks in municipal wastewater facilities. Greater Boston contract development organizations are piloting additively manufactured titanium configurations for perfusion bioreactor applications.
Germany
EMA Annex 1 revisions on aseptic manufacturing are elevating documentation and material traceability requirements for sparger suppliers serving European injectable drug producers. REACH substance restrictions on nickel alloy traceability are extending procurement cycles for stainless steel components. The chemical processing corridor spanning North Rhine-Westphalia and Bavaria specifies corrosion-resistant alumina spargers for halide-handling circuits.
India
CDSCO-aligned manufacturing investments in Hyderabad's Genome Valley and Bengaluru's biotechnology hubs are creating demand for certified sparger infrastructure in sterile fill-finish facilities. FSSAI hygiene mandates are driving stainless steel upgrades in dairy cooperatives across Maharashtra and Gujarat. Coastal aquaculture zones in Andhra Pradesh and Tamil Nadu are substituting paddlewheel aerators with energy-efficient fine-bubble subsurface systems.
Switzerland
Swissmedic oversight of biologics manufacturing is compressing supplier qualification timelines for aseptic processing equipment. Contract manufacturing organizations are unbundling sparger supply from installation validation contracts to compress regulatory filing timelines. Basel-region pharmaceutical equipment suppliers are prioritizing vendors with pre-validated electronic submission packages.
Netherlands
Post-combustion carbon capture deployment timelines are specifying corrosion-resistant ceramic spargers for amine-based CO2 separation systems in energy sector installations. The Eindhoven Region's industrial equipment base is channeling demand toward thermal shock-resistant alumina formulations. Rotterdam-area chemical processors are displacing hastelloy alternatives with ceramic constructions in oxidative degradation environments.
Spargers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base spans porous metal fabricators, membrane filtration specialists, and custom jet-type configuration engineers. Three archetypes dominate: vertically integrated stainless steel sintering houses, diversified cross-sector filtration conglomerates, and niche custom-engineering boutiques. Capacity expansion in certified bioprocessing materials and strategic partnerships for regulatory documentation automation constitute the dominant competitive moves.
Within the porous metal specialization tier, MOTT and CoorsTek occupy positions anchored in premium bioreactor applications. Among diversified filtration conglomerates, Porvair Filtration Group exemplifies cross-sector reach through membrane and sintered product portfolios. Saint-Gobain represents the materials science conglomerate archetype with ceramic formulation capabilities serving corrosive chemical environments. These three entities collectively illustrate the competitive spectrum from pure-play metal fabrication to integrated materials platforms.
| Leading Market Players |
|---|
| MOTT |
| Porvair Filtration Group |
| ELMRIDGE Jet Apparatus |
| GKN plc |
| Eriez Manufacturing Co |
| Tfi Filtration (India) Private Limited |
| Sentry Equipment Corp |
| CoorsTek |
| Saint-Gobain |
| Others |
Value Network & Pricing Analysis
Undercapacity in sintered 316L porous metal feedstock across Western European mills is compressing supplier lead times while elevating pricing leverage for certified sparger fabricators serving FDA-validated bioprocessing installations.
Pricing Analysis
Certification level creates the primary spread across sparger procurement tiers, with FDA Master File documentation and EMA Annex 1 compliance validation commanding substantial premiums over standard industrial grades. Three-tier pricing structure separates pharmaceutical-grade stainless steel with full material traceability from food-grade ceramic configurations and commodity plastic alternatives for ambient chemical service. Cost compression in polypropylene spargers is intensifying because REACH substance restrictions on phthalate plasticizers are narrowing qualification pathways and forcing reformulation investments. Municipal wastewater operators exhibit the highest price sensitivity due to budget-constrained procurement cycles, while biotechnology contract manufacturers prioritize total cost of ownership over unit price.
Supply Chain Analysis
Premium porous stainless steel feedstock production concentrates in Germany, Switzerland, and the United States, with sintering operations anchored in specialized metallurgical facilities serving aerospace and medical device adjacent markets. Sparger fabrication draws from nickel alloy bar stock, alumina ceramic powders, and precision machining capacity. Single-source vulnerability in FDA Master File documentation services extends European procurement cycles. Distribution runs through direct OEM relationships for pharmaceutical-grade systems and regional filtration distributors for industrial chemical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sparger procurement operates as a defensive-moat market where regulatory entrenchment creates substantial switching costs for validated bioprocessing facilities.
For Market Incumbents: Pre-empt emerging additive manufacturing competitors by securing exclusive supply agreements with laser-sintering equipment operators in Massachusetts and Switzerland. Backward integration into porous metal powder production insulates margin structures from nickel alloy traceability documentation delays imposed by REACH enforcement. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-aligned sterile fill-finish corridor by partnering with local validation specialists for steam-in-place qualification services. Carbon capture amine regeneration systems represent the most penetrable white-space application, with corrosion-resistant ceramic sparger demand outpacing established supplier capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among equipment-as-a-service providers bundling sparger supply with lifecycle maintenance contracts. Long-term viability rests on regulatory documentation automation capabilities rather than pore geometry patents. Monitor EMA Annex 1 enforcement intensity as the inflection signal for premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Automation | EMA Annex 1 compliance validation compresses supplier qualification timelines for European injectable drug producers. |
| Backward Integration into Porous Metal Feedstock | In-house sintering capacity insulates margin structures from nickel alloy traceability documentation burdens. |
| Equipment-as-a-Service Model Expansion | Asset-light leasing structures lower entry barriers for mid-scale fermentation operators in North America. |
| Additive Manufacturing Capability Acquisition | Laser-sintered titanium spargers with gradient porosity displace conventional fixed-pore configurations in perfusion bioreactors. |
| Carbon Capture Application Development | Amine-based post-combustion systems specify corrosion-resistant alumina spargers for oxidative degradation control. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA submission databases, and trade customs records covering porous metal and ceramic filtration equipment. Plant engineers at bioprocessing facilities, procurement leads at contract manufacturing organizations, and aftermarket service heads at filtration distributors provided operational perspective. Bottom-up unit economics triangulate against top-down sector spending patterns from pharmaceutical capital expenditure disclosures and municipal wastewater infrastructure budgets.
Forecast inputs span installation geometry, material durability tier, regulatory exposure level, and end-use industry concentration across the projection horizon. Modeled segmentation incorporates type, application, material, and end user dimensions with geographic production cluster overlays. CAGRs derive from regression analysis against biopharmaceutical fermentation capacity expansion timelines and EPA effluent compliance retrofit schedules.
Stress conditions across nickel alloy price volatility, CDSCO enforcement intensity, and carbon capture deployment acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sterilization standard harmonization and additive manufacturing cost curves. Cross-checking against EIA energy sector capital expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Air Heater Tubes Market
Industrial Motors
Global Medium and High Power Motors Market
Industrial Motors
Brushless DC Motor Market
Industrial Motors
Germany AC Motor Market
Industrial Motors
Asia Pacific and Middle East and Africa Submerged Arc Furnace Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
Power Stacker Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Europe Hazardous Location Motors Market
Industrial Motors
Gearless Elevator Traction Motor Market
Industrial Motors
Latin America Hazardous Location Motors Market
Industrial Motors
Explosion Proof Electric Motors and Actuators Sales Market
Industrial Motors
Global Parallel Shaft Geared Motors Market
Industrial Motors
Asia-Pacific Induction Motor Market