
 Cryogenic Air Separation Units (Asus) Market | 2026-2036
Cryogenic Air Separation Units (Asus) Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Air Separation Units (Asus) Market Insights
The cryogenic engineering talent pool is redrawing competitive boundaries across industrial gas equipment. Linde plc leverages its apprenticeship pipelines in Germany to sustain technology leadership in large-scale column distillation systems. Air Products and Chemicals anchors North American project execution through dedicated cryogenic welding and process control academies.
Cryogenic Air Separation Units employ fractional distillation at temperatures below minus 180 degrees Celsius to separate atmospheric air into oxygen, nitrogen, and argon through multi-column rectification systems. Large Units dominate capital deployment due to economies of scale in steel and chemical complexes, while Modular Units attract fastest-growing interest from remote healthcare and small-batch metallurgy operators seeking rapid commissioning. Column Distillation commands the core technology position, though Hybrid Systems gain traction where variable demand profiles require adsorption backup cycles.
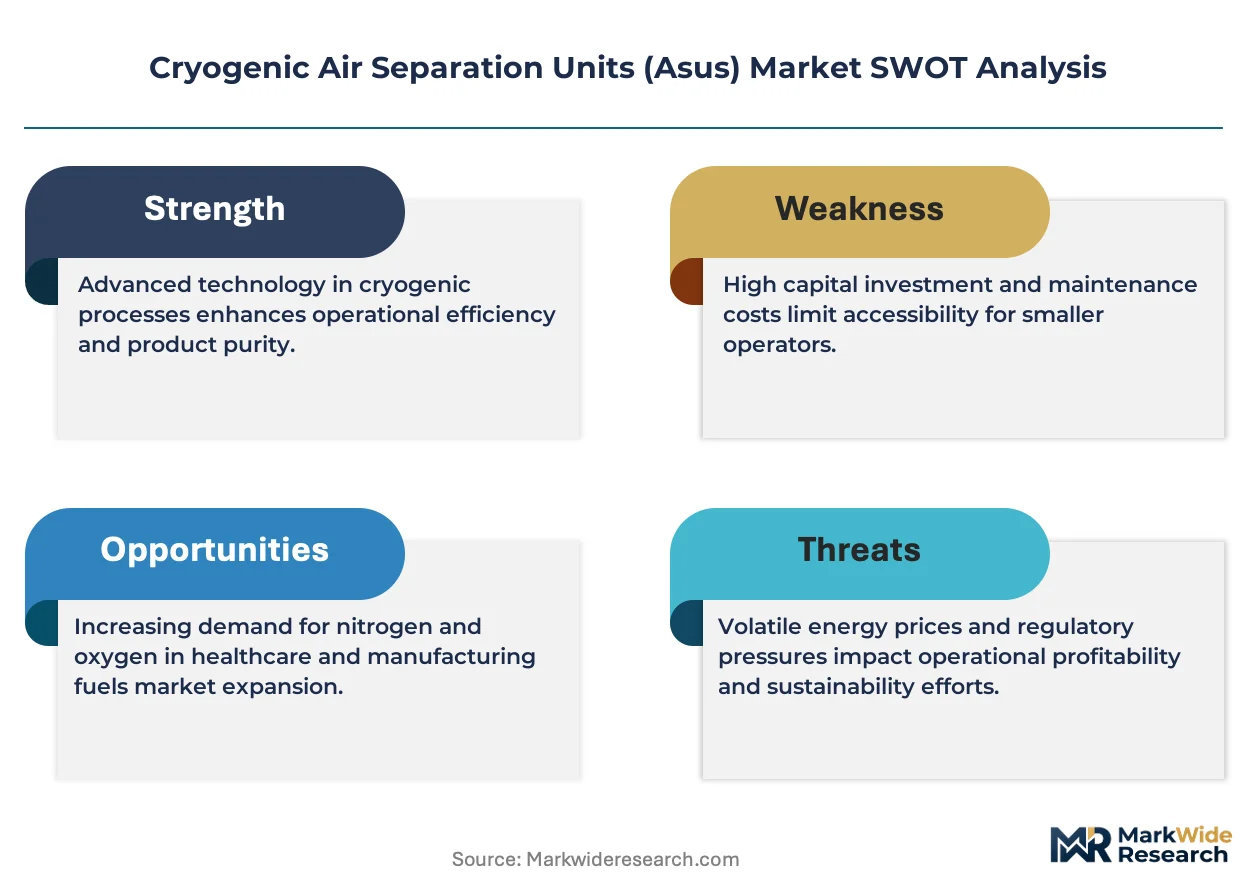
The EPA enforces emissions controls on cryogenic plant refrigerant leakage, while OSHA mandates process safety management for oxygen-enriched environments; both frameworks elevate engineering compliance costs but filter out low-capability entrants. China's MEE imposes dual carbon goals on energy-intensive gas separation facilities, accelerating demand for efficiency retrofits. Stakeholders must monitor regulatory divergence between jurisdictions to optimize plant certification strategies and avoid stranded asset risk from incompatible standards evolution.
Market Dynamics
The cryogenic air separation sector faces a structural squeeze between steelmakers' captive gas strategies and healthcare infrastructure mandates, forcing equipment suppliers to reconcile divergent scale economics and commissioning timelines within a single technology portfolio.
Growth Catalysts
- EPA refrigerant leakage controls:The United States Environmental Protection Agency's tightened emissions frameworks are filtering out low-capability equipment vendors and consolidating procurement toward certified system integrators with documented containment protocols.
- Steel sector argon intensity:Chinese steelmakers are scaling dedicated argon recovery circuits for electric arc furnace operations, pulling demand for high-purity column distillation trains with enhanced rectification stages.
- Remote healthcare oxygen:Modular cryogenic units are penetrating isolated medical facilities across Indonesia and the Philippines where pipeline infrastructure remains economically unviable.
Market Restraints
- Specialized alloy input volatility:Nickel-based cryogenic steels and aluminum heat exchanger materials face price instability tied to Indonesian ore export restrictions, compressing fabrication margins.
- German engineering concentration:Large-column distillation expertise clusters within Central European apprenticeship pipelines, creating talent bottlenecks for non-European project execution.
- Adsorption substitution:Pressure swing adsorption systems are capturing nitrogen demand below 500 tons per day, eroding the addressable market for small-scale cryogenic plants.
Strategic Opportunities
- India medical oxygen corridors:The country's PLI scheme for critical care infrastructure is subsidizing cryogenic liquid oxygen storage and vaporization networks in tier-two cities.
- Hybrid system convergence:Integrating membrane pre-separation with cryogenic finishing stages is opening efficiency gains for variable-load chemical complexes.
- CE marking acceleration:The European Union's streamlined pressure equipment directive certification is reducing time-to-market for modular ASU skids destined for African and Middle Eastern buyers.
Industry Challenges
- Cryogenic welding certification timelines:Qualified orbital welders for vacuum-jacketed piping require 18-24 month training cycles, delaying project commissioning.
- Legacy control system integration:Brownfield chemical complexes demand ASU retrofits compatible with 1990s-era distributed control architectures, complicating automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Air Separation Units (Asus) Market |
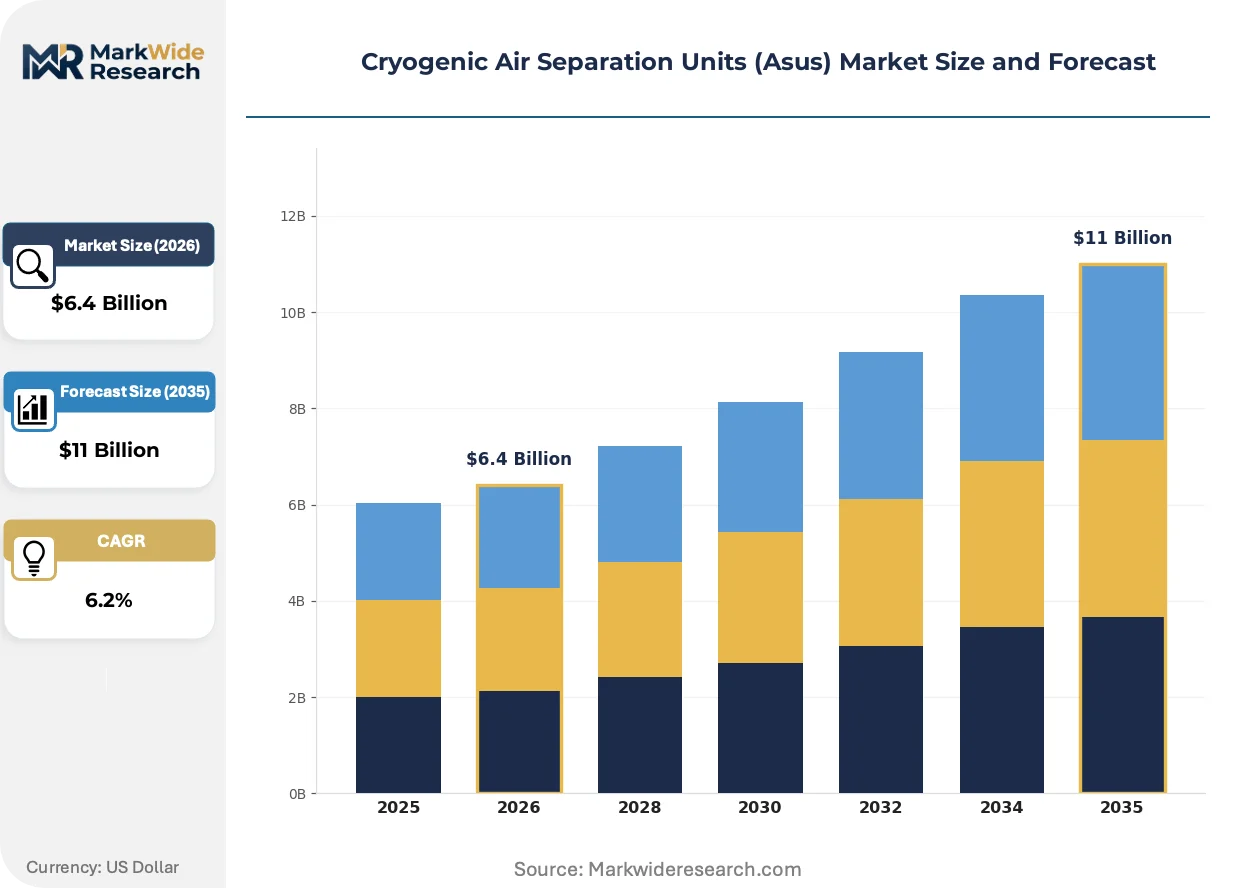
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $11 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Large Units, Medium Units, Small Units, Modular Units Technology: Column Distillation, Membrane Separation, Adsorption, Hybrid Systems End User: Chemical Industry, Metallurgy, Food & Beverage, Healthcare Application: Oxygen Production, Nitrogen Production, Argon Production, Rare Gases |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Messer Group, Taiyo Nippon Sanso Corporation, Praxair Technology, Sichuan Air Separation Plant Group, Cryogenic Industries, Universal Industrial Gases, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Air Separation Units (Asus) Market Trends and Innovations
Equipment architecture is fragmenting along scale lines, with divergent engineering priorities separating megaton steel-integrated plants from rapidly deployable healthcare modules.
Column distillation technology is bifurcating between single-train megaplants exceeding 3,000 tons per day oxygen capacity and containerized micro-units under 50 tons per day. Steelmakers in China and India are commissioning the former through engineering-procurement-construction contracts with decade-long service agreements, while African and Southeast Asian hospital networks are procuring the latter through equipment-leasing structures. This scale divergence is compressing mid-range plant orders and forcing suppliers to choose specialization lanes.
The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in cryogenic pre-cooling circuits, compelling equipment redesign around ammonia and hydrocarbon alternatives. Industrial gas producers operating across Germany, France, and Poland must retrofit existing cold boxes or absorb penalty costs. The regulation is accelerating R&D partnerships between ASU fabricators and compressor OEMs to validate alternative refrigeration cycles.
Hospital procurement groups are consolidating oxygen supply contracts under regional purchasing alliances, displacing single-facility equipment ownership. Brazil's public health system and Australia's state hospital networks are piloting liquid oxygen delivery contracts with built-in peak-demand insurance. This unbundling of capital expenditure from operational responsibility is reshaping vendor relationships toward performance-guaranteed service models.
Cryogenic Air Separation Units (Asus) Market Segmentation
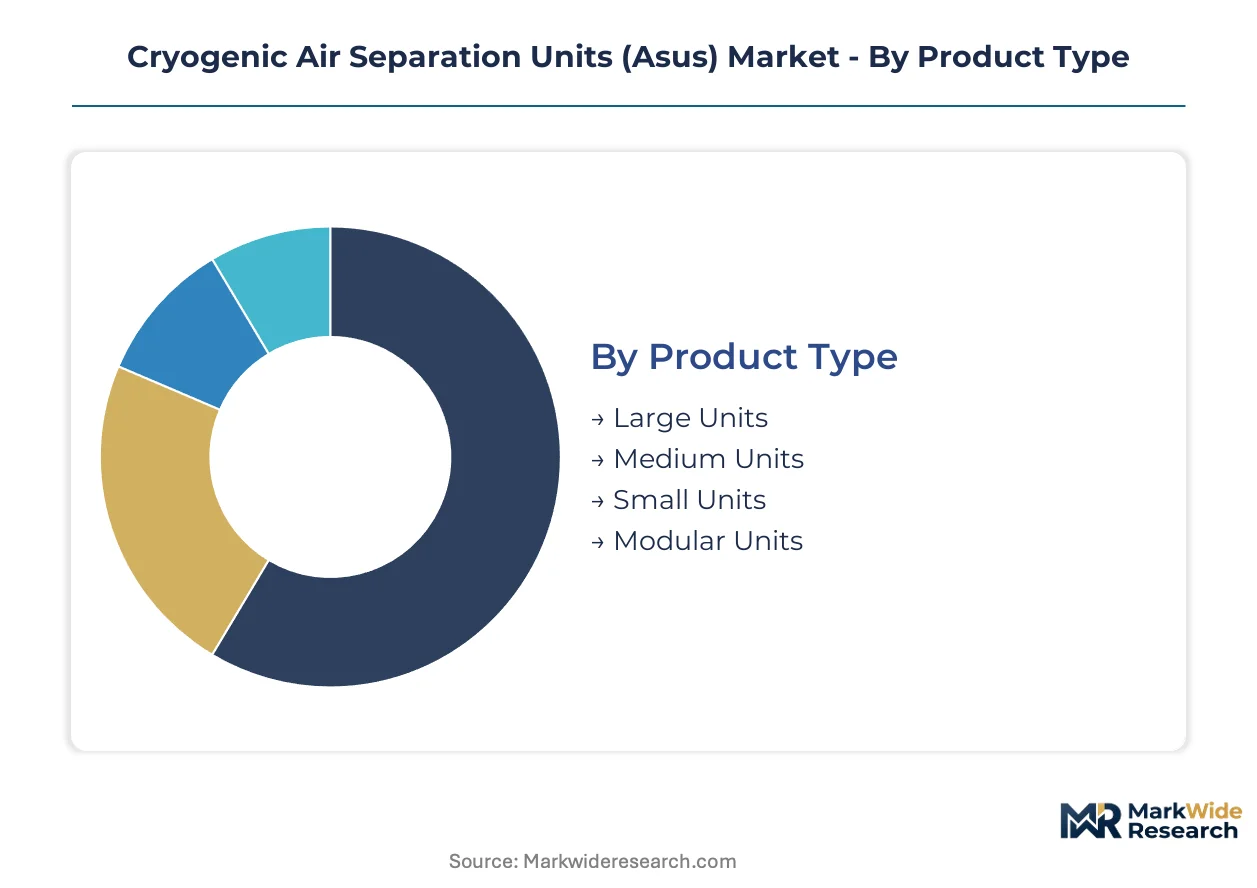
Cryogenic air separation equipment fragments across four distinct dimensions. Scale economics, technology maturity, end-use specifications, and gas purity requirements each create separate procurement logics that suppliers must navigate simultaneously.
Product Type:
Regulatory frameworks diverge sharply by scale. OSHA process safety management rules intensify for units exceeding threshold oxygen capacities, while EPA refrigerant leakage monitoring scales with system complexity. Modular designs face lighter certification burdens but must still satisfy FDA medical device adjacent standards when supplying healthcare infrastructure.
- Large Units:Single-train systems exceeding 3,000 tons per day oxygen capacity dominate integrated steel and chemical complexes. Chinese steelmakers commission these through decade-long engineering-procurement-construction contracts with embedded service agreements. The EPA's tightened emissions frameworks filter procurement toward certified system integrators with documented containment protocols.
- Modular Units:Containerized skids under 50 tons per day enable rapid commissioning for remote healthcare and small-batch metallurgy. Indonesian and Philippine hospital networks procure these through equipment-leasing structures where pipeline infrastructure remains economically unviable. Brazil's public health system pilots liquid oxygen delivery contracts with built-in peak-demand insurance.
- Medium Units:Mid-range plants serving regional chemical complexes face compressed order books as scale divergence accelerates.
- Small Units:Standalone installations for food processing and localized industrial gas supply occupy narrowing market territory between modular flexibility and medium-scale efficiency.
Large Units handle the majority of throughput; Modular Units are gaining share fastest as healthcare infrastructure decentralizes.
Technology:
Capital intensity and energy efficiency trade-offs separate the technology stack. Column distillation demands substantial upfront investment but delivers lowest unit costs at scale. Alternative approaches sacrifice purity or capacity for deployment speed and footprint reduction.
- Column Distillation:Multi-column rectification systems operating below minus 180 degrees Celsius remain the core technology for high-purity oxygen, nitrogen, and argon separation. The European Union's F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in pre-cooling circuits, compelling equipment redesign around ammonia and hydrocarbon alternatives.
- Hybrid Systems:Integrating membrane pre-separation with cryogenic finishing stages opens efficiency gains for variable-load chemical complexes. German and French industrial gas producers must retrofit existing cold boxes or absorb penalty costs under tightening refrigerant rules.
- Membrane Separation:Polymer-based systems capture selective gas permeation applications where purity requirements are moderate and energy costs are secondary.
- Adsorption:Pressure swing systems capture nitrogen demand below 500 tons per day, eroding the addressable market for small-scale cryogenic plants.
Column Distillation commands installed capacity; Hybrid Systems are climbing the fastest as variable demand profiles proliferate.
End User:
Customer procurement maturity varies dramatically. Steel and chemical buyers negotiate decade-long service contracts with performance guarantees. Healthcare and food sector purchasers increasingly favor operational expenditure models over capital ownership.
- Metallurgy:Steelmakers drive the largest equipment deployments. Chinese electric arc furnace operations scale dedicated argon recovery circuits, pulling demand for high-purity column distillation trains with enhanced rectification stages.
- Healthcare:Hospital procurement groups consolidate oxygen supply contracts under regional purchasing alliances. Australia's state hospital networks displace single-facility equipment ownership in favor of liquid oxygen delivery with peak-demand insurance.
- Chemical Industry:Brownfield complexes demand ASU retrofits compatible with 1990s-era distributed control architectures, complicating automation upgrades.
- Food & Beverage:Nitrogen blanketing and freezing applications favor smaller-scale systems with rapid commissioning timelines.
Metallurgy absorbs the dominant share of capital deployment; Healthcare is expanding most quickly as medical oxygen infrastructure proliferates.
Application:
Gas-specific purity requirements and delivery modalities shape equipment configuration. Oxygen and nitrogen demand scale with industrial activity; argon and rare gases tie to specialized metallurgical and electronics applications.
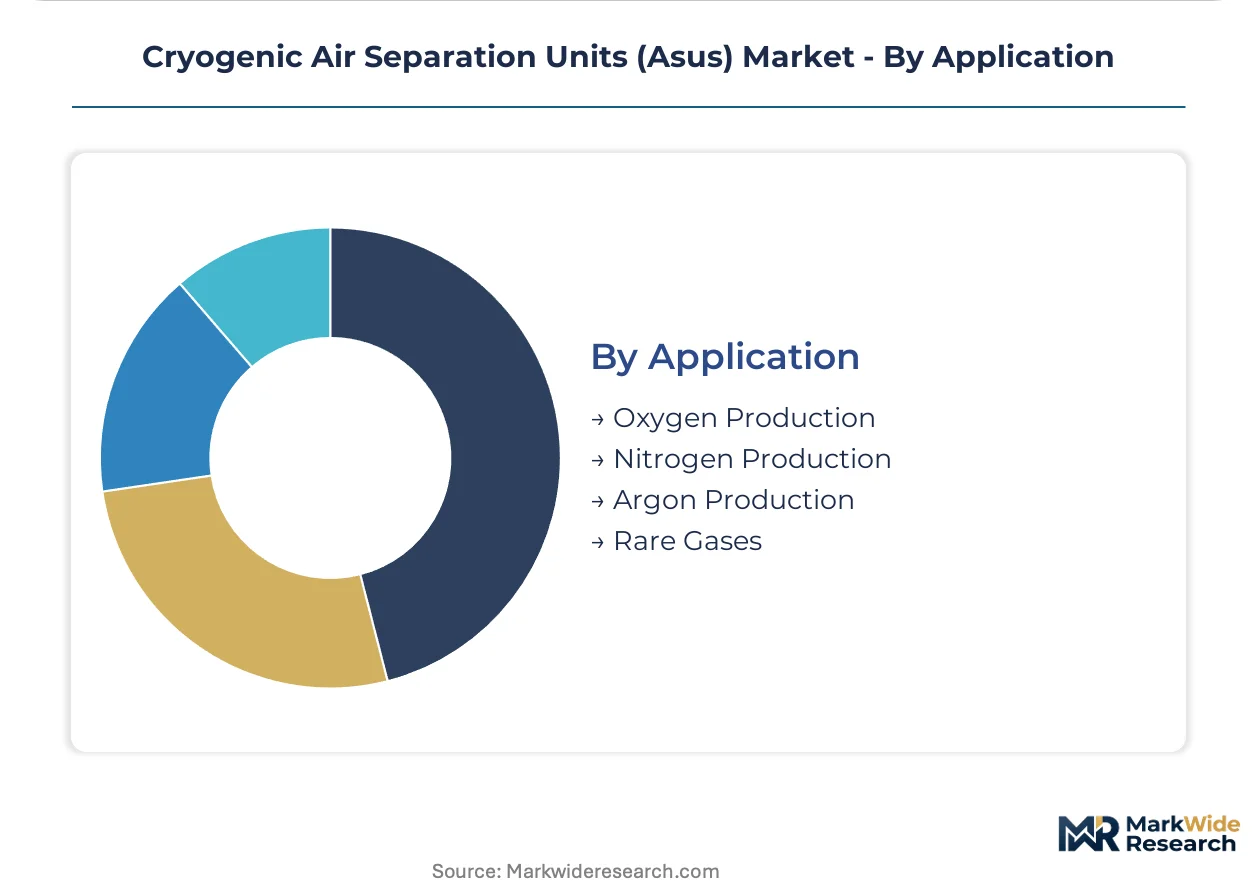
- Oxygen Production:Medical-grade liquid oxygen storage and vaporization networks attract India's PLI scheme subsidies for critical care infrastructure in tier-two cities. The FDA and OSHA jointly regulate oxygen-enriched environments, elevating engineering compliance costs.
- Argon Production:High-purity recovery circuits command premium engineering for semiconductor and specialty steel applications. China's MEE imposes dual carbon goals on energy-intensive gas separation facilities, accelerating efficiency retrofit demand.
- Nitrogen Production:Inerting and blanketing applications span food, chemical, and electronics sectors with varying purity thresholds.
- Rare Gases:Neon, krypton, and xenon recovery from air separation residuals serves lighting, insulation, and propulsion niches with concentrated supply chains.
Oxygen Production handles the majority of throughput; Argon Production shows the steepest expansion trajectory as steel quality specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE anchors the dominant geography through dual carbon mandates on energy-intensive gas separation facilities, filtering procurement toward certified system integrators with documented efficiency protocols.
China
Steelmakers in Hebei and Jiangsu provinces scale dedicated argon recovery circuits for electric arc furnace operations. The MEE imposes dual carbon goals on industrial gas facilities, accelerating demand for column distillation retrofits. Tangshan and Zhangjiagang host concentrated clusters where engineering-procurement-construction contracts bundle decade-long service agreements.
United States
Healthcare providers expand oxygen infrastructure requirements across underserved rural corridors. The EPA enforces refrigerant leakage controls on cryogenic plant pre-cooling circuits, elevating compliance costs. The Gulf Coast petrochemical belt drives demand for large-scale nitrogen inerting systems integrated with refinery complexes.
Germany
Industrial gas producers face F-Gas Regulation mandates phasing down hydrofluorocarbon refrigerants in cold box pre-cooling circuits. The regulation compels equipment redesign around ammonia alternatives. Ruhr Valley chemical complexes anchor retrofit demand as operators absorb penalty costs or validate alternative refrigeration cycles.
India
The PLI scheme for critical care infrastructure subsidizes cryogenic liquid oxygen storage and vaporization networks in tier-two cities. CDSCO and state-level regulators jointly oversee medical device adjacent standards for hospital-grade systems. Maharashtra and Gujarat host emerging fabrication clusters serving decentralized healthcare procurement.
Indonesia
Remote healthcare facilities across the archipelago procure modular cryogenic units through equipment-leasing structures where pipeline infrastructure remains economically unviable. The national pharmaceutical regulator oversees oxygen purity standards for medical applications. Java and Sulawesi concentrate deployment pilots linking island hospital networks to liquid oxygen delivery contracts.
Cryogenic Air Separation Units (Asus) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where German engineering houses dominate large-column distillation while Asian fabricators capture modular unit volume. The vendor base clusters around three strategic archetypes: integrated industrial gas majors with captive equipment divisions, specialized cryogenic engineering houses with apprenticeship pipelines, and regional fabricators serving price-sensitive procurement. Consolidation pressures intensify as EPA and MEE regulations filter out low-capability entrants, while strategic partnerships between ASU fabricators and compressor OEMs accelerate alternative refrigeration cycle validation.
Among Europe-based industrial gas majors, Linde plc and Air Liquide occupy positions exemplifying integrated technology leadership through large-scale column distillation systems. Air Products and Chemicals anchors North American project execution capabilities. Sichuan Air Separation Plant Group represents the regional specialist archetype serving domestic Chinese steelmaker demand.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals |
| Messer Group |
| Taiyo Nippon Sanso Corporation |
| Praxair Technology |
| Sichuan Air Separation Plant Group |
| Cryogenic Industries |
| Universal Industrial Gases |
| Others |
Pricing and Supply Chain Analysis
Ammonia and hydrocarbon refrigerant substitution in cold box pre-cooling circuits is redrawing procurement geography while compressing margins for European fabricators facing F-Gas retrofit deadlines. This input shift simultaneously elevates equipment costs for certified ammonia-compatible systems and opens pricing arbitrage between German engineering houses and Asian competitors with established hydrocarbon supply chains.
Pricing Analysis
Price spreads between German large-column systems and Chinese modular units exceed 40 percent on equivalent oxygen capacity, reflecting apprenticeship pipeline premiums against volume fabrication economics. Pricing stratifies across certified system integrators, regional EPC contractors, and equipment-leasing operators serving healthcare procurement. Cost compression in mid-range plants is intensifying because pressure swing adsorption captures nitrogen demand below 500 tons per day. Hospital procurement groups demonstrate highest price sensitivity through consolidated regional purchasing alliances, while integrated steelmakers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Germany and China anchor cryogenic column fabrication, with Ruhr Valley engineering houses supplying large-train distillation systems and Sichuan fabricators capturing modular unit volume. Nickel-based cryogenic steels and aluminum heat exchanger materials draw from Indonesian ore processing and Australian bauxite refining. Single-source vulnerability concentrates in qualified orbital welders requiring 18-24 month certification cycles. Distribution runs through engineering-procurement-construction contractors for steel-integrated megaplants and equipment-leasing structures for remote healthcare deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cryogenic air separation sector sits in early-cycle expansion as healthcare infrastructure decentralization accelerates modular unit adoption beyond traditional industrial gas demand centers.
For Market Incumbents: Consolidate apprenticeship pipeline control through dedicated cryogenic welding academies in North America and Southeast Asia to offset German engineering concentration. Deepen backward integration into nickel-based alloy supply through long-term offtake agreements with Indonesian ore processors, insulating fabrication margins from export restriction volatility. Pressure swing adsorption substitution in sub-500 ton nitrogen applications demands selective capacity retirement and technology portfolio rebalancing toward hybrid membrane-cryogenic systems. For New Entrants and Emerging Players: Differentiate on rapid commissioning capabilities for tier-two Indian hospital networks subsidized under PLI scheme oxygen corridor development. Target Indonesia and Philippine archipelago healthcare facilities where pipeline infrastructure remains economically unviable and equipment-leasing structures displace capital ownership. Pursue joint validation partnerships with compressor OEMs to accelerate alternative refrigeration cycle certification under tightening F-Gas and EPA frameworks. For Investors and Strategic Acquirers: EPA and MEE emissions framework convergence reshapes the acquisition landscape by filtering out low-capability entrants and consolidating procurement toward certified system integrators. Long-term viability centers on technology leadership in large-column distillation or scale advantages in modular unit fabrication, with limited middle ground. Monitor CE marking acceleration under streamlined pressure equipment directive as signal for European modular ASU skid competitiveness in African and Middle Eastern markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Long-term offtake agreements with Indonesian ore processors stabilize fabrication margins against export volatility. |
| Cryogenic Welding Academy Expansion | Dedicated training pipelines in North America and Southeast Asia relieve 18-24 month certification bottlenecks. |
| Hybrid System R&D Partnership | Collaboration with compressor OEMs validates ammonia and hydrocarbon refrigeration cycles under F-Gas phase-down. |
| Healthcare Leasing Structure Development | Equipment-leasing models align with Brazil and Australia hospital procurement consolidation under regional purchasing alliances. |
| CE Marking Acceleration Program | Streamlined pressure equipment directive certification reduces time-to-market for modular ASU skids in African markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cryogenic plant engineers, industrial gas procurement directors, hospital purchasing committee members, EPC contract managers, and aftermarket service heads. Secondary validation drew from EPA enforcement actions, MEE dual carbon facility audits, EU F-Gas Regulation implementation guidance, SEC filings of integrated industrial gas majors, and customs data on cryogenic steel alloy trade flows. Bottom-up unit economics triangulated against top-down industrial gas demand projections across the analysis window.
Across the projection horizon, the analytical framework modeled equipment scale tiers, technology maturity stages, end-use procurement patterns, and gas purity specification bands. CAGRs were derived from segmented adoption curves weighted by regulatory compliance intensity and steel sector argon recovery circuit deployment. Forecast inputs included electric arc furnace capacity additions in Hebei and Jiangsu provinces, PLI scheme oxygen corridor subsidy allocation trajectories, and F-Gas refrigerant phase-down penalty cost absorption rates.
Decision-makers should treat outputs as directional under sustained EPA and MEE emissions enforcement, stable nickel alloy ore export policy, and continued healthcare infrastructure decentralization; material deviation in any driver would warrant model refresh. Recalibration cycles align with material shifts in refrigerant regulatory harmonization, steel sector technology transitions, and medical oxygen procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Global Explosion-Proof Motor Casting Market
Industrial Motors
North America Refrigeration Oil Market
Industrial Motors
Gear Motor Market
Industrial Motors
Hoist and Elevator Motors Market
Industrial Motors
Europe Induction Motor Market
Industrial Motors
Global Brushed DC Motor Market
Industrial Motors
Gear Reduction Motors Market
Industrial Motors
North America Hazardous Location Motors Market
Industrial Motors
Crude Heater Market
Industrial Motors
Elevator Motors Market
Industrial Motors
Global Low Voltage Motors Market
Industrial Motors
Global Energy Efficient Motor Market
Industrial Motors
Charging Nitrogen Gas Systems Market
Industrial Motors
Latin America Electric Drives Market
Industrial Motors
China AC Motor Market
Industrial Motors
Spargers Market