
 Global Package Testing Market | 2026-2036
Global Package Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Package Testing Market Foresight
Aftermarket service revenue from package validation and retesting is reconfiguring margin pools away from one-time certification toward recurring compliance monitoring. SGS SA leverages its global laboratory footprint to anchor multi-year pharmaceutical testing contracts across North America and Europe. Bureau Veritas competes through specialized cold-chain packaging validation for biologics, while Eurofins Scientific SE differentiates with accelerated shelf-life testing protocols that reduce client time-to-market cycles.
Package testing encompasses the mechanical, environmental, and chemical evaluation of container systems to verify protective performance against specified distribution hazards, including ASTM D4169 drop sequences and ISTA 3A vibration profiles. The primary commercial purpose centers on demonstrating that packaged goods withstand transport stresses while meeting regulatory shelf-life claims. Drop test and vibration test categories dominate current revenue as e-commerce damage claims drive carrier liability requirements. Pharmaceutical end users represent the fastest-growing demand segment due to EU MDR and FDA serialization mandates for unit-level traceability. Plastic material testing occupies the largest share of current volume, though paperboard validation is gaining structural importance as brand owners eliminate single-use plastics from direct-to-consumer shipments.
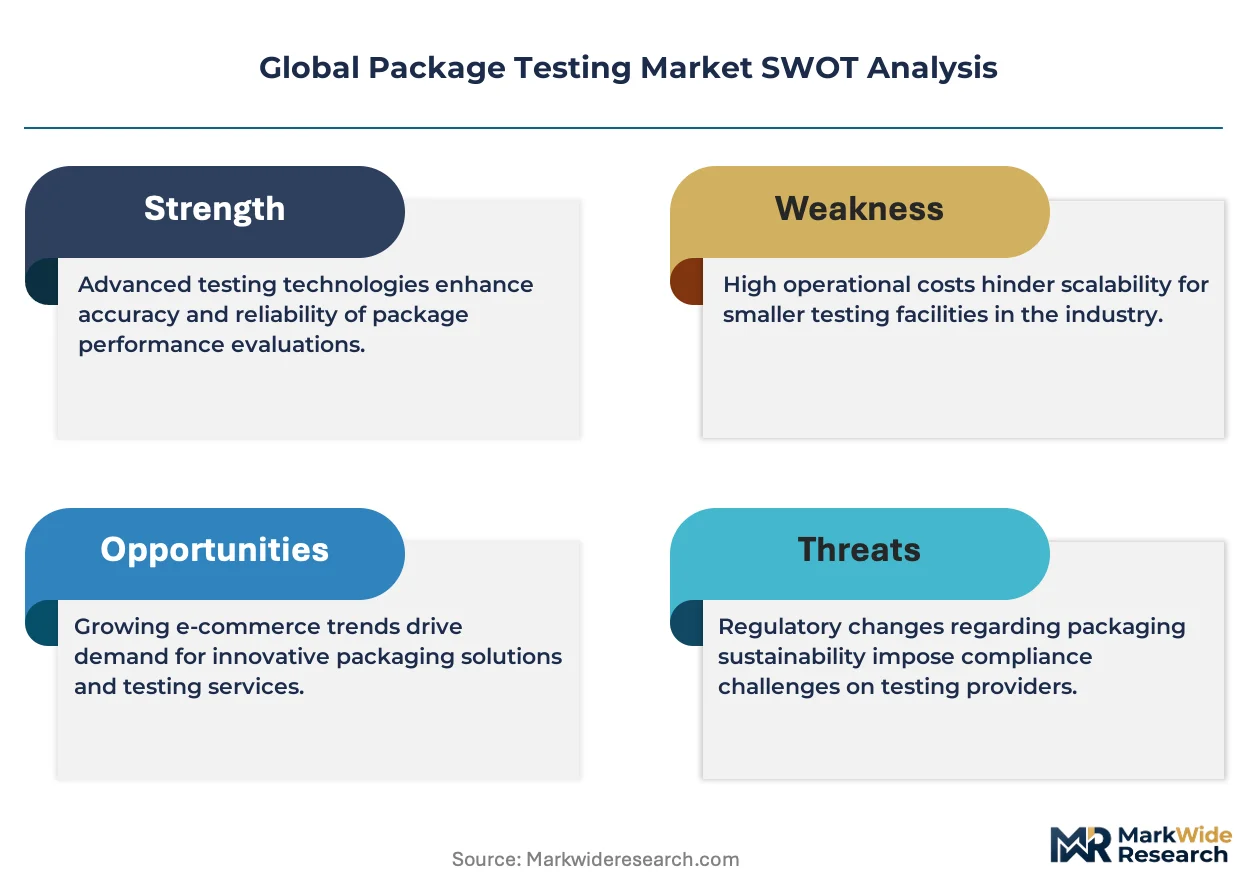
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR traceability mandates compel pharmaceutical manufacturers to validate package integrity at unit and case levels. REACH and RoHS frameworks in Europe restrict certain packaging substrates, redirecting material testing demand toward compliant alternatives. Stakeholders must monitor evolving Extended Producer Responsibility legislation across multiple jurisdictions, as these programs increasingly mandate design-for-recyclability validation that extends testing scope beyond distribution performance to end-of-life material recovery rates.
Market Dynamics
Pharmaceutical serialization mandates across Europe and North America are forcing testing providers to retool for unit-level traceability validation, compressing certification timelines while expanding the scope of required protocols from distribution integrity to cold-chain verification.
Growth Catalysts
- EU MDR traceability mandates:Medical device manufacturers must validate package integrity at unit level, creating sustained demand for tamper-evident testing services across German and French pharmaceutical clusters.
- Biologics cold-chain expansion:Temperature-sensitive biologic therapies require validated thermal packaging, driving specialized testing protocols for insulated shippers and phase-change materials.
- E-commerce damage liability:Carrier networks in China, Germany, and the United States now mandate ISTA 3A certification for high-volume sellers, institutionalizing drop and vibration testing into fulfillment workflows.
Market Restraints
- Capital intensity of thermal chambers:Cold-chain validation requires environmental simulation equipment costing substantially more than mechanical testing rigs, concentrating capability among well-capitalized laboratories.
- Regulatory fragmentation:Divergent serialization requirements between FDA DSCSA and EU MDR force manufacturers to maintain parallel testing protocols, increasing compliance overhead without additive safety benefits.
- Substitution by in-house labs:Large pharmaceutical and consumer goods manufacturers are building captive testing facilities for routine protocols, eroding third-party volume in standardized drop and compression categories.
Strategic Opportunities
- Extended Producer Responsibility mandates:EU Green Deal packaging regulations are mandating design-for-recyclability validation, extending testing scope to material recovery rates and end-of-life performance.
- India pharmaceutical export growth:CDSCO alignment with ICH guidelines is driving Indian generic manufacturers to seek ISO 17025-certified testing for US and EU market access.
- Digital twin convergence:Finite element modeling is hybridizing with physical testing to reduce prototype iterations, enabling laboratories to sell simulation-calibration services alongside empirical validation.
Industry Challenges
- ISO 17025 auditor scarcity:Accreditation bodies face backlogs for laboratory certification, delaying market entry for new testing facilities and constraining capacity expansion timelines.
- Legacy equipment integration:Automated data capture systems must interface with decades-old mechanical testers, creating interoperability friction that slows digital transformation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Package Testing Market |
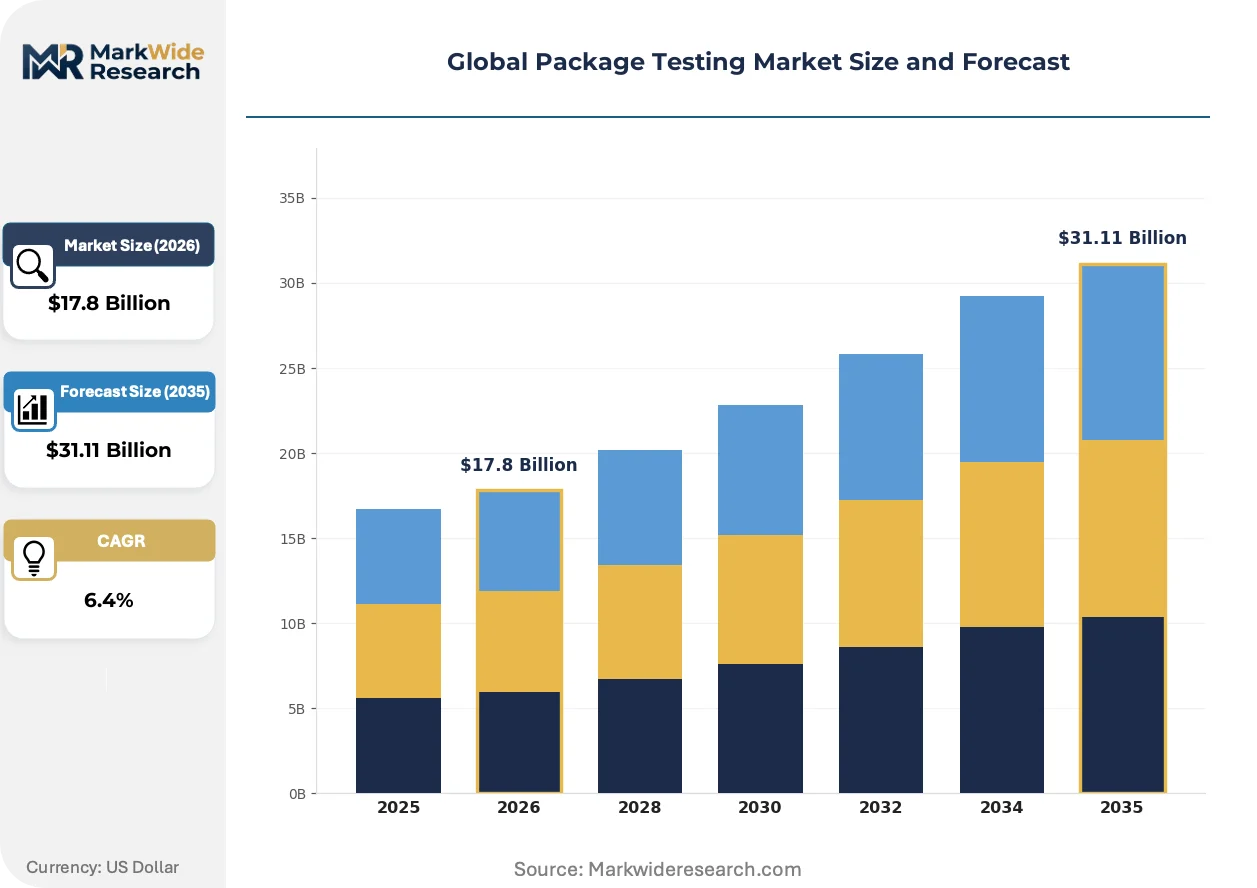
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Drop Test, Vibration Test, Compression Test, Moisture Barrier Test Material: Plastic, Glass, Metal, Paperboard End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Intertek Group PLC, Eurofins Scientific SE, SGS SA, Bureau Veritas SA, TÜV SÜD AG, ALS Limited, Element Materials Technology, Smithers, Merieux NutriSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Package Testing Market Shifts & Advancements
Testing methodologies are converging with simulation and sensor technologies, compressing development cycles while expanding the evidentiary requirements for regulatory submissions across pharmaceutical and e-commerce verticals.
Smart packaging with embedded NFC and temperature-logging sensors is hybridizing physical container validation with digital authentication protocols. Pharmaceutical manufacturers in Switzerland and Germany are adopting these hybrid systems to satisfy both FDA DSCSA and EU MDR traceability requirements. This convergence is forcing testing laboratories to develop new protocols that verify sensor accuracy alongside mechanical integrity, effectively merging electronics validation with traditional package testing disciplines.
REACH substance restrictions are eliminating certain plasticizers and coatings from primary packaging, redirecting material testing demand toward compliant alternatives. The European Chemicals Agency's expanding candidate list forces reformulation cycles that require accelerated aging and migration testing. Medical device and cosmetic brands are responding by front-loading material qualification budgets to avoid supply disruption from sudden regulatory additions.
Direct-to-consumer brand owners are unbundling certification from manufacturing relationships, selecting testing providers based on turnaround speed rather than geographic proximity to production. This pattern concentrates contract volume with laboratories offering 72-hour ISTA certification turnaround, particularly for electronics and personal care shipments originating in Chinese and Vietnamese manufacturing zones. Third-party logistics providers are responding by integrating testing partnerships into their value-added service portfolios.
Global Package Testing Market Segmentation
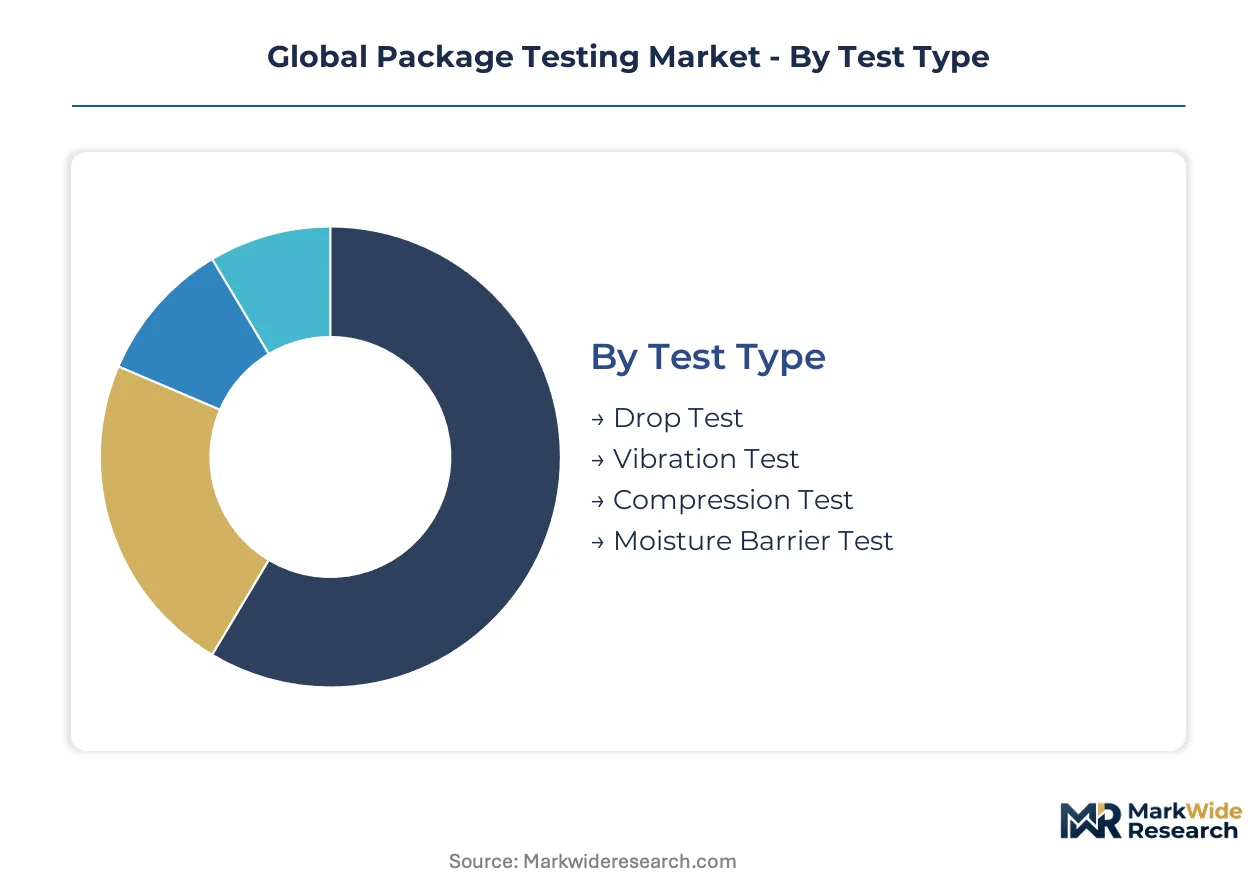
Package testing demand fragments across four intersecting dimensions. Test protocols, substrate materials, end-use industries, and distribution channels each configure distinct capability requirements and pricing structures for laboratories.
Test Type:
Mature protocols dominate current revenue while emerging methodologies capture regulatory-driven expansion.
- Drop Test:Simulates free-fall impacts using ASTM D4169 or ISTA 3A sequences to assess structural failure thresholds. E-commerce fulfillment networks in the United States and Germany mandate this certification for seller liability coverage, compressing turnaround expectations to 72 hours for high-volume accounts.
- Vibration Test:Replicates truck and air freight resonance frequencies through random and sinusoidal profiles. Demand concentrates in electronics and pharmaceutical corridors across China and Switzerland where carrier damage claims drive protocol standardization.
- Compression Test:Evaluates stack load resistance for palletized distribution. Warehouse automation in German logistics hubs sustains steady protocol volume.
- Moisture Barrier Test:Measures water vapor transmission rates for shelf-life validation. Pharmaceutical applications in humid climates are expanding method adoption.
Drop test handles the majority of throughput; moisture barrier test is gaining share fastest on biologics packaging requirements.
Material:
Cost tier structures segment demand between commodity substrates and specialized barrier systems.
- Plastic:Polyethylene, polypropylene, and multilayer films undergo tensile, impact, and migration testing per REACH substance restrictions. Brand owners in France and Italy are accelerating substitution testing as ECHA expands its candidate list of restricted plasticizers.
- Glass:Pharmaceutical vials and cosmetic containers require fracture resistance and chemical durability validation. Swiss and German biologics manufacturers sustain premium testing margins on this substrate.
- Metal:Aluminum and steel packaging for food and industrial applications demands corrosion and seam integrity protocols. Italian and Spanish canning operations anchor regional demand.
- Paperboard:Recyclable fiber-based systems are displacing plastics in direct-to-consumer channels. Swedish and Finnish pulp innovations are redirecting material qualification budgets toward this category.
Plastic commands the largest current volume; paperboard is climbing the fastest on EU Green Deal packaging regulations.
End User:
Application criticality separates routine certification from specialized compliance mandates.
- Food & Beverage:Shelf-life validation and migration testing for FSSAI, FDA, and EFSA compliance. Indian export manufacturers are expanding ISO 17025 certification requirements for US and EU market access.
- Pharmaceuticals:Unit-level traceability under FDA DSCSA and EU MDR drives tamper-evident and cold-chain protocol expansion. German and Swiss clusters concentrate specialized laboratory investment.
- Cosmetics:REACH substance restrictions and primary packaging integrity for premium positioning. French and Italian brand owners front-load material qualification to avoid reformulation disruption.
- Electronics:ISTA 3A certification for damage liability coverage in Chinese and Vietnamese manufacturing zones. Third-party logistics providers are integrating testing partnerships into service portfolios.
Food and beverage sustains the broadest base; pharmaceuticals is expanding most quickly on serialization mandates.
Distribution Channel:
Customer type configures speed-versus-precision tradeoffs in service delivery.
- Retail:Traditional brick-and-mortar supply chains require pallet-level compression and transit testing. German and French retail consolidation sustains steady protocol demand.
- E-commerce:Direct-to-consumer fulfillment demands individual parcel drop and vibration certification. Chinese and US seller ecosystems are institutionalizing ISTA protocols into platform compliance requirements.
- Wholesale:Bulk distribution networks prioritize stack-load validation and unitization integrity. Indian pharmaceutical exporters are aligning CDSCO requirements with wholesale channel specifications.
- Direct Sales:Manufacturer-controlled distribution enables captive testing integration. Large consumer goods manufacturers in the United States are building in-house facilities for routine protocols.
Retail retains the deepest historical base; e-commerce is gaining share fastest on platform-mandated certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by geography. Indian and Chinese buyers prioritize rapid turnaround over premium certification tiers, while Swiss and German pharmaceutical manufacturers absorb higher costs for specialized cold-chain validation.
United States
E-commerce fulfillment networks in California and Texas institutionalize ISTA 3A certification for seller liability coverage. FDA DSCSA serialization mandates compel unit-level traceability validation across pharmaceutical corridors. Boston and Research Triangle Park clusters concentrate biologics cold-chain testing demand.
Germany
Industrial logistics automation in Bavaria and North Rhine-Westphalia sustains compression and pallet testing volume. EU MDR traceability requirements force medical device manufacturers to retest packaging at unit level. Frankfurt and Munich pharmaceutical hubs anchor specialized laboratory investment for tamper-evident protocols.
China
Electronics manufacturing zones in Shenzhen and Dongguan drive drop and vibration certification for cross-border e-commerce. SAMR alignment with international standards pressures exporters toward ISO 17025 accreditation. Yangtze River Delta logistics providers integrate testing partnerships into platform compliance workflows.
Switzerland
Premium biologics manufacturing in Basel demands validated thermal packaging for temperature-sensitive therapies. Swissmedic serialization requirements exceed baseline EU MDR stringency. Zurich and Geneva clusters support specialized cold-chain protocol development at premium pricing tiers.
India
Generic pharmaceutical exporters in Hyderabad and Ahmedabad seek CDSCO-aligned testing for US and EU market access. FSSAI migration testing expands for processed food shipments to Gulf and Southeast Asian markets. Maharashtra packaging hubs accelerate ISO 17025 certification to capture contract manufacturing testing volume.
Global Package Testing Market Competitive Landscape
Capability concentration sits with specialized cold-chain and biologics validators; scale advantage sits with diversified multi-protocol laboratories. The market structures around three tiers: global certifiers with pharmaceutical serialization expertise, regional specialists in e-commerce and consumer goods protocols, and captive in-house facilities at large manufacturers. Strategic moves center on accreditation expansion into emerging pharmaceutical export zones and digital twin calibration services that hybridize simulation with empirical validation.
Within the global certifier tier, SGS SA, Bureau Veritas SA, and Eurofins Scientific SE exemplify divergent specialization vectors. SGS SA anchors multi-year pharmaceutical contracts through laboratory footprint density. Bureau Veritas SA occupies a position emphasizing cold-chain biologics validation. Eurofins Scientific SE represents accelerated shelf-life protocol differentiation that compresses client time-to-market cycles.
| Leading Market Players |
|---|
| Intertek Group PLC |
| Eurofins Scientific SE |
| SGS SA |
| Bureau Veritas SA |
| TÜV SÜD AG |
| ALS Limited |
| Element Materials Technology |
| Smithers |
| Merieux NutriSciences |
| Others |
Supply & Pricing Matrix
Yangtze River Delta freight corridors compress logistics costs for Chinese testing equipment suppliers, concentrating manufacturing scale in Jiangsu and Zhejiang provinces while forcing European and North American laboratories to differentiate through premium certification tiers and bundled compliance services.
Pricing Analysis
Aftermarket service contracts from multi-year pharmaceutical validation agreements now generate the majority of lifetime customer value, displacing one-time certification fees. Three-tier pricing structure across premium, standard, and economy levels segments buyers by protocol complexity and turnaround speed. Cost compression in standard ISTA 3A certification is intensifying because Shenzhen-based laboratories compete on 72-hour turnaround guarantees. E-commerce sellers in Chinese manufacturing zones exhibit the highest price sensitivity; Swiss biologics manufacturers absorb premium cold-chain validation costs without volume negotiation.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for environmental simulation equipment manufacturers. Testing instrument production concentrates in Germany, Japan, and China. Thermal chamber assemblies draw from precision sensor suppliers in Switzerland, compressor systems from Japanese industrial manufacturers, and control software from German automation specialists. Single-source vulnerability sits with Swiss temperature sensor manufacturers serving cold-chain validation protocols. Distribution runs through authorized distributor networks in pharmaceutical corridors and direct OEM relationships with large laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
In-house laboratory buildouts at large pharmaceutical and consumer goods manufacturers threaten to displace third-party testing volume in standardized protocol categories, forcing incumbent service providers to defend their positioning through specialization and captive relationship structures.
For Market Incumbents: Harden defensibility by anchoring multi-year pharmaceutical serialization contracts through ISO 17025 accreditation expansion into Indian and Southeast Asian export zones. Deepen backward integration into proprietary cold-chain phase-change material supply to capture margin pools from biologics packaging validation. In-house laboratory substitution at Procter & Gamble and Unilever-scale manufacturers demands faster turnaround guarantees and digital twin calibration services as retention levers. For New Entrants and Emerging Players: Build out ISO 17025-certified capacity in Hyderabad and Ahmedabad to capture CDSCO-aligned testing demand from Indian generic pharmaceutical exporters seeking US and EU market access. White-space concentration sits with accelerated shelf-life protocol development for cosmetics brands responding to ECHA plasticizer restrictions. Go-to-market positioning should emphasize 72-hour certification turnaround for Vietnamese electronics manufacturers supplying Amazon and Alibaba platform sellers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors laboratories with hybrid physical-digital capabilities that can sell simulation-calibration services alongside empirical validation. Long-term viability across the next decade rests on digital twin convergence and sensor-embedded smart packaging protocol development. Acquisition target archetype: regional specialists in e-commerce ISTA certification with established Chinese seller relationships. The signal to watch is FDA DSCSA enforcement intensity against unit-level traceability violations as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Accreditation Expansion | Captures pharmaceutical export testing demand from Indian CDSCO-aligned manufacturers seeking US market access. |
| Digital Twin Calibration Services | Hybridizes finite element modeling with physical testing to reduce client prototype iteration cycles. |
| Cold-Chain Biologics Specialization | Addresses Swissmedic and EU MDR temperature-sensitive therapy packaging validation requirements. |
| Accelerated Shelf-Life Protocol Development | Compresses time-to-market for cosmetics brands reformulating under REACH substance restrictions. |
| E-Commerce Platform Partnership Integration | Institutionalizes ISTA 3A certification into Alibaba and Amazon seller compliance workflows. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA DSCSA guidance documents, EMA MDR implementation reports, ISTA protocol revision records, and SAMR standard alignment notices. Primary interviews engaged laboratory operations directors, pharmaceutical packaging engineers, third-party logistics procurement managers, and regulatory affairs specialists at EU MDR-notified bodies. Bottom-up demand modeling from test protocol volumes triangulates against top-down market sizing from laboratory accreditation databases and customs equipment import records.
Forecast inputs span test type segmentation, material substrate substitution patterns, end-use industry regulatory compliance deadlines, and distribution channel certification mandate evolution across the projection horizon. Modeled dimensions include pharmaceutical serialization tier, e-commerce platform compliance grade, cold-chain temperature range, and regional regulatory cluster stringency. CAGRs derive from protocol volume growth rates applied to pricing tier trajectories, with biologics cold-chain expansion and EU Green Deal recyclability mandates as key demand drivers.
Stress conditions across FDA DSCSA enforcement intensity, ECHA substance restriction expansion velocity, and Chinese SAMR accreditation alignment timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation schedules and substitution elasticity in material testing. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Pack Testing Machines Market