
 Packaging Testing Market | 2026-2036
Packaging Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Testing Market Intelligence
Compliance with ISO 11607 for sterile medical device packaging is bifurcating the market between certified global laboratories and smaller, regional players. SGS S.A. leverages its extensive network to offer end-to-end validation services for multinational clients. Intertek Group Plc differentiates through its deep expertise in polymer and material science analytics. Bureau Veritas SA competes with a broad portfolio of testing, inspection, and certification services across multiple industries.
Packaging testing encompasses a suite of procedures to assess a container's ability to protect its contents against physical and environmental hazards. This includes methods like drop tests to simulate handling impacts and climate simulation to evaluate performance under temperature and humidity stress. The pharmaceutical and food & beverage sectors represent the largest end-user industries, driving demand. Physical evaluations such as compression and vibration tests remain high-volume services, particularly for corrugated fiberboard and plastic film materials.
Regulatory frameworks set the minimum performance criteria for packaging across key sectors. The US FDA mandates specific testing for food contact materials, while the EU’s REACH regulation governs chemical safety in packaging components. In China, national GB standards dictate requirements for products entering the domestic market. The validation of recycled and biodegradable materials against existing performance benchmarks will define future testing protocol development.
Market Dynamics
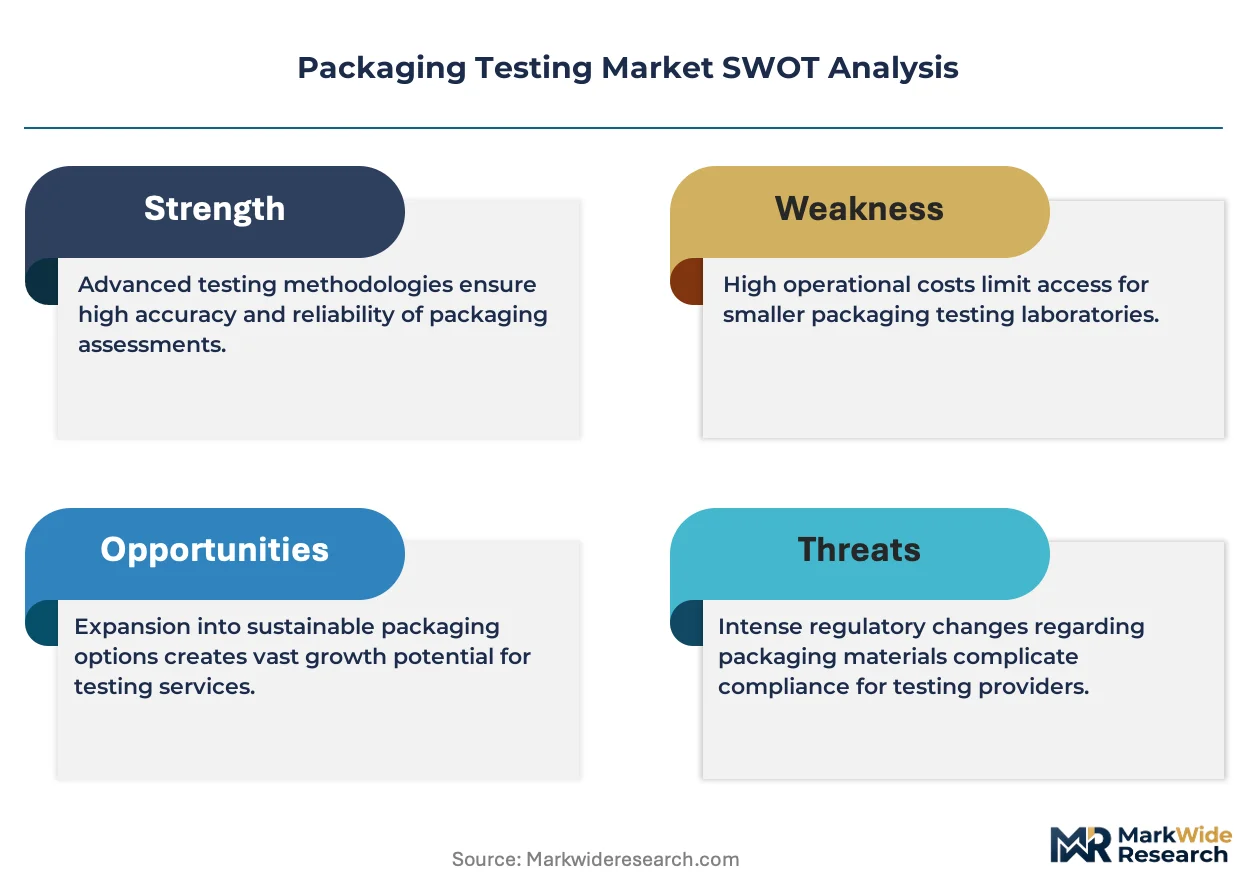
The escalation of regulatory scrutiny, particularly for sterile medical and food-grade packaging, is the central force shaping the market. This transforms testing from a quality assurance function into a non-negotiable prerequisite for market access, driving investment in advanced validation capabilities.
Growth Catalysts
- EU Medical Device Regulation:The EU's MDR mandates rigorous validation of sterile barrier systems under ISO 11607, compelling medical device manufacturers to invest heavily in comprehensive stability and integrity testing services.
- Sustainable Materials Adoption:The food and beverage industry's shift to recycled and biodegradable polymers creates demand for new testing protocols to validate their barrier properties, durability, and safety against established benchmarks for virgin materials.
- Pharmaceutical Cold Chain:Expansion in biologics and cell therapies requires sophisticated thermal packaging solutions, fueling demand for transit testing that simulates entire cold chain journeys, including temperature excursions and vibration profiles.
Market Restraints
- High Capital Investment:The significant cost of acquiring and maintaining advanced testing equipment, such as environmental simulation chambers and high-speed compression testers, presents a substantial barrier to entry for smaller, regional laboratories.
- Standardization Gaps:A lack of globally harmonized testing standards for e-commerce packaging makes it difficult to simulate the unpredictable hazards of direct-to-consumer supply chains, leading to over-packaging or product damage.
- Regulatory Divergence:Disparate regulations for food contact materials, such as the differences between US FDA requirements and EU EFSA rules, force exporters to conduct duplicative and costly tests for different markets.
Strategic Opportunities
- Emerging Market Expansion:Growth in medical device manufacturing in Southeast Asia offers a significant opportunity for establishing local testing facilities certified to global standards like ISO 11607 to serve new production hubs.
- Smart Packaging Validation:The rise of active and intelligent packaging creates a new service category focused on testing the durability and reliability of embedded sensors, indicators, and electronic components under physical stress.
- Digital Simulation Services:Integrating finite element analysis (FEA) with physical testing allows for predictive modeling of package performance, offering a high-value consultative service that can optimize designs and reduce material use.
Industry Challenges
- Specialized Talent Scarcity:A shortage of technicians possessing a hybrid skillset in material science, regulatory affairs, and data analytics hinders the effective operation and interpretation of results from sophisticated analytical instruments.
- Accreditation Timelines:The lengthy and rigorous process of obtaining ISO 17025 accreditation for new or modified test methods can delay the introduction of innovative services that respond to emerging materials or regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Testing Market |
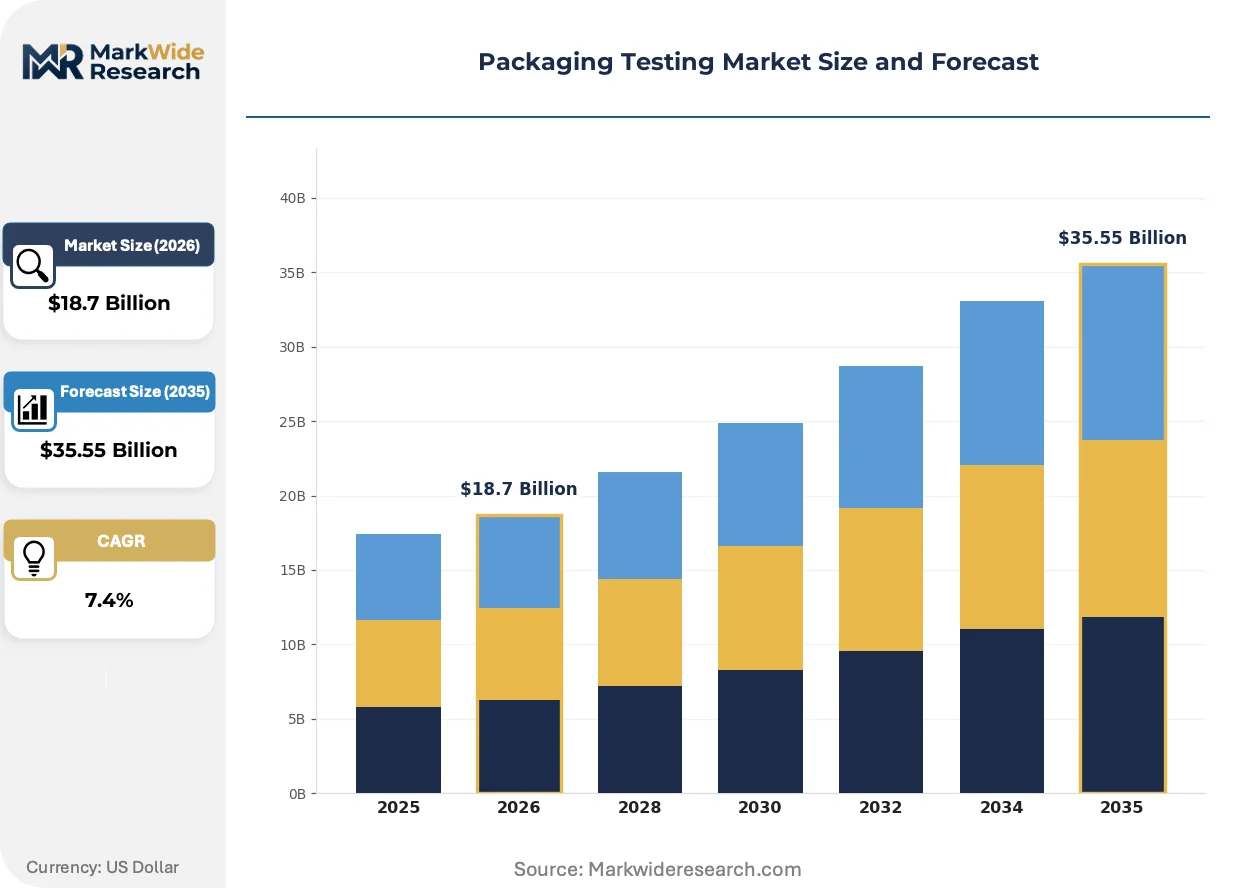
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $35.55 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Drop Test, Vibration Test, Compression Test, Climate Simulation, Seal Integrity, Leak Test Material Type: Plastic Films, Paperboard, Glass, Metal Cans, Flexible Pouches, Corrugated Fiberboard End User Industry: Food & Beverage, Pharmaceuticals, Electronics, Personal Care, Chemicals, Consumer Goods Packaging Format: Bottles, Cartons, Blister Packs, Tubes, Jars, Cans |
| Companies Covered | SGS S.A, Intertek Group Plc, Bureau Veritas SA, Eurofins Scientific SE, TÜV SÜD AG, Mérieux NutriSciences Corporation, ALS Limited, Microbac Laboratories Inc., National Technical Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Testing Market Strategic Shifts & Innovations
The market's evolution is defined by a pivot from discrete physical tests to integrated, data-rich validation strategies. This shift is a direct response to more complex global supply chains, novel materials, and stringent regulatory frameworks demanding a holistic proof of performance.
Digital simulation software creates virtual models of packaging to predict performance under various physical and environmental stresses before physical prototyping. The consumer electronics and automotive sectors are strong adopters, seeking to accelerate development cycles. This software-first approach is decomposing the traditional, linear sequence of design-prototype-test by enabling parallel, iterative virtual validation and optimizing material usage early in the process.
China's national GB standards for packaging, especially for food and pharmaceutical products, are becoming progressively more stringent and specific. This regulatory tightening compels both domestic producers and international companies to perform testing in accredited Chinese laboratories or with their certified partners. The food and beverage sector is most affected, forcing packaging redesigns and a re-evaluation of regional testing strategies to ensure compliance for market entry.
A transition from transactional, project-based testing to subscription-style service agreements is gaining momentum among large consumer packaged goods firms. This model replaces ad-hoc test requests with a partnership that provides dedicated testing capacity, priority scheduling, and consultative support through a unified platform. This demand-side shift is particularly prominent in the fast-moving consumer goods industry, where frequent product launches necessitate a more agile and predictable validation workflow.
Packaging Testing Market Segmentation
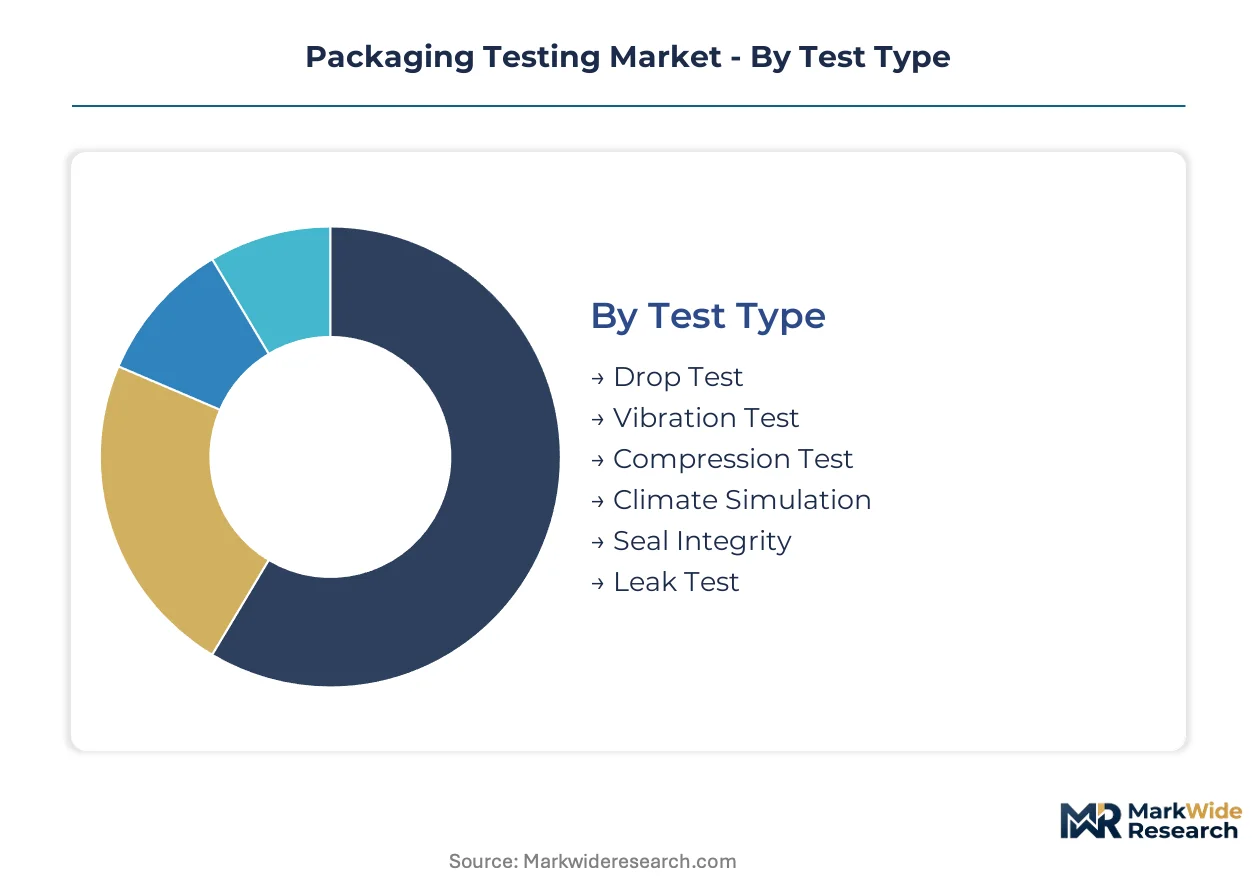
The Packaging Testing market's segmentation reflects the intricate demands of product protection, regulatory compliance, and material innovation across diverse industries. Understanding these distinct segments is crucial for laboratories to tailor their service offerings and for manufacturers to navigate complex validation requirements effectively.
Test Type:
The geographic spread of packaging testing services often dictates the prevalence of certain test types, with export-focused regions requiring specific validation methods to meet international standards.
- Seal Integrity:This critical test assesses the strength and integrity of seals in sterile barrier systems, particularly vital for medical devices under ISO 11607 compliance. Demand for this test is concentrating in Europe and the US, driven by stringent pharmaceutical regulations.
- Climate Simulation:This procedure evaluates packaging performance under controlled temperature and humidity extremes, crucial for pharmaceutical cold chain products and perishable food items. Asia-Pacific regions, with their diverse climates, show significant demand for these services.
- Drop Test:Simulates impacts during handling and transit, ensuring package contents remain protected from physical damage.
- Vibration Test:Assesses a package's resistance to vibrational stress encountered during transportation, common for consumer goods.
- Compression Test:Measures a package's ability to withstand stacking forces, particularly relevant for corrugated fiberboard in warehousing.
- Leak Test:Detects breaches in packaging that could compromise product sterility or freshness, essential for food and medical products.
Seal Integrity commands the established base. The steepest expansion runs through Climate Simulation.
Material Type:
Segmentation by material type highlights the diverse functional applications of packaging, each demanding tailored testing approaches to ensure performance and safety.
- Corrugated Fiberboard:Widely used for shipping containers, testing focuses on compression strength, burst resistance, and drop performance to protect goods during transit. E-commerce expansion in China is a primary driver for high-volume testing of this material.
- Plastic Films:Employed in flexible packaging for food and medical products, these materials require barrier property testing, seal strength analysis, and chemical migration studies. European regulations like REACH heavily influence testing protocols for plastic films.
- Paperboard:Utilized for cartons and folding boxes, testing evaluates stiffness, printability, and creasing performance.
- Glass:Common for beverages and pharmaceuticals, glass packaging undergoes tests for impact resistance, thermal shock, and chemical inertness.
- Metal Cans:Used for food and beverages, testing includes internal pressure resistance, corrosion resistance, and seal integrity.
- Flexible Pouches:These versatile packages require rigorous testing for seal strength, puncture resistance, and barrier properties against moisture and oxygen.
Paperboard testing remains a foundational service, while the validation of Flexible Pouches is expanding most quickly.
End User Industry:
Segmentation by end-user industry reveals how the sheer volume of packaged goods in certain sectors drives consistent demand for specific testing regimes.
- Pharmaceuticals:Requires extensive sterile barrier validation, stability testing, and cold chain simulation to meet regulations like the EU MDR. The US FDA mandates rigorous testing for drug packaging.
- Food & Beverage:High-volume sector demanding tests for shelf-life, barrier properties, and food contact material safety under regulations like US FDA and EU EFSA. China's GB standards are also critical for market entry.
- Electronics:Packaging for electronic devices needs shock and vibration testing to prevent damage to sensitive components during transit.
- Personal Care:Products require testing for package integrity, material compatibility, and dispensing functionality.
- Chemicals:Packaging for chemicals undergoes stringent testing for containment, material compatibility, and hazard communication compliance.
- Consumer Goods:This broad category demands a range of physical tests to ensure product protection and brand integrity through the supply chain.
Food & Beverage demand for testing is stable, whereas Pharmaceuticals shows dynamic expansion.
Packaging Format:
The maturity of various packaging formats influences the type and frequency of required testing, from established designs to novel structures.
- Blister Packs:Predominantly used in pharmaceuticals, these require precise testing for seal integrity, child resistance, and material compatibility. NMPA regulations in China specify requirements for pharmaceutical blister packs.
- Cartons:Widely used across food, personal care, and consumer goods, cartons undergo compression, drop, and material strength tests. Demand is high in India for consumer product packaging.
- Bottles:Common for liquids, bottles are tested for impact resistance, leak integrity, and closure performance.
- Tubes:Used for pastes and creams, tubes require testing for burst strength, cap integrity, and product compatibility.
- Jars:Often glass or plastic, jars are tested for impact resistance, seal performance, and stackability.
- Cans:Metal cans for food and beverages are tested for seam integrity, internal pressure, and corrosion resistance.
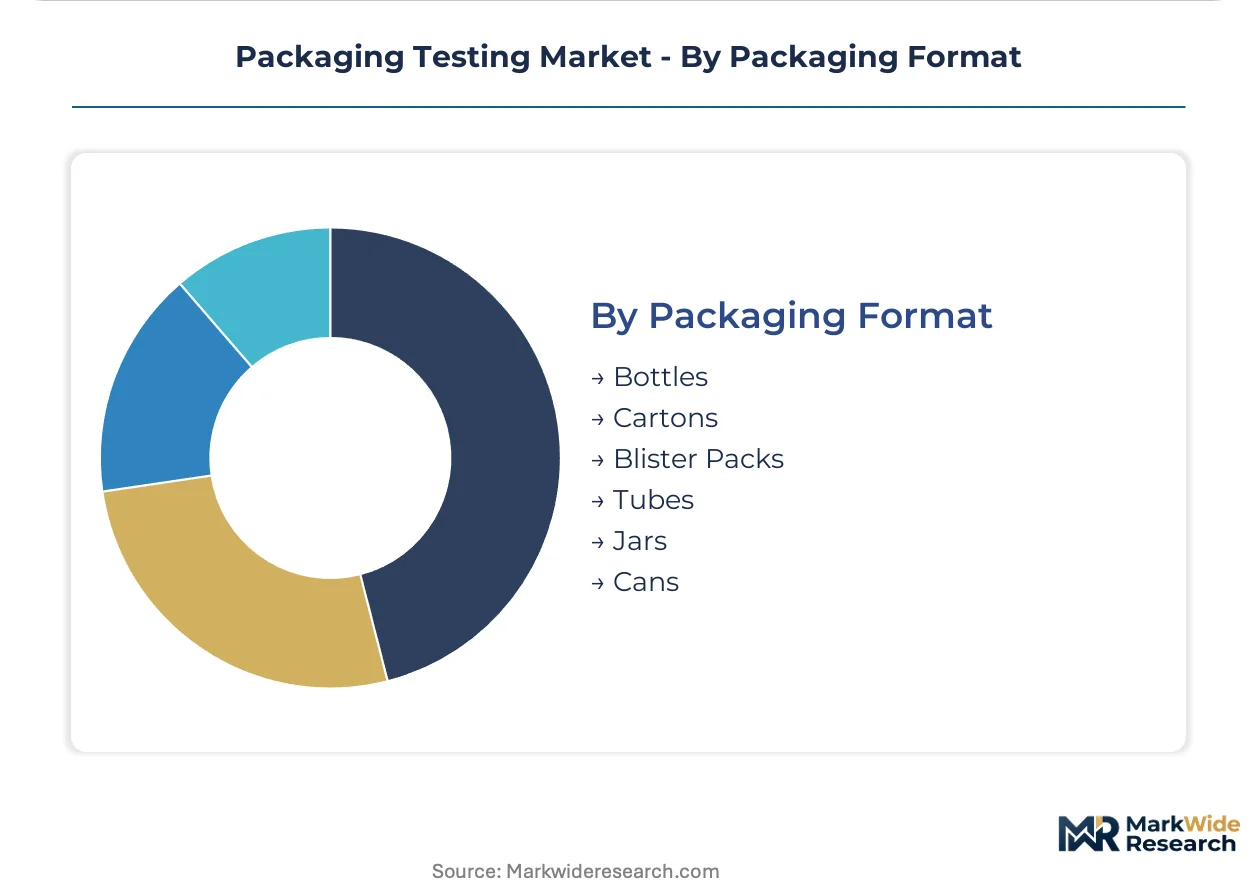
Traditional formats like Cans maintain relevance, but innovation drives growth in Blister Packs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The escalation of regulatory scrutiny for sterile medical and food-grade packaging is transforming market access requirements across diverse regions. This compliance-driven demand for comprehensive validation services pushes investment into advanced testing capabilities globally. Strict adherence to international and national standards becomes a non-negotiable prerequisite.
United States
The US FDA mandates rigorous testing for food contact materials and drug packaging, driving demand for specialized testing services. Pharmaceutical cold chain expansion, particularly for biologics, requires sophisticated thermal packaging validation. California's biotech and medical device manufacturing hubs require extensive sterile barrier and stability testing.
Germany
The EU's Medical Device Regulation (MDR) compels German medical device manufacturers to invest heavily in ISO 11607 compliant packaging validation. Demand also stems from the automotive sector for robust component packaging and the food industry for sustainable material testing. The Rhine-Main region, a pharmaceutical R&D cluster, drives demand for advanced integrity testing.
China
National GB standards for food and pharmaceutical packaging are becoming increasingly stringent, necessitating localized testing for market entry. China's role as a major exporter of consumer and medical goods generates high volumes of physical and environmental testing. The Yangtze River Delta region experiences substantial demand for corrugated fiberboard testing due to e-commerce growth.
India
The expanding pharmaceutical manufacturing sector in India requires extensive sterile packaging validation and cold chain simulation services. BIS standards for packaging materials and CDSCO regulations for drug packaging are critical drivers. Hyderabad's pharmaceutical industry cluster fuels demand for advanced leak and seal integrity tests.
Japan
Japan's high-precision electronics industry and quality-focused food sector demand meticulous packaging performance testing. PMDA regulations for medical devices and JIS standards for industrial packaging ensure product integrity and safety. The Tokyo metropolitan area is a hub for smart packaging innovation, requiring validation of embedded sensors and indicators.
Packaging Testing Market Key Industry Players
Player mix skews toward established global testing, inspection, and certification (TIC) firms with extensive accreditation and network capabilities. The market structure exhibits a tiered consolidation, with a few large players dominating high-value, complex validation services. Strategic archetypes include global generalists, specialized material science experts, and regional niche providers. Geographic expansion into emerging production hubs and portfolio diversification into smart packaging validation are common competitive moves.
Specialists in comprehensive testing services include SGS S.A., Intertek Group Plc, and Bureau Veritas SA. SGS S.A. leverages its extensive global network to offer end-to-end validation for multinational clients. Intertek Group Plc differentiates through deep expertise in polymer and material science analytics, crucial for novel material validation. Bureau Veritas SA occupies a position with a broad portfolio of testing, inspection, and certification services across multiple industries.
| Leading Market Players |
|---|
| SGS S.A |
| Intertek Group Plc |
| Bureau Veritas SA |
| Eurofins Scientific SE |
| TÜV SÜD AG |
| Mérieux NutriSciences Corporation |
| ALS Limited |
| Microbac Laboratories Inc. |
| National Technical Systems Inc. |
Cost & Logistics Intelligence
Project-based testing agreements and subscription service contracts lock in both supply access and price visibility for specialized packaging validation. This dual contract approach helps stabilize revenue streams for testing laboratories while ensuring manufacturers meet stringent regulatory deadlines.
Pricing Analysis
Cost-plus contract patterns, indexed to specialized equipment depreciation and accredited personnel salaries, define pricing for complex validation services. Price differentiation drivers include the specific certification level required, such as ISO 17025 for laboratory competence, and the volume scale of testing batches. Pricing pressure stems from the commoditization of basic physical tests for standard materials, while specialized services command premium rates due to regulatory complexity. Multinational pharmaceutical and medical device firms exhibit lower price sensitivity for critical sterile barrier testing compared to smaller consumer goods manufacturers.
Supply Chain Analysis
Lead times for specialized testing equipment, particularly environmental simulation chambers, directly impact service delivery capacity for packaging testing laboratories. Geographic supply concentration for advanced testing equipment centers in Germany, the United States, and Japan. The industry relies on a consistent supply of calibration standards and specialized polymer samples for material science analytics. Talent scarcity in material science and regulatory affairs presents a structural risk. Distribution runs through a global network of accredited laboratories and direct service delivery models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a fragmentation opportunity, driven by the demand-side shift towards validating sustainable packaging materials across diverse industries.
For Market Incumbents: Shield core sterile barrier testing revenue by continuously investing in advanced validation technologies for biologics cold chain and smart packaging. Expand global ISO 17025 accreditation to counter localized regulatory threats from national GB standards. Deepen expertise in polymer science to address the validation needs of novel biodegradable and recycled materials. Control key certification pathways to maintain a competitive advantage against emerging specialized entrants.
For New Entrants and Emerging Players: Anchor in specific material science niches, such as barrier property validation for recycled plastics or testing embedded sensors in active packaging. Target underpenetrated regional markets like Southeast Asia, where medical device manufacturing is expanding, requiring ISO 11607 compliance. A focused go-to-market strategy emphasizing rapid accreditation for specific local regulations, like India's BIS standards, can secure initial market share.
For Investors and Strategic Acquirers: Specialized material science laboratories with unique polymer analysis capabilities represent attractive acquisition targets over the next five to ten years. These firms often possess proprietary testing methods or niche accreditations that complement broader testing portfolios. A signal to watch for inflection is the increasing adoption of digital simulation services, indicating a shift towards more capital-efficient validation models.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Cold Chain Testing Capacity | Supports pharmaceutical industry growth in biologics and cell therapies requiring sophisticated thermal validation. |
| Invest in Sustainable Material Validation | Addresses food and beverage industry demand for testing recycled and biodegradable packaging properties. |
| Acquire Regional Accreditation Specialists | Strengthens market access by complying with diverse national standards like China's GB regulations. |
| Develop Digital Simulation Services | Offers predictive modeling of package performance, reducing physical prototyping costs for consumer electronics. |
| Enhance Polymer Science Expertise | Differentiates services by providing deep analysis for novel plastic films and flexible pouches in medical applications. |
Research Approach
Desk research of ISO standards documents, FDA guidance, EU MDR texts, and corporate sustainability reports preceded structured interviews with packaging engineers, regulatory affairs specialists, quality assurance managers, and material scientists. This primary and secondary data was then subjected to both bottom-up and top-down triangulation to ensure comprehensive market sizing and validation.
Variance decomposition informed the analytical framework for market projections over the projection horizon. Segmentation dimensions modeled included test type, material type, end-user industry, packaging format, and regional regulatory clusters. Compound annual growth rates were derived through regression analysis, factoring in market share shifts and competitive dynamics. Key forecast inputs included regulatory changes, material innovation cycles, and e-commerce growth rates.
Material uncertainties — unforeseen geopolitical events affecting supply chains, rapid shifts in global regulatory harmonization, or breakthrough material discoveries — sit outside the modeled envelope. Forecasts reflect assumptions documented through stakeholder consultations and secondary data analysis. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Pack Testing Machines Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Packaging Inspection Systems Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Europe Package Testing Market