
 North America Package Testing Market | 2026-2036
North America Package Testing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Package Testing Market Analytics
Mexico's industrial corridor expansion is rewriting regional logistics infrastructure, drawing package testing capacity southward to serve automotive and electronics export hubs. Intertek leverages its cross-border laboratory network to capture pharmaceutical and medical device validation work. SGS anchors quality assurance programs for food exporters navigating FDA and USDA entry requirements. Cryopak specializes in temperature-controlled packaging qualification for biologics shipments.
North America Package Testing encompasses mechanical, environmental, and thermal evaluation protocols that verify packaging integrity across distribution cycles, employing drop towers, vibration tables, climatic chambers, and compression rigs to simulate real-world stress conditions. The practice ensures product protection, regulatory compliance, and cost optimization for manufacturers shipping fragile, perishable, or regulated goods. Shock Testing and Vibration Testing dominate volume due to universal application across electronics and automotive parts, while Compression Testing commands premium pricing in palletized food and beverage distribution. Flexible Packaging testing is accelerating fastest as e-commerce subscription models and sustainable film substitutions proliferate among consumer goods brands.
FDA regulations govern pharmaceutical and medical device packaging validation, with 21 CFR Part 211 setting current good manufacturing practice standards that directly mandate container closure integrity. ASTM Standards and ISTA Standards provide the methodological backbone for consumer goods and logistics performance certification, with ISTA 3A and ASTM D4169 serving as the dominant e-commerce and unit-load simulation protocols. Stakeholders must monitor evolving state-level extended producer responsibility legislation and bioplastics performance gaps as sustainability mandates begin to override legacy material specifications.
Market Dynamics
FDA's serialization mandates for pharmaceutical distribution security are compressing testing timelines while biotech clusters in Massachusetts and California concentrate demand for cold chain validation services.
Growth Catalysts
- Biologics cold chain expansion:Temperature-sensitive biopharmaceutical shipments across the United States require thermal packaging qualification that exceeds traditional pharmaceutical standards.
- 21 CFR Part 211 enforcement:Current good manufacturing practice standards for container closure integrity are tightening compliance-driven testing volumes.
- E-commerce subscription models:Flexible packaging for recurring consumer deliveries is generating new mechanical and environmental test protocols.
Market Restraints
- Capital equipment cycles:Drop towers, vibration tables, and climatic chambers require substantial reinvestment every seven to ten years.
- Bioplastics performance gaps:Sustainable film substitutions often fail ASTM D4169 compression and ISTA 3A drop sequences.
- Laboratory capacity concentration:Testing infrastructure clusters near automotive and electronics export corridors in Mexico's industrial belt.
Strategic Opportunities
- Extended producer responsibility mandates:State-level legislation in California and New York is forcing packaging redesigns that require pre-market validation.
- Medical device sterilization validation:Gamma and ethylene oxide barrier testing for implantable devices represents underpenetrated service expansion.
- Cross-border pharmaceutical logistics:Temperature qualification for shipments between United States and Mexican maquiladora facilities is creating new protocol demand.
Industry Challenges
- ASTM and ISTA protocol harmonization:Divergent simulation standards between e-commerce and unit-load testing create certification complexity for multi-channel brands.
- Thermal chamber calibration cycles:Maintaining NIST-traceable qualification for climatic testing demands continuous metrology investment.
- Legacy ERP integration:Test data management systems must interface with pharmaceutical batch records governed by 21 CFR Part 11 electronic signature requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Package Testing Market |
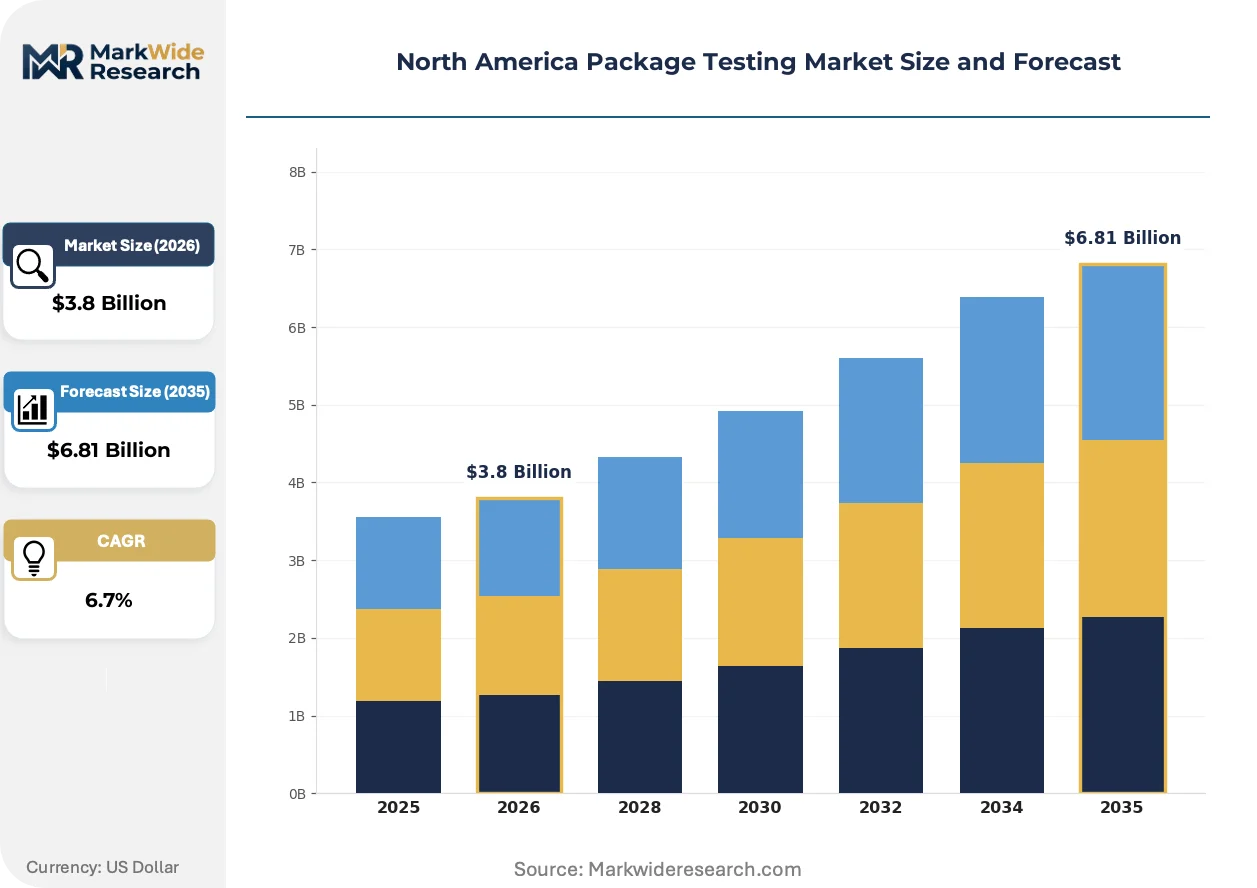
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Shock Testing, Vibration Testing, Compression Testing, Drop Testing Package Type: Flexible Packaging, Rigid Packaging, Paperboard Packaging, Glass Packaging End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Testing Standard: ASTM Standards, ISTA Standards, ISO Standards, FDA Regulations |
| Companies Covered | DDL, Inc., Intertek, SGS, CSZ Testing Services Laboratories, Cryopak, Advance Packaging, Nefab, Bureau Veritas, UL Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Package Testing Market Evolving Landscape
Digital simulation tools are compressing physical test cycles while regulatory mandates force real-time data traceability across pharmaceutical supply chains.
Finite element analysis software is virtualizing structural modeling for corrugated fiberboard and expanded polystyrene cushioning before physical prototype production. Consumer electronics manufacturers in California are adopting these tools to reduce ISTA 3A certification cycles from weeks to days. The technology is virtualizing traditional drop tower and compression rig workflows, allowing engineers to iterate packaging geometry without material waste.
FDA's Drug Supply Chain Security Act implementation deadlines are mandating unit-level serialization that requires packaging line validation and authentication testing. Pharmaceutical contract packagers must verify barcode readability, tamper-evidence integrity, and aggregation accuracy across distribution temperatures. Biotech manufacturers in Massachusetts are responding by integrating vision systems and environmental chambers into qualification protocols.
Third-party logistics providers are unbundling packaging engineering from freight contracts, creating direct procurement relationships with specialized testing laboratories. E-commerce brands previously reliant on carrier packaging guidelines now commission custom ISTA 3A sequences for subscription box durability. This pattern concentrates most visibly among direct-to-consumer food and beverage startups in Texas and Colorado seeking differentiation through unboxing experience reliability.
North America Package Testing Market Segmentation
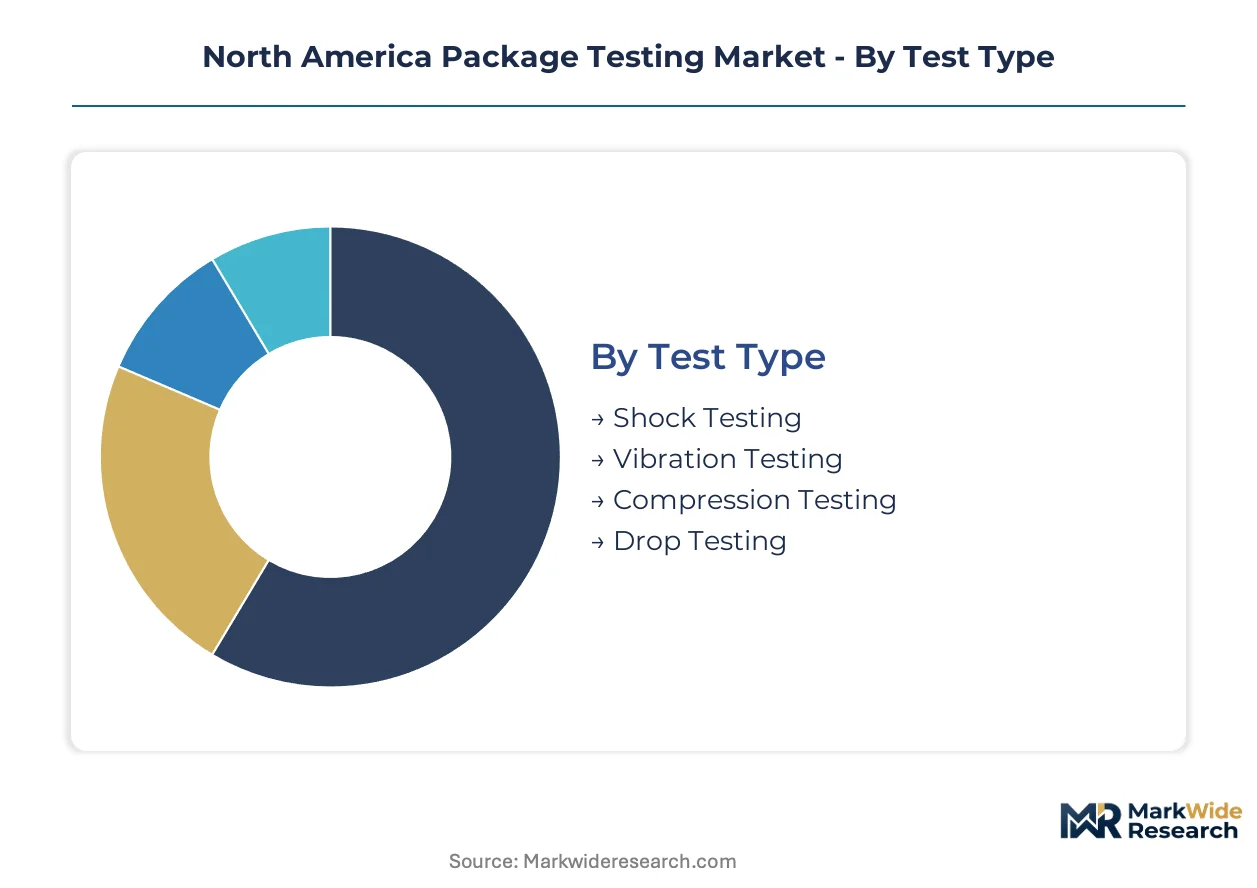
Package testing in North America fragments across four distinct dimensions that shape procurement patterns and laboratory capacity allocation. Test type and package material specifications determine equipment investment cycles, while end-user verticals and regulatory compliance standards dictate geographic clustering of testing infrastructure.
Test Type:
Mechanical stress simulation spans a use-case spectrum from single-unit consumer electronics to palletized industrial shipments, with each protocol demanding specialized instrumentation and calibration regimens.
- Shock Testing:Accelerated impact simulation using pendulum or pneumatic shock machines measures packaging response to sudden deceleration events. Electronics manufacturers in California's Bay Area dominate procurement for semiconductor and device protection validation, driven by ISTA 3A certification requirements for e-commerce distribution.
- Vibration Testing:Electrodynamic and hydraulic shaker tables replicate truck, rail, and air transport frequency spectra. Automotive parts suppliers in Mexico's industrial corridor concentrate demand for component shipping validation, with just-in-time delivery mandates compressing test turnaround windows.
- Compression Testing:Static and dynamic load frames evaluate stacking strength for warehouse storage configurations.
- Drop Testing:Free-fall towers and incline impact surfaces simulate handling mishaps across distribution nodes.
The dominant share belongs to Shock Testing, while Vibration Testing is closing the gap fastest.
Package Type:
Material substrate selection drives testing protocol variation, with film-based formats requiring distinct environmental conditioning compared to structural containers.
- Flexible Packaging:Polymer films, laminates, and pouches demand seal integrity and puncture resistance evaluation under thermal cycling. Food subscription services in Texas and Colorado are expanding test volumes for recurring delivery durability, responding to consumer complaint thresholds for damaged goods.
- Glass Packaging:Brittle material fracture mechanics testing under vibration and impact loading. Wine and spirits distributors in California's Central Valley require specialized shock absorption validation for export shipments, with breakage rates directly tied to carrier liability negotiations.
- Rigid Packaging:Molded plastics and thermoformed containers undergo compression and drop sequence validation.
- Paperboard Packaging:Corrugated fiberboard edge crush and burst strength testing for e-commerce fulfillment.
Flexible Packaging commands the largest testing commitment by volume, though Glass Packaging is gaining share fastest among premium beverage exporters.
End User:
Vertical industry requirements stratify testing intensity, with regulated sectors demanding documentary traceability that consumer goods categories rarely match.
- Pharmaceuticals:Container closure integrity, sterility maintenance, and cold chain thermal qualification under 21 CFR Part 211. Biotech clusters in Massachusetts and California are concentrating demand for biologics stability testing, with temperature excursion documentation now mandatory for distribution licensing.
- Food & Beverage:Shelf-life extension validation, migration testing, and distribution durability for perishable supply chains. Mexican produce exporters navigating FDA and USDA entry requirements are driving cross-border laboratory utilization at Intertek and SGS facilities.
- Electronics:Electrostatic discharge protection and shock absorption for fragile component shipments.
- Consumer Goods:Unboxing experience reliability and retail-ready presentation durability.
Pharmaceuticals absorb the highest testing expenditure per unit, yet Food & Beverage is expanding most quickly as direct-to-consumer delivery models proliferate.
Testing Standard:
Regulatory and industry consensus specifications create compliance hierarchies that determine laboratory accreditation requirements and customer audit protocols.
- ASTM Standards:Consensus-based methods including D4169 for unit-load distribution simulation. Palletized food and beverage distribution in the Midwest relies heavily on ASTM compression and vibration sequences, with retailer acceptance criteria often specifying exact protocol variants.
- FDA Regulations:21 CFR Part 211 cGMP mandates for pharmaceutical container closure integrity. Enforcement actions against contract packagers in Puerto Rico and New Jersey are tightening compliance-driven testing volumes, with warning letters citing inadequate validation documentation.
- ISTA Standards:Performance-based certification protocols for e-commerce and retail distribution.
- ISO Standards:International harmonization frameworks for multinational manufacturer quality systems.
ASTM Standards hold the broadest adoption across end-user categories, while FDA Regulations are climbing fastest as serialization mandates tighten pharmaceutical packaging line validation requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach and Los Angeles complex anchors trans-Pacific container flows that generate massive package testing demand for electronics and consumer goods entering North American distribution networks.
United States
Biotech clusters in Massachusetts and California concentrate demand for cold chain validation services as biologics shipments expand. FDA serialization mandates under the Drug Supply Chain Security Act compress testing timelines for pharmaceutical contract packagers. Temperature-controlled packaging qualification now dominates laboratory capacity allocation around Boston and San Diego.
Mexico
Automotive and electronics export hubs in Nuevo León and Baja California draw package testing capacity southward to serve just-in-time delivery mandates. Mexican produce exporters navigate FDA and USDA entry requirements that demand pre-shipment validation at cross-border laboratory facilities. The maquiladora corridor generates new protocol demand for temperature qualification between United States and Mexican manufacturing sites.
Canada
Natural resource extraction equipment and pharmaceutical exports drive mechanical stress simulation demand around Toronto and Vancouver. Health Canada regulations align with FDA standards for medical device packaging validation, creating integrated compliance pathways for cross-border manufacturers. Cold chain infrastructure for temperature-sensitive biologics concentrates testing procurement in Ontario and Quebec.
North America Package Testing Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying calibrated instrumentation and consumables to end-user laboratories. The North American market exhibits moderate consolidation, with multinational testing conglomerates operating alongside regional specialists and equipment fabricators. Three archetypes dominate: full-service certification houses, temperature-focused cold chain specialists, and equipment manufacturers with captive service arms. Capacity expansion and cross-border laboratory networking represent the dominant competitive vectors as firms chase pharmaceutical and automotive testing flows.
Among multinational certification houses, Intertek, SGS, and Bureau Veritas exemplify the integrated service model spanning mechanical, environmental, and regulatory compliance testing. These firms occupy positions anchored by geographic footprint breadth and accreditation depth. Cryopak represents the cold chain specialist archetype, sitting within the temperature-controlled packaging qualification segment. Equipment-led players such as DDL and CSZ Testing Services Laboratories anchor the upstream instrumentation tier, supplying drop towers, vibration tables, and climatic chambers to both captive and third-party laboratories.
| Leading Market Players |
|---|
| DDL, Inc. |
| Intertek |
| SGS |
| CSZ Testing Services Laboratories |
| Cryopak |
| Advance Packaging |
| Nefab |
| Bureau Veritas |
| UL Solutions |
| Others |
Value Network & Pricing Analysis
Overcapacity in California's laboratory corridor is compressing test margins while concentrating pricing power among ISO 17025-accredited facilities serving FDA-regulated pharmaceutical clients. Utilization gaps between biotech-cluster demand centers and Mexico's automotive export belt create geographic arbitrage opportunities that reshape supplier investment patterns.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with certification grade and volume scale as primary differentiation drivers. Premium tiers attach to 21 CFR Part 211 compliance documentation and cold chain thermal qualification, while economy tiers serve non-regulated consumer goods validation. Cost compression in standard-tier mechanical testing is intensifying because equipment manufacturers are deploying captive service arms with aggressive pricing. Small-batch pharmaceutical startups exhibit highest price sensitivity; multinational contract packagers show least sensitivity due to regulatory risk transfer requirements.
Supply Chain Analysis
Upstream feedstock for testing instrumentation draws from Germany, Japan, and the United States, with electrodynamic shaker systems and climatic chambers as critical component categories. NIST-traceable calibration standards and specialized vibration isolation platforms create single-source vulnerability for high-precision thermal qualification. Distribution runs through third-party logistics providers that unbundle packaging engineering from freight contracts, creating direct laboratory procurement relationships among e-commerce subscription brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning. Accreditation depth and FDA audit history generate switching costs that protect incumbent laboratory relationships.
For Market Incumbents: Entrench cross-border laboratory networks between United States and Mexican maquiladora corridors to capture temperature qualification demand for pharmaceutical shipments. Deepen backward integration into NIST-traceable metrology services to reduce third-party calibration dependency. Cryopak's cold chain specialization and Intertek's geographic footprint exemplify defensible positioning against emerging temperature-focused entrants.
For New Entrants and Emerging Players: Pursue medical device sterilization validation as an underpenetrated service expansion, particularly gamma and ethylene oxide barrier testing for implantable devices. Texas and Colorado direct-to-consumer food and beverage startups represent the most penetrable segment due to unmet subscription box durability requirements. Lead with digital simulation tool integration to compress ISTA 3A certification cycles as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cold chain specialists with pharmaceutical client concentration and multi-year validation service agreements. Long-term viability centers on laboratories with embedded regulatory compliance workflows rather than commodity mechanical testing capacity. Acquisition target archetype: regional specialists with FDA warning letter remediation expertise and biotech cluster proximity. Watch for state-level extended producer responsibility legislation acceleration as an inflection indicator for packaging redesign validation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Laboratory Network Expansion | Captures temperature qualification demand for pharmaceutical shipments between United States and Mexican maquiladora facilities. |
| Digital Simulation Tool Integration | Compresses ISTA 3A certification cycles from weeks to days for California consumer electronics manufacturers. |
| NIST-Traceable Metrology Service Buildout | Reduces third-party calibration dependency and protects margin in climatic chamber qualification segments. |
| Medical Device Sterilization Validation Entry | Addresses underpenetrated gamma and ethylene oxide barrier testing for implantable device manufacturers. |
| Extended Producer Responsibility Compliance Service Launch | Positions laboratories for California and New York state-level packaging redesign validation mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across laboratory directors, pharmaceutical quality assurance managers, packaging engineers at contract packagers, and third-party logistics procurement leads. Secondary validation drew from FDA warning letter databases, ASTM and ISTA protocol revision records, SEC filings of listed testing conglomerates, and customs data on testing equipment imports. Bottom-up segment sizing triangulated against top-down market envelope calculations from equipment manufacturer shipment records and laboratory accreditation databases.
Calibration against historical growth trajectories in adjacent validation services anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include test type, package material substrate, end-user vertical, and regulatory compliance tier. CAGRs were derived from slope analysis of equipment investment cycles and regulatory mandate implementation timelines. Pharmaceutical serialization deadlines and biologics cold chain expansion curves served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by equipment manufacturers with captive service arms would shift outcomes beyond modeled ranges. Cross-checking against laboratory utilization rates reported in industry association benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Global Package Testing Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Pack Testing Machines Market