

Package Testing Silicone Rubber Socket Market Size, Share, and Industry Trends Forecast 2026-2036
Package Testing Silicone Rubber Socket Market Insights
The capital-intensity divergence between vertically integrated silicone compounders and pure-play socket assemblers is unwinding competitive stability in this niche. ISC Technology leverages captive silicone formulation capabilities to control material consistency across BGA and QFN socket lines. TSE Co., Ltd. anchors its position through backward integration into high-temperature silicone polymer synthesis. Smiths Interconnect competes via precision-machined contact structures that extend cycle life in burn-in applications.
Package testing silicone rubber sockets are elastomeric test interfaces molded from platinum-cured silicone compounds with Shore A hardness ranging from 40 to 70, designed to provide temporary electrical contact between device under test and tester hardware without solder attachment. These components absorb thermal expansion mismatches during temperature cycling from -55°C to 150°C while maintaining contact resistance below 50 milliohms. BGA sockets dominate volume demand due to the ubiquity of ball grid array packages in consumer and automotive semiconductors, though LGA sockets command premium positioning in server CPU verification where pin count exceeds 4,000. Liquid silicone rubber injection molding is displacing compression molding for sub-0.4mm pitch applications where dimensional tolerance tightens to ±0.01mm.
FDA regulations on platinum catalyst residues, REACH restrictions on volatile siloxanes, and RoHS substance limits collectively shape material formulation choices and supplier qualification timelines in this market. Japan's PMDA-aligned quality system requirements and South Korea's K-Battery and K-Semiconductor initiative standards add further compliance layers for regional market access. Stakeholders must monitor evolving halogen-free mandates and contact plating specifications as heterogeneous integration packaging expands test socket duty cycles.
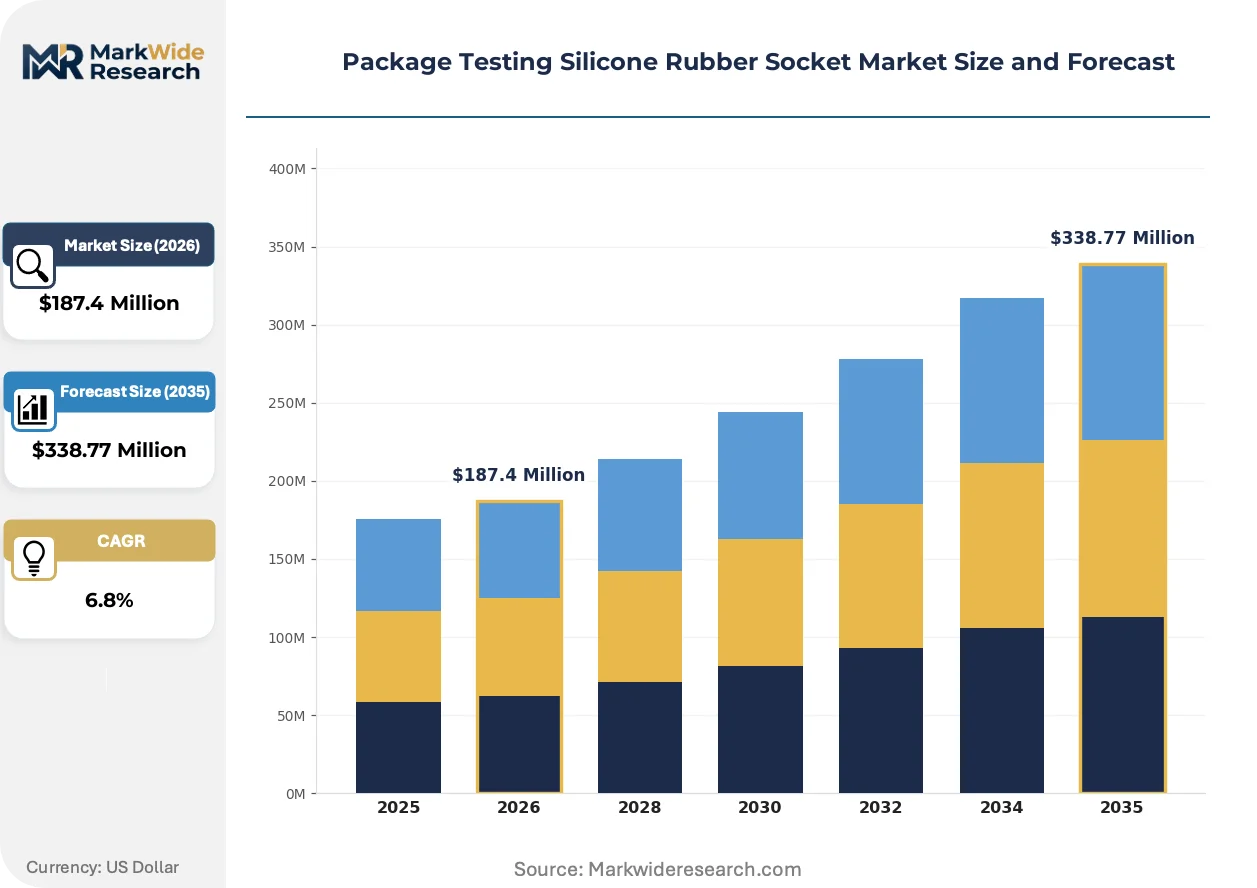
Market Dynamics
Advanced packaging complexity is fragmenting socket procurement patterns across semiconductor test facilities, as heterogeneous integration multiplies pin counts and thermal cycling requirements beyond legacy silicone compound specifications.
Growth Catalysts
- Heterogeneous Integration Packaging:Chiplet architectures in high-performance computing are multiplying test socket duty cycles and contact density requirements. Burn-in facilities in Taiwan and South Korea are expanding silicone rubber socket orders to match.
- Japan's METI Semiconductor Revitalization Policies:Domestic content incentives for advanced packaging equipment are redirecting procurement toward certified Japanese silicone compounders. PMDA-aligned quality systems are accelerating supplier qualification timelines.
- Automotive Semiconductor Verification:AEC-Q100 Grade 0 testing protocols are extending temperature cycling ranges from -55°C to 150°C. Elastomeric sockets with platinum-cured formulations are displacing mechanical alternatives in power module validation.
Market Restraints
- Platinum Catalyst Cost Volatility:Platinum group metal price swings directly compress gross margins for liquid silicone rubber compounders. Formulators with captive catalyst recovery systems partially hedge this exposure.
- East Asian Supply Concentration:Hsinchu Science Park and Seoul's Pangyo belt host over seventy percent of high-volume socket demand. Geopolitical friction across the Taiwan Strait concentrates risk in a single procurement corridor.
- REACH Volatile Siloxane Restrictions:ECHA classification of certain siloxanes as substances of very high concern is forcing reformulation of legacy compounds. Requalification cycles extend twelve to eighteen months.
Strategic Opportunities
- India's PLI Scheme for Semiconductors:Gujarat and Tamil Nadu greenfield fabs are establishing first-mover test infrastructure. Local socket assembly partnerships with compound importers can preempt multinational incumbents.
- Sub-0.4mm Pitch Liquid Silicone Rubber Injection:Two-shot molding convergence with micro-cavity thermal management is enabling ±0.01mm tolerance at volume. This process-material pairing opens premium positioning in mobile AP verification.
- China's GB Standards for Test Interface Materials:Mandatory domestic certification for semiconductor test equipment is creating captive demand for locally compounded silicone. Joint ventures with state-designated material labs secure access.
Industry Challenges
- Platinum-Cured Formulation Expertise Scarcity:Compounders with deep knowledge of platinum catalyst inhibition chemistry and post-cure dynamics are concentrated in Japan and Germany. Talent poaching between ISC Technology and TSE Co. intensifies wage pressure.
- Multi-Regulatory Certification Parallelism:Simultaneous FDA, REACH, RoHS, and PMDA qualification demands dedicated regulatory affairs teams. Smaller socket assemblers lack resources to maintain concurrent compliance portfolios.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Package Testing Silicone Rubber Socket Market Trends and Innovations
Liquid silicone rubber processing is fragmenting the competitive map between precision molders and legacy compression houses, as dimensional tolerances tighten and thermal cycling specifications multiply across automotive and server CPU segments.
Two-shot liquid silicone rubber injection molding is bifurcating the socket market between sub-0.4mm pitch specialists and legacy compression molders. High-volume burn-in facilities in Taiwan are adopting this technology for BGA sockets with 4,000-plus pin counts. The process is bifurcating supplier tiers, as capital requirements for micro-cavity tooling exclude mid-scale compounders from premium server CPU verification contracts.
REACH restrictions on volatile siloxanes are compressing formulation freedom for European socket suppliers. ECHA's SVHC candidate list expansion forces compounders to redesign platinum-cured systems around alternative crosslinking chemistries. German automotive test houses are accelerating qualification of halogen-free silicone grades to preempt downstream OEM bans.
Consolidated procurement by Taiwan Semiconductor Manufacturing and Samsung Foundry is compressing socket vendor margins and extending payment terms. Tier-one test facilities are unbundling socket supply from turnkey tester contracts, forcing pure-play assemblers to compete directly with vertically integrated equipment vendors. This pattern concentrates most acutely in Hsinchu, where facility expansion is synchronizing with advanced packaging ramp schedules.
Package Testing Silicone Rubber Socket Market Segmentation
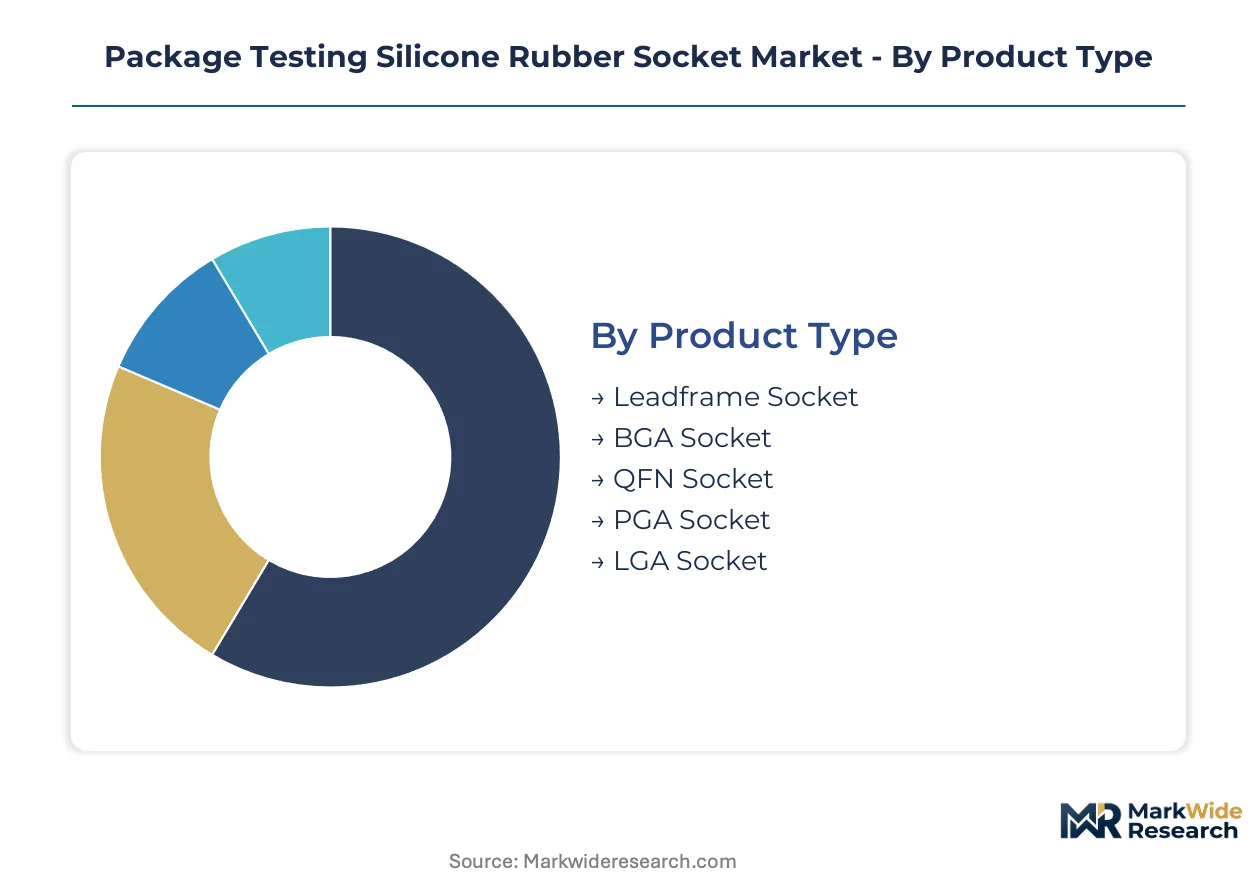
Package testing silicone rubber sockets fragment across four dimensions that determine procurement priorities and margin capture. Product type and material composition dominate supplier positioning, while application specificity and end-user concentration shape volume contracting patterns.
Product Type:
Premium margins concentrate in high-pin-count sockets for server CPU and advanced packaging verification, while consumer semiconductor testing drives volume at compressed pricing.
- BGA Socket:Ball grid array interfaces molded from platinum-cured silicone with Shore A 50-70 hardness accommodate solder sphere contact arrays from 0.4mm to 1.0mm pitch. Taiwan's Hsinchu Science Park burn-in facilities are expanding procurement to match heterogeneous integration ramp schedules. Automotive semiconductor qualification is extending temperature cycling specifications beyond legacy compound limits.
- LGA Socket:Land grid array configurations serve pin counts exceeding 4,000 in server CPU verification where contact resistance must hold below 30 milliohms across -55°C to 150°C cycles. Seoul's Pangyo semiconductor belt commands premium positioning for these specifications. Two-shot liquid silicone rubber injection molding is displacing compression molding at sub-0.4mm pitch.
- QFN Socket:Quad flat no-lead sockets handle perimeter pad configurations with molded sidewall contact structures.
- PGA Socket:Pin grid array variants retain niche positioning in legacy microprocessor test infrastructure.
- Leadframe Socket:Traditional dual-inline and small-outline package interfaces serve commodity semiconductor verification.
The dominant share belongs to BGA Socket, while LGA Socket is closing the gap fastest.
Material Composition:
Formulation chemistry determines thermal performance ceilings and regulatory compliance burdens across regional qualification requirements.
- Liquid Silicone Rubber:Platinum-cured injection molding compounds enable ±0.01mm dimensional tolerance for mobile AP verification at sub-0.4mm pitch. Taiwan Semiconductor Manufacturing consolidated procurement is compressing compounder margins while extending volume commitments. REACH volatile siloxane restrictions are forcing reformulation of legacy systems.
- High-Temperature Silicone:Peroxide-cured formulations withstand continuous exposure above 200°C in power module burn-in applications. AEC-Q100 Grade 0 automotive protocols are displacing mechanical socket alternatives. Japan's METI domestic content incentives favor certified Japanese compounders.
- Fluorosilicone:Fluorinated backbone structures resist solvent exposure in harsh environment reliability assessment.
- Room-Temperature Silicone:Condensation-cure systems serve low-cost compression molding for standard consumer package testing.
- Thermoplastic Elastomer:TPE alternatives compete on material cost for single-use disposable test interfaces.
Liquid Silicone Rubber commands the largest volume position, though High-Temperature Silicone is expanding most quickly in automotive verification.
Application:
Test protocol severity determines socket duty cycle requirements and replacement frequency, directly influencing lifetime value calculations.
- Semiconductor Package Testing:High-volume burn-in and final test operations consume elastomeric sockets at rates exceeding 10,000 insertions per unit in Taiwan and South Korea facilities. Heterogeneous integration is multiplying pin density and thermal cycling requirements. Consolidated procurement by Samsung Foundry is unbundling socket supply from turnkey tester contracts.
- Failure Analysis:Diagnostic applications demand precision contact structures for destructive and non-destructive examination of field returns. Electronics OEMs in Japan's semiconductor revitalization corridor are expanding captive failure analysis capacity. PMDA-aligned quality systems accelerate supplier qualification.
- Integrated Circuit Verification:Design validation protocols precede mass production ramp.
- Quality Assurance:Incoming inspection and process control applications serve assembly house operations.
- Reliability Assessment:Accelerated life testing and environmental stress screening qualify package integrity.
Semiconductor Package Testing holds the dominant application share, with Failure Analysis gaining share fastest.
End User:
Procurement sophistication varies sharply between vertically integrated IDMs and outsourced test service providers.
- Chip Manufacturers:Integrated device manufacturers in Taiwan and South Korea specify custom socket designs synchronized with advanced packaging roadmaps. Direct compounder relationships bypass distributor markups for high-volume programs. India's PLI scheme for semiconductors is attracting first-mover Gujarat and Tamil Nadu fab investments.
- Test Laboratories:Independent verification facilities maintain multi-platform socket inventories to serve diverse customer portfolios. China's GB standards for test interface materials mandate domestic certification. Joint ventures with state-designated material labs secure regional access.
- Assembly Houses:Outsourced semiconductor assembly and test providers optimize socket utilization rates across customer programs.
- Electronics OEMs:Original equipment manufacturers with captive semiconductor operations maintain specialized verification infrastructure.
- Contract Manufacturers:Electronics manufacturing service providers source sockets through consolidated component procurement.
Chip Manufacturers represent the largest end-user segment, while Test Laboratories are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Taiwan and South Korea prioritize high-volume burn-in sockets for heterogeneous integration, while Japan and Germany emphasize automotive-grade material certification, and China builds domestic supply chains under state-directed procurement mandates.
Taiwan
Semiconductor package testing facilities at Hsinchu Science Park and Taichung's Central Taiwan Science Park consume elastomeric sockets at rates exceeding 10,000 insertions per unit. The National Science and Technology Council's advanced packaging subsidies are expanding local burn-in capacity. Kaohsiung's emerging semiconductor cluster is attracting socket assembly joint ventures with Japanese compounders.
South Korea
Samsung Foundry and SK Hynix are unbundling socket supply from turnkey tester contracts, forcing direct procurement negotiations. The K-Semiconductor initiative under METI-aligned standards is tightening material traceability requirements. Seoul's Pangyo semiconductor belt commands premium positioning for LGA sockets with pin counts exceeding 4,000.
Japan
Automotive semiconductor verification under AEC-Q100 Grade 0 protocols is extending temperature cycling ranges from -55°C to 150°C. METI's domestic content incentives redirect procurement toward certified Japanese silicone compounders with PMDA-aligned quality systems. Kyushu's silicon island hosts concentrated platinum-cured formulation expertise.
China
GB standards for test interface materials mandate domestic certification for semiconductor test equipment procurement. State-designated material labs in Shanghai and Beijing are qualifying locally compounded silicone for captive socket production. Yangtze River Delta fabs are establishing parallel supply chains to hedge import dependency.
Germany
Automotive test houses are accelerating qualification of halogen-free silicone grades to preempt downstream OEM bans. ECHA's SVHC candidate list expansion is forcing compounders to redesign platinum-cured systems around alternative crosslinking chemistries. Bavaria's precision molding specialists are adopting two-shot liquid silicone rubber injection for sub-0.4mm pitch applications.
Package Testing Silicone Rubber Socket Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. Vertically integrated compounders with captive silicone formulation capabilities control material consistency across high-volume product lines, while pure-play socket assemblers compete on precision-machined contact structures and cycle life extension. Three archetypes dominate: Japanese material specialists with backward polymer synthesis integration, Taiwanese precision molders serving foundry procurement clusters, and European automotive-focused compounders navigating REACH reformulation mandates. Consolidated procurement by Taiwan Semiconductor Manufacturing and Samsung Foundry is compressing vendor margins, while two-shot liquid silicone rubber injection molding is bifurcating supplier tiers through capital-intensive micro-cavity tooling requirements.
Among East Asian material-integrated specialists, TSE Co., Ltd. and ISC Technology exemplify the compounder-assembler convergence model, with the former anchoring high-temperature silicone polymer synthesis capabilities and the latter leveraging captive formulation control across BGA and QFN socket lines. Smiths Interconnect occupies a position within the precision-contact tier, representing European expertise in extending cycle life for burn-in applications. These three entities illustrate how regional industrial bases—Japan's material science corridor, Taiwan's foundry-proximate manufacturing belt, and Europe's automotive certification hub—shape competitive positioning without cross-border operational overlap.
| Leading Market Players |
|---|
| ISC Technology |
| TSE Co., Ltd. |
| JMT (TFE) |
| SNOW Co., Ltd. |
| SRC Inc. |
| Smiths Interconnect |
| WinWay Technology |
| Ironwood Electronics |
| LEENO Industrial |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization rates exceeding ninety percent at Taiwanese liquid silicone rubber compounders are compressing price floors for socket assemblers while simultaneously concentrating procurement leverage among Hsinchu-based burn-in facilities. This scale dynamic creates asymmetric bargaining power where consolidated buyers extract volume discounts while smaller test laboratories absorb premium pricing for expedited delivery.
Pricing Analysis
After-sales service contracts and replacement part programs generate lifetime value multiples exceeding initial socket unit sales by factors of three to five across high-volume burn-in operations. Three-tier pricing structure across automotive-grade certification, industrial-standard, and economy-tier unqualified sockets separates Samsung Foundry procurement from independent test house purchasing. Cost compression in standard-grade BGA sockets is intensifying because consolidated procurement by Taiwan Semiconductor Manufacturing extends payment terms to ninety days. Independent test laboratories exhibit highest price sensitivity due to fragmented order volumes, while integrated device manufacturers with captive burn-in infrastructure demonstrate lowest sensitivity given total cost of ownership framing.
Supply Chain Analysis
Inventory cycles stretching sixteen to twenty weeks for platinum-cured silicone compounds are forcing socket assemblers to pre-position material buffers ahead of heterogeneous integration ramp schedules. Supply concentrates in Japan for high-temperature polymer synthesis, Taiwan for precision molding capacity, and Germany for automotive certification expertise. Raw material dependencies center on platinum group metal catalysts, high-purity silicone monomers, and precision-machined contact pin substrates. Single-source vulnerability for platinum catalyst supply from South African refiners exposes compounders to commodity price volatility. Distribution runs through direct foundry procurement contracts rather than distributor networks, with consolidated buyers negotiating frame agreements that bypass traditional channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Package testing silicone rubber sockets sit within an early-cycle expansion phase as heterogeneous integration multiplies contact density requirements beyond legacy mechanical socket capabilities. Advanced packaging complexity at Taiwan Semiconductor Manufacturing and Samsung Foundry is accelerating elastomeric socket penetration rates.
For Market Incumbents: Consolidate formulation expertise through selective acquisition of Japanese platinum-cured compound specialists facing generational succession pressures. Deepen captive silicone polymer synthesis capabilities to hedge platinum catalyst cost volatility while simultaneously qualifying halogen-free grades ahead of downstream OEM mandates. Defensive positioning requires preemptive certification investment under China's GB standards before state-designated material labs close access to foreign compounders.
For New Entrants and Emerging Players: Lead with two-shot liquid silicone rubber injection molding capability targeting sub-0.4mm pitch mobile AP verification where incumbent capacity constraints create delivery backlogs. India's Gujarat and Tamil Nadu greenfield fabs present the most penetrable geography given first-mover test infrastructure buildout and absence of entrenched supplier relationships. A joint venture structure with state-designated material laboratories secures mandatory domestic certification under China's procurement mandates.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated compounder-assemblers with captive silicone formulation and direct foundry relationships spanning multiple packaging generations. Long-term viability over the next decade rests on positioning against heterogeneous integration roadmaps rather than legacy package formats. Acquisition targets should demonstrate platinum-cured formulation expertise with PMDA-aligned quality systems. The signal to watch is qualification timeline compression for halogen-free silicone grades at German automotive test houses, indicating downstream OEM mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Polymer Synthesis | TSE Co., Ltd. anchors material consistency across high-temperature socket lines through captive monomer production. |
| Two-Shot Liquid Silicone Rubber Injection Molding | Precision molders in Taiwan's Hsinchu corridor capture sub-0.4mm pitch server CPU contracts from compression houses. |
| Joint Venture with State-Designated Material Labs | Foreign compounders secure GB standards certification access for China's captive semiconductor test equipment procurement. |
| Halogen-Free Silicone Grade Qualification | German automotive test houses preempt downstream OEM bans through accelerated REACH-compliant formulation adoption. |
| Platinum Catalyst Recovery Systems | Formulators with in-house precious metal recycling partially hedge gross margin exposure to South African refinery supply volatility. |
Research Methodology
A spread of perspectives from socket design engineers at Taiwanese burn-in facilities, procurement leads at South Korean foundries, Japanese silicone compounder technical directors, and German automotive test house quality managers converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEMI equipment market reports, ECHA regulatory filings, and METI policy documentation. Bottom-up unit demand modeling triangulated against top-down semiconductor capital expenditure forecasts.
Segmentation dimensions modeled include socket product type, material composition grade, application protocol severity, and end-user procurement sophistication across the projection horizon. CAGRs were derived from regression analysis against heterogeneous integration packaging roadmaps and foundry capacity expansion schedules. Industry-specific forecast inputs incorporated platinum group metal price trajectory assumptions and REACH volatile siloxane restriction implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained advanced packaging complexity acceleration or abrupt platinum supply disruption would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation pacing and foundry consolidation trends. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.