
 Food Packaging Tester Market | 2026-2036
Food Packaging Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Food Packaging Tester Market Foresight
Ready-to-eat meal production is expanding faster than legacy dry-goods packaging, pulling investment toward seal integrity and oxygen permeability validation. SGS leverages its pan-European laboratory network to anchor contract testing demand from multinational food manufacturers. Eurofins Scientific competes through specialized diagnostics capabilities that extend into packaging migration and contaminant screening. Bureau Veritas dominates third-party certification workflows for exporters seeking dual FDA-EMA compliance.
Food packaging testers are instruments and systems that quantify barrier performance, mechanical durability, and seal reliability under simulated distribution stresses, typically measuring parameters such as leak rates in mbar·L/s, compression resistance in newtons, or oxygen transmission rates in cm³/m²·day. Their primary commercial purpose is to prevent spoilage, ensure label-claimed shelf life, and satisfy retailer audit protocols before shipment. Seal integrity testers lead equipment demand because vacuum decay and pressure decay methods have displaced destructive sampling in high-volume dairy and fresh produce operations. Infrared spectroscopy and gas chromatography segments are gaining share among quality assurance labs that need molecular-level verification of volatile compound ingress. Mechanical force testing retains stable placement within frozen food and confectionery supply chains where drop and compression failures drive insurance claims.
FDA food contact notification rules and the EU F-Gas Regulation shape equipment specifications by mandating documentation of barrier properties and restricting certain testing gas chemistries. BIS certification requirements in India and China's GB standards for food packaging safety create parallel compliance tracks that fragment vendor qualification protocols. Stakeholders must monitor how EFSA's evolving migration limit guidance and state-level extended producer responsibility laws in California and New York reshape capital allocation between inline testing and laboratory outsourcing.
Market Dynamics
Processed food manufacturers are consolidating testing workflows under single-source contracts that bundle inline instrumentation with laboratory validation, compressing vendor margins while raising technical certification barriers for new entrants.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Tightening seal integrity mandates force dairy processors to upgrade vacuum decay testing capacity ahead of enforcement deadlines.
- Ready-to-eat meal production:Extended shelf-life claims for chilled prepared foods drive oxygen permeability validation at volumes exceeding legacy dry-goods testing.
- Germany's export certification infrastructure:Downstream retail audit requirements from chains like Aldi and Lidl concentrate demand for dual FDA-EMA compliant testing documentation.
Market Restraints
- Helium supply concentration:Russia and Qatar control over 60% of global helium production, creating volatility in leak detection gas costs for mass spectrometry systems.
- Calibration equipment import dependency:High-precision reference standards for oxygen transmission rate validation originate from a narrow base of German and Japanese metrology suppliers.
- F-Gas Regulation phase-down:Restrictions on sulfur hexafluoride and perfluorocarbon tracer gases limit method options for pharmaceutical barrier testing that shares equipment platforms with food applications.
Strategic Opportunities
- India BIS certification expansion:Mandatory food packaging safety testing under GB-standard-equivalent protocols creates first-mover advantage for laboratories establishing Mumbai and Delhi facilities.
- Biodegradable barrier films:PLA and PHA substrates with unproven shelf-life performance require novel accelerated aging protocols that existing equipment cannot execute without modification.
- California extended producer responsibility:State-level packaging waste accountability laws incentivize inline testing investment to minimize material over-engineering and subsequent compliance penalties.
Industry Challenges
- Spectroscopy technician scarcity:FTIR and GC-MS operation for migration screening requires analytical chemistry credentials that food industry quality labs struggle to recruit against pharmaceutical salary benchmarks.
- Legacy MES integration:Inline seal testers from the 2010s lack OPC-UA connectivity, forcing costly middleware development to feed data into modern manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Packaging Tester Market |
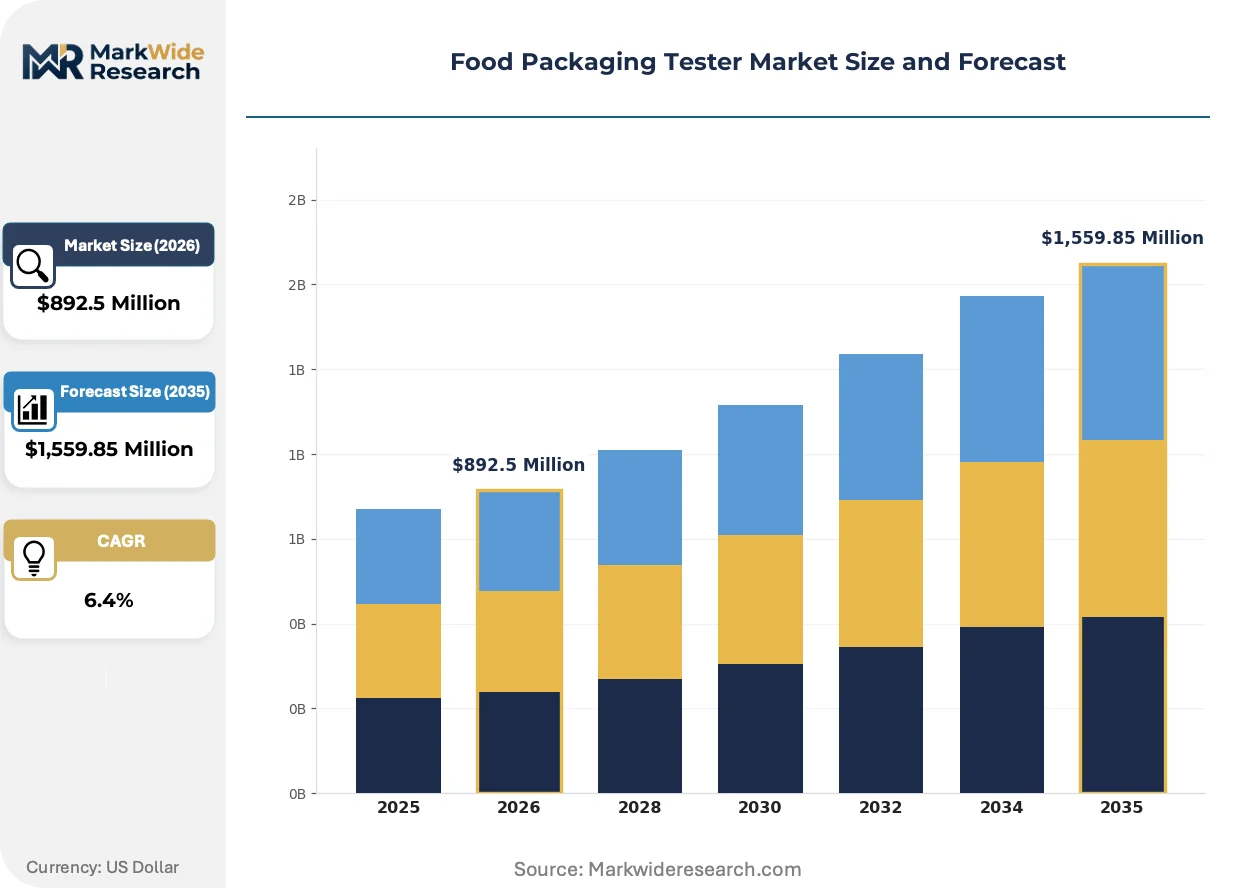
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,559.85 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leak Tester, Compression Tester, Drop Tester, Seal Integrity Tester, Oxygen Permeability Tester Technology: Vacuum Decay, Pressure Decay, Infrared Spectroscopy, Gas Chromatography, Mechanical Force Application: Processed Food, Fresh Produce, Dairy Products, Confectionery, Frozen Food End User: Food Manufacturers, Quality Assurance Labs, Packaging Companies, Research Institutes |
| Companies Covered | SGS, Intertek, ALS Ltd, Eurofins Scientific, Bureau Veritas, TÜV SÜD, Mérieux NutriSciences, Robert Bosch, GEA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Packaging Tester Market Shifts & Advancements
Non-destructive testing methods are displacing destructive sampling protocols across high-volume production lines, while regulatory documentation requirements digitize compliance workflows and reshape capital allocation between inline and laboratory assets.
Laser-based headspace analysis is expanding into modified atmosphere packaging validation for fresh produce and protein applications. Berry producers in California and Spain are adopting tunable diode laser absorption spectroscopy to replace chromatographic oxygen verification, cutting per-sample testing time from hours to seconds. This displacement is compressing third-party laboratory revenue from routine batch release testing while expanding equipment vendor service contract penetration.
The EU F-Gas Regulation's accelerated phase-down of high-global-warming-potential testing gases is forcing equipment redesigns across leak detection segments. Manufacturers are retrofitting mass spectrometry systems for hydrogen tracer compatibility, though hydrogen's flammability profile complicates installation in dairy plants with existing safety protocols. Frozen food processors in northern Europe face the steepest compliance timeline pressure, with 2027 deadlines for SF6 elimination in barrier validation workflows.
Retailer audit consolidation is compressing vendor qualification cycles for multinational food manufacturers. Unilever and Nestlé procurement teams are unbundling after-sales calibration services from equipment purchase contracts, instead awarding multi-year service agreements to independent metrology providers. This disintermediation is most visible in Germany, where TÜV and DAkkS-accredited laboratories now compete directly with original equipment manufacturers for recurring revenue streams.
Food Packaging Tester Market Segmentation
Equipment selection in food packaging testing follows distinct procurement logics across production environments. Inline automation demands differ sharply from laboratory validation workflows, while regulatory scope determines whether manufacturers invest in single-parameter instruments or multi-technology platforms.
Product Type:
Volume deployment clusters around entry-level leak detection, while premium absorption concentrates in multi-parameter systems for export certification.
- Seal Integrity Tester:Vacuum decay and pressure decay methods dominate high-volume dairy and fresh produce operations where non-destructive protocols displaced destructive sampling. German exporters to Aldi and Lidl procurement networks drive demand for dual-method systems capable of FDA-EMA documentation.
- Oxygen Permeability Tester:Coulometric and optical sensor technologies quantify barrier performance for modified atmosphere packaging in chilled ready-to-eat meals. California berry producers and Spanish vegetable exporters are expanding validation capacity ahead of extended shelf-life claims.
- Leak Tester:Mass spectrometry and helium-based systems serve pharmaceutical-adjacent food applications requiring detection thresholds below 0.01 mbar·L/s.
- Compression Tester:Mechanical force validation for palletized distribution stresses retains stable placement within frozen food supply chains where insurance claims drive specification rigor.
- Drop Tester:Impact simulation equipment concentrates in confectionery and fragile goods packaging where retail damage allowances are tightening.
Mature deployment sits with Seal Integrity Tester. Newer deployment is concentrated in Oxygen Permeability Tester.
Technology:
Method selection tracks the tension between throughput velocity and molecular specificity, with regulatory chemistry restrictions reshaping platform economics.
- Vacuum Decay:Non-destructive detection of microleaks in flexible packaging operates at cycle times under 30 seconds per unit. Dairy processors across the EU are upgrading capacity ahead of Packaging and Packaging Waste Regulation enforcement deadlines.
- Infrared Spectroscopy:FTIR-based headspace analysis enables rapid oxygen and carbon dioxide verification without chromatographic delay. Fresh produce packers in California and Spain are adopting tunable diode laser variants that cut per-sample time from hours to seconds.
- Pressure Decay:Simpler instrumentation for rigid container validation dominates emerging market quality labs with constrained capital budgets.
- Gas Chromatography:Molecular-level migration screening for volatile compound ingress requires analytical chemistry expertise that food industry labs struggle to recruit.
- Mechanical Force:Drop and compression simulation retains placement in frozen food and logistics-heavy supply chains.
Established penetration characterizes Vacuum Decay. Accelerating uptake defines Infrared Spectroscopy.
Application:
End-use differentiation separates commodity testing from certification-intensive segments where retailer audit protocols dictate equipment specification.
- Processed Food:Shelf-life validation for retort pouches, aseptic cartons, and vacuum-sealed meats requires multi-parameter testing platforms. Consolidation under single-source contracts is compressing vendor margins while raising technical barriers.
- Fresh Produce:Modified atmosphere packaging for berries, leafy greens, and cut vegetables drives oxygen permeability investment at volumes exceeding legacy dry-goods testing. California and Spain dominate regional demand concentration.
- Dairy Products:Yogurt, cheese, and extended-life milk packaging mandate seal integrity protocols with documented traceability for EU export.
- Frozen Food:Mechanical durability testing for cryogenic distribution stresses retains stable equipment placement.
- Confectionery:Moisture barrier validation and impact resistance specification concentrate in premium chocolate and fragile goods segments.
Deep integration marks Processed Food. Expansion momentum centers on Fresh Produce.
End User:
Procurement authority splits between manufacturing operations seeking inline automation and external validation services managing regulatory documentation burdens.
- Food Manufacturers:Inline testing integration with manufacturing execution systems drives capital allocation toward OPC-UA-enabled instrumentation. Unilever and Nestlé procurement teams are unbundling calibration services from equipment purchase contracts.
- Quality Assurance Labs:Third-party certification workflows for dual FDA-EMA compliance concentrate demand in Germany's TÜV and DAkkS-accredited facility network.
- Packaging Companies:Material suppliers investing in barrier film development require accelerated aging protocols for biodegradable substrates.
- Research Institutes:Novel validation methodology for PLA and PHA biodegradable films drives limited but high-specification equipment demand.
Installed base dominance belongs to Food Manufacturers. Emerging contract growth defines Quality Assurance Labs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Germany and Japan, while consumption concentrates in export-intensive food processing economies facing downstream retailer certification mandates.
Germany
Dairy processors and chilled ready-to-eal manufacturers drive vacuum decay testing upgrades ahead of EU Packaging and Packaging Waste Regulation deadlines. The country's national metrology institute enforces DAkkS accreditation standards that downstream Aldi and Lidl procurement networks mandate for supplier qualification. Testing equipment demand concentrates in North Rhine-Westphalia's industrial corridor, where packaging machinery OEMs integrate inline validation systems.
United States
California berry producers and frozen food distributors anchor oxygen permeability validation investment for extended shelf-life claims. FDA food contact notification rules and California's extended producer responsibility laws reshape capital allocation between inline testing and laboratory outsourcing. The Central Valley agricultural cluster adopts tunable diode laser absorption spectroscopy to replace chromatographic verification methods.
China
Domestic food manufacturers expand quality assurance capacity to meet GB standards for food packaging safety and dual carbon goals for sustainable materials. The national market regulator enforces barrier property documentation requirements that parallel EU technical specifications. Equipment procurement concentrates in the Yangtze River Delta, where processed food exporters face downstream certification requirements from European retail chains.
India
Processed food manufacturers invest in seal integrity testing ahead of BIS certification expansion for mandatory food packaging safety protocols. The national standards body aligns technical requirements with GB-standard-equivalent frameworks to facilitate export market access. Mumbai and Delhi laboratory facilities capture contract testing demand from multinational food manufacturers seeking first-mover positioning.
Spain
Fresh produce exporters in the Valencia and Murcia regions drive modified atmosphere packaging validation for berry and vegetable shipments to Northern European retail networks. The EU F-Gas Regulation accelerates equipment replacement timelines for SF6-dependent leak detection systems. Barcelona-area quality laboratories compete for pan-European contract testing workflows from chilled food distributors.
Food Packaging Tester Market Competitive Landscape
Top-tier vendors anchor premium multi-parameter system supply, while mid-tier specialists populate single-technology segments with price-competitive offerings. Pan-European laboratory networks compete directly with original equipment manufacturers for recurring calibration and validation service revenue. Two strategic archetypes dominate: integrated testing service providers bundling equipment with certification workflows, and pure-play instrumentation manufacturers focusing on OPC-UA-enabled inline automation. Competitive moves concentrate on unbundling after-sales services from equipment purchase contracts and geographic expansion into BIS-mandated testing markets.
Within the integrated service provider tier, SGS and Bureau Veritas occupy positions spanning equipment distribution, laboratory validation, and third-party certification. Eurofins Scientific represents the specialized diagnostics archetype with capabilities extending into molecular-level contaminant screening. Among Germany-based technical service groups, TÜV SÜD exemplifies the accreditation-heavy positioning required for dual FDA-EMA compliance documentation.
| Leading Market Players |
|---|
| SGS |
| Intertek |
| ALS Ltd |
| Eurofins Scientific |
| Bureau Veritas |
| TÜV SÜD |
| Mérieux NutriSciences |
| Robert Bosch |
| GEA Group |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between DAkkS-accredited systems and uncertified bench units manifests in both pricing premiums and supply chain configurations. German metrology suppliers command 40-60% price premiums for traceable calibration standards that downstream Aldi and Lidl procurement networks mandate, while commodity pressure decay instruments flow through distributors serving emerging market quality labs with constrained capital budgets.
Pricing Analysis
Short lead-time premiums for helium-compatible mass spectrometry systems run 15-25% above standard delivery schedules as dairy processors race EU Packaging and Packaging Waste Regulation deadlines. Equipment vendors operate on a three-tier pricing structure across premium, standard, and economy levels: OPC-UA-enabled inline systems with integrated MES connectivity anchor the premium tier, standalone laboratory units populate the standard tier, and refurbished or entry-level pressure decay instruments serve price-sensitive emerging market buyers. Cost compression in the standard tier is intensifying because Unilever and Nestlé procurement teams are unbundling calibration services from equipment purchase contracts. Small-to-mid food manufacturers exhibit highest price sensitivity, while export-intensive German dairy processors show lowest sensitivity due to downstream retailer audit mandates.
Supply Chain Analysis
Workforce availability constraints in southern Germany and western Japan limit production scaling for high-precision oxygen transmission rate reference standards. Equipment assembly draws from German sensor component suppliers, Japanese metrology-grade electronics, and Chinese steel fabrication for mechanical frames. Helium supply concentration in Russia and Qatar creates single-source vulnerability for mass spectrometry leak detection systems. Distribution runs through packaging machinery OEMs in North Rhine-Westphalia who integrate inline validation systems, supplemented by direct laboratory sales for standalone units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Helium supply concentration and metrology-grade component scarcity prop pricing power for vendors with secured gas contracts and backward-integrated calibration capabilities.
For Market Incumbents: Anticipate margin compression from independent metrology providers competing for recurring calibration revenue streams that Unilever and Nestlé procurement teams are unbundling from equipment contracts. Defend position by deepening backward integration into reference standard production in Germany and accelerating OPC-UA connectivity development to lock in manufacturing execution system integration. Certification investment in India's BIS-equivalent protocols creates geographic hedge against European procurement consolidation. For New Entrants and Emerging Players: Capture white-space in biodegradable barrier film validation protocols that existing equipment cannot execute without modification for PLA and PHA substrates. India's BIS certification expansion represents the most penetrable geography, with Mumbai and Delhi laboratory facilities offering first-mover positioning before multinational food manufacturers consolidate testing contracts. Go-to-market angle: modular retrofit kits for legacy 2010s inline seal testers lacking MES connectivity, priced below full system replacement. For Investors and Strategic Acquirers: Re-rating potential sits with specialized diagnostics laboratories given EFSA's evolving migration limit guidance and state-level extended producer responsibility laws reshaping capital allocation between inline testing and outsourcing. Long-term viability favors quality assurance labs with dual FDA-EMA accreditation and pan-European facility networks over pure-play instrumentation manufacturers facing hardware commoditization. Signal to watch: California and New York extended producer responsibility enforcement timelines as inflection indicator for inline testing investment velocity versus laboratory outsourcing preference.| Strategic Initiative | Industry Significance |
|---|---|
| OPC-UA Connectivity Development | Enables seamless MES integration that Unilever and Nestlé procurement teams now require for inline systems. |
| Helium Supply Contract Securement | Mitigates gas cost volatility from Russia and Qatar concentration that threatens mass spectrometry margins. |
| BIS-Accredited Laboratory Establishment | Captures mandatory testing demand in India before multinational food manufacturers consolidate vendor relationships. |
| Biodegradable Film Protocol Development | Addresses unmet validation need for PLA and PHA substrates with unproven shelf-life performance. |
| Independent Metrology Service Launch | Competes for recurring calibration revenue that OEMs are losing to TÜV and DAkkS-accredited laboratories. |
Research Methodology
Trade publications, equipment vendor technical documentation, and EU regulatory filings formed the secondary backbone, supplemented by customs records for German and Japanese metrology component flows. Primary interviews with packaging machinery OEM procurement heads, dairy processor quality directors, third-party laboratory technical managers, and retailer audit compliance officers validated demand assumptions. Bottom-up triangulation across equipment shipment data and top-down cross-check against processed food production capacity expansion produced volume estimates.
Bottom-up modeling anchored forecasts, with top-down macro validation against food processing capital expenditure trends. Segmentation dimensions included product type (seal integrity, oxygen permeability, mechanical force), technology method (vacuum decay, infrared spectroscopy, pressure decay), application (processed food, fresh produce, dairy), and end-user procurement authority (inline manufacturing integration versus laboratory outsourcing). CAGRs derived from regression analysis of historical equipment replacement cycles and regulatory deadline clustering. Industry-specific inputs incorporated EU F-Gas Regulation phase-down timelines and BIS certification expansion schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to helium supply disruption, EFSA migration limit revisions, and California extended producer responsibility enforcement intensity. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Packaging Inspection Systems Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
North America Package Testing Market