
 Asia-Pacific Package Testing Market | 2026-2036
Asia-Pacific Package Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Package Testing Market Outlook
Japan's METI packaging recycling guidelines and China's dual carbon goals are consolidating sustainability-driven testing demand across the Asia-Pacific. SGS S.A. leverages its extensive laboratory network to dominate pharmaceutical and food safety certification. Intertek Group Plc anchors its regional position through specialized cold-chain validation services for temperature-sensitive shipments. Bureau Veritas competes aggressively on electronics packaging compliance for export markets.
Asia-Pacific package testing encompasses mechanical, environmental, and material integrity assessments applied to shipping containers, protective cushioning, and sealed primary packs. Compression testing evaluates stack-load resistance under warehouse storage conditions, while vibration and drop protocols simulate multi-modal transit stress. Drop test and vibration test segments lead volume due to universal application across e-commerce fulfillment networks. Pharmaceutical end users command premium pricing for shock test validation of biologic and vaccine distribution systems. Paperboard material testing is accelerating as brands substitute fiber-based alternatives for plastic compliance with EPR frameworks.
China's SAMR enforces GB standards for transport packaging, while India's BIS mandates IS certification for export-ready goods. Japan's JIS standards and Australia's TGA therapeutic goods guidelines further fragment compliance requirements across national boundaries. Stakeholders must map regulatory divergence country-by-country rather than applying uniform test protocols across the region.
Market Dynamics
India's PLI scheme for pharmaceuticals and electronics is consolidating testing demand around domestic certification infrastructure, compressing lead times for export-ready packaging validation.
Growth Catalysts
- Biologic cold-chain expansion:Vaccine distribution networks across Southeast Asia require shock and thermal validation protocols that pharmaceutical contract manufacturers cannot bypass.
- China's dual carbon goals:Fiber-based packaging substitution mandates under MEE guidelines accelerate paperboard compression and moisture-resistance testing volumes.
- E-commerce fulfillment density:Last-mile networks in Indonesia and Vietnam drive drop-test standardization for corrugated durability across humid climates.
Market Restraints
- Equipment import dependence:Vibration table and climatic chamber supply concentrates in German and Japanese OEMs, exposing Indian and Vietnamese labs to currency volatility and extended procurement cycles.
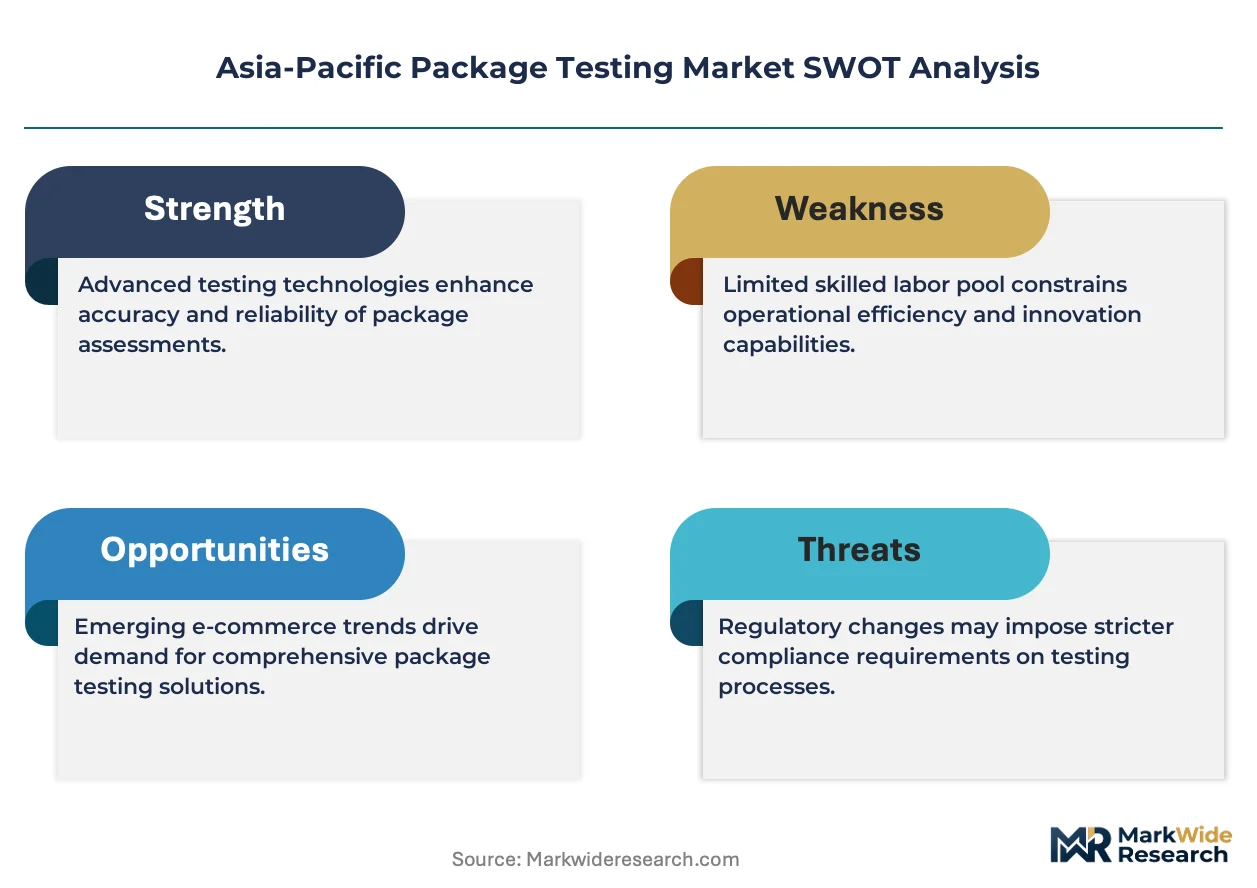
- Regulatory fragmentation:Divergent GB standards under SAMR, JIS specifications under METI, and TGA therapeutic goods guidelines force redundant test matrices for multi-country product launches.
- Technical limitation in accelerated aging:Current thermal cycling protocols fail to predict fiberboard performance beyond 18-month shelf lives, constraining adoption for premium export goods.
Strategic Opportunities
- Underpenetrated ASEAN pharmaceutical corridors:Thailand and Vietnam lack ISO 17025-accredited cold-chain validation labs, creating first-mover positioning for regional certification networks.
- Technology convergence:Integration of IoT-enabled shock loggers with traditional drop-test protocols enables real-world transit data feedback into laboratory simulation parameters.
- Regulatory tailwind:Japan's METI packaging recycling guidelines and Australia's EPR frameworks mandate recyclability verification, opening material integrity testing for molded fiber alternatives.
Industry Challenges
- Certification timeline compression:CDSCO and TGA therapeutic goods approvals require parallel packaging validation, stretching laboratory queue management systems.
- Skill scarcity in multi-modal simulation:Operators capable of correlating sea-air-road vibration spectra to laboratory random vibration profiles remain concentrated in Shanghai and Singapore.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Package Testing Market |
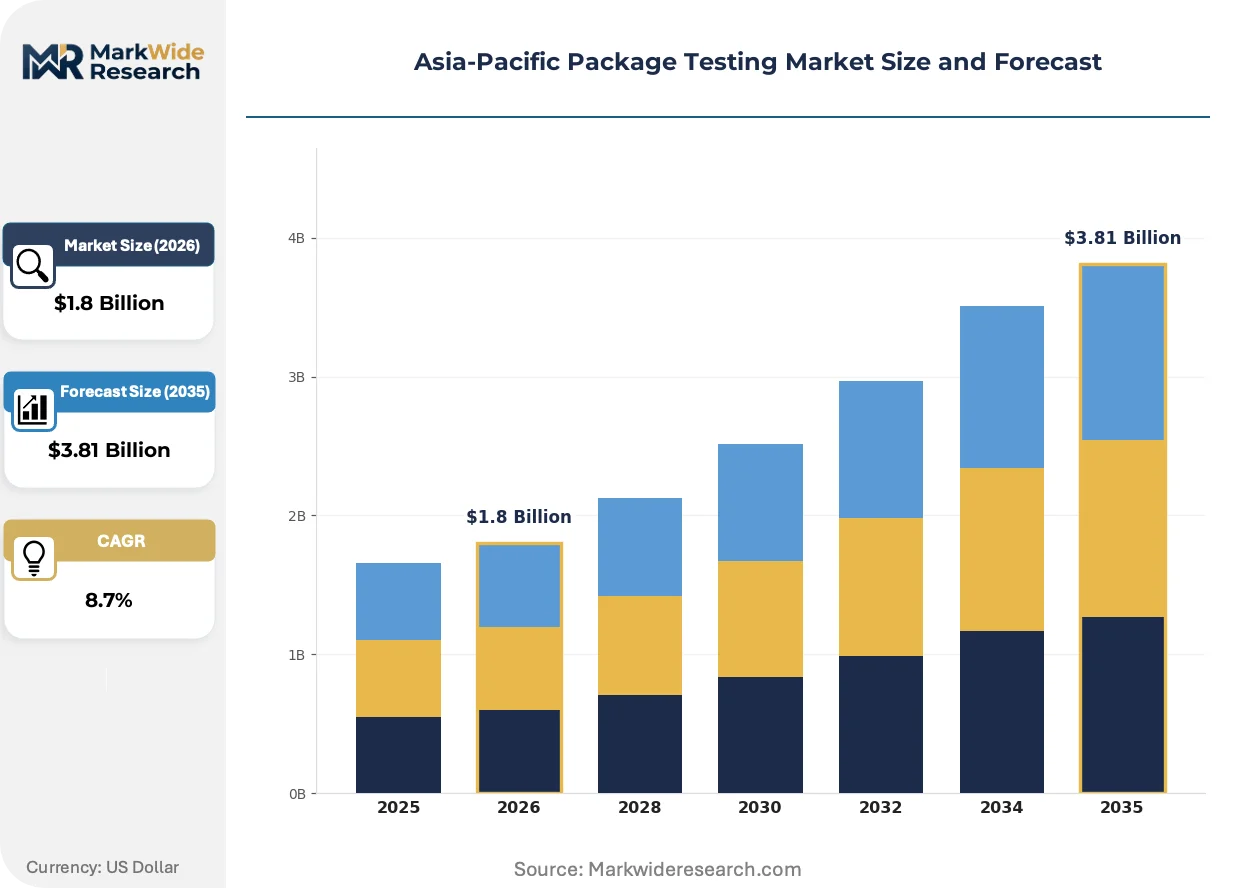
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Drop Test, Vibration Test, Compression Test, Shock Test Material Type: Plastic, Glass, Metal, Paperboard End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | SGS S.A., Intertek Group Plc, DDL, Inc., CSZ Testing Services Laboratories, CRYOPAK, Bureau Veritas, TÜV SÜD, Advance Packaging, Nefab, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Package Testing Market Strategic Shifts
Digital twin simulation and sensor-embedded packaging are compressing the traditional test-certify-ship cycle, enabling predictive failure modeling before physical prototypes enter laboratories.
Automated robotic drop testing is overtaking manual drop tower protocols in high-volume e-commerce certification labs. Chinese third-party logistics providers now mandate robotic repeatability for supplier onboarding. This standardization is compressing inter-lab result variance and enabling centralized audit trails for cross-border shipments.
China's SAMR enforcement of updated GB/T 4857 transport packaging standards tightens compression test acceptance criteria for electronics exports. Korean battery manufacturers serving European EV supply chains must now dual-certify against both GB and REACH-aligned protocols. The compliance burden falls heaviest on mid-tier contract packagers lacking in-house regulatory mapping capabilities.
Brand procurement teams now bundle packaging testing with sustainability verification, collapsing what were separate vendor relationships. Australian retailers and Japanese consumer electronics OEMs lead this consolidation, issuing unified RFPs for performance testing and carbon footprint validation. The practice is visible most acutely in Melbourne and Tokyo metropolitan sourcing offices.
Asia-Pacific Package Testing Market Segmentation
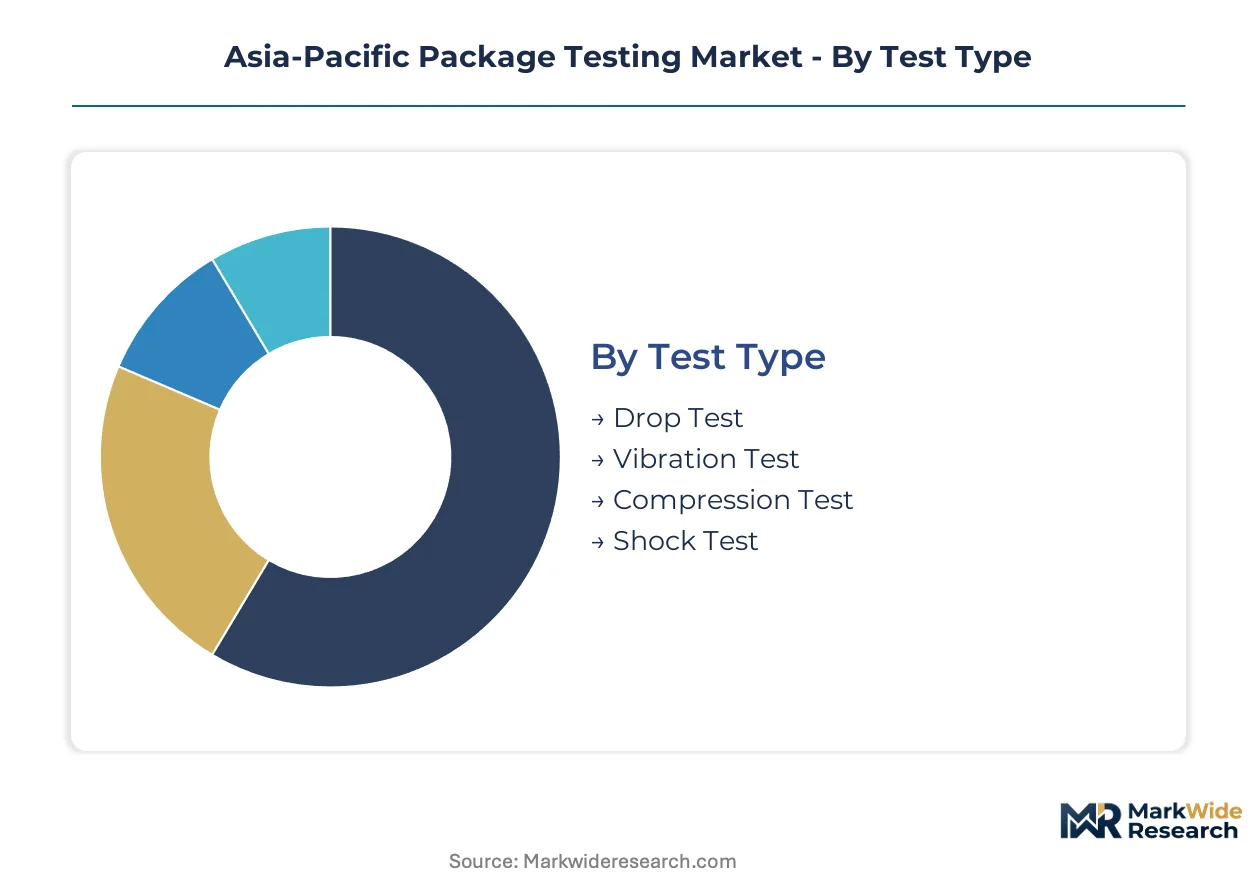
Package testing demand across Asia-Pacific fragments across four analytical dimensions, each mapping to distinct procurement patterns and certification requirements. Test type segmentation reveals volume-driven commoditization alongside premium pharmaceutical protocols. Material and end-user splits expose sustainability-driven substitution effects reshaping laboratory service mixes.
Test Type:
Drop test and vibration test dominate transaction volumes across e-commerce fulfillment networks, while shock test commands premium pricing from cold-chain pharmaceutical validation.
- Drop Test:Simulates free-fall impacts from handling heights typical of last-mile distribution. Demand concentrates in Indonesia and Vietnam as corrugated durability requirements tighten under humid climate stress.
- Vibration Test:Replicates multi-modal transit spectra across road, rail, and sea corridors. Electronics exporters in China's Pearl River Delta drive standardization as SAMR enforces updated GB/T 4857 protocols.
- Compression Test:Evaluates stack-load resistance under warehouse storage conditions.
- Shock Test:Validates biologic and vaccine distribution systems against thermal-mechanical stress.
Today's leader: Drop Test. Tomorrow's challenger: Shock Test.
Material Type:
Plastic retains volume dominance in electronics cushioning, while paperboard climbs fastest on fiber substitution mandates under China's MEE guidelines and Japan's METI recycling frameworks.
- Paperboard:Compression and moisture-resistance testing accelerates as brands substitute fiber-based alternatives for plastic compliance. Australian retailers now bundle performance testing with recyclability verification in unified procurement.
- Plastic:Remains entrenched in shock-absorbing inserts and sterile barrier systems. Korean battery manufacturers serving European EV supply chains must dual-certify against GB and REACH-aligned protocols.
- Glass:Fragility assessment concentrates in pharmaceutical primary packaging.
- Metal:Corrosion resistance protocols serve aerosol and processed food segments.
Paperboard expands most quickly; plastic defends incumbent position through specialized barrier applications.
End User:
Pharmaceutical end users extract premium pricing for cold-chain validation, while electronics and food & beverage segments compete on throughput speed and cost per test.
- Pharmaceuticals:CDSCO and TGA therapeutic goods approvals require parallel packaging validation, stretching laboratory queue management systems. India's PLI scheme consolidates domestic certification infrastructure for export-ready biologics.
- Electronics:Compression test acceptance criteria tightened under SAMR enforcement for exports. Robotic drop testing standardization now mandated by Chinese third-party logistics providers for supplier onboarding.
- Food & Beverage:Shelf-life extension drives accelerated aging protocol demand.
- Cosmetics:Premium positioning requires aesthetic integrity validation under transit stress.
Pharmaceuticals capture margin; electronics capture volume.
Distribution Channel:
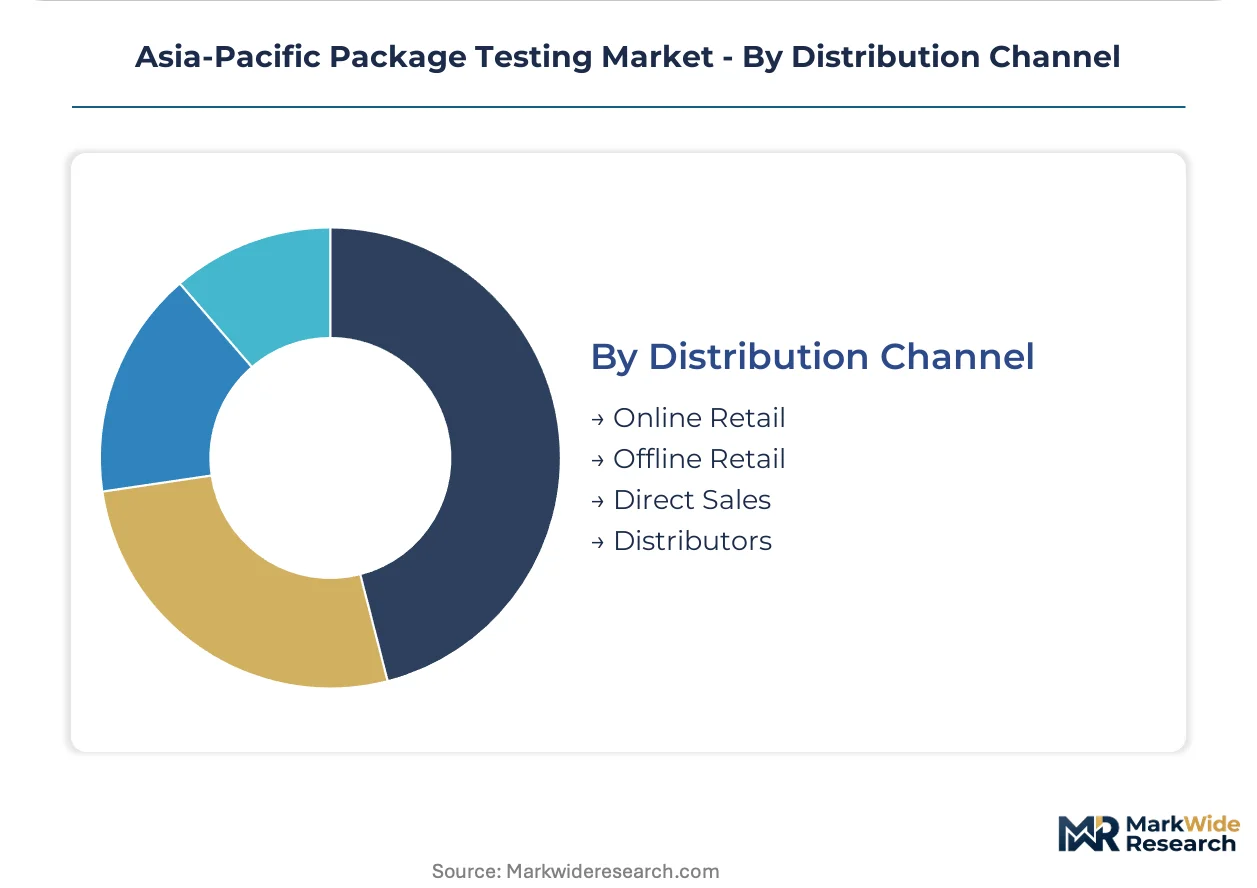
Direct sales anchor pharmaceutical and electronics certification relationships, while distributors aggregate fragmented demand from mid-tier food and cosmetics brands.
- Direct Sales:Laboratory networks like SGS and Intertek maintain dedicated account teams for pharmaceutical cold-chain validation. Long-term contracts specify ISO 17025 accreditation and regulatory mapping capabilities.
- Distributors:Aggregate testing demand from mid-tier contract packagers lacking in-house regulatory expertise. Bureau Veritas competes aggressively through electronics packaging compliance bundling.
- Online Retail:Digital procurement platforms emerging for standardized test requisitions.
- Offline Retail:Traditional laboratory walk-in services persist for small-batch cosmetics validation.
Direct sales deepen; distributors broaden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Package testing infrastructure in Asia-Pacific traces its modern lineage to post-war Japanese industrial standardization, which subsequently diffused through South Korean electronics manufacturing and China's export-oriented growth corridors. Today's regional map reflects this inherited technical hierarchy while incorporating new capacity centers in India and Southeast Asia.
China
Electronics exports from the Pearl River Delta and Yangtze River Delta drive vibration and compression test volumes as SAMR enforces updated GB/T 4857 transport packaging standards. The country's dual carbon goals under MEE guidelines accelerate fiber-based packaging substitution, expanding paperboard moisture-resistance testing demand. Shanghai and Shenzhen host the densest laboratory clusters serving Korean battery manufacturers requiring dual GB-REACH certification.
Japan
Pharmaceutical cold-chain validation commands premium pricing as PMDA therapeutic goods guidelines mandate parallel packaging approval processes. METI packaging recycling guidelines consolidate sustainability-driven testing demand across consumer electronics and food sectors. The Kanto corridor around Tokyo maintains regional leadership in multi-modal simulation capabilities and ISO 17025-accredited biologics validation.
India
PLI scheme incentives for pharmaceuticals and electronics compress lead times for export-ready packaging certification as domestic testing infrastructure expands. CDSCO therapeutic goods approvals require parallel validation, stretching laboratory queue management systems in Maharashtra and Gujarat. Hyderabad and Bengaluru clusters concentrate cold-chain validation capacity for biologic contract manufacturing.
South Korea
Battery manufacturers serving European EV supply chains drive dual-certification demand against GB and REACH-aligned protocols. MFDS pharmaceutical guidelines and electronics export requirements sustain premium-margin testing segments. The Seoul Capital Area and Busan-Ulsan corridor anchor specialized climatic chamber capacity for temperature-sensitive automotive component validation.
Australia
TGA therapeutic goods guidelines and EPR frameworks mandate recyclability verification, opening material integrity testing for molded fiber alternatives. Retail procurement teams in Melbourne and Sydney bundle performance testing with carbon footprint validation. The country's geographic isolation sustains dedicated sea-air-road multi-modal simulation requirements distinct from intra-Asian corridors.
Asia-Pacific Package Testing Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification complexity and regulatory mapping capabilities. The market structure consolidates around three laboratory networks with ISO 17025 accreditation breadth, while mid-tier regional specialists compete on geographic proximity and sector-specific turnaround speed. Strategic archetypes include: (1) full-service multinationals with pharmaceutical cold-chain dominance, (2) electronics-focused compliance specialists with robotic testing standardization, and (3) sustainability-verification bundlers capturing procurement consolidation trends. Dominant competitive moves center on accreditation expansion into underpenetrated ASEAN pharmaceutical corridors and technology convergence partnerships integrating IoT sensor data with laboratory simulation protocols.
Within the full-service multinational tier, SGS S.A. and Intertek Group Plc exemplify archetypes differentiated by sector emphasis, with the former representing pharmaceutical and food safety certification breadth and the latter anchoring cold-chain validation specialization. Bureau Veritas occupies a position among electronics compliance bundlers competing aggressively on export-market regulatory mapping. These three entities collectively represent the premium-margin tier structure shaping regional competitive dynamics.
| Leading Market Players |
|---|
| SGS S.A. |
| Intertek Group Plc |
| DDL, Inc. |
| CSZ Testing Services Laboratories |
| CRYOPAK |
| Bureau Veritas |
| TÜV SÜD |
| Advance Packaging |
| Nefab |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up laboratory networks in India and Southeast Asia are consolidating testing capacity while compressing turnaround premiums, tightening pricing discipline for mid-tier contract packagers dependent on outsourced validation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical cold-chain certification from e-commerce commodity testing and mid-tier electronics compliance. Price differentiation hinges on ISO 17025 accreditation tier and geographic proximity to manufacturing clusters. Cost compression in the standard tier is intensifying because Chinese third-party logistics providers now mandate robotic testing repeatability for supplier onboarding. E-commerce fulfillment networks exhibit the highest price sensitivity, while biologic vaccine distributors accept premium positioning for thermal-mechanical shock validation.
Supply Chain Analysis
Vibration table and climatic chamber supply rests on German and Japanese OEMs, exposing Indian and Vietnamese laboratories to currency volatility and extended procurement cycles. Equipment sourcing concentrates in Germany, Japan, and the United States, while consumables and calibration standards feed from Singapore and South Korea. Single-source vulnerability in precision instrumentation creates bottlenecks for rapid capacity expansion. Distribution runs through direct manufacturer relationships for accredited laboratories, with distributors serving fragmented mid-tier demand in Indonesia and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's SAMR enforcement of updated GB/T 4857 transport packaging standards and Japan's METI recycling guidelines are accelerating mandatory testing volumes across export corridors.
For Market Incumbents: Anticipate margin compression from robotic testing standardization by Chinese third-party logistics providers by deepening ISO 17025 accreditation breadth into underpenetrated ASEAN pharmaceutical corridors. Defend against emerging sustainability-verification bundlers by integrating IoT-enabled shock loggers with traditional drop-test protocols, creating predictive failure modeling capabilities that commodity laboratories cannot replicate. For New Entrants and Emerging Players: Enter via Thailand and Vietnam where ISO 17025-accredited cold-chain validation labs remain scarce, capturing first-mover positioning as regional biologic contract manufacturing expands. Target pharmaceutical corridors requiring parallel CDSCO and TGA therapeutic goods packaging approval, leveraging regulatory mapping expertise as the primary go-to-market wedge against established multinational networks. For Investors and Strategic Acquirers: Testing equipment manufacturers serving laboratory networks are the most active acquirer in this space, seeking captive demand channels as German and Japanese OEMs face pricing pressure from regional capacity buildouts. Long-term viability rests on technology convergence plays integrating real-world transit sensor data with laboratory simulation protocols. Watch for Japan's METI packaging recycling guideline enforcement tightening as the signal indicating accelerated fiber-based substitution demand and material integrity testing volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Expansion into ASEAN Pharmaceutical Corridors | Thailand and Vietnam lack ISO 17025 cold-chain labs, creating first-mover positioning for regional networks. |
| Technology Convergence Partnerships | Integration of IoT shock loggers with drop-test protocols enables predictive failure modeling before physical prototyping. |
| Robotic Testing Standardization | Chinese third-party logistics providers now mandate automated repeatability, compressing inter-lab result variance. |
| Sustainability Verification Bundling | Australian retailers and Japanese OEMs issue unified RFPs for performance testing and carbon footprint validation. |
| Domestic Infrastructure Investment | India's PLI scheme compresses lead times for export-ready certification as Hyderabad and Bengaluru clusters expand. |
Study Parameters
Direct dialogue with laboratory operations directors, pharmaceutical packaging engineers, regulatory affairs managers at CDSCO and TGA, and procurement leads at Chinese third-party logistics providers grounded qualitative insights. Secondary validation drew from SAMR GB standards filings, METI recycling guideline enforcement notices, BIS certification databases, and customs trade data for vibration table and climatic chamber imports. Bottom-up test volume estimates triangulated against top-down regional manufacturing output projections.
Bottom-up modeling aggregated test transaction volumes by type, material, and end-user segment across the projection horizon, while top-down analysis calibrated against regional export manufacturing growth and regulatory enforcement intensity. Segmentation dimensions included test type, material substitution trajectory, end-user industry, and geographic regulatory cluster. CAGRs derived from correlated regression against pharmaceutical cold-chain expansion, e-commerce fulfillment density, and fiber-based packaging substitution mandates. Industry-specific inputs incorporated PLI scheme incentive disbursement patterns and dual carbon goal enforcement timelines.
The model holds under sustained regulatory enforcement of GB, JIS, and TGA standards; deviation in trade policy fragmentation or accelerated equipment localization in India would shift laboratory capacity expansion trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Pack Testing Machines Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Packaging Testing Equipment Market