
 Pre-Validated Packaging Market | 2026-2036
Pre-Validated Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Validated Packaging Market Analytics
Qualified cleanroom technician availability is collapsing across European and North American manufacturing hubs, forcing converters to automate validation workflows or lose contract renewals. Amcor leverages its integrated film extrusion and thermoforming footprint to control pouch supply for sterile drug products. Gerresheimer anchors glass vial pre-validation through dedicated ISO 15378-certified plants in Germany and India. West Pharmaceutical Services dominates elastomeric closure integration, a capability few competitors replicate at equivalent scale.
Pre-validated packaging denotes primary containers and secondary barrier systems that have undergone sterilization, particulate testing, and container closure integrity verification prior to receipt by the drug product manufacturer, typically supplied with certificates of analysis and irradiation dose mapping. These systems eliminate in-house validation cycles for biologics, vaccines, and cell therapies where sterility assurance levels of 10^-6 are mandatory. Glass vials and sterile bags command the deepest margin pools due to biologics' sensitivity to extractables and the capital intensity of depyrogenation tunnels. Blister packs lead volume in solid-dose pharmaceuticals, though polyethylene and polypropylene pouches are gaining fastest in prefilled syringe and wearable injector formats.
FDA cGMP regulations and the EU MDR framework enforce traceable validation documentation for every lot released to pharmaceutical customers, creating compliance moats for certified converters. ISO 13485 and CE marking requirements filter out regional packaging suppliers lacking quality management infrastructure, concentrating procurement among multi-site validated players. Stakeholders must monitor how USP <1207> revisions on deterministic leak testing reshape acceptance criteria for sterile barrier systems.
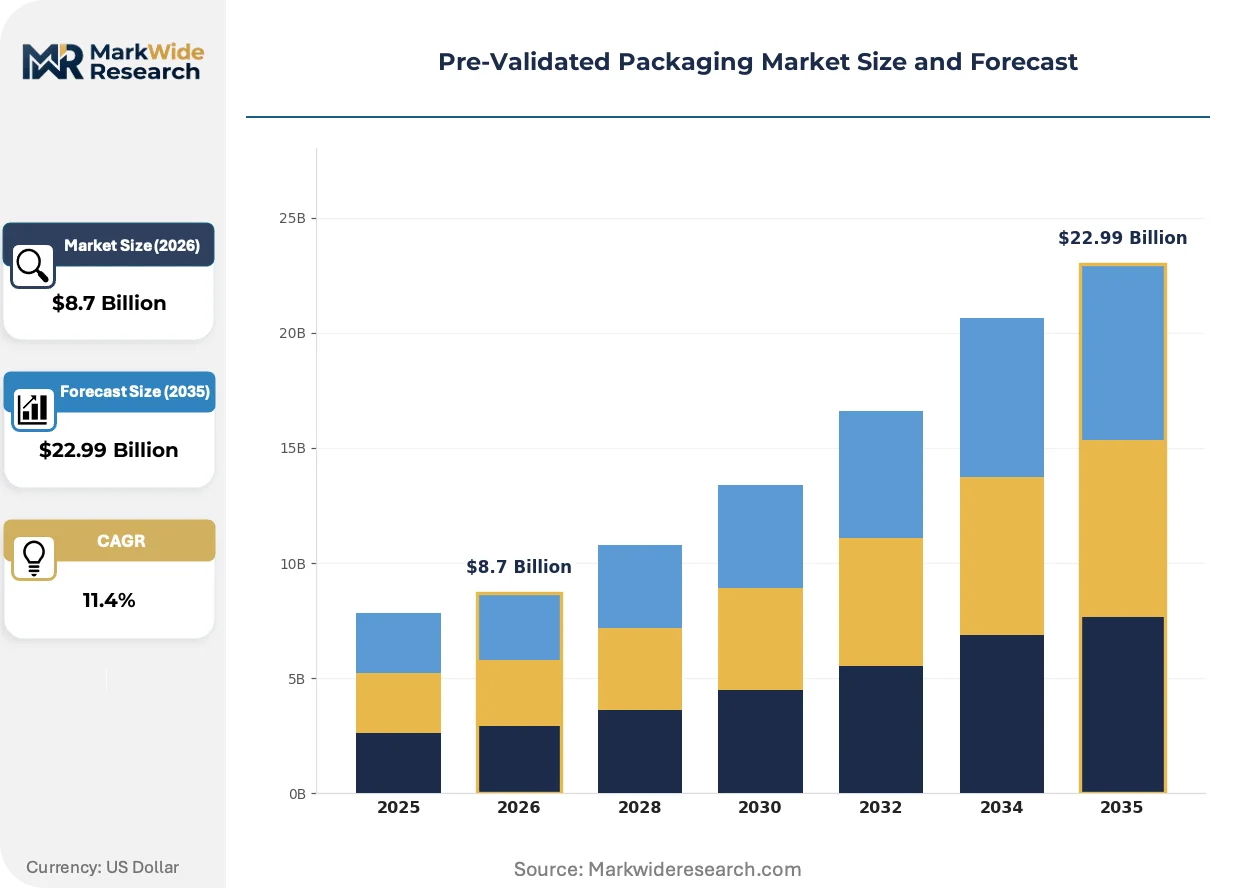
Market Dynamics
Pre-validated packaging supply chains are compressing validation timelines through deterministic leak testing adoption, as biologics manufacturers eliminate redundant in-house sterility verification cycles to accelerate cell therapy commercialization.
Growth Catalysts
- EU MDR traceability mandates:The EU Medical Device Regulation forces pharmaceutical firms toward pre-certified sterile barrier systems with lot-level documentation, eliminating supplier qualification overhead for Class III drug-device combinations.
- Cell therapy manufacturing expansion:Autologous and allogeneic cell therapy producers require ISO 15378-certified primary containers with irradiation dose mapping, creating dedicated demand for pre-validated glass vials and polymer bags.
- Rhine-Main cluster outsourcing:Germany's pharmaceutical contract manufacturing concentration is driving regional demand for ready-to-use sterile containers with certificates of analysis, accelerating fill-finish automation adoption.
Market Restraints
- Depyrogenation tunnel capital intensity:Glass vial pre-validation requires continuous thermal processing equipment exceeding standard converter capex thresholds, limiting supplier entry.
- Ethylene oxide sterilization capacity concentration:Sterilization service providers cluster in specific industrial zones, creating geographic single-point-of-failure exposure for just-in-time supply chains.
- Elastomeric formulation IP lock-in:West Pharmaceutical Services and select competitors control proprietary closure compound recipes, constraining alternative sourcing for high-value biologics applications.
Strategic Opportunities
- Prefilled syringe wearable integration:Combination product manufacturers seek pre-validated polymer pouches with integrated needle safety systems, opening design partnerships between packaging converters and device engineers.
- ISO 13485 certification arbitrage:Mid-scale converters in Eastern European manufacturing zones can capture contract manufacturing organization procurement by achieving quality management certification faster than incumbent players.
- Deterministic leak testing equipment convergence:Vacuum decay and laser-based headspace analysis technologies are merging, enabling converters to offer dual-method validation documentation that satisfies both USP and EP requirements.
Industry Challenges
- Qualified cleanroom technician scarcity:ISO 14644-1 Class 7 and Class 8 facility operations require certified personnel that European and North American labor markets cannot supply at replacement rates.
- Legacy ERP integration friction:Pre-validated packaging lot tracking systems must interface with customer SAP and Oracle environments, creating implementation delays and data mapping errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Validated Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Sterile Bags, Pouches, Vials Material: Glass, Polyethylene, Polypropylene, Aluminum Application: Pharmaceuticals, Medical Devices, Biotechnology, Diagnostics Certification: ISO 13485, CE Mark, GMP Compliance, FDA Approved |
| Companies Covered | Amcor, Gerresheimer, West Pharmaceutical Services, AptarGroup, Schott Pharma, Stevanato Group, Berry Global, SGD Pharma, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Validated Packaging Market Evolving Landscape
Pre-validated packaging is undergoing material substitution and testing methodology transformation, with polymer systems encroaching on glass dominance and deterministic methods replacing probabilistic sterility assurance approaches.
Cyclic olefin polymer and cyclic olefin copolymer pre-filled syringe barrels are displacing borosilicate glass for protein-based biologics, as Amcor and Becton Dickinson scale extrusion-thermoforming capacity. Biologics manufacturers in Switzerland and Massachusetts are specifying these materials for wearable injector applications where breakage risk and weight reduction drive specification changes. Glass retains margin concentration in lyophilized products, but polymer is capturing growth in liquid-dose prefilled formats.
FDA's updated container closure integrity guidance is mandating deterministic leak test methods for sterile barrier systems, rendering probabilistic dye ingress and bubble emission tests insufficient for new drug applications. The guidance compresses validation documentation timelines for converters while forcing pharmaceutical firms to retest legacy packaging configurations. Parenteral drug manufacturers in the United States are responding by consolidating supplier bases around converters with in-house vacuum decay and high-voltage leak detection capabilities.
Certificate-of-analysis-driven procurement is consolidating buying power among multi-site biologics manufacturers, who now demand irradiation dose mapping and particulate testing documentation with every lot. Contract manufacturing organizations are displacing in-house packaging qualification teams, outsourcing sterility assurance to specialized converters. This pattern is most pronounced in Germany's pharmaceutical manufacturing corridor and the Boston-Cambridge biotech cluster, where fill-finish capacity constraints push validation risk upstream.
Pre-Validated Packaging Market Segmentation
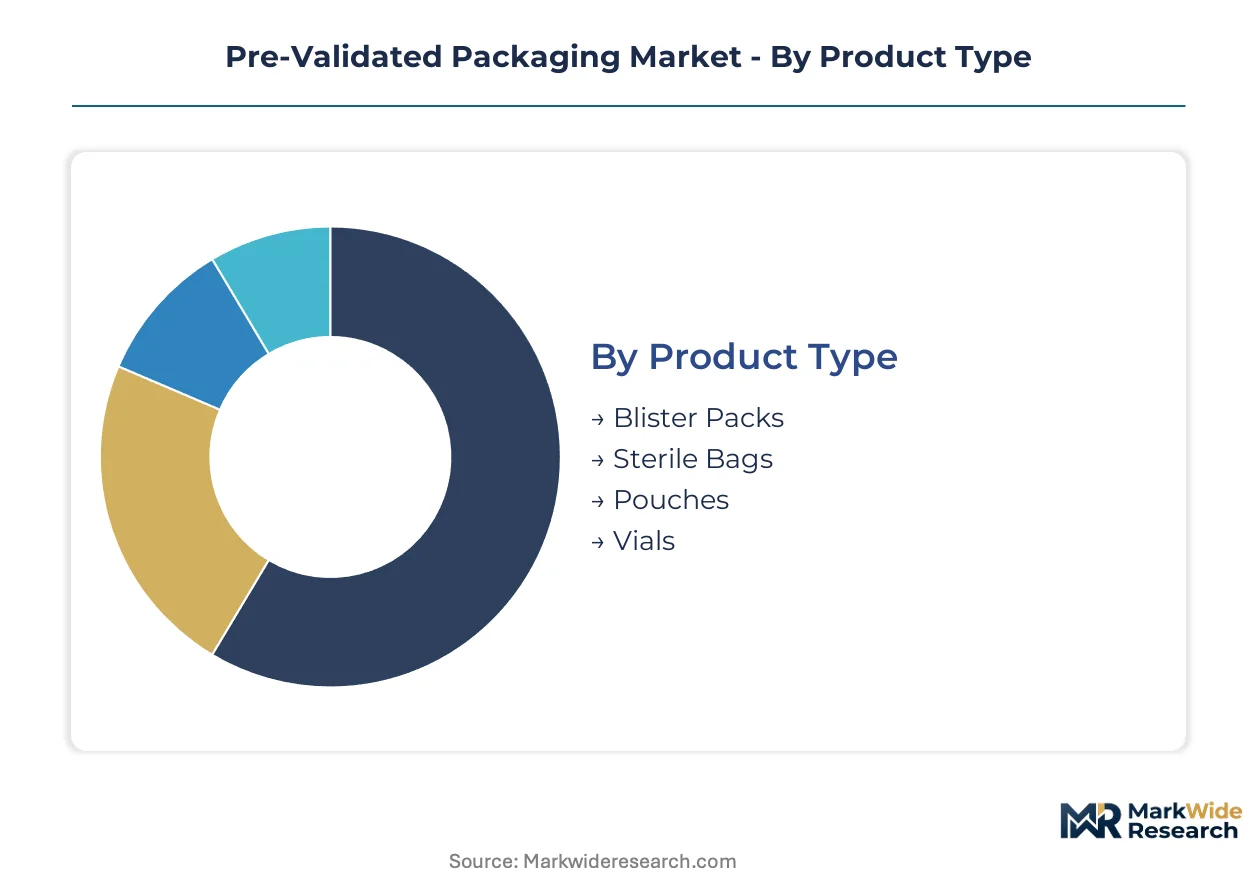
Pre-validated packaging procurement channels diverge sharply by sterility assurance requirements and regulatory complexity. Glass vials and sterile bags flow through specialized biologics distributors with ISO 15378-certified warehousing, while blister packs and pouches reach pharmaceutical manufacturers through broader industrial supply networks. Understanding these channel dynamics enables converters to align certification investments with customer access patterns.
Product Type:
Channel strategy varies by container complexity, with high-sterility formats requiring dedicated cold-chain logistics and certificate-of-analysis documentation at every handoff.
- Vials:Borosilicate and tubular glass containers undergo depyrogenation and sterile barrier packaging before release. Demand concentrates in Germany's Rhine-Main pharmaceutical cluster for fill-finish outsourcing of cell therapies and vaccines, where ISO 15378-certified supply with irradiation dose mapping is non-negotiable.
- Sterile Bags:Multi-layer polymer films with welded seams provide flexible containment for bioreactor harvests and bulk drug substance storage. Massachusetts and Switzerland biologics manufacturers specify these for wearable injector applications where breakage risk and weight reduction override glass preferences.
- Pouches:Polyethylene and polypropylene laminates serve secondary barrier functions for prefilled syringes and combination products.
- Blister Packs:Thermoformed cavities with lidding foil dominate solid-dose oral pharmaceuticals.
Vials dominate installed base. Sterile bags are where expansion concentrates.
Material:
Cost tier stratification separates premium borosilicate formulations from commodity polymer grades, with aluminum occupying a mid-tier niche for moisture-sensitive applications.
- Glass:Type I borosilicate and treated soda-lime compositions deliver inert surfaces for parenteral biologics. Lyophilized products in Germany and India command the deepest margin pools due to extractables sensitivity and capital-intensive depyrogenation tunnel requirements.
- Polypropylene:Cyclic olefin polymer and copolymer variants displace glass in protein-based liquid doses. Amcor and Becton Dickinson extrusion-thermoforming capacity scales are capturing prefilled syringe specifications where breakage risk drives material substitution.
- Polyethylene:Low-density and linear-low formulations provide flexible film structures for secondary barriers.
- Aluminum:Cold-form foil and strip pack laminates deliver absolute moisture and light protection.
Glass commands premium pricing tiers. Polypropylene is climbing the fastest.
Application:
Customer type determines validation depth, with biotechnology firms demanding lot-level documentation that medical device manufacturers often delegate to contract sterilization providers.
- Biotechnology:Autologous and allogeneic cell therapy producers require ISO 15378-certified primary containers with deterministic leak testing validation. The Boston-Cambridge cluster's fill-finish capacity constraints push sterility assurance risk upstream to specialized converters.
- Pharmaceuticals:Traditional small-molecule parenteral and oral dosage manufacturers balance regulatory compliance against procurement efficiency. EU MDR traceability mandates are consolidating supplier bases around multi-site validated players with integrated quality management systems.
- Medical Devices:Class III drug-device combinations leverage pre-certified sterile barrier systems to eliminate supplier qualification overhead.
- Diagnostics:In-vitro reagent containment emphasizes shelf-life stability over parenteral sterility assurance levels.
Pharmaceuticals anchor volume demand. Biotechnology shows the steepest expansion trajectory.
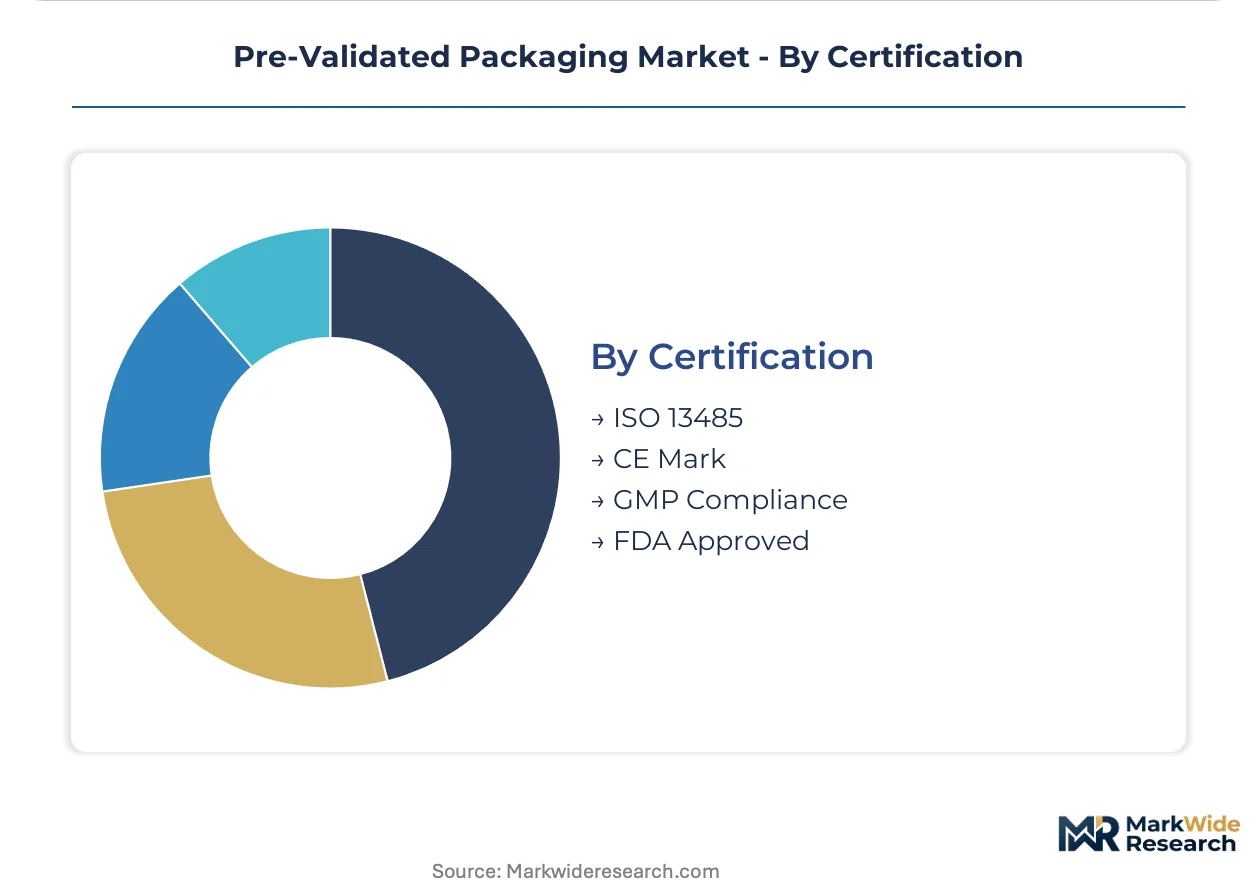
Certification:
Geographic regulatory scope creates tiered market access, with FDA and EU MDR dual certification unlocking the broadest customer bases while single-market approvals constrain growth ceilings.
- ISO 13485:Medical device quality management certification filters out regional packaging suppliers lacking infrastructure for traceable documentation. Eastern European manufacturing zones present arbitrage opportunities for mid-scale converters achieving certification faster than incumbent players.
- FDA Approved:cGMP compliance and container closure integrity guidance adherence enable supply to US biologics manufacturers. Updated USP less-than-1207-greater-than revisions on deterministic leak testing are reshaping acceptance criteria for sterile barrier systems.
- CE Mark:EU MDR conformity assessment permits placement on the European Economic Area market.
- GMP Compliance:General pharmaceutical manufacturing practice certification satisfies baseline regulatory expectations.
ISO 13485 gates market entry. FDA approval is where procurement premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's updated container closure integrity guidance anchors demand concentration in the United States, while EMA traceability mandates and Germany's fill-finish outsourcing expansion reshape European procurement patterns across multiple industrial clusters.
United States
Biologics manufacturers in Massachusetts and California are accelerating adoption of ready-to-use sterile containers for cell therapy commercialization. FDA cGMP regulations enforce traceable validation documentation for every lot released. The Boston-Cambridge cluster's fill-finish capacity constraints push sterility assurance risk upstream to specialized converters with in-house deterministic leak testing capabilities.
Germany
The Rhine-Main pharmaceutical cluster is driving regional demand for ready-to-use sterile containers with certificates of analysis. EU MDR traceability mandates force pharmaceutical firms toward pre-certified sterile barrier systems with lot-level documentation. Contract manufacturing organizations in Hesse and Bavaria are displacing in-house packaging qualification teams, outsourcing validation to ISO 15378-certified suppliers.
Switzerland
Biologics manufacturers specify cyclic olefin polymer pre-filled syringe barrels for wearable injector applications where breakage risk and weight reduction override glass preferences. Swissmedic regulations align with EU MDR conformity assessment requirements. The Basel pharmaceutical manufacturing corridor concentrates procurement among multi-site validated players with integrated quality management systems.
India
CDSCO's tightening sterility assurance standards for parenteral drug exports are pushing contract manufacturers toward pre-validated primary containers. The country's national pharmaceutical regulator is harmonizing with FDA and EMA guidance on container closure integrity. ISO 15378-certified plants in Gujarat and Maharashtra are capturing outsourcing demand from European and North American biologics firms.
Japan
PMDA's emphasis on deterministic leak testing methods is reshaping acceptance criteria for sterile barrier systems in new drug applications. METI's quality infrastructure investments support converter certification upgrades. The Kanto region's pharmaceutical manufacturing base is consolidating supplier relationships around converters with dual-method validation documentation satisfying both USP and EP requirements.
Pre-Validated Packaging Market Competitive Landscape
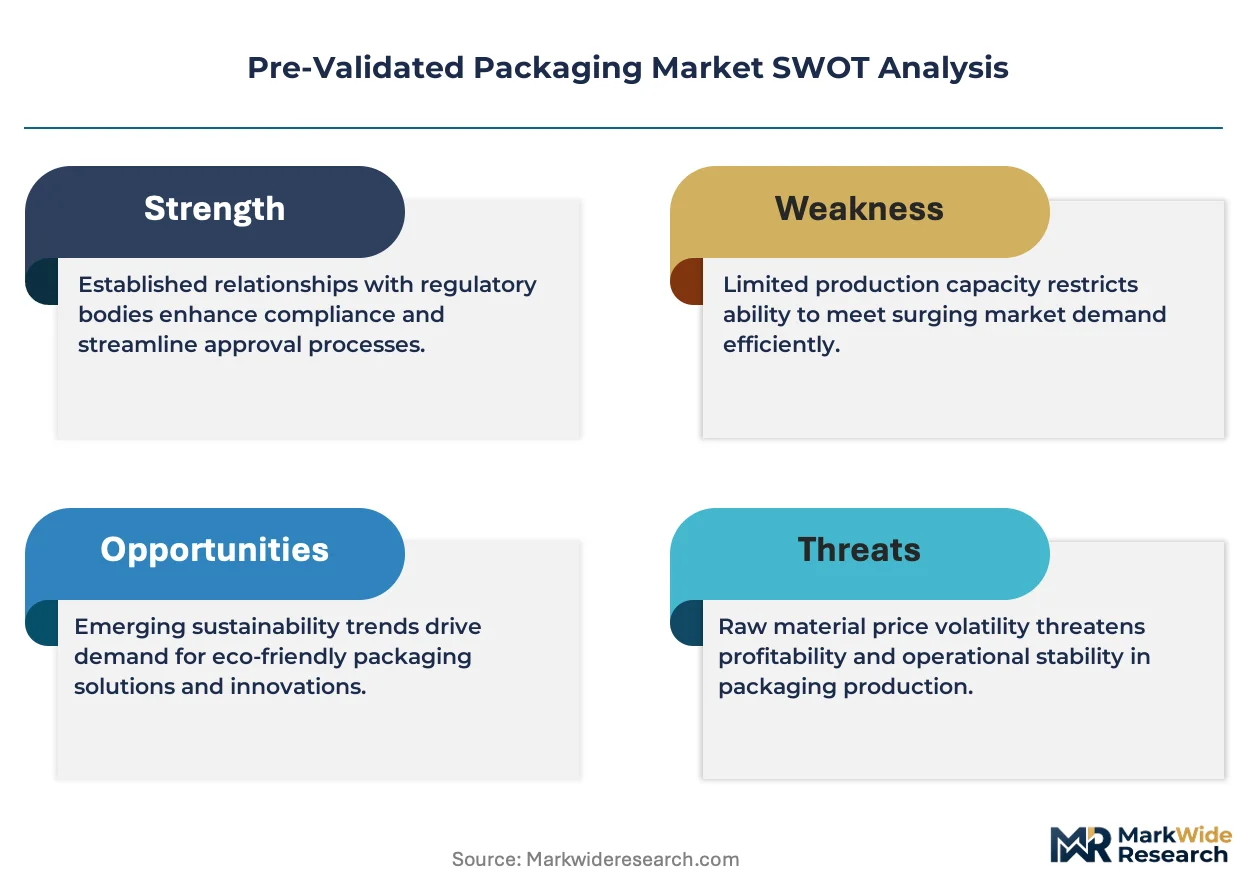
A small set of integrated leaders sits above a broader specialist tier, with the market exhibiting concentrated supply-side dynamics around sterilization capacity and elastomeric formulation IP. Glass vial pre-validation requires continuous thermal processing equipment exceeding standard converter capex thresholds, filtering entry to established multi-site operators. Two strategic archetypes dominate: integrated film-to-container converters controlling extrusion and thermoforming footprints, and specialized closure compounders with proprietary elastomeric recipes. Competitive moves center on deterministic leak testing equipment convergence and ISO 13485 certification arbitrage in emerging manufacturing zones.
Among the integrated packaging converters, Amcor exemplifies the film extrusion-to-sterile-container archetype through its control of pouch supply chains for drug products. Gerresheimer occupies a position within the glass primary container tier, with name-embedded geographic anchoring in Germany. West Pharmaceutical Services represents the elastomeric closure integration specialist archetype, a capability configuration few competitors replicate at equivalent scale. These three entities anchor the premium-tier competitive structure while mid-scale converters in Eastern European manufacturing zones pursue certification arbitrage to capture contract manufacturing organization procurement.
| Leading Market Players |
|---|
| Amcor |
| Gerresheimer |
| West Pharmaceutical Services |
| AptarGroup |
| Schott Pharma |
| Stevanato Group |
| Berry Global |
| SGD Pharma |
| Nipro Corporation |
| Others |
Value Network & Pricing Analysis
Cyclic olefin polymer substitution for borosilicate glass in prefilled syringe applications simultaneously relocates manufacturing gravity toward Amcor and Becton Dickinson's extrusion-thermoforming hubs in Switzerland and Massachusetts while compressing margin premiums historically captured by German and Indian glass converters with captive depyrogenation tunnels.
Pricing Analysis
Glass vials for lyophilized biologics command 40-60% premiums over polymer alternatives in Germany's Rhine-Main cluster, where ISO 15378 certification and irradiation dose mapping documentation create tiered pricing stratification across premium certified, standard GMP-compliant, and economy unvalidated tiers. Price differentiation hinges on deterministic leak testing capability and FDA submission support, with biotechnology firms showing lowest price sensitivity due to sterility assurance failure costs. Pricing pressure stems from qualified cleanroom technician scarcity forcing automation capex absorption by converters.
Supply Chain Analysis
Just-in-time inventory strategies dominate biologics procurement in Massachusetts and California, though Germany's contract manufacturing organizations are building strategic stockpiles of pre-validated glass vials to mitigate ethylene oxide sterilization capacity concentration in specific industrial zones. Supply concentrates in Germany, India, and Switzerland for glass primary containers, while polymer film extrusion anchors in the United States and Western Europe. Raw material dependencies include borosilicate tubing, cyclic olefin resins, and halobutyl elastomer compounds. Single-source vulnerability runs through West Pharmaceutical Services' proprietary closure formulation IP. Distribution runs through ISO 15378-certified specialized distributors with cold-chain capabilities for high-sterility formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-validated packaging sits at an inflection where FDA's deterministic leak testing mandate eliminates probabilistic methods, creating winner-take-most dynamics among converters with capital-intensive validation infrastructure.
For Market Incumbents: Compound certification moats by accelerating ISO 13485 audits in Eastern European manufacturing zones before mid-scale competitors achieve quality management infrastructure. Deepen backward integration into cyclic olefin polymer resin supply to defend margin position against Amcor's extrusion-thermoforming scale. Prioritize deterministic leak testing equipment convergence offering dual-method validation satisfying both USP and EP requirements. For New Entrants and Emerging Players: Anchor in prefilled syringe wearable integration partnerships where combination product manufacturers seek polymer pouches with needle safety systems, a white space lacking established converter-device engineering alliances. Target contract manufacturing organization procurement in Germany's Rhine-Main cluster where fill-finish outsourcing displaces in-house packaging qualification teams. Pursue ISO 15378 certification arbitrage by achieving validation standards faster than incumbent multi-site players. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized converters with captive sterilization capacity and elastomeric formulation IP. Long-term viability over the next decade hinges on deterministic testing equipment ownership rather than outsourced validation services. Acquisition targets should demonstrate integrated film-to-container capabilities or proprietary closure compound recipes. Watch for PMDA harmonization with FDA container closure integrity guidance as the signal indicating accelerated Japanese market access premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Deterministic Leak Testing Equipment Convergence | Vacuum decay and laser headspace analysis merger satisfies dual USP and EP documentation requirements for sterile barrier systems. |
| ISO 13485 Certification Arbitrage | Eastern European mid-scale converters capture CMO procurement by achieving quality infrastructure faster than incumbent players. |
| Backward Integration into Cyclic Olefin Resins | Converters securing captive polymer supply defend margin compression from glass-to-polymer material substitution trends. |
| Prefilled Syringe Wearable Partnerships | Device-engineering alliances open design control for combination products requiring integrated needle safety systems. |
| Ethylene Oxide Sterilization Capacity Expansion | Geographic diversification mitigates single-point-of-failure exposure in concentrated industrial sterilization zones. |
Research Methodology
A standing panel of fill-finish operations directors, regulatory affairs managers at biologics manufacturers, cleanroom facility engineers, and pharmaceutical procurement leads provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA cGMP guidance documents, EMA MDR conformity assessment databases, ISO 15378 certification registries, and USP container closure integrity revision notices. Bottom-up demand modeling triangulated against top-down supply capacity assessments across converter manufacturing footprints.
Consistency checks validated volume and value outputs against external benchmarks including customs data for sterile barrier system imports, capital expenditure disclosures from listed packaging converters, and fill-finish capacity expansion announcements from contract manufacturing organizations. Segmentation modeling spanned product type, material substitution trajectories, certification tier, and regional regulatory cluster. CAGRs derived from sterilization capacity buildout timelines and biologics pipeline advancement rates.
Decision-makers should treat outputs as directional under assumptions of continued FDA enforcement of deterministic testing methods and sustained EU MDR traceability mandates; material deviation would warrant model refresh. Revision becomes warranted when qualified cleanroom technician labor availability or ethylene oxide sterilization capacity constraints cross thresholds forcing sustained automation capex acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Pack Testing Machines Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Packaging Inspection Systems Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Global Package Testing Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Package Testing Silicone Rubber Socket Market