

Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market Insights
Equipment procurement channels for advanced packaging metrology are tilting toward direct partnerships between inspection system vendors and captive foundry packaging divisions. KLA leverages its installed base in wafer-level inspection to extend into post-die-bond X-ray CT workflows. Nordson anchors its position through inline systems that integrate with high-volume flip-chip and fan-out lines. YXLON International specializes in high-resolution computed tomography configurations for failure analysis labs serving automotive-grade chiplet qualification.
Heterogeneous integration and advanced packaging X-ray CT inspection systems employ multi-axis rotational scanning with sub-micron voxel resolution, typically operating at 130-300 kV tube potential, to non-destructively resolve solder microbumps, copper pillar integrity, and through-silicon via fill quality in stacked die assemblies. Computed tomography and microfocus modalities dominate current procurement for 3D IC and MEMS device applications where void detection at 0.5 µm scale determines yield. Inline inspection systems command premium positioning as package manufacturers automate 100% screening of high-bandwidth memory and photonics modules, while desktop systems retain stable demand in research institutes and failure analysis labs performing root-cause investigations.
FDA device-quality frameworks, U.S. export control classifications administered by the Bureau of Industry and Security, and ISO 9001 quality management standards collectively shape equipment certification requirements and market access conditions for inspection system vendors. The U.S. CHIPS Act funding disbursements tie domestic facility construction to provenance-verified metrology toolchains, tightening vendor qualification windows. Stakeholders must monitor how tightening multilateral semiconductor equipment coordination affects serviceability commitments and spare-part logistics for installed CT inspection fleets.
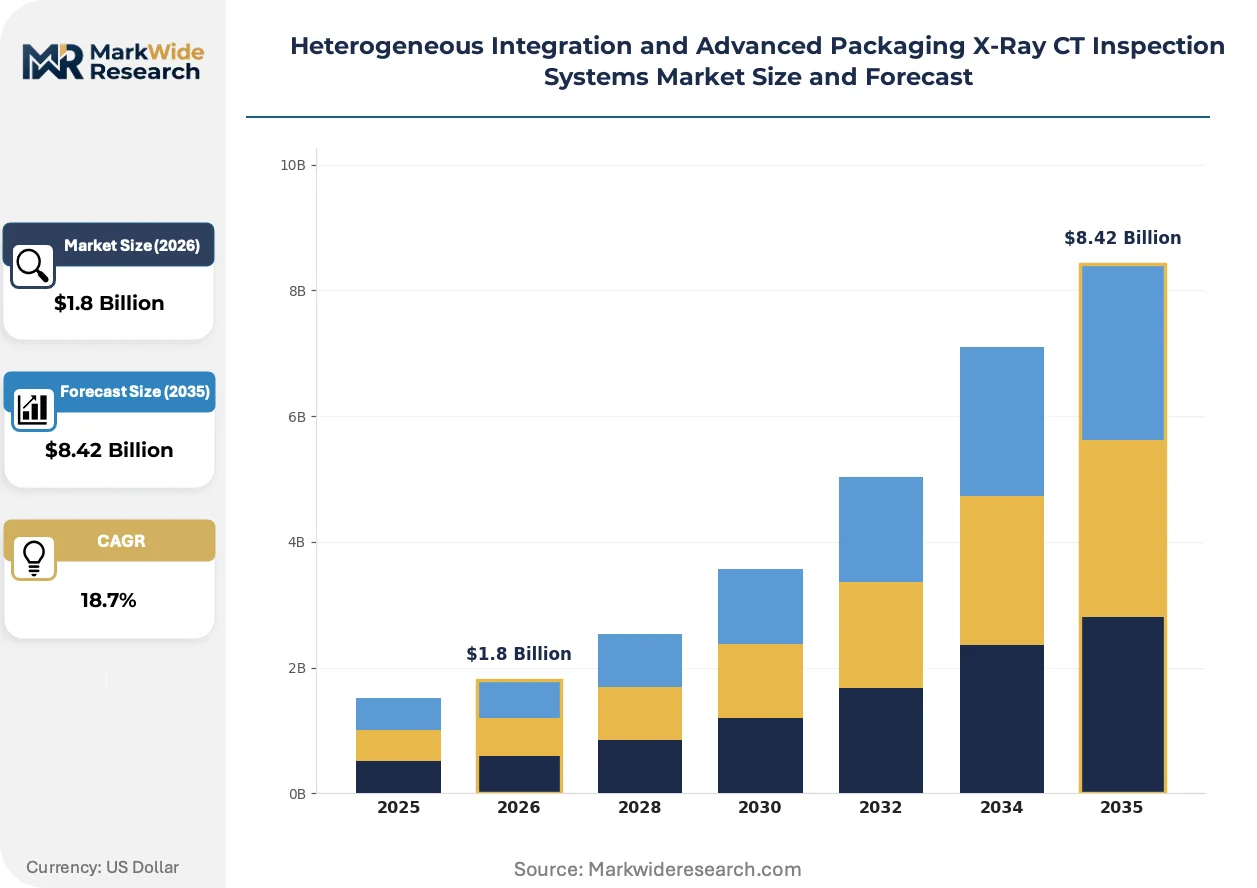
Market Dynamics
The transition from 2.5D interposers to true 3D IC stacking with hybrid bonding is compressing inspection throughput requirements while demanding sub-micron defect detection across ever-thinner die stacks. This structural inflection favors vendors capable of integrating AI-assisted reconstruction with high-speed rotational CT platforms.
Growth Catalysts
- CHIPS Act capital flows:U.S. Bureau of Industry and Security export classifications are channeling facility investment toward provenance-verified metrology infrastructure, accelerating domestic inspection system procurement for captive packaging operations.
- Automotive chiplet qualification:Tier-1 automotive suppliers are mandating 100% X-ray CT screening for high-bandwidth memory modules used in autonomous driving compute platforms, creating dedicated demand for inline inspection lanes.
- Hybrid bonding adoption:Die-to-wafer and wafer-to-wafer bonding with copper-to-copper interfaces requires void-free inspection at bondline interfaces, pulling high-resolution CT into front-end-of-line packaging workflows previously served by optical methods.
Market Restraints
- Tungsten target supply concentration:Microfocus X-ray tube manufacturing depends on tungsten filament and target supplies concentrated in Chinese and Russian refining operations, exposing inspection system producers to input cost volatility and potential supply disruption.
- Detector fab capacity constraints:Flat-panel detector production for CT systems relies on amorphous silicon backplane fabrication capacity shared with medical imaging and flat-display applications, creating allocation bottlenecks during demand surges.
- Technical resolution ceiling:Penetration requirements for stacked memory exceeding 16-high HBM configurations push 300 kV tube potentials against fundamental contrast limits for sub-0.3 µm void detection, constraining yield improvement trajectories.
Strategic Opportunities
- India packaging expansion:PLI scheme disbursements for semiconductor assembly and test facilities in Gujarat and Karnataka are creating greenfield demand for inspection infrastructure without incumbent vendor lock-in.
- Photonics module inspection:Co-packaged optics for AI training clusters require hermetic seal integrity verification and fiber alignment validation, opening adjacent application space beyond traditional IC packaging.
- AI-assisted reconstruction convergence:Deep learning-based artifact reduction and automated defect classification are compressing scan-to-decision timelines, enabling throughput gains that justify premium system pricing against legacy iterative reconstruction platforms.
Industry Challenges
- Multiphysics simulation expertise gap:System architects capable of integrating thermal management, vibration isolation, and precision motion control for sub-micron CT platforms command scarcity premiums, constraining vendor scaling.
- ISO 9001 certification timeline compression:Automotive and medical device end-users are demanding 12-month qualification cycles for new inspection equipment against traditional 18-24 month validation periods, stressing vendor quality engineering capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market Trends and Innovations
Computational methods are displacing hardware-intensive approaches across inspection workflows, while regulatory provenance requirements and buyer consolidation are reshaping vendor-customer relationships. Three developments merit particular attention.
Digital twin architectures for CT system calibration and predictive maintenance are virtualizing traditional field service models. Equipment vendors are deploying remote monitoring platforms that simulate tube degradation and motion system drift before physical failure. This virtualization compresses unplanned downtime and enables subscription-based service revenue, displacing transactional spare parts business.
REACH substance restrictions on lead-containing solders and RoHS recast directives are accelerating transition to pure tin and silver-sintered interconnects in European packaging operations. These materials exhibit different X-ray attenuation signatures and void morphologies than legacy SAC alloys, forcing recalibration of automated defect classification algorithms. German automotive qualification labs are driving adoption of updated inspection protocols aligned with these material transitions.
Consolidated procurement through captive foundry packaging divisions is displacing independent OSAT purchasing autonomy. Taiwan-based advanced packaging operations are negotiating enterprise-wide inspection system frameworks that standardize across multiple fab sites. This concentration transfers pricing leverage to buyers and favors vendors with established service footprints in Hsinchu and Taichung science parks.
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market Segmentation
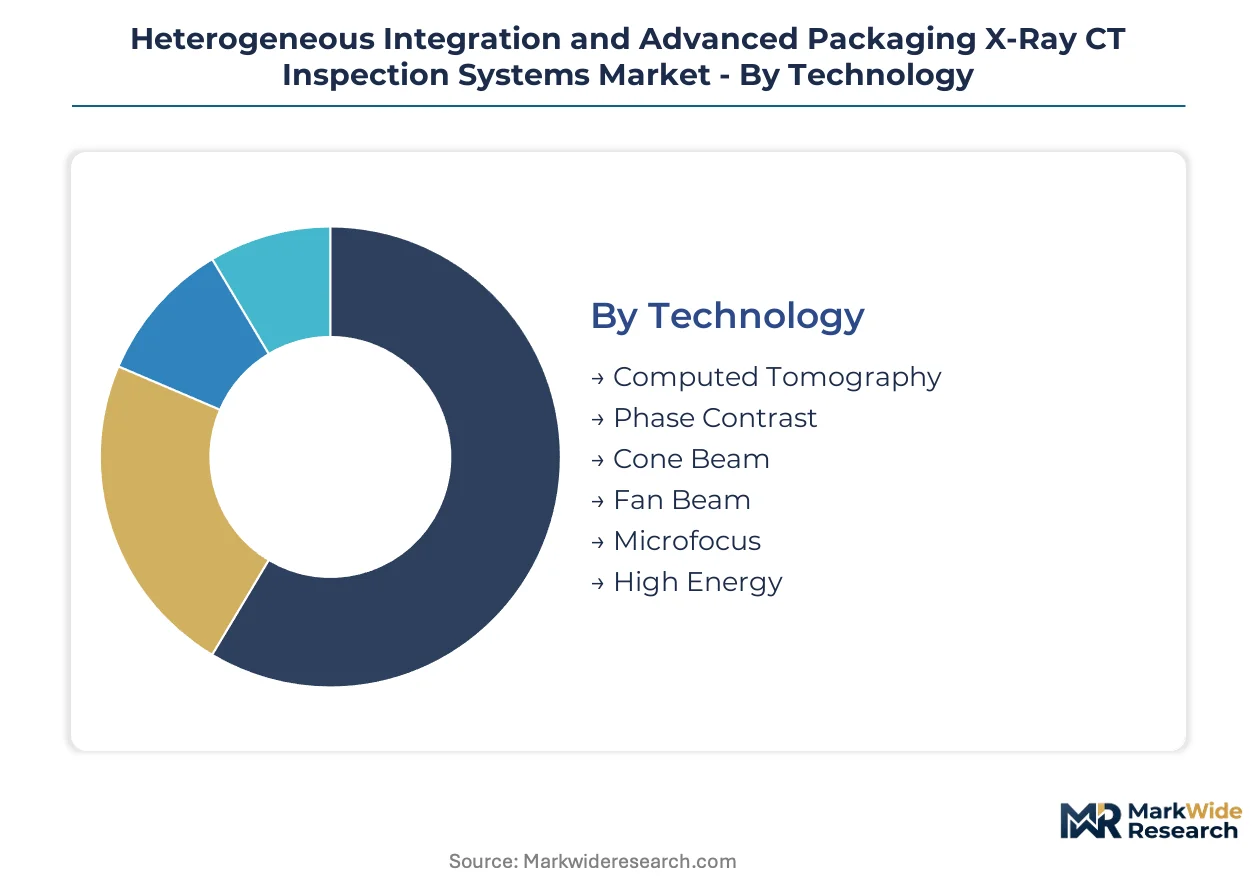
X-ray CT inspection systems for heterogeneous integration serve divergent technical requirements across packaging workflows. Equipment configurations vary sharply between high-volume production screening and laboratory-grade failure analysis, driving distinct vendor specialization strategies.
Technology:
After-sales service intensity escalates with tube complexity and reconstruction algorithm sophistication, pulling vendors toward subscription-based maintenance contracts for high-end modalities.
- Computed Tomography:Multi-axis rotational scanning with iterative reconstruction algorithms dominates 3D IC and HBM stack qualification. Taiwan-based foundry packaging divisions deploy CT systems for 100% screening of hybrid-bonded die assemblies, where sub-micron void detection determines yield trajectories.
- Microfocus:Sub-5 µm focal spot tubes enable sub-micron voxel resolution for solder microbump integrity verification. South Korean memory manufacturers concentrate procurement of microfocus platforms for high-bandwidth memory module qualification, driven by automotive chiplet reliability mandates.
- Phase Contrast:Edge-enhancement imaging for low-density polymer and adhesive inspection in fan-out wafer-level packaging.
- Cone Beam:Rapid volumetric acquisition for PCB and larger package substrate screening.
- Fan Beam:Linear detector arrays for high-throughput inline inspection of standard flip-chip assemblies.
- High Energy:300+ kV tube potentials penetrating 16-high HBM stacks and thick power module substrates.
By volume, Computed Tomography leads. By growth pace, Phase Contrast is expanding most quickly as fan-out packaging adoption accelerates.
Application:
Application-specific calibration requirements fragment vendor development roadmaps, with each vertical demanding customized defect classification libraries and throughput specifications.
- Semiconductor Package:Flip-chip, wire-bond, and wafer-level package inspection for voids, cracks, and delamination. United States captive packaging operations under CHIPS Act funding prioritize domestic procurement of automated CT lanes for advanced substrate qualification.
- 3D IC:True vertical stacking with hybrid bonding demands sub-micron resolution across thinned die interfaces. Taiwan and South Korea foundries drive equipment specifications for through-silicon via fill quality and copper-to-copper bondline verification.
- MEMS Devices:Cavity integrity and moving component clearance measurement for accelerometers and gyroscopes.
- Photonics Modules:Co-packaged optics inspection for fiber alignment and hermetic seal validation in AI training clusters.
- Printed Circuit Boards:Multilayer substrate via plating and inner layer registration verification.
- Nanoelectronics:Research-grade inspection for emerging device architectures and materials characterization.
Semiconductor Package generates the highest absolute equipment shipments. Photonics Modules shows the steepest expansion trajectory as co-packaged optics deployment scales.
Product Type:
Capital deployment patterns diverge sharply between high-volume manufacturers automating production lines and research institutions prioritizing analytical flexibility over throughput.
- Inline Inspection Systems:Fully automated platforms integrating with pick-and-place and reflow lines for 100% screening. Automotive tier-1 suppliers in Germany mandate inline CT lanes for high-bandwidth memory modules, driven by zero-defect reliability protocols under KBA oversight.
- Desktop Systems:Compact footprints for failure analysis labs and research institutes requiring analytical versatility. United States university packaging research centers and national laboratories anchor steady demand for configurable desktop platforms.
- Semi-Automatic:Operator-assisted loading with automated scan sequences for medium-volume production environments.
- Fully Automatic:Magazine-fed operation with robotic handling for uninterrupted high-volume screening.
- Portable Units:Field-deployable systems for equipment OEM service verification and installed base audits.
- Customized Solutions:Application-specific configurations for unique package form factors or extreme resolution requirements.
Inline Inspection Systems command the highest average selling prices. Desktop Systems maintain the broadest geographic penetration across research ecosystems.
End User:
Procurement autonomy concentrates with captive foundry packaging divisions, compressing independent OSAT purchasing leverage and favoring vendors with multi-site service capabilities.
- Package Manufacturers:Captive advanced packaging operations at leading foundries and IDMs. Taiwan-based operations in Hsinchu and Taichung science parks negotiate enterprise-wide inspection frameworks standardizing across multiple fab sites.
- Failure Analysis Labs:Root-cause investigation facilities requiring highest-resolution configurations for defect characterization. Automotive qualification labs in Germany and the United States drive specifications for automated defect classification algorithms.
- Assembly Houses:Outsourced semiconductor assembly and test providers procuring mid-range systems for customer-mandated screening.
- Quality Control Units:Incoming inspection and supplier audit functions within larger manufacturing organizations.
- Research Institutes:National laboratories and university centers developing next-generation packaging technologies.
- Equipment OEMs:Inspection system vendors and subsystem suppliers performing internal validation and supplier qualification.
Package Manufacturers account for the largest revenue concentration. Failure Analysis Labs are gaining share fastest as automotive and medical device qualification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage for X-ray CT inspection systems concentrates with Taiwanese foundry packaging divisions, while U.S. captive operations under CHIPS Act mandates absorb cost premiums for provenance-verified toolchains. This asymmetry reshapes vendor negotiation dynamics across procurement channels.
United States
Domestic packaging capacity expansion under CHIPS Act disbursements drives inspection infrastructure investment toward captive foundry operations. Bureau of Industry and Security export classifications restrict equipment sourcing to provenance-verified vendors, tightening vendor qualification windows. Greater Phoenix and Austin metro clusters anchor new advanced packaging facilities requiring automated CT lanes for substrate qualification.
Taiwan
Hsinchu and Taichung science park operations negotiate enterprise-wide inspection frameworks standardizing across multiple fab sites, compressing vendor pricing autonomy. Foundry packaging divisions consolidate procurement leverage through multi-site service agreements. Hybrid bonding adoption for 3D IC stacking pulls high-resolution CT into front-end-of-line workflows previously served by optical methods.
South Korea
Memory manufacturers concentrate microfocus platform procurement for high-bandwidth memory module qualification driven by automotive chiplet reliability mandates. MFDS medical device frameworks and automotive KBA protocols shape equipment certification requirements for qualification labs. Seoul Capital Area and Busan-Ulsan corridors anchor high-volume screening operations for export-bound modules.
Germany
Automotive tier-1 suppliers mandate inline CT lanes for high-bandwidth memory modules under zero-defect reliability protocols monitored by KBA. REACH substance restrictions on lead-containing solders force recalibration of automated defect classification algorithms for pure tin and silver-sintered interconnects. Bavarian automotive qualification labs drive updated inspection protocol adoption aligned with material transitions.
India
PLI scheme disbursements for semiconductor assembly and test facilities in Gujarat and Karnataka create greenfield demand for inspection infrastructure without incumbent vendor lock-in. Central Electricity Authority grid reliability standards and BIS certification requirements shape equipment qualification timelines. Dholera and Bengaluru corridors anchor first-mover packaging investments requiring metrology toolchain deployment.
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market Competitive Landscape
Metrology incumbents and specialized inspection system vendors split the market along integration depth and resolution specialization vectors. Equipment procurement tilts toward direct partnerships between system vendors and captive foundry packaging divisions, compressing independent OSAT purchasing autonomy. Three archetypes dominate: wafer-level metrology extenders, inline packaging integration specialists, and high-resolution laboratory-grade configurators. Competitive moves concentrate on AI-assisted reconstruction convergence and multi-site service footprint expansion.
Within the wafer-level metrology extension tier, KLA leverages its installed base to anchor position, while Nordson occupies the inline packaging integration specialist archetype through high-volume line integration. YXLON International exemplifies the laboratory-grade configuration specialist serving automotive qualification protocols. These three represent the strategic positioning spectrum vendors must navigate to secure enterprise-wide framework agreements with consolidated packaging operations.
| Leading Market Players |
|---|
| KLA |
| Onto Innovation |
| Nordson |
| YXLON International |
| Nikon Metrology |
| North Star Imaging |
| Camtek |
| Bruker |
| ZEISS |
| Others |
Pricing and Supply Chain Analysis
Hsinchu and Taichung science park foundry packaging divisions command pricing leverage through enterprise-wide framework agreements that standardize CT inspection procurement across multiple fab sites. This geographic concentration of buyer power compresses vendor margins while amplifying cost premiums for provenance-verified toolchains under U.S. CHIPS Act disbursement requirements.
Pricing Analysis
The customization-premium spread spans three-tier pricing structure across premium, standard, and economy levels, with inline inspection systems commanding the highest configured-to-order premiums due to integration complexity. Price differentiation hinges on ISO 9001 certification tier and after-sales service bundling intensity. Cost compression in standard desktop systems is intensifying because captive foundry packaging divisions negotiate volume-scale discounts. Independent OSATs exhibit highest price sensitivity; captive foundry operations absorb certification-driven premiums.
Supply Chain Analysis
Upstream feedstock constraints center on tungsten filament and target supplies drawn from Chinese and Russian refining operations, exposing microfocus X-ray tube manufacturers to input cost volatility. Raw material dependencies extend to amorphous silicon backplanes for flat-panel detectors, precision motion control subsystems, and high-voltage power electronics. Single-source vulnerability in tungsten supply creates structural risk. Distribution runs through direct vendor partnerships with captive foundry packaging divisions, displacing independent channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where subscription-based maintenance contracts and remote monitoring platforms expand faster than hardware unit sales, driven by digital twin architectures for predictive maintenance.
For Market Incumbents: Pre-empt margin erosion from AI-assisted reconstruction convergence by deepening backward integration into precision motion control subsystems and expanding multi-site service footprints in Hsinchu and Taichung science parks. Certification investment in ISO 9001 automotive qualification protocols defends position against laboratory-grade configurators targeting failure analysis labs. For New Entrants and Emerging Players: India's Gujarat and Karnataka corridors offer greenfield penetration without incumbent vendor lock-in, particularly for mid-range semi-automatic systems serving PLI scheme-funded assembly and test facilities. Target Dholera and Bengaluru packaging clusters through localized service partnerships and BIS certification pre-qualification. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with installed bases in Taiwan-based foundry packaging divisions, where multi-site service agreements generate predictable aftermarket income. Long-term viability favors acquisition targets with AI-assisted reconstruction software stacks and proven automotive qualification lab relationships. Watch hybrid bonding adoption rates in 3D IC stacking as inflection indicator for high-resolution CT demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Reconstruction Platform Development | Deep learning-based artifact reduction compresses scan-to-decision timelines for HBM module screening. |
| Multi-Site Service Footprint Expansion | Enterprise-wide framework agreements in Hsinchu and Taichung require localized technical support capacity. |
| Automotive Qualification Lab Partnership | KBA-monitored zero-defect protocols mandate dedicated inline CT lanes for chiplet verification. |
| Backward Integration into Motion Control | Precision thermal management and vibration isolation subsystems command scarcity premiums in sub-micron platforms. |
| Remote Monitoring Platform Deployment | Digital twin architectures for tube degradation simulation enable subscription-based service revenue conversion. |
Research Methodology
Desk research of Bureau of Industry and Security export classifications, FDA device-quality frameworks, and ISO 9001 certification databases preceded structured interviews with equipment OEM procurement directors, foundry packaging division metrology leads, automotive qualification lab managers, and aftermarket service heads. Secondary validation drew from SEC filings of publicly traded metrology vendors, CHIPS Act funding disbursement records, and Taiwan Stock Exchange disclosure documents. Bottom-up equipment shipment estimates triangulated against top-down packaging capacity expansion projections.
The analytical framework held technology adoption curves and regulatory provenance requirements fixed across the projection horizon while varying hybrid bonding penetration rates and automotive chiplet qualification mandates. Segmentation dimensions modeled include technology modality, application workflow, product automation tier, and end-user procurement autonomy. CAGRs derived from weighted average of capacity-driven equipment procurement and replacement cycle analysis, with explicit inputs for tungsten supply volatility and flat-panel detector allocation constraints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by China-based packaging entrants or accelerated REACH substance restriction timelines would shift outcomes. Cross-checking against Bureau of Industry and Security license application data and Taiwan-based foundry capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.