
 Pack Testing Machines Market | 2026-2036
Pack Testing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pack Testing Machines Market Analytics
Qualified metrology technicians is rotating toward automated platforms as pack testing shifts from manual gauging to software-driven validation systems. ZwickRoell AG leverages its Stuttgart engineering base to dominate precision tensile and compression testing for pharmaceutical blister packs. Labthink Instruments Co., Ltd. anchors Asian supply chains with localized calibration networks and region-specific compliance tooling. AMETEK Inc. competes through vertically integrated sensor manufacturing that sustains margin pools in high-throughput leakage detection.
Pack testing machines evaluate seal integrity, material strength, and barrier performance of containers, cartons, and flexible films using calibrated force, pressure, or electrical measurement protocols with precision typically rated to 0.5% of full scale. These systems verify that pharmaceutical vials, food pouches, and industrial drums withstand distribution stresses while preserving shelf stability. Automated systems are capturing share fastest as batch records integrate directly with LIMS and ERP platforms, though mechanical testing retains volume leadership in emerging manufacturing economies where capital constraints favor simpler equipment. Pharmaceutical packaging commands the deepest margin pool among application segments due to FDA 21 CFR Part 11 validation requirements and zero-defect quality agreements.
FDA enforcement of container closure integrity testing for sterile injectables and EMA Annex 1 revisions on barrier qualification are mandating capital upgrades across GMP-certified facilities. ISO 11607 and ASTM D4169 provide the technical baselines that OEMs must embed to achieve market access in regulated jurisdictions. Stakeholders must weigh retrofit compatibility against full-platform replacement as software-driven architectures redefine total cost of ownership calculations.
Market Dynamics
Automated validation systems are compressing equipment replacement cycles as pharmaceutical manufacturers face FDA 21 CFR Part 11 compliance deadlines and EMA Annex 1 barrier qualification mandates. The shift from mechanical gauging to software-driven metrology is forcing capital allocation decisions across GMP-certified facilities.
Growth Catalysts
- FDA Container Closure Integrity Mandates:Sterile injectables manufacturers must deploy deterministic leak detection methods, accelerating capital expenditure on vacuum decay and high-voltage leak detection systems.
- EMA Serialization Directives:European contract packaging organizations are automating batch record integration to satisfy track-and-trace requirements, pulling demand for LIMS-compatible testing platforms.
- Stuttgart-Düsseldorf Machinery Cluster:German precision engineering concentration enables rapid prototyping of pharmaceutical-grade tensile testers, shortening equipment qualification timelines for continental supply chains.
Market Restraints
- Stainless Steel and Sensor Cost Volatility:Force transducer and precision frame material costs fluctuate with nickel pricing, squeezing margin pools for mid-tier equipment OEMs.
- Single-Source Calibration Dependency:ISO 17025-accredited metrology laboratories concentrate in Germany, Japan, and the United States, creating geographic bottlenecks for validation certificate issuance.
- Mechanical Tester Longevity:Legacy manual gauging equipment operates for 15-20 years in emerging manufacturing economies, delaying replacement demand despite regulatory pressure.
Strategic Opportunities
- India Pharmaceutical Manufacturing Expansion:CDSCO's tightening GMP enforcement and PLI scheme incentives are prompting domestic blister pack producers to upgrade from visual inspection to automated seal integrity verification.
- AI-Enabled Predictive Maintenance Convergence:Machine learning algorithms overlaid on force-displacement curves enable real-time wear detection, creating aftermarket service revenue streams beyond equipment sales.
- Biologics Cold Chain Validation:Cell and gene therapy temperature excursion testing requirements represent an emerging application segment with limited incumbent equipment specialization.
Industry Challenges
- Metrology Technician Scarcity:Qualified personnel capable of executing Installation Qualification and Operational Qualification protocols per FDA guidelines command premium compensation, constraining deployment velocity.
- Legacy ERP Integration Complexity:Brownfield pharmaceutical facilities running on-premise MES platforms face multi-month validation timelines when connecting automated testers to existing batch record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pack Testing Machines Market |
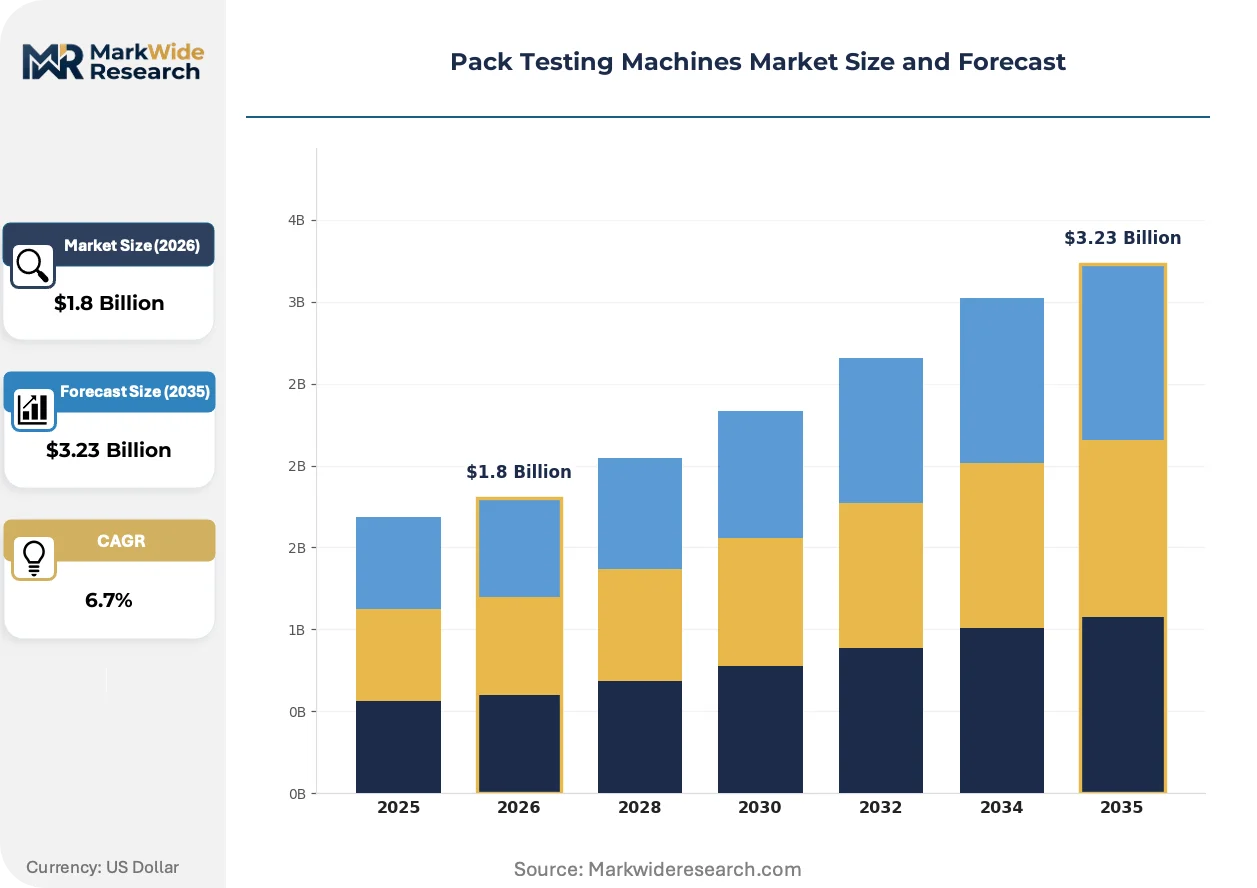
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Testers, Leakage Testers, Compression Testers, Tensile Testers End User: Manufacturers, Quality Control Labs, Research Institutes, Packaging Firms Technology: Mechanical Testing, Automated Systems, Software-Driven Solutions, Manual Test Systems Application: Food Packaging, Pharmaceutical Packaging, Consumer Goods, Industrial Packaging |
| Companies Covered | Mettler-Toledo International Inc., AMETEK Inc., ZwickRoell AG, Shimadzu Corporation, Labthink Instruments Co., Ltd., Presto Group, Qualitest International Inc., Instron, Tinius Olsen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pack Testing Machines Market Evolving Landscape
Software-defined validation architectures are compressing the boundary between quality control and manufacturing execution. Equipment vendors now compete on data interoperability rather than mechanical precision alone.
Deterministic leak detection methods including vacuum decay and high-voltage leak detection are supplanting probabilistic dye ingress and bubble emission tests in sterile pharmaceutical applications. Contract packaging organizations in Germany and Switzerland are completing this transition within 18-24 month equipment refresh cycles. The shift eliminates operator-dependent variability while generating machine-readable batch records that satisfy FDA 21 CFR Part 11 audit trails.
EMA Annex 1 revisions on barrier qualification and container closure integrity are mandating deterministic testing methods for sterile medicinal products. The regulation eliminates subjective visual inspection for critical seal defects, forcing capital upgrades across European GMP-certified facilities. Aseptic fill-finish operations in Ireland, Belgium, and Italy represent the most concentrated compliance pressure given their biologics manufacturing density.
Service contract unbundling is fragmenting traditional equipment procurement models. Pharmaceutical manufacturers now separate hardware acquisition from validation, calibration, and software maintenance obligations, pressuring OEMs to demonstrate recurring revenue capabilities. This pattern concentrates in North American and Western European markets where quality assurance departments operate as independent profit centers with discrete budget authority.
Pack Testing Machines Market Segmentation
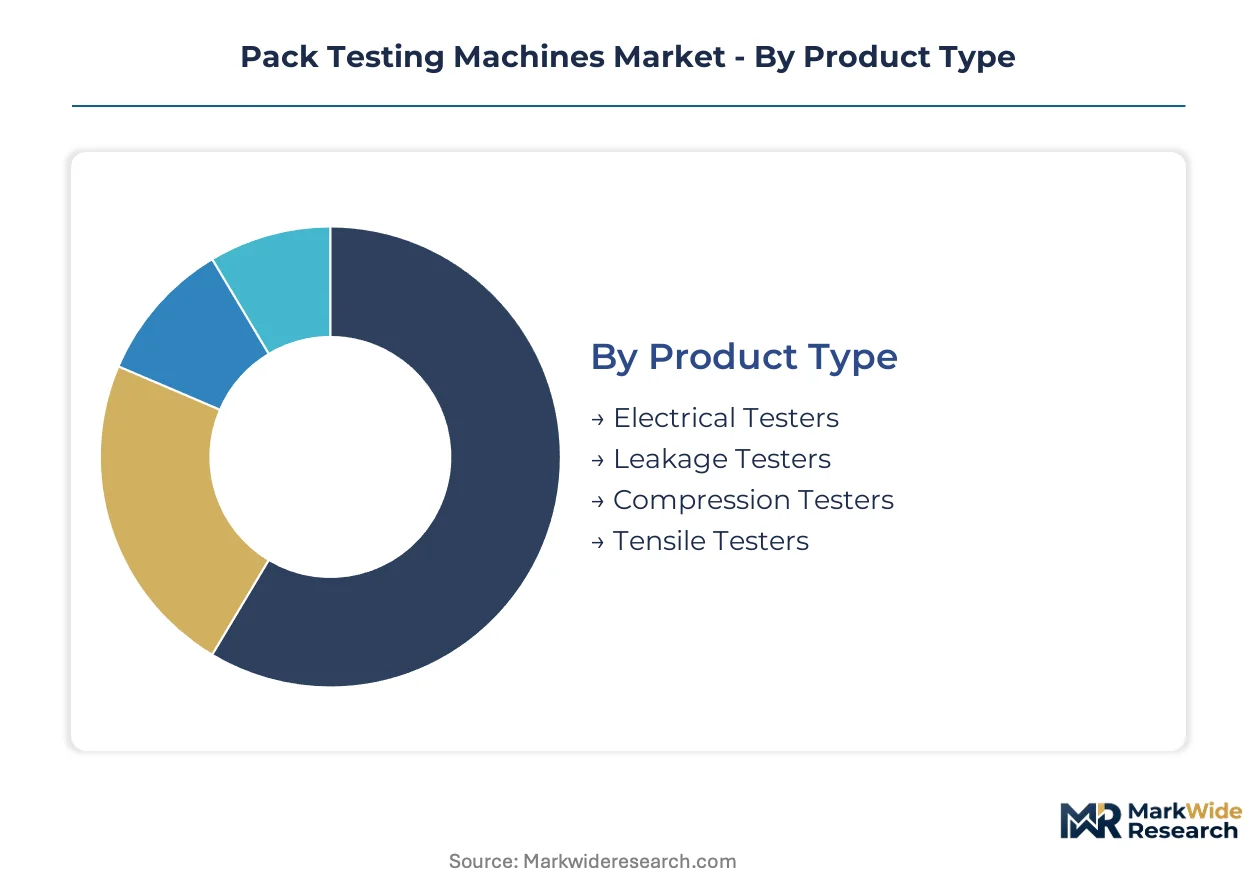
Pack testing machines serve divergent compliance regimes across pharmaceutical serialization, food safety mandates, and industrial durability standards. Segmentation reveals how capital allocation priorities split between deterministic leak detection for sterile injectables and mechanical gauging for emerging manufacturing economies with constrained quality assurance budgets.
Product Type:
Electrical testers and leakage testers concentrate in export-oriented pharmaceutical supply chains serving FDA-regulated markets, while compression and tensile equipment retains stronger domestic manufacturing bases in Germany and Japan.
- Electrical Testers:High-voltage leak detection systems apply calibrated electrical potential to identify pinholes in pharmaceutical blister packs and vial seals. Demand clusters around Stuttgart engineering corridors supplying continental European aseptic fill-finish operations under EMA Annex 1 compliance pressure.
- Leakage Testers:Vacuum decay and pressure decay systems measure gas escape rates with sensitivity to detect defects below 10 microns. German and Swiss contract packaging organizations deploy these systems fastest to eliminate operator-dependent dye ingress protocols.
- Compression Testers:Vertical load frames evaluate carton stacking strength and bottle crush resistance per ASTM D4169 distribution simulation protocols.
- Tensile Testers:Precision force measurement systems characterize seal peel strength and film elongation properties for flexible packaging validation.
Leakage testers hold the largest share; momentum sits with electrical testers as sterile injectables manufacturers accelerate deterministic method adoption.
End User:
Cost tier stratification separates capital-intensive automated platform adopters from budget-constrained mechanical equipment users, with research institutes occupying a distinct funding model dependent on grant cycles rather than production economics.
- Manufacturers:Pharmaceutical producers and food processors operate the highest equipment utilization rates, integrating testers directly into production lines for 100% inspection regimes. FDA 21 CFR Part 11 validation requirements and EMA serialization mandates drive replacement of manual gauging with LIMS-connected automated systems.
- Quality Control Labs:Independent testing facilities and corporate QA departments perform batch release verification and stability protocol execution. These operations concentrate in Germany, the United States, and Japan where ISO 17025 accreditation requirements sustain premium pricing for validated equipment.
- Research Institutes:Academic and government laboratories evaluate novel packaging materials and barrier technologies prior to commercial scale-up.
- Packaging Firms:Contract packaging organizations face compressed equipment refresh cycles as brand owners transfer serialization compliance liability downstream.
Manufacturers dominate volume; packaging firms are climbing the fastest as contract manufacturing organizations absorb regulatory compliance burdens from pharmaceutical sponsors.
Technology:
Application maturity splits sharply between validated pharmaceutical environments requiring software-defined architectures and industrial segments where mechanical longevity outweighs connectivity features.
- Mechanical Testing:Dial gauges, dead-weight loaders, and manual force application devices persist in emerging manufacturing economies where capital constraints favor 15-20 year equipment lifecycles over connectivity-enabled replacement.
- Automated Systems:Robotic sample handling and programmable test sequences enable unattended operation with direct LIMS and ERP integration. These systems command premium positioning in North American and Western European markets where quality assurance departments operate as independent profit centers.
- Software-Driven Solutions:Machine learning overlays on force-displacement curves enable predictive maintenance and real-time wear detection, creating aftermarket service revenue streams beyond hardware sales.
- Manual Test Systems:Operator-dependent gauging retains volume leadership in price-sensitive industrial packaging segments with limited regulatory compliance pressure.
Mechanical testing retains volume leadership; software-driven solutions show the steepest expansion trajectory as AI-enabled predictive maintenance converges with pharmaceutical validation requirements.
Application:
Margin concentration follows regulatory intensity, with pharmaceutical packaging commanding premium positioning due to zero-defect quality agreements and sterile product liability exposure.
- Pharmaceutical Packaging:Container closure integrity testing for sterile injectables, blister pack seal verification, and barrier qualification for biologics cold chain applications. FDA enforcement of deterministic methods and EMA Annex 1 revisions mandate capital upgrades across GMP-certified facilities in Ireland, Belgium, and Italy.
- Food Packaging:Modified atmosphere packaging leak detection, retort pouch seal validation, and shelf-life barrier performance testing. European food safety authorities and USDA inspection protocols drive equipment specification requirements.
- Consumer Goods:Cosmetic and personal care packaging durability testing with lower regulatory compliance thresholds than pharmaceutical or food segments.
- Industrial Packaging:Drum, pail, and intermediate bulk container testing for chemical and hazardous material transport compliance with UN certification requirements.
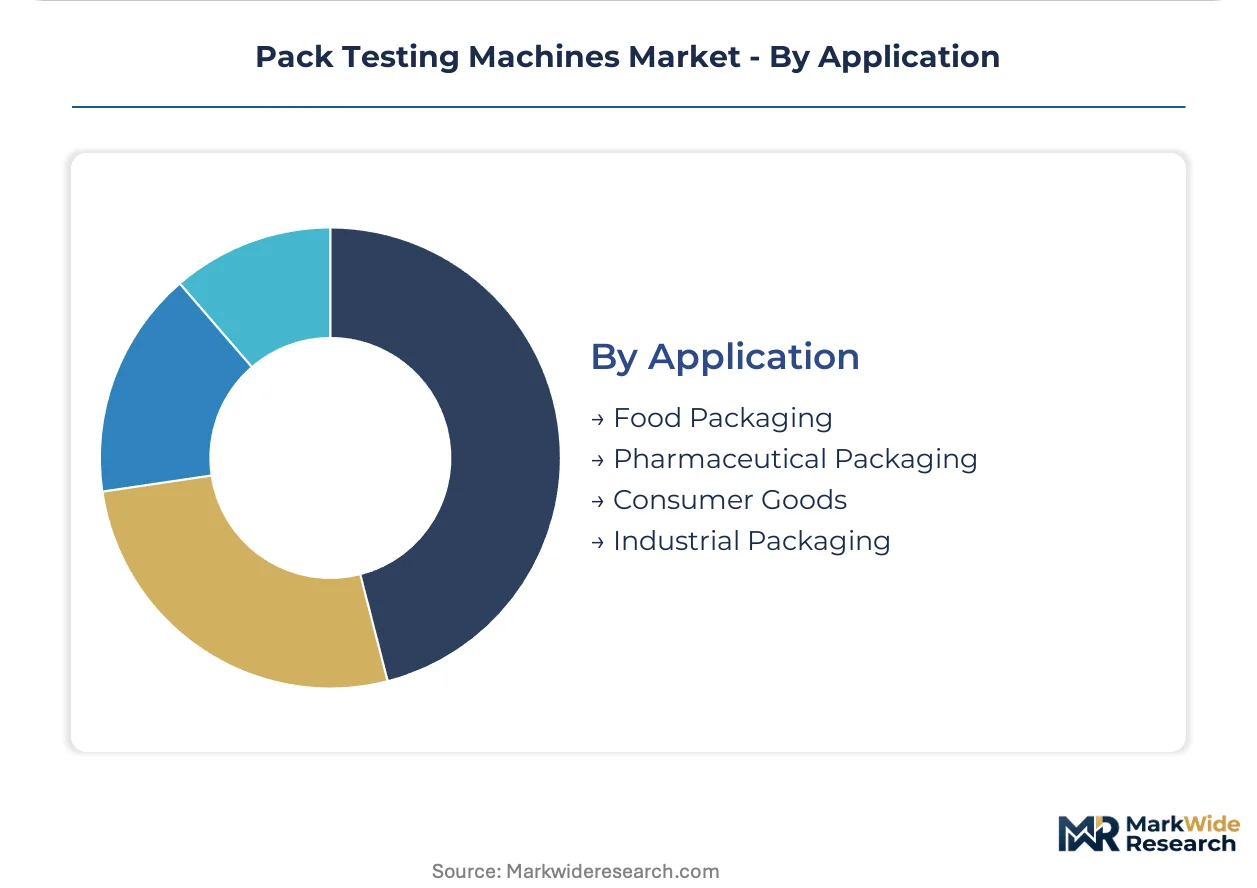
Pharmaceutical packaging commands the deepest margin pool; food packaging is expanding most quickly as modified atmosphere and active packaging technologies proliferate across European and North American retail supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature pharmaceutical manufacturing corridors deploying deterministic leak detection systems and emerging industrial economies retaining mechanical gauging equipment for extended replacement cycles.
Germany
Stuttgart and Düsseldorf host precision engineering clusters supplying continental European aseptic fill-finish operations with pharmaceutical-grade tensile and compression testers. EMA Annex 1 revisions on barrier qualification mandate deterministic testing methods, compressing equipment refresh cycles to 18-24 months among contract packaging organizations.
United States
FDA enforcement of container closure integrity testing for sterile injectables drives capital allocation toward vacuum decay and high-voltage leak detection platforms. Quality assurance departments in North American pharmaceutical facilities operate as independent profit centers with discrete budget authority, accelerating automated system adoption.
India
CDSCO's tightening GMP enforcement and PLI scheme incentives prompt domestic blister pack producers to upgrade from visual inspection to automated seal integrity verification. Maharashtra and Gujarat pharmaceutical manufacturing corridors represent concentrated demand as contract manufacturers absorb serialization compliance liability from international sponsors.
China
NMPA alignment with international GMP standards and domestic biologics manufacturing expansion create demand for validated testing equipment in Yangtze River Delta pharmaceutical clusters. Local producers balance regulatory compliance pressure against capital constraints favoring longer mechanical equipment lifecycles.
Switzerland
Swissmedic oversight of sterile medicinal products and high-density biologics manufacturing in Basel and Zurich drive premium positioning for software-defined validation architectures. Contract packaging organizations complete deterministic method transitions fastest here, generating machine-readable batch records satisfying international audit trail requirements.
Pack Testing Machines Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure reflecting regulatory validation requirements that favor established calibration networks and software interoperability capabilities. The upper tier commands premium positioning through captive sensor manufacturing and direct LIMS integration, while mid-tier fabricants compete on retrofit compatibility and regional service density. Two strategic archetypes dominate: precision engineering specialists concentrated in German machinery corridors, and vertically integrated instrumentation conglomerates with in-house transducer production. Competitive moves center on unbundling service contracts from hardware sales and converging predictive maintenance algorithms with pharmaceutical validation protocols.
Among Germany-based precision engineering specialists, ZwickRoell AG anchors the pharmaceutical-grade tensile testing segment from its Stuttgart engineering base. AMETEK Inc. represents the integrated instrumentation archetype through captive sensor manufacturing that sustains margin pools in high-throughput applications. Labthink Instruments Co., Ltd. occupies a position within Asian supply chain specialists, leveraging localized calibration networks to serve region-specific compliance tooling demand.
| Leading Market Players |
|---|
| Mettler-Toledo International Inc. |
| AMETEK Inc. |
| ZwickRoell AG |
| Shimadzu Corporation |
| Labthink Instruments Co., Ltd. |
| Presto Group |
| Qualitest International Inc. |
| Instron |
| Tinius Olsen |
| Others |
Value Network & Pricing Analysis
Stuttgart-Düsseldorf precision engineering clusters generate scale economies that compress unit production costs for pharmaceutical-grade tensile frames while simultaneously elevating price floors through captive calibration networks. FDA 21 CFR Part 11 validation requirements and EMA Annex 1 barrier qualification mandates concentrate procurement authority among quality assurance departments with discrete budget autonomy, decoupling equipment pricing from pure manufacturing cost curves.
Pricing Analysis
Long-term service contracts dominate capital equipment procurement as pharmaceutical manufacturers unbundle hardware acquisition from validation, calibration, and software maintenance obligations. Price differentiation rests on ISO 17025 accreditation tier and LIMS integration depth, with premium positioning commanding multiples over baseline mechanical systems. Cost compression in mid-tier equipment intensifies because nickel-price volatility squeezes force transducer margins. Emerging manufacturing economies in India and China exhibit highest price sensitivity, while North American sterile injectables producers demonstrate lowest sensitivity due to liability exposure and zero-defect quality agreements.
Supply Chain Analysis
Inventory lead times for precision force transducers and stainless steel frames extend from German and Japanese component suppliers, creating working capital intensity for equipment OEMs. Manufacturing concentration centers on Germany, Japan, and the United States, with secondary assembly nodes emerging in China and India. Raw material dependencies draw from nickel alloys, piezoelectric sensors, and precision-machined aluminum. Single-source vulnerability in ISO 17025-accredited metrology laboratories creates geographic bottlenecks for validation certificate issuance. Distribution runs through direct sales teams serving pharmaceutical manufacturers and authorized distributors penetrating emerging industrial packaging segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA container closure integrity mandates and EMA Annex 1 revisions on deterministic testing methods constitute a regulatory inflection accelerating equipment replacement cycles across GMP-certified facilities. Software-defined validation architectures are displacing mechanical gauging protocols, compressing the competitive window for incumbent positioning.
For Market Incumbents: Consolidate calibration network density in Germany, Japan, and the United States to defend against emerging Asian competitors with localized service capabilities. Acquire predictive maintenance software specialists to capture recurring revenue streams as service contracts unbundle from hardware sales. Capacity addition in Maharashtra and Gujarat pharmaceutical corridors addresses CDSCO enforcement tightening and PLI scheme incentives driving Indian blister pack automation.
For New Entrants and Emerging Players: Differentiate on AI-enabled predictive maintenance overlays that machine learning algorithms deploy across force-displacement curves for real-time wear detection. Target biologics cold chain validation as white-space application with limited incumbent equipment specialization. Penetrate contract packaging organizations in Switzerland and Ireland through software interoperability demonstrations satisfying EMA serialization audit trail requirements.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated instrumentation conglomerates with captive sensor manufacturing sustaining margin pools in high-throughput leakage detection. Long-term viability over the projection horizon rests on recurring revenue capabilities as pharmaceutical quality assurance departments operate with discrete budget authority. Acquisition target archetype: precision engineering specialists with Stuttgart-Düsseldorf engineering bases and established FDA 21 CFR Part 11 validation protocols. Signal to watch: CDSCO GMP enforcement intensity in Indian pharmaceutical manufacturing corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | ISO 17025-accredited laboratory density in Germany and Japan defends premium positioning against Asian competitors. |
| Predictive Maintenance Software Acquisition | Machine learning overlays on force-displacement curves capture recurring revenue beyond equipment sales. |
| Indian Manufacturing Corridor Presence | Maharashtra and Gujarat facilities address CDSCO enforcement and PLI scheme-driven automation demand. |
| Biologics Cold Chain Validation Development | Cell and gene therapy temperature excursion testing opens application segment with limited incumbent specialization. |
| LIMS Integration Partnership | Direct ERP and batch record connectivity satisfies FDA 21 CFR Part 11 audit trail requirements for sterile injectables manufacturers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quality assurance directors, metrology technicians, pharmaceutical packaging engineers, and contract manufacturing procurement leads. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA Annex 1 revision texts, ISO 11607 and ASTM D4169 technical standards, and SEC filings of listed instrumentation conglomerates. Bottom-up equipment shipment analysis triangulated against top-down pharmaceutical capital expenditure surveys across the analysis window.
Across the modeling period, segmentation dimensions included product type, end user archetype, technology tier, and application vertical with regional regulatory cluster overlays. CAGRs were derived from installed base depreciation curves and replacement cycle compression under deterministic testing mandates. Industry-specific forecast inputs incorporated CDSCO GMP enforcement timelines and NMPA alignment with international standards in Chinese biologics manufacturing.
Forecasts assume regulatory continuity in FDA, EMA, and CDSCO enforcement regimes; material policy shifts would require re-modeling replacement demand trajectories. Nickel price volatility and metrology technician scarcity represent specific risk factors that could revise capital expenditure timing. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Packaging Inspection Systems Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Box Compression Tester Market
Packaging Testing
Global Package Testing Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Packaging Testing Market