
 Food Packaging Testing Market | 2026-2036
Food Packaging Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Food Packaging Testing Market Foresight
Asset-light leasing models for spectroscopy and chromatography equipment is reconfiguring capital barriers for mid-sized contract testing services. SGS S.A. leverages its geographic laboratory network to sustain multi-country certification coverage. Eurofins Scientific SE anchors its position through specialized migration testing capabilities for polymer-based food contact materials. Intertek Group PLC differentiates via integrated packaging lifecycle services spanning raw material validation to finished goods release.
Food packaging testing encompasses physicochemical and microbiological evaluation protocols that verify barrier performance, seal integrity, and contaminant migration limits in materials contacting consumable products. Gas chromatography-mass spectrometry detection thresholds for primary aromatic amines and heavy metals typically operate at parts-per-billion sensitivity to ensure consumer safety compliance. Migration testing for plastic films commands the largest current revenue pool due to regulatory complexity across layered polymer structures, while biodegradable materials represent the fastest-growing segment as polylactic acid and cellulose-based substrates require novel decomposition-byproduct screening. Seal integrity validation for ready-to-eat meals concentrates margin pools where modified atmosphere packaging failures carry substantial food spoilage liability.
FDA food contact notification rules and EFSA migration limit frameworks collectively shape testing volume by mandating substance-specific extraction studies for new packaging chemistries. BIS packaging standards in India and FSSAI safety directives are expanding mandatory testing scopes beyond microbial limits into heavy metal leachate quantification. Stakeholders must monitor evolving regulatory reciprocity agreements between jurisdictions to anticipate where redundant testing obligations will consolidate or proliferate.
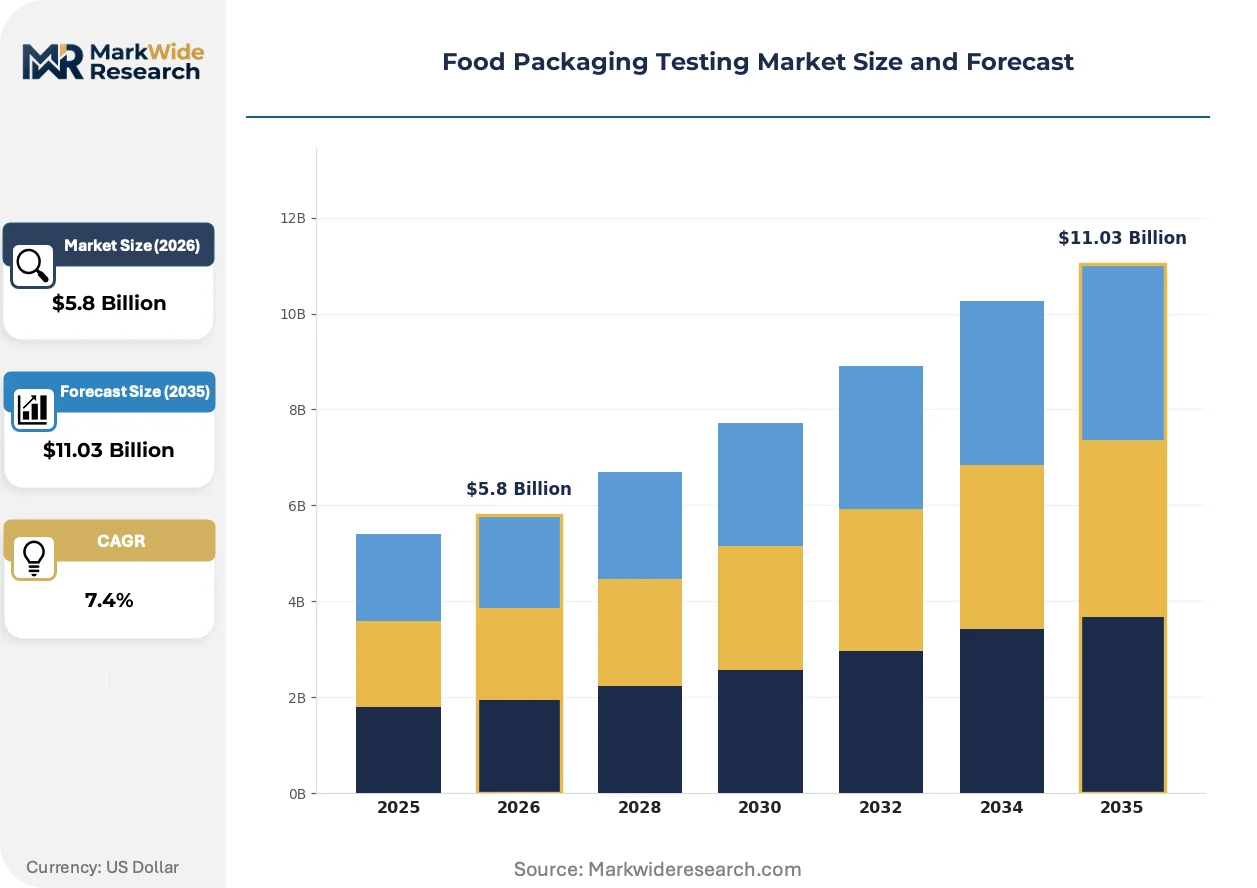
Market Dynamics
Regulatory fragmentation across FDA, EFSA, and FSSAI jurisdictions is forcing testing providers to build multi-standard capability stacks rather than single-market specialization.
Growth Catalysts
- EFSA Migration Limits:The European Food Safety Authority's tightening thresholds for primary aromatic amines in plastic food contact materials are expanding mandatory extraction study volumes for polymer film producers supplying ready-to-eat meal packaging.
- Biodegradable Substrate Proliferation:Polylactic acid and cellulose-based packaging materials entering commercial food service channels require novel decomposition-byproduct screening protocols that legacy petroleum-based testing suites cannot execute.
- India FSSAI Directives:India's Food Safety and Standards Authority has extended mandatory testing scopes beyond microbial limits into heavy metal leachate quantification, creating new compliance service demand from domestic and export-oriented food processors.
Market Restraints
- Helium Supply Concentration:Gas chromatography-mass spectrometry systems depend on helium carrier gas where supply concentrates in Qatar, Russia, and Algeria, exposing testing laboratories to input cost volatility and allocation rationing during geopolitical disruptions.
- Spectroscopy Equipment Capital Intensity:Fourier-transform infrared and inductively coupled plasma mass spectrometry instruments require seven-figure capital deployment, constraining mid-sized contract testing services from expanding migration testing capacity.
- Regulatory Reciprocity Gaps:Absence of mutual recognition agreements between FDA food contact notification frameworks and EFSA migration limit regimes forces redundant testing obligations for multinational food packaging suppliers.
Strategic Opportunities
- Asset-Light Leasing Models:Equipment-as-a-service arrangements for chromatography and spectroscopy systems are reconfiguring capital barriers, enabling mid-tier testing laboratories to access migration testing capability without balance-sheet impairment.
- Modified Atmosphere Packaging Failures:Ready-to-eat meal producers face substantial food spoilage liability from seal integrity failures, concentrating margin pools for specialized validation services that verify barrier performance across polymer multilayer structures.
- Germany EFSA Compliance Hub:German food packaging exporters serving pan-European distribution networks require centralized multi-country certification coverage, rewarding testing providers with geographic laboratory networks.
Industry Challenges
- Analytical Chemist Talent Scarcity:Gas chromatography-mass spectrometry operation and parts-per-billion detection threshold interpretation require specialized skill sets where training pipeline output lags demand from expanding regulatory testing mandates.
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA food contact notification, EFSA migration limit compliance, and FSSAI packaging safety directive adherence creates complex project management overhead for testing service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Packaging Testing Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.03 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Material Characterization, Seal Integrity, Migration Testing, Microbial Analysis, Mechanical Testing Packaging Material: Plastic Films, Paperboard, Metal Cans, Glass Containers, Biodegradable Materials Application: Fresh Produce, Frozen Foods, Ready-to-Eat Meals, Beverages, Confectionery End User: Packaging Manufacturers, Food Processors, Quality Assurance Labs, Contract Testing Services |
| Companies Covered | SGS S.A., Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Bureau Veritas, 3M Company, Bio-Rad Laboratories, Inc., Intertek Group PLC, Merck KGaA, Eurofins Scientific SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Packaging Testing Market Shifts & Advancements
Digital instrumentation and automated sample handling are compressing detection timelines while regulatory data submission requirements are hardening traceability standards across food contact material supply chains.
Spectroscopic fingerprinting combined with machine learning classification algorithms is digitizing contaminant identification workflows. Ready-to-eat meal packaging producers in North America are adopting these integrated systems at accelerated replacement cycles for legacy chromatography-dependent protocols. The technology is digitizing quality control documentation, enabling real-time regulatory submission preparation that reduces certification timeline risk.
REACH Annex XVII restrictions on phthalates and bisphenol A in food contact materials are expanding substance-specific testing mandates across European polymer supply chains. Industrial consequence includes mandatory requalification of existing packaging chemistries previously grandfathered under transitional provisions. Flexible film converters serving dairy and meat packaging segments are most affected, responding by accelerating substitution toward non-phthalate plasticizers with accompanying extraction study requirements.
Buyer consolidation among multinational food processors is compressing testing service procurement cycles from annual frameworks to campaign-based engagement models. Third-party certification bodies face disintermediation pressure as captive testing laboratories at SGS S.A., Eurofins Scientific SE, and Intertek Group PLC leverage integrated packaging lifecycle services spanning raw material validation to finished goods release. Germany and India represent demand concentration zones where this procurement evolution is most visible, with ready-to-eat meal producers consolidating testing spend toward providers with geographic laboratory network coverage.
Food Packaging Testing Market Segmentation
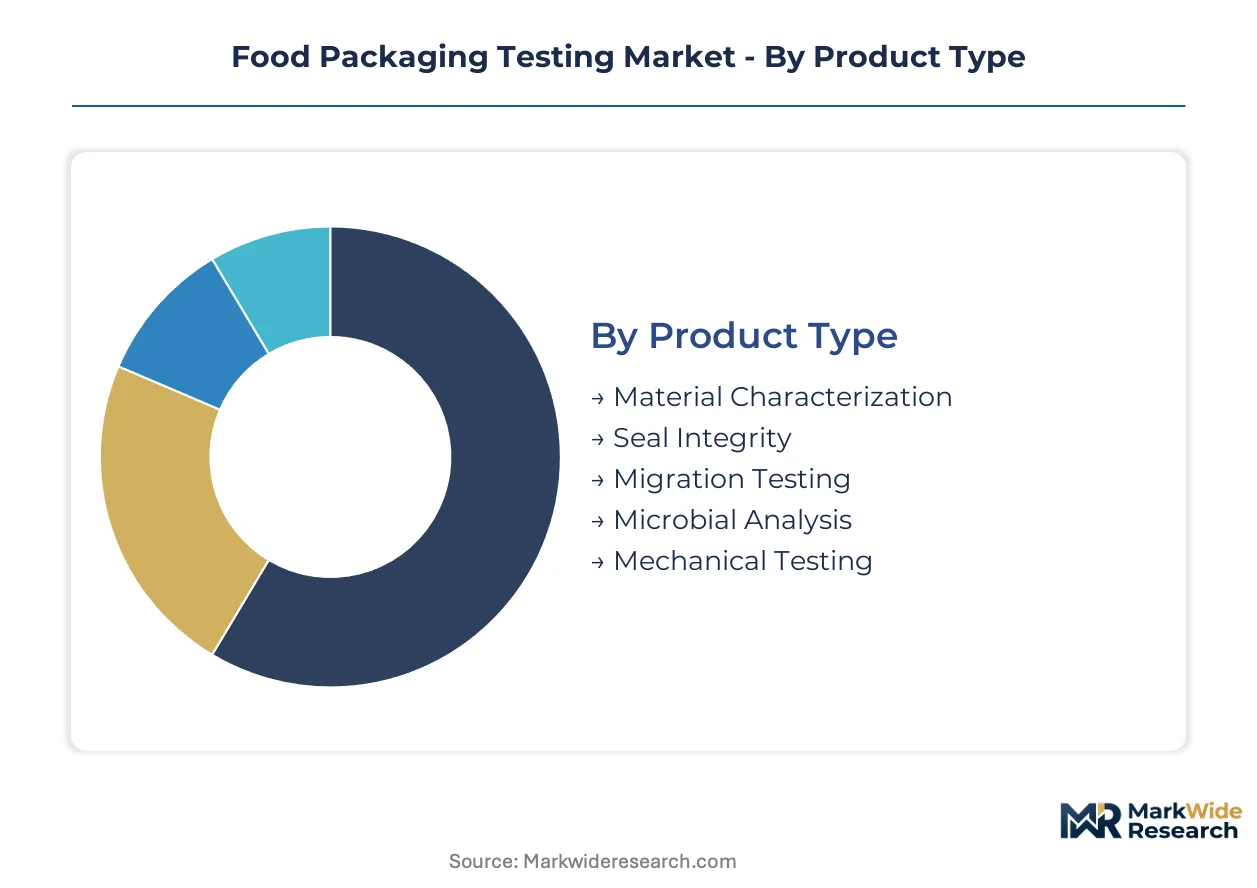
Testing demand fragments across material chemistries, functional validation requirements, and supply chain positions. Each segmentation dimension captures distinct procurement patterns and regulatory exposure profiles that reshape competitive positioning.
Product Type:
Cost tier separates basic quality assurance from specialized migration and integrity protocols requiring capital-intensive instrumentation.
- Migration Testing:Extraction studies for plastic food contact materials operate at parts-per-billion detection thresholds using gas chromatography-mass spectrometry. FDA food contact notification rules and EFSA migration limits mandate substance-specific protocols for polymer multilayer structures supplying ready-to-eat meal packaging.
- Seal Integrity:Modified atmosphere packaging validation concentrates margin pools where barrier failures trigger substantial food spoilage liability. Demand clusters with North American ready-to-eat meal producers facing compressed shelf-life tolerances.
- Material Characterization:Fourier-transform infrared spectroscopy identifies polymer composition and additive packages.
- Microbial Analysis:Aerobic plate counts and pathogen screening verify sterile barrier performance.
- Mechanical Testing:Tensile strength and puncture resistance protocols validate transport durability.
Migration testing holds installed capacity. Seal integrity is rotating up the share rankings.
Packaging Material:
Application exposure determines regulatory complexity and decomposition screening requirements.
- Plastic Films:Layered polymer structures dominate current revenue pools due to extraction study complexity across coextruded barriers. EFSA migration limits for primary aromatic amines and India's FSSAI heavy metal leachate directives expand mandatory testing volumes for film converters.
- Biodegradable Materials:Polylactic acid and cellulose-based substrates require novel decomposition-byproduct screening that legacy petroleum-based testing suites cannot execute. Germany's packaging exporters drive early standardization demand.
- Paperboard:Recycled fiber content raises extractable heavy metal concerns.
- Metal Cans:Interior coating migration and corrosion resistance testing.
- Glass Containers:Thermal shock and chemical durability validation.
Plastic films hold installed capacity. Biodegradable materials are climbing the fastest.
Application:
Customer risk tolerance separates commodity validation from high-liability spoilage prevention protocols.
- Ready-to-Eat Meals:Modified atmosphere packaging failures carry substantial food safety liability, concentrating testing spend toward integrated lifecycle services. North American producers require migration testing for plastic films under FDA food contact notification frameworks.
- Fresh Produce:Ethylene permeability and moisture vapor transmission testing preserves shelf life. Demand concentrates with export-oriented operations serving extended distribution networks.
- Frozen Foods:Cold-chain durability and seal integrity under thermal cycling.
- Beverages:Flavor scalping and carbonation retention validation.
- Confectionery:Fat bloom prevention and aroma barrier testing.
Ready-to-eat meals hold installed capacity. Fresh produce is rotating up the share rankings.
End User:
Supply chain position determines captive versus outsourced testing economics and certification timeline pressures.
- Contract Testing Services:Asset-light leasing models for spectroscopy and chromatography equipment reconfigure capital barriers for mid-tier laboratories. Geographic laboratory network coverage rewards providers serving Germany and India's tightening compliance requirements.
- Quality Assurance Labs:Captive facilities at multinational food processors face disintermediation pressure from integrated third-party certification bodies.
- Packaging Manufacturers:Raw material validation to finished goods release protocols.
- Food Processors:Campaign-based procurement models compress testing service engagement cycles.
Contract testing services hold installed capacity. Quality assurance labs are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food contact notification rules in the United States, EFSA migration limits across European polymer supply chains, and India's FSSAI packaging safety directives are expanding mandatory testing scopes and reshaping geographic demand concentration.
United States
Ready-to-eat meal producers in the Midwest and Southeast require migration testing for plastic films to comply with FDA food contact notification rules. Modified atmosphere packaging validation concentrates margin pools where barrier failures trigger substantial food spoilage liability. Chicago and Atlanta host contract testing laboratories serving pan-American distribution networks.
Germany
German food packaging exporters serving pan-European distribution networks require centralized multi-country certification coverage. EFSA migration limits for primary aromatic amines in plastic food contact materials expand mandatory extraction study volumes for polymer film producers. The Rhine-Ruhr and Bavarian industrial clusters anchor migration testing demand for dairy and meat packaging segments.
India
India's FSSAI has extended mandatory testing scopes beyond microbial limits into heavy metal leachate quantification, creating new compliance service demand from domestic and export-oriented food processors. BIS packaging standards are tightening alongside FSSAI directives. Maharashtra and Gujarat concentrate contract testing services for flexible film converters.
China
Polylactic acid and cellulose-based packaging materials entering commercial food service channels require novel decomposition-byproduct screening protocols. GB standards for food contact materials are expanding substance-specific testing mandates. The Yangtze River Delta and Pearl River Delta host polymer multilayer structure manufacturers driving migration testing volume.
Japan
JIS standards for food contact materials and METI guidance on biodegradable packaging substrates shape testing requirements for export-oriented polymer converters. Seal integrity validation for ready-to-eat meals concentrates demand in the Kanto region. Tokyo and Osaka anchor quality assurance laboratory networks serving processed food manufacturers.
Food Packaging Testing Market Competitive Landscape
On the supply side, the industry is consolidating around integrated certification bodies with geographic laboratory networks and specialized migration testing capabilities. Tiered competition separates asset-heavy global providers from mid-sized regional laboratories accessing equipment through leasing arrangements. Two strategic archetypes dominate: integrated lifecycle service providers spanning raw material validation to finished goods release, and specialized migration testing laboratories with polymer-specific extraction study expertise. Dominant competitive moves include geographic laboratory network expansion and equipment-as-a-service partnerships that reconfigure capital barriers for mid-tier entrants.
Within the integrated certification tier, SGS S.A., Eurofins Scientific SE, and Intertek Group PLC exemplify providers leveraging multi-country laboratory coverage to sustain certification reciprocity across FDA, EFSA, and FSSAI jurisdictions. These entities occupy positions where buyer consolidation among multinational food processors compresses procurement cycles toward campaign-based engagement models. Specialized equipment manufacturers including Agilent Technologies, Inc. and Thermo Fisher Scientific Inc. sit upstream, supplying gas chromatography-mass spectrometry and spectroscopy systems that enable parts-per-billion detection thresholds.
| Leading Market Players |
|---|
| SGS S.A. |
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Bureau Veritas |
| 3M Company |
| Bio-Rad Laboratories, Inc. |
| Intertek Group PLC |
| Merck KGaA |
| Eurofins Scientific SE |
| Others |
Supply & Pricing Matrix
Undercapacity in European spectroscopy instrument manufacturing is compressing lead times for gas chromatography-mass spectrometry systems and tilting pricing power toward equipment lessors who can guarantee delivery slots. This utilization squeeze propagates downstream into testing service rates, where laboratories with secured instrument access command premium positioning against competitors facing capital deployment delays.
Pricing Analysis
Certification level creates the primary spread between economy and premium testing tiers, with FDA-grade migration studies commanding substantial premiums over standard ISO protocols. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales documentation intensity and regulatory submission support bundling. Cost compression in the economy tier is intensifying because asset-light leasing models are democratizing access to chromatography capacity. Small contract laboratories exhibit highest price sensitivity, while multinational food processors prioritize certification timeline certainty over rate negotiation.
Supply Chain Analysis
Helium feedstock draws from concentrated extraction operations in Qatar, Algeria, and Russia, creating single-source vulnerability for gas chromatography-mass spectrometry operations. Fourier-transform infrared spectroscopy systems rest on germanium and tellurium component supply anchored in China and Belgium. Tariff exposure runs through precision optical element imports. Distribution runs through authorized equipment distributors serving regional laboratory clusters, with aftermarket service contracts extending supplier capture over testing facility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent testing providers face substitution pressure from spectroscopic fingerprinting platforms digitizing contaminant detection workflows, requiring defensive repositioning around regulatory submission integration capabilities.
For Market Incumbents: Harden certification reciprocity coverage across FDA, EFSA, and FSSAI jurisdictions to defend against disintermediation by integrated lifecycle service providers. Deepen backward integration into polymer-specific extraction study expertise, concentrating investment in migration testing capacity for layered film structures where regulatory complexity sustains margin pools.
For New Entrants and Emerging Players: Establish a beachhead in biodegradable substrate screening protocols, where polylactic acid and cellulose-based packaging chemistries lack standardized testing suites. Target German food packaging exporters requiring centralized multi-country certification coverage, leveraging equipment-as-a-service partnerships to bypass capital intensity barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract testing services with geographic laboratory network coverage serving tightening EFSA and FSSAI compliance requirements. Long-term viability hinges on migration testing specialization rather than commoditized mechanical validation. Acquisition candidates should demonstrate established extraction study protocols for polymer multilayer structures. Watch helium supply allocation rationing as an inflection indicator for input cost volatility exposure across chromatography-dependent laboratories.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Laboratory Network Expansion | Multi-country certification coverage consolidates procurement from pan-European food packaging exporters. |
| Equipment-as-a-Service Partnership | Asset-light leasing reconfigures capital barriers for mid-tier migration testing capacity expansion. |
| Biodegradable Substrate Protocol Development | Novel decomposition-byproduct screening captures fastest-growing material chemistry segment demand. |
| Regulatory Submission Integration | Real-time documentation preparation compresses FDA food contact notification timeline risk. |
| Helium Supply Diversification | Alternative carrier gas qualification mitigates geopolitical disruption exposure for chromatography operations. |
Research Methodology
Desk research of regulatory filing databases, customs trade records, and equipment manufacturer technical specifications preceded structured interviews with contract testing laboratory directors, food packaging procurement managers, polymer converter technical leads, and regulatory affairs specialists at certification bodies. Primary fieldwork combined telephone and video interviews with secondary validation against FDA food contact notification submissions, EFSA scientific opinions, and FSSAI directive amendments. Bottom-up testing volume estimates triangulated against top-down market sizing derived from spectroscopy and chromatography instrument shipment data.
Forecast assumptions held helium supply concentration and regulatory reciprocity gaps as fixed structural conditions while varying biodegradable substrate adoption rates and equipment leasing penetration across the projection horizon. Segmentation modeling captured testing type, packaging material chemistry, application liability exposure, and end-user supply chain position. CAGRs derived from regression analysis against historical compliance mandate expansion patterns, with specific inputs including EFSA migration limit revision frequency and India FSSAI enforcement escalation trajectory.
Macroeconomic conditions sit as an overlay; deviation in food processor capital expenditure cycles or polymer raw material pricing would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement continuity rather than policy reversal scenarios. Cross-checking against instrument manufacturer order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Europe Package Testing Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Bottle Perpendicularity Tester Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Packaging Inspection Systems Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Middle East and Africa Package Testing Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Global Package Testing Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Food Packaging Tester Market