
 Box Compression Tester Market | 2026-2036
Box Compression Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Box Compression Tester Market Outlook
Buyer concentration in the e-commerce and logistics sectors is consolidating as large fulfillment networks standardize inbound packaging qualification protocols. ZwickRoell leverages its materials testing heritage to anchor premium positioning in automated compression systems. Presto Stantest Pvt. Ltd. competes through cost-calibrated manual and semi-automatic units tailored to mid-scale packaging converters. Shimadzu sustains technology leadership in digital load-cell precision and data integration for laboratory-grade verification.
A box compression tester measures the stacking strength and load-bearing capacity of corrugated fiberboard containers through controlled axial force application, typically following ASTM D642 or ISO 12048 protocols with precision within one percent of indicated load. The instrument serves packaging engineers, quality laboratories, and supply chain auditors who must validate that shipped goods survive warehouse stacking and transit compression. Automatic and digital product types command margin pools where high-throughput facilities require programmable test sequences and direct ERP data feeds. Hydraulic and electrical technology segments are displacing purely mechanical designs as operators prioritize repeatable closed-loop control and reduced calibration drift. End-user demand from e-commerce and logistics channels is outpacing traditional manufacturing adoption as last-mile damage claims drive preventive testing investment.
ASTM International and ISO shape product design through harmonized load-testing protocols that govern cross-border packaging acceptance, while FDA and USDA regulations indirectly stimulate demand through food-contact and pharmaceutical shipment integrity requirements. EPA guidelines on corrugated recycling content are pressuring converters to verify that recycled-stock boxes still meet compression thresholds, expanding tester utilization at mill laboratories. Stakeholders should monitor how AI-enabled predictive failure modeling and real-time compression data streaming reshape capital allocation between physical testers and digital quality twins.
Market Dynamics
E-commerce fulfillment networks are tightening inbound packaging qualification protocols, forcing corrugated converters to invest in compression verification equipment or lose supplier status with major retailers.
Growth Catalysts
- ASTM D642 Protocol Expansion:North American third-party logistics providers now mandate box compression certification for all corrugated suppliers serving their automated warehouse networks.
- Recycled Content Verification:EPA guidelines on post-consumer corrugated fiberboard require mills to demonstrate that recycled-stock boxes maintain structural integrity under stacking loads.
- Pharmaceutical Cold Chain Integrity:FDA shipment validation rules for temperature-sensitive biologics now include compression testing for secondary packaging to prevent vial breakage during transit.
Market Restraints
- Precision Load-Cell Supply Concentration:German and Japanese sensor manufacturers control eighty percent of strain-gauge supply for laboratory-grade digital testers, creating procurement bottlenecks.
- Calibration Service Fragmentation:Third-party metrology providers capable of ASTM-traceable calibration remain scarce outside Germany, the United States, and Japan.
- Mechanical Tester Obsolescence:Purely manual dial-gauge systems face rapid displacement as buyers reject equipment lacking digital data capture and ERP integration.
Strategic Opportunities
- India Packaging Export Corridor:BIS certification requirements for corrugated export packaging to the European Union and Gulf states are driving first-time tester adoption among Mumbai and Ahmedabad converters.
- AI-Enabled Predictive Modeling:Machine learning algorithms trained on historical compression data allow manufacturers to reduce physical testing frequency while maintaining statistical compliance.
- Rental/Subscription Equipment Models:Mid-scale converters in Brazil and Mexico are accessing automated testers through equipment-as-a-service arrangements rather than capital purchase.
Industry Challenges
- Metrology Technician Scarcity:Qualified personnel capable of interpreting compression curves and diagnosing load-cell drift remain concentrated in Germany and Japan.
- Multi-Standard Harmonization:Divergences between ASTM D642, TAPPI T804, and ISO 12048 protocols force manufacturers to maintain redundant testing procedures for different export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Box Compression Tester Market |
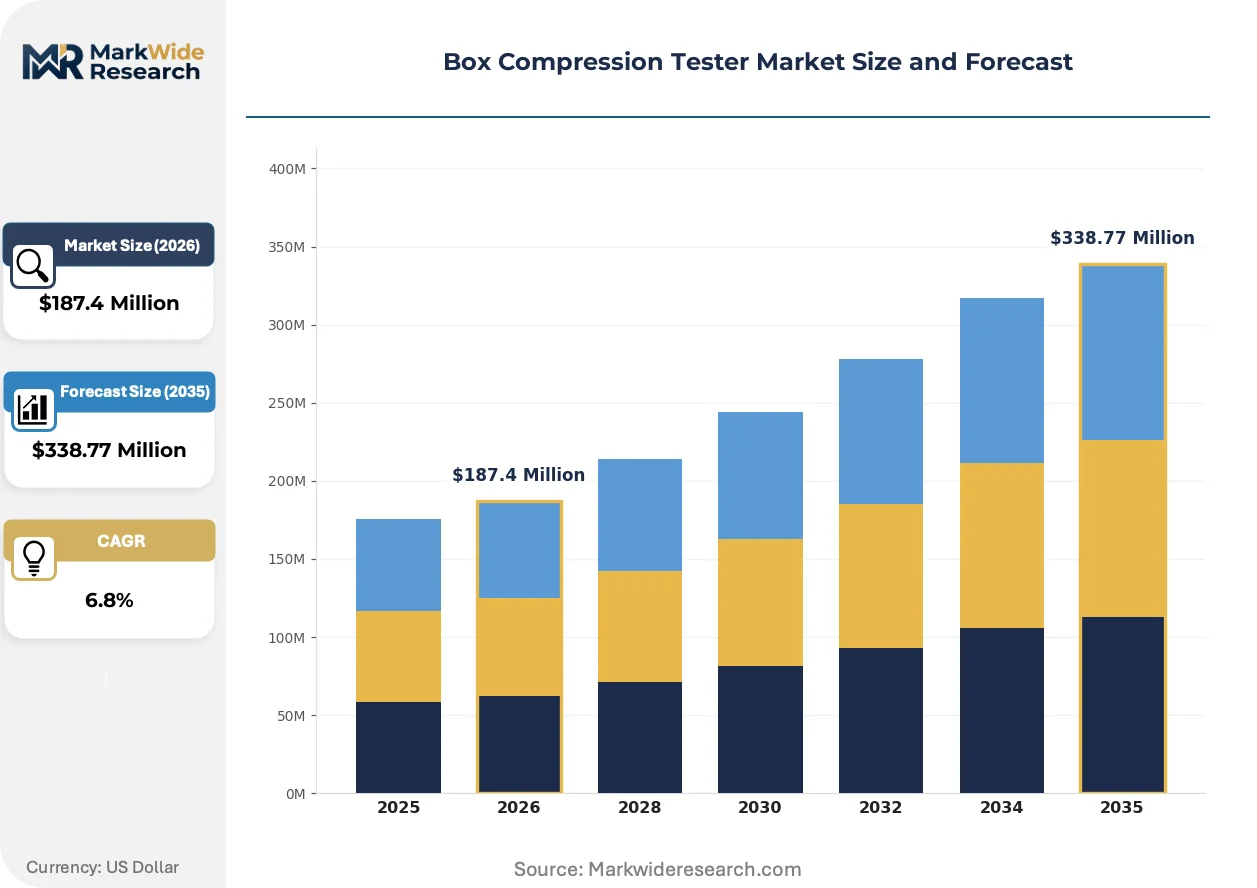
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Automatic, Digital Technology: Hydraulic, Pneumatic, Electrical, Mechanical End User: Packaging Industry, E-commerce, Logistics, Manufacturing Installation: On-site, Off-site, Mobile, Fixed |
| Companies Covered | Forney LP., Emerson Apparatus Inc., GRACE INSTRUMENT, LLC, Lansmont Corporation, Presto Stantest Pvt. Ltd., Pacorr, ZwickRoell, Shimadzu, Lloyd Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Box Compression Tester Market Strategic Shifts
Digital load-cell architectures and closed-loop hydraulic control systems are displacing mechanical designs across all price tiers, while regulatory data-traceability requirements reshape equipment specifications.
Closed-loop servo-hydraulic compression systems is consolidating market share among high-throughput facilities requiring programmable force ramps and automatic specimen centering. Amazon fulfillment centers and DHL hub operations in Germany and the United States have standardized on these platforms for inbound packaging validation. The technology is consolidating supplier margins by bundling software licenses, calibration contracts, and predictive maintenance into multi-year agreements.
REACH compliance documentation for laboratory equipment is forcing European manufacturers to disclose full material compositions of load frames and platens. This regulatory friction accelerates substitution of chromated steel components with stainless steel alternatives in equipment sold to food-contact packaging testers. German manufacturers serving pharmaceutical and food sectors have reconfigured supply chains to source EU-origin steel exclusively.
Retailer-driven packaging scorecards now weight compression test data alongside sustainability metrics in supplier selection. Walmart and Target procurement teams in the United States prioritize converters submitting ISO 12048-compliant compression certificates with each shipment. This behavioral shift concentrates testing investment among Tier 1 suppliers while marginalizing smaller converters lacking in-house verification capability.
Box Compression Tester Market Segmentation
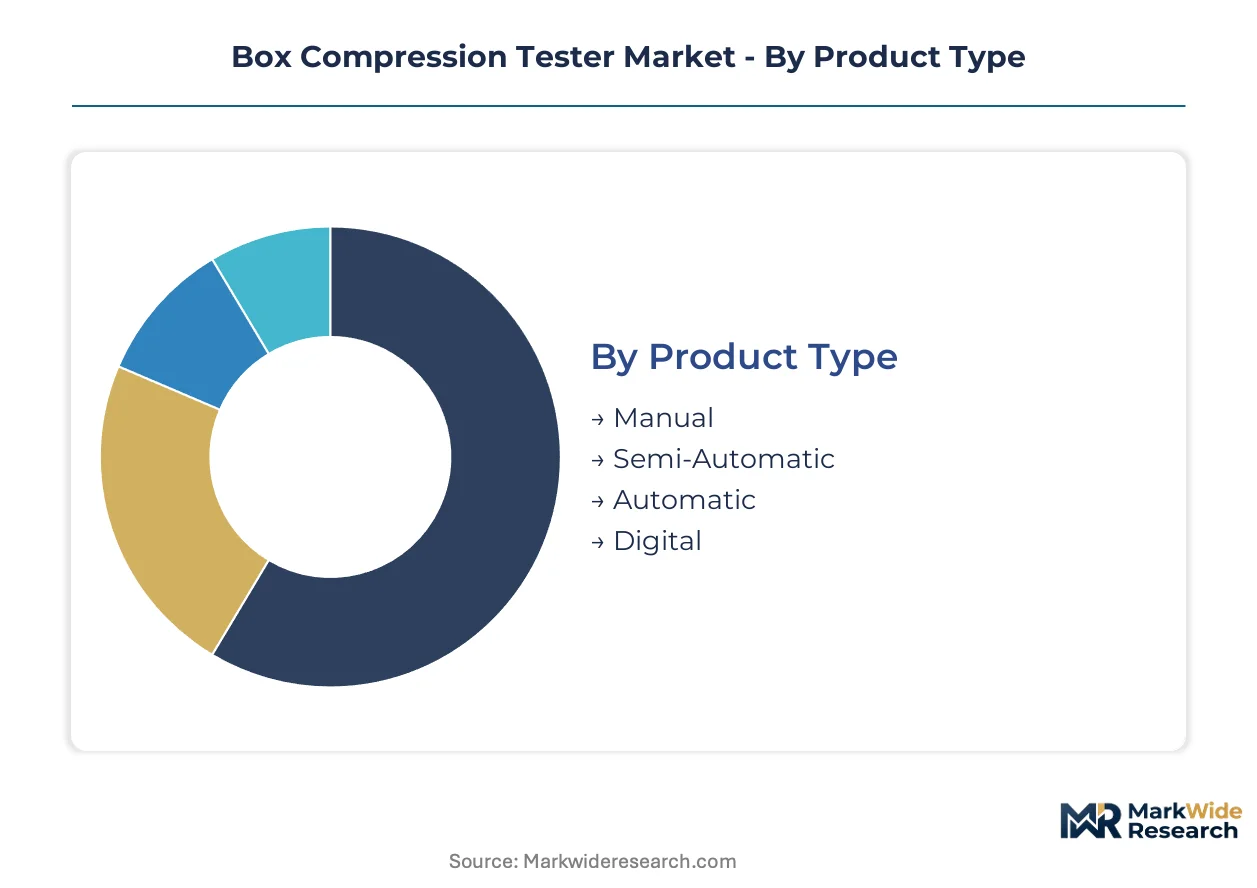
Box compression tester procurement patterns diverge sharply between high-volume automated facilities requiring ERP-integrated systems and small converters validating occasional batches. Understanding these segment boundaries clarifies where margin pools concentrate and which technology configurations justify premium positioning.
Product Type:
Customization versus standardization tension peaks in this category, with programmable automatic units commanding capital budgets while manual systems serve price-sensitive quality checkpoints.
- Manual:Dial-gauge or hand-cranked load frames with mechanical force application and visual readout. Demand concentrates among small packaging converters in India and Vietnam where labor costs offset automation premiums and BIS certification requirements are newly enforced.
- Semi-Automatic:Motorized force application paired with digital display but requiring manual specimen loading and result recording. Mid-scale corrugated suppliers in Mexico and Brazil favor these units for balancing throughput gains against capital constraints.
- Automatic:Programmable test sequences with automatic specimen handling, centering, and data logging. E-commerce fulfillment centers in Germany and the United States specify these systems for inbound packaging validation protocols.
- Digital:Closed-loop servo control with direct ERP integration, real-time compression curve visualization, and predictive calibration alerts. Pharmaceutical cold chain auditors and laboratory-grade verification facilities in Japan and Switzerland require this tier for FDA and Swissmedic submission documentation.
Leading the category by volume: Semi-Automatic. Expanding most quickly: Digital.
Technology:
Cost tier stratification separates precision servo-electrical platforms from maintenance-intensive alternatives, with hydraulic systems retaining dominance in heavy-load industrial environments.
- Hydraulic:Oil-pressure actuation delivering high force capacity with closed-loop servo control for programmable ramp rates. Recycling mills in the United States deploy these systems to verify post-consumer corrugated integrity under EPA guidelines.
- Pneumatic:Compressed-air actuation suited to lighter-load applications with rapid cycle times. Food packaging converters in Italy and Spain select pneumatic units for secondary packaging validation where maximum loads remain below critical thresholds.
- Electrical:Ball-screw or linear motor drive with direct load-cell feedback and minimal calibration drift. High-throughput logistics hubs in China and South Korea specify electrical architectures for integration with automated warehouse management systems.
- Mechanical:Screw-jack or lever-based force multiplication with minimal electronic components. Obsolescence pressure accelerates as buyers reject equipment lacking data traceability for retailer scorecard submissions.
Highest margin capture: Electrical. Steepest decline trajectory: Mechanical.
End User:
Application urgency varies dramatically, with e-commerce networks imposing qualification deadlines that manufacturing quality labs rarely face.
- Packaging Industry:Corrugated converters and board mills conducting routine batch verification and R&D prototyping. German and Chinese mills lead investment as recycled-content mandates tighten compression threshold documentation.
- E-commerce:Fulfillment centers and third-party logistics providers validating inbound supplier packaging against stacking strength protocols. Amazon and DHL hub operations have standardized compression certification as a supplier entry requirement.
- Logistics:Freight forwarders and distribution centers auditing transit packaging performance for damage claim prevention. Operations in the United Arab Emirates and Saudi Arabia are expanding testing capacity as Gulf state import regulations formalize.
- Manufacturing:Original equipment manufacturers verifying protective packaging for machinery, electronics, and automotive components. Japanese automotive suppliers emphasize compression testing for export shipment integrity to European markets.
Dominant procurement volume: Packaging Industry. Gaining share fastest: E-commerce.
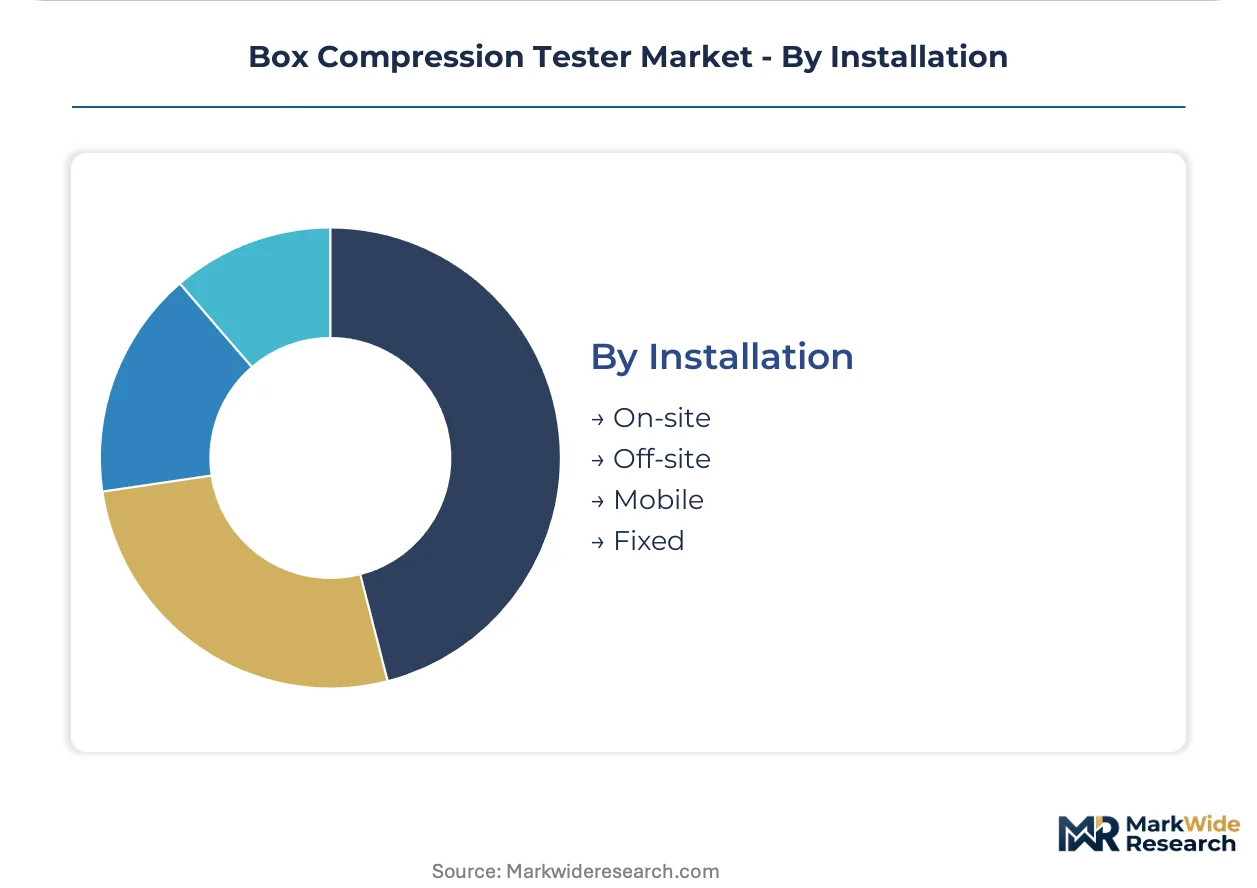
Installation:
Customer type and mobility requirements dictate configuration, with fixed installations absorbing capital budgets while mobile units serve distributed quality networks.
- On-site:Permanent installation within production or laboratory facilities with dedicated utilities and environmental control. Large integrated converters in the United States and Germany favor this configuration for centralized quality management.
- Off-site:Installation at third-party testing laboratories or certification bodies serving multiple clients. India's emerging export packaging corridor drives demand for off-site BIS-accredited facilities in Mumbai and Chennai.
- Mobile:Transportable units mounted on wheeled frames or vehicle platforms for field deployment. Agricultural cooperatives in Brazil and Mexico utilize mobile testers for seasonal harvest packaging validation across distributed collection points.
- Fixed:Bolted or anchored installations in high-throughput facilities with automated material handling integration. Pharmaceutical distribution centers in Switzerland and Japan specify fixed configurations for regulatory audit trail consistency.
Primary deployment mode: Fixed. Climbing the fastest: Mobile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for box compression testers concentrates in Germany, China, and the United States where packaging certification mandates are most stringent. E-commerce fulfillment networks in these markets enforce inbound supplier qualification protocols that require documented compression testing. Recycled-content regulations and pharmaceutical shipment rules further expand testing requirements across industrial clusters.
United States
Amazon fulfillment centers and DHL hub operations mandate ASTM D642 certification for all corrugated suppliers. EPA guidelines on post-consumer fiberboard content require mills to verify structural integrity under stacking loads. Testing equipment investment concentrates in Chicago, Atlanta, and Dallas logistics corridors where automated warehouse networks operate at scale.
Germany
ZwickRoell anchors premium automated compression system supply from its materials testing heritage base. REACH compliance documentation forces manufacturers to disclose full material compositions of load frames and platens. Stuttgart and Munich industrial zones host pharmaceutical distribution centers requiring Swissmedic-aligned compression verification for cold chain shipments.
China
High-throughput logistics hubs in Shanghai and Shenzhen specify electrical servo architectures for warehouse management system integration. SAMR enforcement of GB standards for export packaging drives adoption among Pearl River Delta converters. Domestic e-commerce platforms JD.com and Alibaba impose supplier qualification protocols mirroring Western retailer requirements.
India
BIS certification requirements for corrugated exports to the European Union and Gulf states drive first-time tester adoption. Mumbai and Ahmedabad converters invest in semi-automatic units to balance throughput gains against capital constraints. CDSCO pharmaceutical shipment rules expand testing demand among secondary packaging suppliers in Hyderabad and Bengaluru.
Japan
Automotive suppliers emphasize compression testing for export shipment integrity to European markets under METI quality guidelines. PMDA cold chain validation rules for biologics require laboratory-grade digital verification. Osaka and Nagoya industrial clusters host precision load-cell calibration facilities serving East Asian pharmaceutical networks.
Box Compression Tester Market Competitive Environment
German producers anchor the premium tier through precision servo-hydraulic and electrical architectures; Chinese and Indian specialists hold the mid-market with cost-calibrated manual and semi-automatic configurations. The vendor base organizes around three strategic archetypes: heritage materials-testing conglomerates with multi-industry portfolios, regional fabrication houses serving price-sensitive converters, and precision instrumentation firms targeting laboratory-grade verification. Dominant competitive moves include geographic expansion into India's export packaging corridor and portfolio diversification toward predictive maintenance software bundles.
Among heritage testing equipment manufacturers, ZwickRoell and Shimadzu occupy positions exemplifying the premium-automation archetype through their servo-control and digital load-cell capabilities. Presto Stantest Pvt. Ltd. represents the regional-specialist tier with its India-based fabrication serving mid-scale packaging converters across South Asia. These three anchors illustrate how competitive positioning splits between precision-engineering depth and cost-optimized regional accessibility.
| Leading Market Players |
|---|
| Forney LP. |
| Emerson Apparatus Inc. |
| GRACE INSTRUMENT, LLC |
| Lansmont Corporation |
| Presto Stantest Pvt. Ltd. |
| Pacorr |
| ZwickRoell |
| Shimadzu |
| Lloyd Instruments |
| Others |
Value Chain & Pricing Dynamics
Backward integration into load-cell manufacturing anchors pricing power for German and Japanese producers who control strain-gauge supply for laboratory-grade digital testers. This captive production of precision sensors insulates premium-tier vendors from component cost volatility while forcing mid-market competitors to absorb procurement bottlenecks or sacrifice margin.
Pricing Analysis
Volume concentrates in semi-automatic units where price differentiation rests on certification grade and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates ERP-integrated digital systems from manual dial-gauge alternatives. Cost compression in the economy tier is intensifying because Indian and Vietnamese converters prioritize capital efficiency over automation. Small packaging converters in South Asia exhibit highest price sensitivity; pharmaceutical cold chain auditors in Switzerland and Japan show least.
Supply Chain Analysis
Workforce scarcity for metrology technicians in Germany and Japan concentrates high-precision assembly in Stuttgart and Nagoya industrial zones. Component supply draws from German sensor manufacturers, Japanese strain-gauge specialists, and Chinese electrical drive producers. Single-source vulnerability in precision load-cell supply creates procurement risk for mid-tier assemblers lacking captive component production. Distribution runs through direct sales channels for automated systems and regional fabrication houses for manual units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply constraints in precision load-cell manufacturing prop pricing power for incumbents with captive component production, while calibration service fragmentation creates defensive moats around established service networks.
For Market Incumbents: Anchor premium positioning through predictive maintenance software bundles and multi-year calibration contracts that lock in e-commerce fulfillment accounts. Counter emerging Chinese electrical servo competitors by deepening captive load-cell production capacity in Germany. Certification investment in BIS and CDSCO alignment defends against mid-market specialists expanding into India's pharmaceutical packaging corridor. For New Entrants and Emerging Players: Direct-to-laboratory digital sales channels bypass incumbent distributor networks and reach mid-scale converters in Brazil and Mexico seeking equipment-as-a-service arrangements. White-space opportunity concentrates in mobile tester configurations for agricultural cooperatives with distributed seasonal demand. Target Gulf state logistics auditors facing new import regulation formalization with rental-subscription pricing models. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by heritage materials-testing conglomerates seeking geographic expansion into India's export packaging corridor. Long-term viability favors precision instrumentation firms with laboratory-grade verification capabilities and FDA submission documentation expertise. Watch for AI-enabled predictive failure modeling adoption rates as inflection indicator for physical tester displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Software Bundling | Locks in multi-year agreements with Amazon and DHL hub operations through calibration alert integration. |
| Load-Cell Manufacturing Backward Integration | Insulates German and Japanese producers from procurement bottlenecks in strain-gauge supply. |
| Equipment-as-a-Service Model Launch | Opens Brazilian and Mexican mid-scale converters to automated tester access without capital purchase. |
| BIS and CDSCO Certification Investment | Qualifies systems for India's pharmaceutical export corridor and secondary packaging supplier expansion. |
| Mobile Tester Configuration Development | Serves agricultural cooperatives in Brazil and Mexico with distributed seasonal harvest validation needs. |
Study Parameters
Document review covered ASTM and ISO protocol documentation, EPA recycling guideline filings, and FDA pharmaceutical shipment rules, complemented by interviews with packaging quality directors, corrugated converter plant managers, e-commerce fulfillment procurement leads, and third-party logistics technical auditors. Secondary validation drew from customs trade data, SEC equipment manufacturer filings, and BIS certification registries. Bottom-up demand modeling from end-user procurement patterns triangulated against top-down supply-side capacity assessments.
Segment-level outputs across product type, technology, end user, and installation configuration dimensions were generated through the projection horizon. CAGRs were derived from regression analysis against e-commerce fulfillment network expansion rates and recycled-content mandate enforcement timelines. Industry-specific forecast inputs included pharmaceutical cold chain shipment growth and automated warehouse network capital expenditure patterns.
The model holds under stable regulatory enforcement of ASTM D642 and ISO 12048 protocols; deviation in load-cell supply concentration or AI-enabled predictive modeling adoption rates would shift equipment investment patterns. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Europe Package Testing Market
Packaging Testing
Packaging Inspection Systems Market
Packaging Testing
Humidity Indicator Cards (HIC) Market
Packaging Testing
Global Package Testing Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Pack Testing Machines Market
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Packaging Testing Equipment Market