

Packaging Burst Strength Test Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Burst Strength Test Market Insights
North American contract testing laboratories is recalibrating capacity allocation toward pharmaceutical and medical device validation services. Smithers leverages decades of materials science expertise to anchor premium testing contracts with FDA-regulated medical device manufacturers. Nelson Labs competes through specialized sterile barrier validation protocols that align with USP <1207> container closure integrity standards. Westpak sustains geographic dominance across California's biomedical packaging cluster, operating ISO 17025-accredited facilities that serve both domestic and export-bound pharmaceutical clients.
Packaging burst strength testing measures the maximum internal pressure a sealed package withstands before rupture, typically expressed in kilopascals or pounds per square inch, using hydraulic or pneumatic pressurization methods to simulate real-world stress conditions. The procedure validates seal integrity for sterile medical devices, food retort pouches, and pharmaceutical blisters where containment failure risks product loss or contamination. Fully automatic testers command the highest margin pools due to throughput advantages in high-volume pharmaceutical quality control labs, while manual testers retain relevance in small-batch medical device prototyping. Pneumatic methods are displacing hydraulic systems in cleanroom environments where oil-free operation prevents particulate contamination of sterile barriers.
FDA's 21 CFR Part 820 quality system regulation and ISO 11607-1 sterilization packaging standards create binding validation requirements that directly shape equipment procurement cycles for burst strength testers. The EU Medical Device Regulation and REACH chemical compliance frameworks further tighten material traceability, forcing European manufacturers to document burst test data across supplier tiers. Stakeholders must monitor evolving harmonization between FDA's updated sterile packaging guidance and the EU MDR's post-market surveillance requirements, as divergence in acceptance criteria would fragment testing protocols and equipment specifications across Atlantic supply chains.
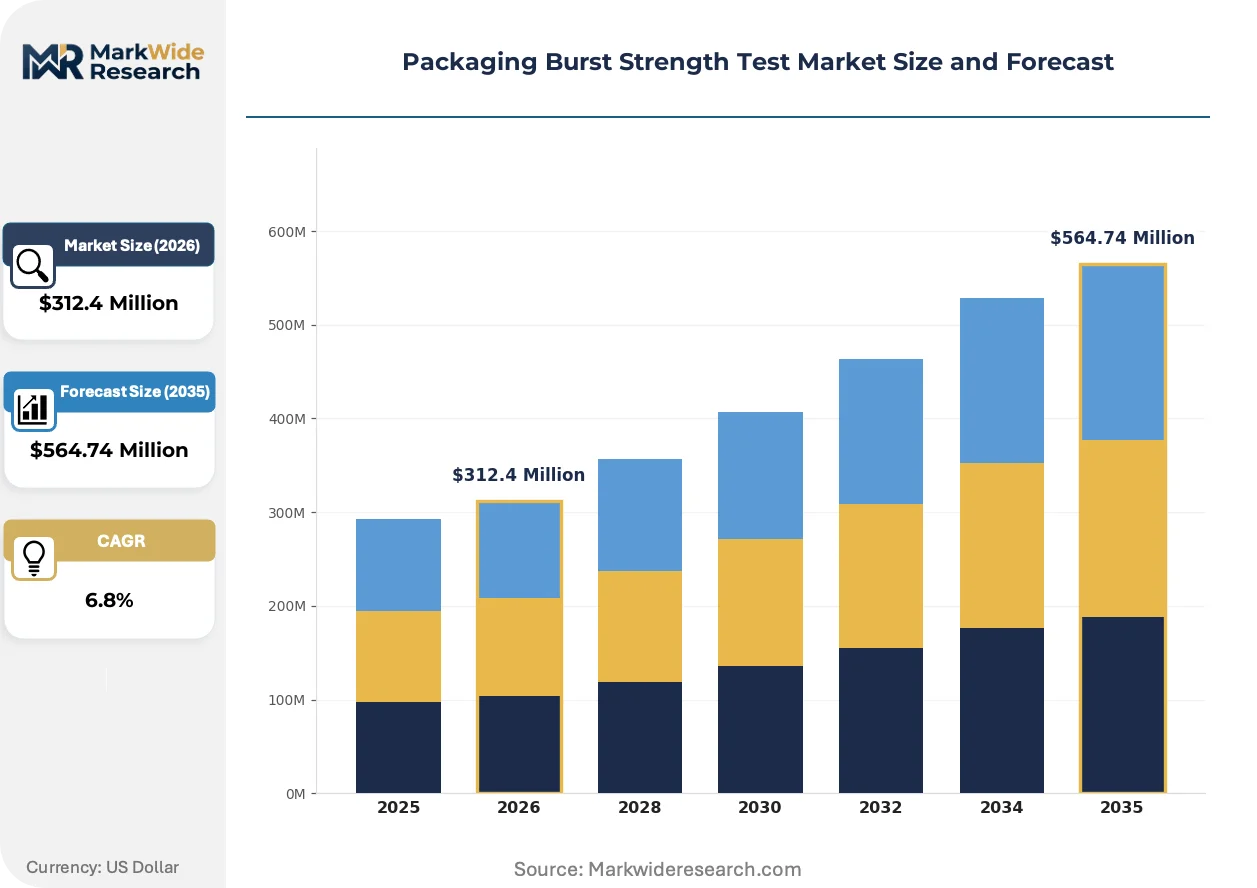
Market Dynamics
Pharmaceutical serialization mandates in the United States and Europe are compressing validation timelines for sterile barrier systems, forcing burst strength testing from periodic quality checks into continuous production-line integration.
Growth Catalysts
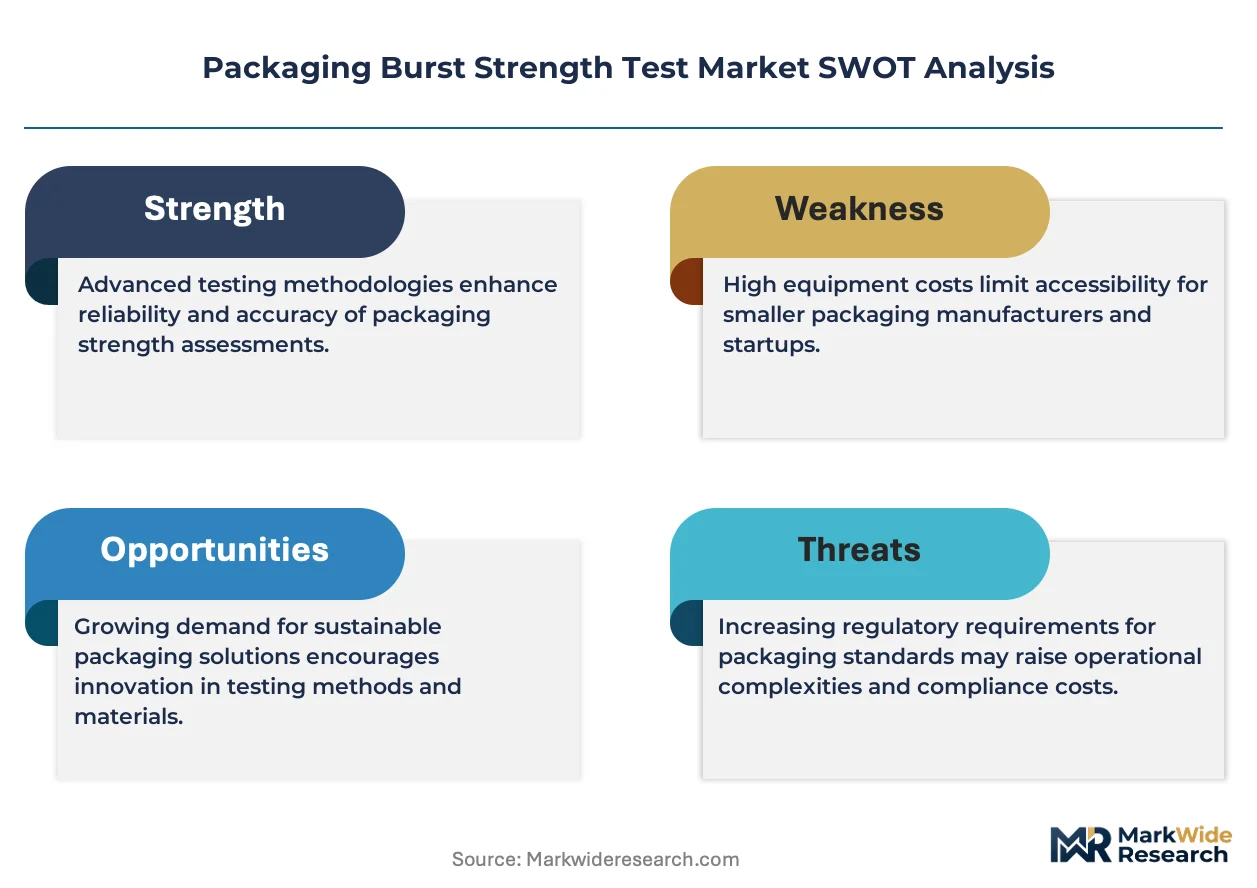
- EU MDR sterilization packaging standards:Terminally sterilized medical devices now require documented burst test data across supplier tiers, expanding equipment procurement cycles for European manufacturers.
- Pneumatic pressurization methods:Oil-free operation prevents particulate contamination in cleanroom environments, accelerating displacement of hydraulic systems in pharmaceutical quality control labs.
- Germany's medical device packaging corridor:Burst testing integrates with ISO 11607 compliance workflows, concentrating demand in specialized validation service clusters around Stuttgart and Munich.
Market Restraints
- High-precision sensor costs:Piezoelectric pressure transducers and calibrated orifice plates constitute 35-40% of fully automatic tester bill-of-materials, compressing margins for mid-tier equipment vendors.
- Supply concentration in precision machining:CNC-manufactured test fixtures and burst diaphragms rely on specialized German and Swiss machine shops, creating single-source vulnerabilities.
- REACH chemical compliance documentation:Material traceability requirements for elastomeric seals and hydraulic fluids impose administrative burdens that extend European equipment qualification timelines.
Strategic Opportunities
- India's pharmaceutical export sector:CDSCO alignment with FDA quality system regulations creates demand for ISO 17025-accredited burst testing capacity serving ANDA filers and contract manufacturers.
- Biologics cold chain packaging:Temperature excursion-resistant flexible containers for mRNA vaccines require novel burst validation protocols at ultra-low temperatures.
- Digital twin integration:Finite element modeling of seal failure modes converges with physical testing to reduce prototype iterations in medical device development cycles.
Industry Challenges
- ISO 17025 assessor availability:Accredited metrology laboratories face 6-12 month backlogs for burst tester calibration and measurement uncertainty verification.
- Legacy hydraulic system retrofit complexity:Existing installed bases require extensive plumbing and control architecture modifications to accommodate pneumatic conversion kits.
- Cross-harmonization between FDA and EU MDR:Divergence in acceptance criteria for seal integrity validation fragments testing protocols across Atlantic supply chains.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Burst Strength Test Market Trends and Innovations
Real-time data capture and machine learning classification of failure modes are transforming burst strength testing from destructive quality control into predictive process optimization tools for high-volume pharmaceutical operations.
Machine vision systems are integrating with pneumatic burst testers to correlate seal deformation patterns with pressure-time curves, enabling root-cause classification of adhesive failures versus material ruptures. Medical device manufacturers in Minnesota and Massachusetts are deploying these hybrid systems to reduce false-positive rejection rates in sterile barrier validation. The technology is integrating statistical process control databases with enterprise quality management systems, compressing deviation investigation timelines from days to hours.
REACH Annex XVII restrictions on perfluorinated compounds are forcing reformulation of barrier coatings used in retort pouch applications, requiring recalibration of burst test acceptance thresholds across European food packaging operations. The European Chemicals Agency's substance evaluation roadmap now includes sealant polymers previously exempt from migration testing. Retort processors in Italy and Spain are responding by commissioning multi-variable burst studies that correlate coating chemistry with heat-seal performance degradation.
Contract testing laboratories are unbundling validation services from equipment sales, allowing pharmaceutical clients to access ISO 17025-accredited burst testing without capital expenditure on dedicated systems. This service model is displacing in-house quality lab construction among mid-scale generic drug manufacturers. The shift is most visible in California's biomedical packaging cluster, where shared-access testing facilities now handle burst validation for multiple ANDA holders under single quality agreements.
Packaging Burst Strength Test Market Segmentation
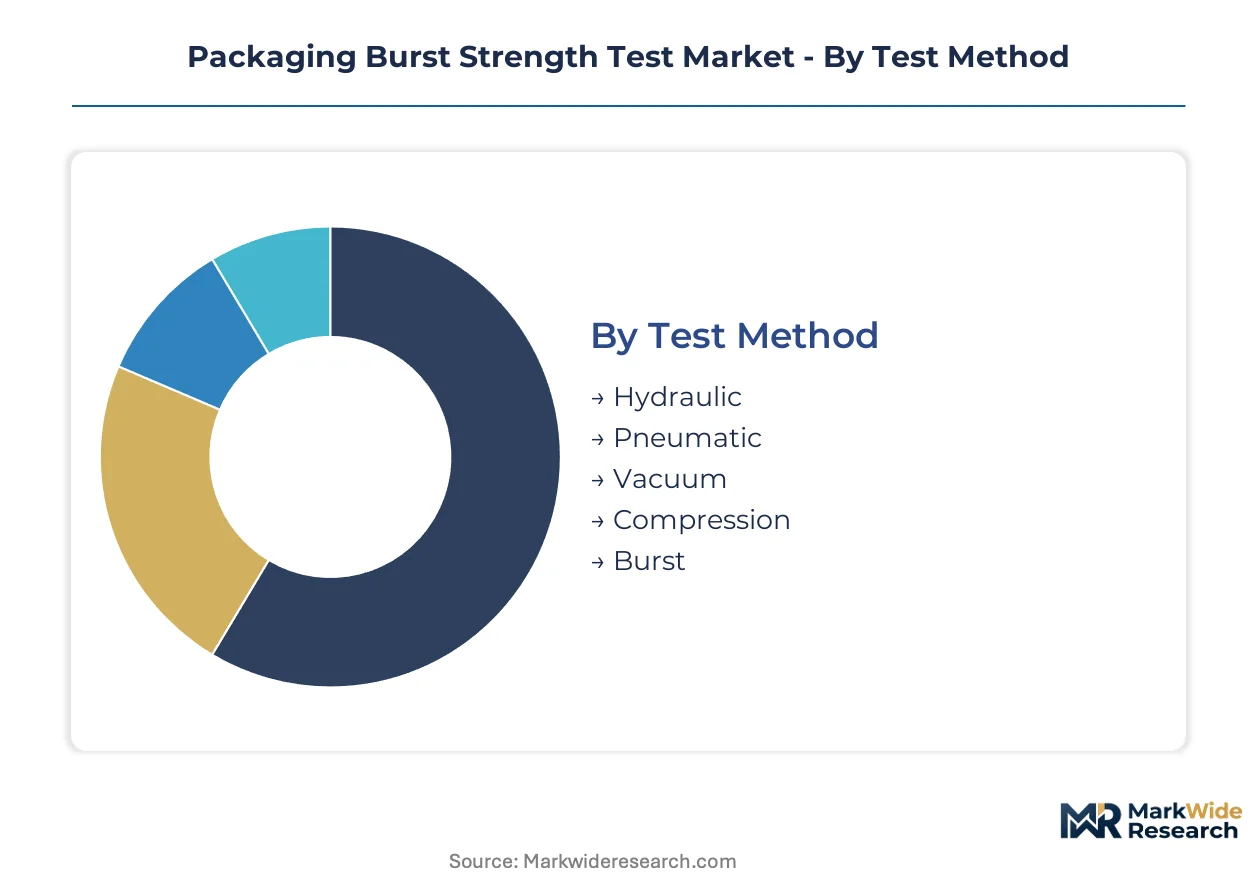
Segmentation in packaging burst strength testing reveals distinct capital requirements and operational constraints across validation methodologies. Equipment procurement cycles, calibration protocols, and end-use compliance burdens vary sharply by test approach and material target.
Test Method:
Hydraulic systems demand the heaviest upfront capital outlay due to precision pump assemblies and fluid containment infrastructure. Pneumatic configurations reduce mechanical complexity but require cleanroom-grade air handling.
- Hydraulic:Oil-based pressurization delivers the highest pressure ranges for heavy-duty corrugated and rigid container validation. Demand concentrates in German automotive parts packaging facilities where DIN 55440 burst specifications govern returnable container fleets.
- Pneumatic:Compressed gas systems eliminate fluid contamination risks in pharmaceutical sterile barrier testing. FDA-regulated medical device manufacturers in Minnesota and Massachusetts are displacing hydraulic bases with oil-free pneumatic architectures to meet USP <1207> container closure integrity mandates.
- Vacuum:Negative pressure differential testing for flexible pouch seal integrity in retort food applications.
- Compression:Axial load simulation for stack-height validation in distribution packaging.
- Burst:Standard diaphragm rupture protocols for paperboard and fiber-based containers.
Most installed capacity flows through Hydraulic systems in heavy industrial packaging. Expansion is steepest in Pneumatic configurations for pharmaceutical cleanroom deployment.
Packaging Material:
Material thickness and fiber orientation dictate sensor specification and fixture design, fragmenting equipment standardization across substrate categories.
- Corrugated Board:Flute structure variability requires programmable span adjustment in test fixtures. E-commerce fulfillment centers in the Netherlands specify burst testing for recycled-content board grades under EU Packaging and Packaging Waste Regulation compliance.
- Plastic Film:Elongation characteristics demand high-speed data capture to catch yield point transitions. Pharmaceutical blister pack manufacturers in Switzerland use validated burst profiles to demonstrate seal integrity for Swissmedic sterile product submissions.
- Paperboard:Fiber-based substrates for folding carton applications in consumer goods.
- Foil Laminates:Multi-layer barrier structures for pharmaceutical and food retort applications.
- Kraft Paper:Industrial sack and bagging materials for chemical and agricultural bulk packaging.
Corrugated Board commands the largest installed equipment base. Plastic Film applications are climbing the fastest as pharmaceutical serialization tightens flexible container validation.
End Industry:
Regulatory stringency tiers separate capital deployment patterns, with life sciences demanding accredited metrology that food and consumer segments rarely require.
- Pharmaceuticals:Sterile barrier validation under ISO 11607-1 and EU MDR documentation requirements. CDSCO-aligned contract manufacturers in India are building ISO 17025-accredited burst capacity to serve ANDA filers targeting FDA export markets.
- Food & Beverage:Retort pouch and aseptic carton seal verification. Italian and Spanish processors are recalibrating acceptance thresholds under ECHA REACH Annex XVII perfluorinated compound restrictions.
- Electronics:Moisture barrier bag validation for semiconductor and component shipping.
- Personal Care:Flexible tube and sachet integrity for cosmetic and hygiene products.
Food & Beverage holds the broadest installed base across regional processing clusters. Pharmaceuticals shows the steepest expansion trajectory as serialization mandates compress validation timelines.
Equipment Type:
Automation level determines throughput economics and operator skill requirements, creating a three-tier procurement market with distinct margin pools.
- Fully Automatic Tester:Robotic sample handling and statistical process control integration for high-volume pharmaceutical quality control labs. California's biomedical packaging cluster deploys these systems for multi-shift ANDA validation under single quality agreements.
- Semi-Automatic Tester:Operator-assisted loading with automated pressurization and data logging. Mid-scale generic drug manufacturers in India favor this tier to balance throughput against capital constraints.
- Manual Tester:Hand-operated pump and gauge configurations for small-batch medical device prototyping.
- Portable Tester:Battery-powered field units for incoming inspection at contract packaging sites.
Fully Automatic systems concentrate revenue in premium pharmaceutical installations. Portable configurations are gaining share fastest in distributed quality audit applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping equipment procurement patterns as manufacturers relocate validation capacity toward jurisdictions with streamlined qualification pathways. Cost-of-compliance gaps between FDA-regulated and emerging-market regimes are accelerating investment in ISO 17025-accredited facilities outside traditional pharmaceutical corridors.
United States
Pharmaceutical serialization mandates under the Drug Supply Chain Security Act are compressing sterile barrier validation timelines. FDA's 21 CFR Part 820 quality system regulation binds burst tester procurement cycles for medical device manufacturers. Minnesota and Massachusetts host concentrated deployment of pneumatic testing architectures serving sterile barrier validation workflows.
Germany
EU MDR sterilization packaging standards mandate documented burst test data across supplier tiers for terminally sterilized devices. ECHA REACH chemical compliance frameworks impose material traceability burdens on elastomeric seal documentation. Stuttgart and Munich anchor specialized validation service clusters integrating burst testing with ISO 11607 compliance workflows.
India
CDSCO alignment with FDA quality system regulations is driving demand for accredited burst testing capacity among ANDA filers. The country's pharmaceutical export sector requires validation infrastructure serving contract manufacturers targeting US markets. Gujarat and Maharashtra are building ISO 17025-accredited facilities to capture qualification contracts from generic drug exporters.
Switzerland
Swissmedic sterile product submissions require validated burst profiles for pharmaceutical blister pack manufacturers. The country's precision instrumentation heritage supports high-specification sensor calibration services. Basel and Zurich host metrology laboratories serving cross-border pharmaceutical packaging operations.
Italy
ECHA REACH Annex XVII restrictions on perfluorinated compounds are forcing retort pouch processor recalibration of burst test acceptance thresholds. Food packaging operations face reformulation-driven validation requirements for barrier coatings. Emilia-Romagna processors are commissioning multi-variable burst studies correlating coating chemistry with heat-seal performance degradation.
Packaging Burst Strength Test Market Competitive Landscape
German and Swiss producers anchor the precision-instrument tier; North American specialists hold contract validation service density. Market structure fragments across equipment fabrication and accredited testing services, with limited overlap between capital-goods manufacturers and ISO 17025-certified laboratories. Three archetypes dominate: precision sensor integrators, contract testing laboratories, and hybrid equipment-plus-validation providers. Capacity expansion and strategic unbundling of validation services from equipment sales represent the dominant competitive vectors.
Within the contract testing tier, Smithers and Nelson Labs exemplify divergent specialization strategies. Smithers occupies a position leveraging materials science heritage for premium FDA-regulated medical device engagements. Nelson Labs sits within sterile barrier validation protocols aligned with USP container closure integrity standards. Westpak anchors geographic concentration across California's biomedical packaging cluster, representing the hybrid model combining ISO 17025-accredited facilities with regional service density.
| Leading Market Players |
|---|
| Westpak |
| Cardinal Health |
| Smithers |
| Keystone Package Testing |
| TEN-E Packaging Services |
| DDL |
| Nelson Labs |
| Applus+ Keystone |
| QUALITEST International |
| Others |
Pricing and Supply Chain Analysis
Stainless steel price indices on the London Metal Exchange cascade through pneumatic burst tester manufacturing, compressing margins for mid-tier equipment vendors while premium sensor integrators in Germany and Switzerland maintain pricing power through captive machining capabilities.
Pricing Analysis
Distributor margins of 18-25% separate factory-gate equipment costs from end-user pharmaceutical procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by automation grade and ISO 17025 calibration bundling. Cost compression in standard-tier pneumatic systems is intensifying because Indian contract manufacturers are sourcing uncalibrated base units from Chinese sensor suppliers. Mid-scale generic drug manufacturers in India exhibit the highest price sensitivity, while FDA-regulated medical device OEMs in Minnesota and Massachusetts prioritize validation documentation over unit economics.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Singapore, and Chicago anchor hub-and-spoke patterns for precision sensor replenishment. CNC-manufactured test fixtures and burst diaphragms draw from specialized German and Swiss machine shops, creating single-source vulnerabilities for elastomeric seal components. Tariff exposure on Chinese-origin piezoelectric transducers threatens margin stability for mid-tier vendors. Distribution runs through ISO 17025-accredited metrology laboratories that bundle equipment sales with calibration service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaging burst strength test market functions as a geographic-arbitrage play, with cost-of-compliance gaps between FDA-regulated US regimes and emerging-market qualification pathways creating equipment procurement migration toward CDSCO-aligned Indian facilities.
For Market Incumbents: Acquire ISO 17025-accredited calibration laboratories to lock in recurring service revenue streams. Smithers and Nelson Labs demonstrate how sterile barrier validation expertise anchors premium pricing against emerging pneumatic equipment vendors from Asia. Capacity addition in Gujarat and Maharashtra captures ANDA-filer demand before local competitors achieve FDA alignment. Certification investment in EU MDR documentation workflows defends position against regional European challengers. For New Entrants and Emerging Players: Mid-scale generic drug manufacturers in India represent the most penetrable buyer archetype, as capital constraints prevent in-house quality lab construction. Biologics cold chain packaging for mRNA vaccines offers white-space demand for ultra-low temperature burst validation protocols that incumbent equipment vendors have not addressed. Go-to-market execution should unbundle validation services from equipment sales, mirroring Westpak's shared-access facility model in California's biomedical packaging cluster. For Investors and Strategic Acquirers: Asymmetric upside sits with hybrid equipment-plus-validation providers that combine precision sensor fabrication with ISO 17025-accredited testing services. Long-term viability hinges on regulatory harmonization between FDA and EU MDR standards, which would consolidate fragmented testing protocols and favor scale players over point-solution vendors. The signal to watch is CDSCO's progression toward mutual recognition agreements with FDA, which would validate Indian contract manufacturing infrastructure and trigger equipment procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Pneumatic Architecture Conversion | Oil-free operation meets USP <1207> container closure integrity mandates in Minnesota cleanrooms. |
| ISO 17025 Accreditation Expansion | Calibration laboratory capacity in Gujarat serves ANDA filers targeting FDA export markets. |
| Digital Twin Integration | Finite element modeling of seal failure modes reduces medical device prototype iterations. |
| Cold Chain Validation Protocol Development | Ultra-low temperature burst testing captures biologics packaging demand from mRNA vaccine manufacturers. |
| REACH-Compliant Material Reformulation | Perfluorinated compound restrictions force retort pouch processor recalibration in Italy and Spain. |
Research Methodology
Bottom-up pharmaceutical and medical device validation modeling reconciled against top-down precision instrumentation manufacturing tracking forms the analytical core of this study. Primary interviews with biomedical engineers, GPO contracts managers, sterile barrier validation specialists, and aftermarket service heads combined with secondary validation from FDA 510(k) filings, ISO 11607-1 technical documentation, EU MDR substance databases, and customs records for pneumatic pressurization equipment. Triangulation across these sources reconciles equipment shipment data with end-user procurement patterns.
Input-output matrices map sensor component costs through final equipment pricing across test method, automation level, and end-use industry dimensions. Modeled segmentation spans hydraulic versus pneumatic pressurization architectures, corrugated board versus plastic film material targets, and pharmaceutical sterile barrier versus food retort pouch applications. CAGRs derive from equipment replacement cycles tied to regulatory recertification timelines and calibration protocol updates. Forecast inputs incorporate REACH chemical compliance roadmap milestones and CDSCO-FDA alignment progression indicators.
Inputs from FDA warning letter databases and EMA medical device registration filings were available through the study window; gaps in private contract manufacturer procurement data introduce uncertainty bands around Indian market penetration assumptions. Forecasts reflect documented assumptions regarding regulatory harmonization velocity and sensor supply chain stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.