
 Bottle Perpendicularity Tester Market | 2026-2036
Bottle Perpendicularity Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Bottle Perpendicularity Tester Market Insights
Aftermarket calibration and certification revenue is tilting toward equipment vendors with embedded service networks. Presto leverages its Indian manufacturing base to anchor aftermarket contracts across South Asian beverage bottlers. AT2E USA competes through specialized pharmaceutical-sector positioning, while Saicheng Instrument dominates domestic replacement-part logistics for Chinese packaging lines.
A bottle perpendicularity tester measures the deviation of a bottle's vertical axis from true perpendicularity, typically resolving to 0.1 mm precision using rotating probe or laser triangulation methods, ensuring container stability during filling, capping, and label application. Automatic testers command the widest installed base in high-speed beverage manufacturing, though portable testers are gaining traction among contract packaging firms running multi-site audits. Laser measurement technology leads R&D spending as optical inspection matures into a cost-optimized option for mid-tier pharmaceutical packaging operations.
FDA container closure integrity guidance and EU MDR traceability mandates tighten dimensional tolerance requirements for drug delivery bottles, directly expanding tester procurement in quality assurance labs. China's NMPA Good Manufacturing Practice standards and GB national standards for pharmaceutical packaging further shape product specifications for instruments sold into Asian manufacturing plants. Stakeholders must monitor how evolving pharmacopeial container standards in multiple jurisdictions redefine acceptable perpendicularity thresholds and testing protocol automation levels.
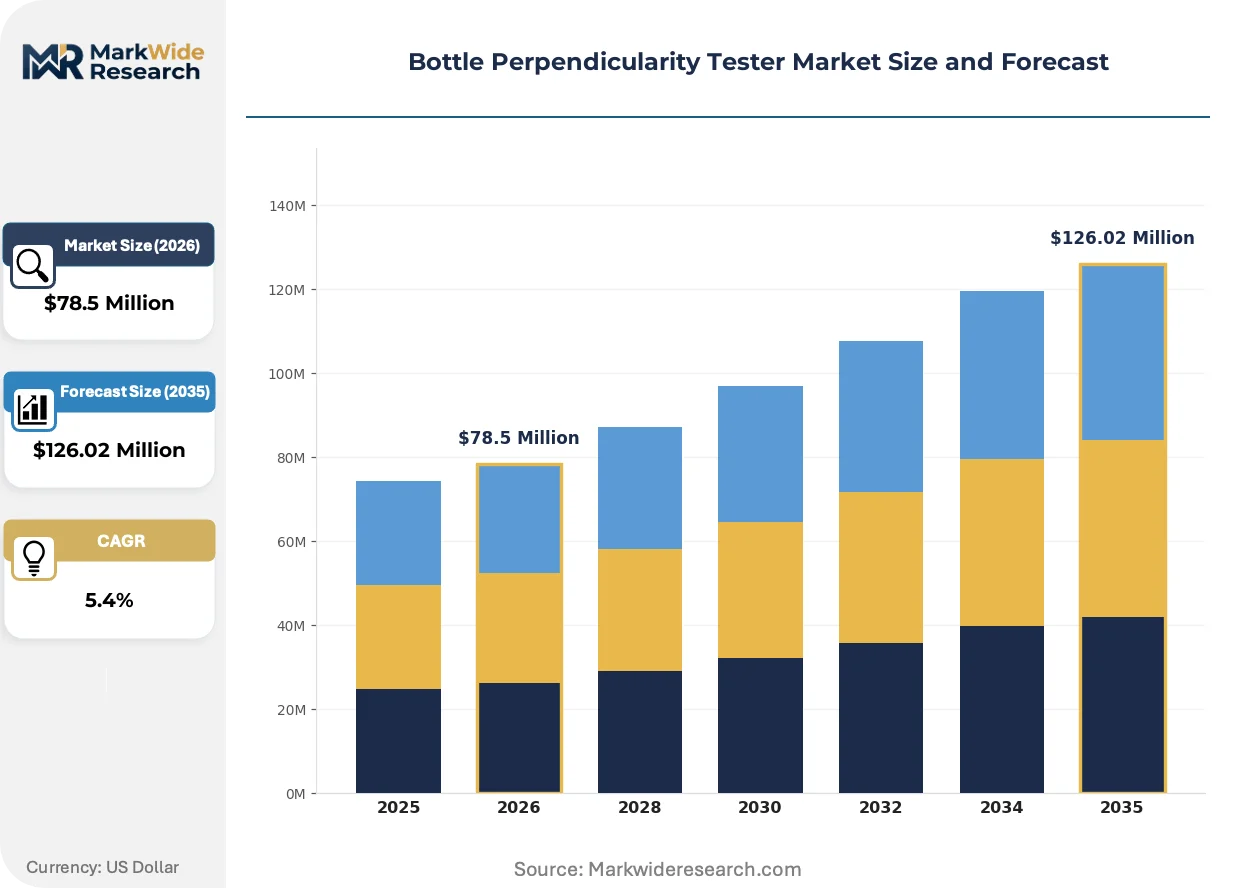
Market Dynamics
Pharmaceutical packaging lines are tightening dimensional tolerance verification as FDA container closure guidance and EU MDR traceability requirements harden quality control mandates. Laser triangulation systems are displacing mechanical probe methods in mid-tier quality assurance labs, compressing equipment replacement cycles and reshaping vendor procurement criteria.
Growth Catalysts
- FDA Container Closure Integrity Guidance:Dimensional tolerance mandates for drug delivery bottles are expanding tester deployment in United States pharmaceutical quality labs. Automated perpendicularity verification is becoming standard for parenteral packaging lines.
- Laser Triangulation Technology:Optical measurement systems are capturing share from rotating probe methods in beverage bottling operations. Resolution improvements to 0.1 mm precision are validating container stability for high-speed filling lines.
- German Pharmaceutical Packaging Expansion:Quality control budget allocations for container geometry verification are rising across Bavarian and Baden-Württemberg manufacturing clusters. EU MDR compliance deadlines are accelerating capital equipment procurement.
Market Restraints
- Precision Optics Input Volatility:Laser diode and CMOS sensor costs fluctuate with semiconductor foundry capacity constraints. Asian component sourcing exposes equipment margins to supply concentration risk.
- Mechanical Probe Obsolescence Drag:Installed base of rotating probe testers in mature beverage markets creates upgrade hesitation. Capital recovery timelines extend replacement decisions.
- CE Marking Technical Documentation Burden:EU machinery directive conformity assessment timelines delay market entry for non-European vendors. Notified body queue congestion extends certification cycles.
Strategic Opportunities
- Contract Packaging Multi-Site Audits:Portable perpendicularity testers are penetrating third-party packaging services running distributed quality verification. Mobility features command pricing premiums over fixed installations.
- China NMPA GMP Alignment:GB national standards for pharmaceutical packaging are elevating instrumentation requirements across Shandong and Jiangsu manufacturing provinces. Domestic substitution policies favor localized supply chains.
- Aftermarket Service Unbundling:Embedded calibration networks are capturing recurring revenue from beverage bottlers seeking ISO 17025 traceability. Certification retention contracts extend customer lifetime value.
Industry Challenges
- Metrology Technician Scarcity:Qualified personnel for laser system calibration and optical alignment are concentrated in established industrial regions. Training pipeline gaps constrain deployment velocity.
- Legacy System Integration Complexity:New optical testers must interface with existing SCADA and MES architectures in pharmaceutical packaging lines. Protocol translation adds implementation cost and timeline risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bottle Perpendicularity Tester Market |
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $126.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Tester, Semi-Automatic Tester, Manual Tester, Portable Tester Technology: Laser Measurement, Optical Inspection, Mechanical Gauge, Ultrasonic Detection Application: Beverage Manufacturing, Pharmaceutical Packaging, Cosmetic Bottling, Chemical Containers End User Industry: Contract Packaging, Quality Assurance Labs, Manufacturing Plants, Product Development Centers |
| Companies Covered | Labnics, Presto, AT2E USA, Horizon Tester, Saicheng Instrument, Parisa, Texcare Instruments Limited, Testronix Instruments, Multi Tech Engineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bottle Perpendicularity Tester Market Trends and Innovations
Measurement modality convergence and regulatory documentation automation are compressing equipment differentiation cycles. Vendors are racing to embed predictive calibration algorithms and cloud-connected traceability features ahead of pharmacopeial standard revisions.
Laser triangulation perpendicularity testers are collapsing the cost-performance boundary that previously separated premium optical systems from mechanical probe alternatives. Mid-tier pharmaceutical packaging operations in the United States and Germany are adopting sub-micron resolution units formerly reserved for high-speed beverage lines. Equipment margins are compressing as optical component commoditization accelerates.
EU MDR Annex I technical documentation requirements are mandating automated measurement data integrity for container geometry verification. Pharmaceutical quality labs must demonstrate ALCOA+ principles for perpendicularity test records. Laser systems with embedded audit trails and electronic signature capabilities are capturing preference in European procurement specifications.
Certification-driven vendor selection is displacing specification-only procurement in pharmaceutical quality assurance. Buyers now weight ISO 17025 calibration accreditation and FDA 21 CFR Part 11 software validation equally with measurement precision metrics. United States contract packaging firms are consolidating supplier relationships around vendors offering bundled compliance documentation.
Bottle Perpendicularity Tester Market Segmentation
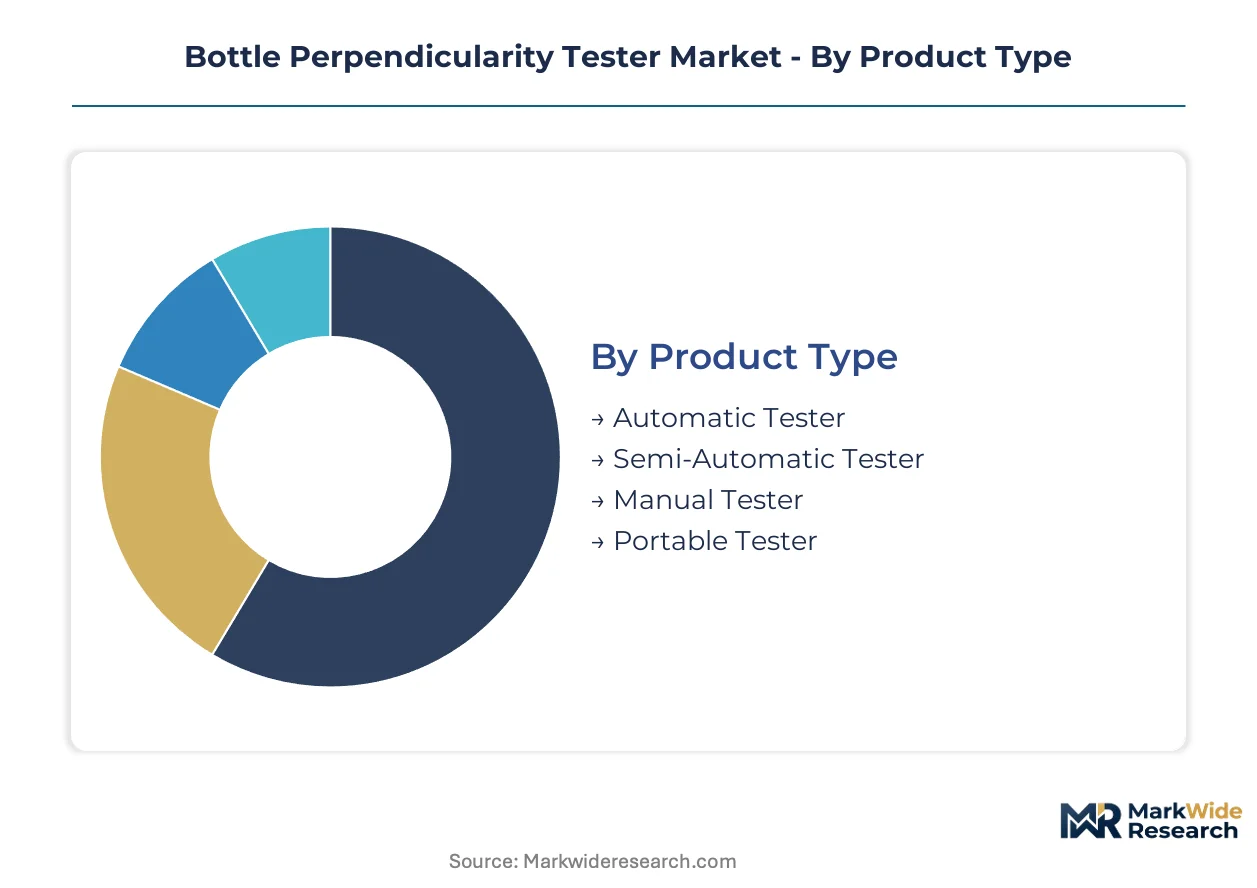
Perpendicularity tester procurement diverges sharply by operational tempo and regulatory exposure. High-speed bottling lines demand continuous automated verification, while distributed quality networks prioritize mobility and audit flexibility.
Product Type:
Automatic testers anchor high-volume beverage and pharmaceutical lines where throughput dictates inspection frequency. Portable and manual variants serve intermittent validation needs across contract packaging networks and product development workflows.
- Automatic Tester:Rotating probe or laser triangulation systems integrate directly into conveyor architectures for 100% inline inspection. Beverage bottlers in Germany and the United States deploy these units to maintain FDA and EU MDR compliance at filling speeds exceeding 60,000 bottles per hour.
- Portable Tester:Battery-powered units with wireless data logging enable multi-site audit protocols for third-party packaging services. Contract packagers running distributed operations across North American manufacturing clusters command pricing premiums for mobility features and rapid deployment capability.
- Semi-Automatic Tester:Benchtop systems requiring operator-assisted bottle positioning serve mid-tier pharmaceutical quality labs with moderate throughput requirements.
- Manual Tester:Mechanical gauge configurations persist in legacy beverage operations and emerging market installations where capital constraints limit automation investment.
Established volume favors automatic testers; emerging adoption favors portable testers.
Technology:
Measurement modality selection hinges on precision requirements and total cost of ownership trajectories. Optical systems are compressing the performance gap that previously separated premium laser configurations from mechanical alternatives.
- Laser Measurement:Triangulation systems achieve 0.1 mm resolution through CMOS sensor arrays and structured light projection. Pharmaceutical packaging lines in Bavarian manufacturing clusters specify these units for EU MDR Annex I technical documentation compliance.
- Mechanical Gauge:Rotating probe methods with dial indicator readouts dominate legacy installed bases in mature beverage markets. Capital recovery timelines and technician familiarity extend replacement cycles despite optical performance advantages.
- Optical Inspection:Machine vision configurations leveraging area scan cameras offer intermediate precision for mid-tier cosmetic and chemical container applications.
- Ultrasonic Detection:Non-contact thickness-correlated perpendicularity measurement serves specialized chemical container verification where material property variation affects geometric stability.
Laser measurement commands R&D investment concentration; mechanical gauge retention reflects installed base inertia.
Application:
Regulatory stringency and container geometry complexity shape application-level demand patterns. Parenteral drug delivery bottles face the tightest dimensional tolerances, while beverage containers prioritize high-speed stability verification.
- Pharmaceutical Packaging:Parenteral and ophthalmic bottle formats require sub-millimeter perpendicularity control to ensure closure integrity and dosing accuracy. FDA container closure guidance and EU MDR traceability mandates are expanding automated tester deployment in United States and German quality assurance labs.
- Beverage Manufacturing:Carbonated soft drink and bottled water lines verify container stability to prevent label misapplication and capping defects. High-speed filling operations in North American bottling clusters specify laser triangulation systems for 0.1 mm resolution at production line velocities.
- Cosmetic Bottling:Premium skincare and fragrance packaging emphasizes aesthetic alignment for shelf presentation and pump mechanism functionality.
- Chemical Containers:Industrial and agricultural chemical bottles prioritize stackability and leak-free sealing over cosmetic precision requirements.
Pharmaceutical packaging drives specification escalation; beverage manufacturing sustains unit volume concentration.
End User Industry:
Procurement authority and compliance documentation requirements fragment end user behavior. Manufacturing plants prioritize throughput integration, while quality assurance labs emphasize metrological traceability and audit readiness.
- Quality Assurance Labs:Independent testing facilities and captive pharmaceutical quality operations require ISO 17025 calibration accreditation and FDA 21 CFR Part 11 software validation. These buyers consolidate supplier relationships around vendors offering bundled compliance documentation and embedded service networks.
- Contract Packaging:Third-party packaging services running multi-site operations for pharmaceutical and cosmetic brands demand portable testers with rapid deployment and standardized audit protocols. Mobility features and cloud-connected traceability command procurement preference.
- Manufacturing Plants:Integrated beverage and pharmaceutical production facilities specify inline automatic systems with SCADA and MES protocol compatibility.
- Product Development Centers:R&D and pilot line operations utilize semi-automatic and manual configurations for formulation-stage container qualification.
Quality assurance labs concentrate specification authority; contract packaging represents the steepest expansion trajectory for portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply by geography. German and United States pharmaceutical buyers prioritize compliance documentation over unit cost, while Indian and Chinese beverage bottlers drive hard on aftermarket service pricing.
United States
FDA container closure integrity guidance and parenteral packaging line expansion dominate procurement decisions. 21 CFR Part 11 software validation requirements filter vendor selection toward accredited calibration networks. New Jersey and North Carolina pharmaceutical clusters specify automated laser systems for high-speed bottle inspection.
Germany
EU MDR Annex I technical documentation mandates accelerate capital equipment replacement in Bavarian and Baden-Württemberg manufacturing zones. CE marking conformity assessment timelines disadvantage non-European vendors. Munich and Stuttgart quality labs consolidate supplier relationships around embedded service providers.
China
NMPA Good Manufacturing Practice standards and GB national packaging specifications elevate instrumentation requirements across Shandong and Jiangsu provinces. Domestic substitution policies favor localized supply chains and captive calibration networks. Qingdao beverage bottlers anchor regional demand for mid-tier automatic testers.
India
CDSCO pharmaceutical packaging regulations and FSSAI beverage safety standards shape quality control budget allocations. Presto leverages its domestic manufacturing base to capture aftermarket contracts across South Asian bottling operations. Maharashtra and Gujarat contract packaging clusters drive portable tester adoption for multi-site audit protocols.
Japan
METI industrial standards and PMDA pharmaceutical container specifications enforce stringent dimensional tolerance verification. JIS-compliant measurement traceability requirements privilege vendors with accredited calibration infrastructure. Osaka and Nagoya pharmaceutical packaging lines specify laser triangulation systems for sub-millimeter resolution.
Bottle Perpendicularity Tester Market Competitive Landscape
Specialized instrumentation vendors and diversified testing equipment conglomerates split the market along service-network depth versus portfolio-breadth lines. The vendor base organizes into three archetypes: embedded-service specialists with captive calibration infrastructure, technology-focused optical measurement developers, and diversified laboratory equipment distributors with broad geographic footprints. Competitive moves concentrate on aftermarket service unbundling and laser measurement technology licensing to compress replacement cycles in legacy mechanical probe installed bases.
Among India-based fabricators, Presto occupies a position exemplifying the embedded-service archetype through its domestic manufacturing and calibration network density. AT2E USA represents the pharmaceutical-specialist vector with United States market positioning. Saicheng Instrument anchors the China-based tier, occupying a position shaped by domestic replacement-part logistics capabilities for localized packaging lines.
| Leading Market Players |
|---|
| Labnics |
| Presto |
| AT2E USA |
| Horizon Tester |
| Saicheng Instrument |
| Parisa |
| Texcare Instruments Limited |
| Testronix Instruments |
| Multi Tech Engineers |
| Others |
Pricing and Supply Chain Analysis
Shanghai-Rotterdam container freight corridors transmit semiconductor component volatility directly into laser triangulation system landed costs, compressing margins for European and North American equipment vendors while amplifying price differentiation between premium optical configurations and mechanical probe alternatives. Calibration network density and spare-part logistics proximity now determine effective pricing power more than manufacturing scale.
Pricing Analysis
Aftermarket service contracts and ISO 17025 calibration subscriptions generate lifetime value multiples exceeding initial equipment sales. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 11-validated pharmaceutical systems from mid-tier beverage units and manual gauge configurations. Cost compression in economy tiers intensifies because Chinese domestic substitution policies accelerate localized manufacturing. Contract packaging firms exhibit highest price sensitivity; German pharmaceutical quality labs demonstrate lowest sensitivity due to EU MDR compliance documentation requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates strategic sourcing decisions for CMOS sensors and laser diode arrays. Precision optics manufacturing concentrates in Germany, Japan, and China, with equipment assembly drawing from Indian and Chinese fabrication bases. Semiconductor foundry capacity constraints present single-source vulnerability for sensor procurement. Distribution runs through embedded service networks rather than arms-length dealer channels, privileging vendors with captive calibration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as regulatory documentation requirements splinter procurement authority between quality assurance labs, contract packagers, and manufacturing engineers, creating specialized niches for compliance-focused and mobility-optimized equipment variants.
For Market Incumbents: Build calibration network moats through ISO 17025 accreditation density in pharmaceutical manufacturing clusters. Deepen backward integration into laser diode sourcing to mitigate semiconductor foundry concentration risk. Acquire portable tester specialists to defend against emerging entrants targeting contract packaging mobility requirements. Prioritize FDA 21 CFR Part 11 software validation investment as regulatory documentation automation accelerates replacement cycles. For New Entrants and Emerging Players: Establish a beachhead in Indian and Chinese beverage bottling aftermarket service contracts where Presto and Saicheng Instrument maintain geographic coverage gaps. Target portable tester penetration among North American contract packaging firms running multi-site audit protocols. Pursue laser measurement technology licensing agreements with established optical component suppliers to bypass R&D capital requirements and accelerate time-to-market. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors embedded-service specialists with captive calibration infrastructure over pure-play equipment manufacturers. Long-term viability rests on recurring revenue share and customer lifetime value extension through certification retention contracts. Monitor pharmacopeial container standard revision timing as inflection indicator for replacement cycle acceleration across pharmaceutical quality lab installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | ISO 17025 accreditation density captures recurring revenue from FDA-regulated pharmaceutical packaging lines. |
| Laser Technology Licensing | Optical measurement IP partnerships compress development timelines for mid-tier market entrants. |
| Portable Product Line Development | Battery-powered wireless units penetrate contract packaging multi-site audit protocols. |
| Regulatory Software Validation | FDA 21 CFR Part 11 embedded audit trails meet EU MDR ALCOA+ documentation mandates. |
| Regional Manufacturing Localization | Domestic assembly in India and China satisfies NMPA and CDSCO procurement preferences. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with quality assurance lab directors, contract packaging operations managers, pharmaceutical packaging engineers, and aftermarket service heads; and secondary validation against FDA guidance documents, EU MDR technical specifications, NMPA GMP standards, SEC equipment vendor filings, and customs trade data for precision optics components. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporated product type substitution dynamics, technology modality displacement rates, regulatory compliance deadline clustering, and regional manufacturing localization policies. Segmentation dimensions spanned automatic-portable-manual-tester categories, laser-mechanical-optical-ultrasonic technologies, pharmaceutical-beverage-cosmetic-chemical applications, and quality lab-contract packager-manufacturing plant end users. CAGRs derived from equipment replacement cycle compression analysis and capital expenditure elasticity to regulatory mandate timing.
Sensitivities concentrate around semiconductor component cost volatility, notified body queue congestion for CE marking, and pharmacopeial standard revision schedules. Forecasts reflect assumptions regarding regulatory enforcement consistency and technology adoption curve steepness. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Testing
Heterogeneous Integration and Advanced Packaging X-Ray CT Inspection Systems Market
Packaging Testing
Packaging Burst Strength Test Market
Packaging Testing
North America Package Testing Market
Packaging Testing
Pre-Validated Packaging Market
Packaging Testing
Food Packaging Testing Market
Packaging Testing
Asia-Pacific Package Testing Market
Packaging Testing
Packaging Testing Services Market
Packaging Testing
Package Testing Silicone Rubber Socket Market
Packaging Testing
Heat Sealing Tester Market
Packaging Testing
Global Bowie Dick Test Pack Market
Packaging Testing
Packaging Testing Equipment Market
Packaging Testing
Packaging Extended Producer Responsibility Compliance Test Platforms Market
Packaging Testing
Food Packaging Tester Market
Packaging Testing
Pack Testing Machines Market
Packaging Testing
Packaging Testing Market
Packaging Testing
Humidity Indicator Cards (HIC) Market