
 Pre-Shave Care Market | 2026-2036
Pre-Shave Care Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Shave Care Market Analytics
Subscription-based replenishment services is decoupling pre-shave purchases from traditional retail cycles, shifting consumer lock-in toward recurring delivery models. The Procter & Gamble Company leverages its Gillette shave club infrastructure to anchor recurring revenue in the North American mass market. L'Oréal S.A. differentiates through dermatological testing protocols that sustain premium pricing across European pharmacy channels. Beiersdorf AG operates a concentrated R&D hub in Hamburg that specializes in sensitive-skin formulations for the Nivea Men portfolio.
Pre-shave care encompasses topical formulations applied before blade contact to soften facial hair, reduce friction, and protect epidermal integrity, typically incorporating humectants, essential oils, and surfactants in oil-in-water or water-in-oil emulsions manufactured through high-shear homogenization at controlled temperatures. The primary commercial purpose centers on improving shave comfort while minimizing razor burn, ingrown hairs, and transepidermal water loss in both consumer and professional settings. Shaving oil commands the highest margin pool among product types due to concentrated actives and minimal water content, while e-commerce as an application channel is expanding fastest as direct-to-consumer brands bypass traditional wholesale markups. Professional salons represent a mature but stable segment where barbers prioritize bulk formats and consistent supply reliability over formulation novelty.
The U.S. Food and Drug Administration governs cosmetic labeling and ingredient safety claims for pre-shave products sold in American retail, while the European Chemicals Agency enforces REACH compliance on fragrance allergens and preservative concentrations in formulations distributed across EU member states. California's Proposition 65 and the EU Cosmetics Regulation together compel manufacturers to reformulate traditional pre-shave gels containing formaldehyde-releasing preservatives or synthetic musks. Stakeholders must monitor divergence between FDA cosmetic oversight and emerging state-level clean beauty mandates that could fragment compliance requirements for multi-market brands.
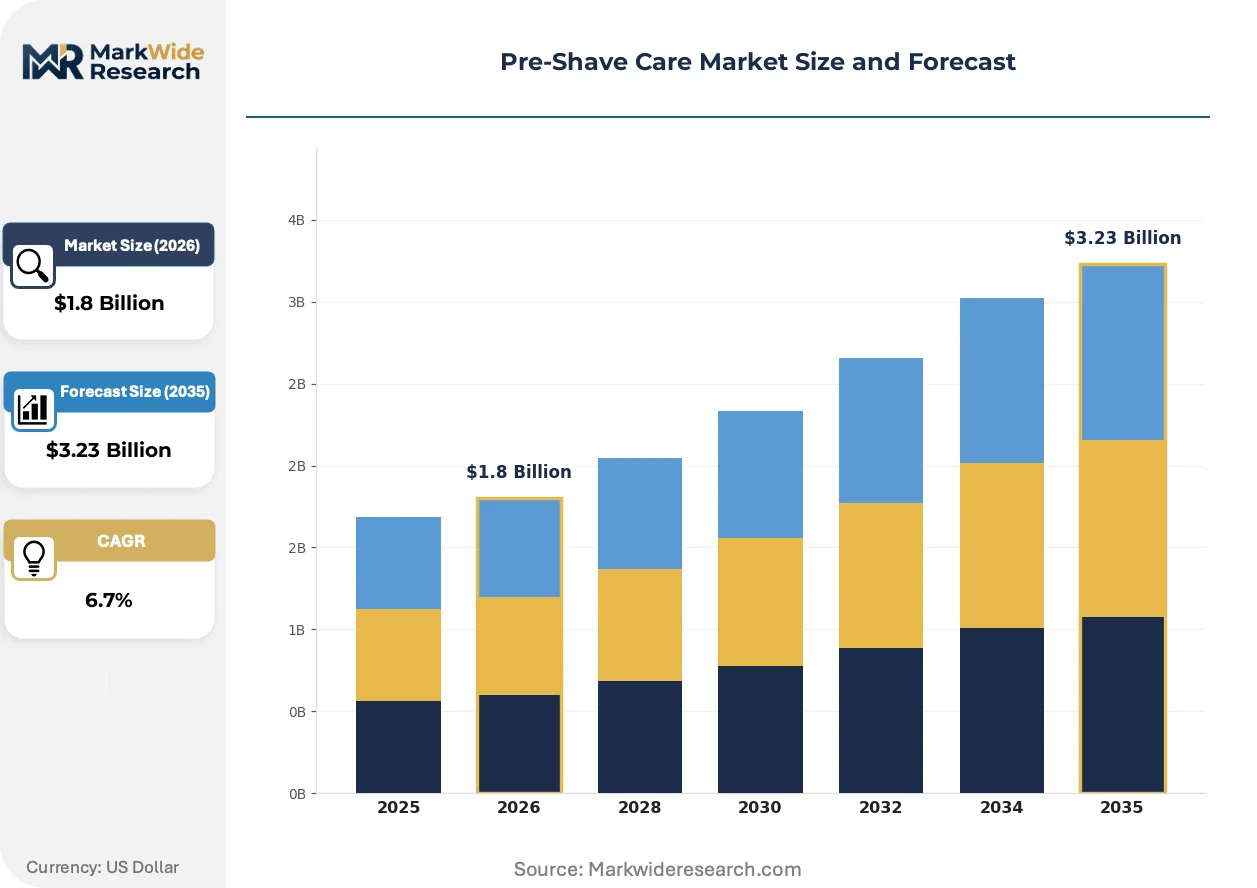
Market Dynamics
Subscription-based replenishment services are decoupling pre-shave purchases from traditional retail cycles, shifting consumer lock-in toward recurring delivery models anchored by direct-to-consumer infrastructure. This structural force is reshaping how brands capture lifetime value and how distribution economics allocate margin between manufacturers and retail intermediaries.
Growth Catalysts
- Straight-razor certification expansion:Barbering academies across North America and Western Europe are scaling enrollment for traditional wet-shaving programs, creating institutional demand for professional-grade pre-shave formulations.
- REACH compliance on fragrance allergens:The European Chemicals Agency's enforcement is compelling manufacturers to reformulate with transparent ingredient decks, opening premium positioning for clean-label specialists.
- Artisanal apothecary channel concentration:Germany's men's grooming channel commands premium positioning through barber-supply wholesalers and heritage apothecary brands that elevate pre-share care into ritual commerce.
Market Restraints
- Shea butter and jojoba oil price volatility:Input cost swings for natural emollients compress margin pools for oil-based formulations that command the highest category premiums.
- Water-scarcity processing constraints:High-shear homogenization at controlled temperatures requires substantial water inputs, creating operational friction in drought-prone manufacturing clusters.
- Formaldehyde-releasing preservender pressure:California's Proposition 65 and the EU Cosmetics Regulation together force costly reformulation cycles for legacy gel formulations.
Strategic Opportunities
- Clean beauty statute tailwinds:Emerging state-level disclosure mandates in New York create first-mover advantage for brands with pre-positioned transparent supply chains.
- Professional salon bulk formats:Barbers prioritize consistent supply reliability over formulation novelty, opening white space for private-label and contract-manufactured professional lines.
- E-commerce channel bypass:Direct-to-consumer brands circumvent traditional wholesale markups, capturing margin that previously accrued to multi-brand retailers.
Industry Challenges
- Trained formulation chemist scarcity:Specialized expertise in sensitive-skin emulsion science concentrates in Hamburg and Basel, creating talent acquisition bottlenecks for new market entrants.
- Multi-jurisdiction compliance synchronization:Divergence between FDA cosmetic oversight and emerging state-level clean beauty mandates fragments quality assurance protocols for multi-market brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Shave Care Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shaving Oil, Pre-Shave Lotion, Gel, Cream Application: Personal Care, Professional Salons, Barbershops, E-commerce End User: Men, Women, Unisex, Professionals Distribution Channel: Online Stores, Supermarkets, Drugstores, Specialty Shops |
| Companies Covered | The Procter & Gamble Company, L'Oréal S.A., Unilever PLC, Beiersdorf AG, Edgewell Personal Care Company, Johnson & Johnson, Energizer Holdings, Inc., Malhotra Shaving Products Ltd., Claus Porto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Shave Care Market Evolving Landscape
Pre-shave care is undergoing material and regulatory transformation as botanical actives displace synthetic chemistry and enforcement frameworks tighten on transparency. These shifts are compressing traditional formulation paradigms while opening structural advantage for compliant specialists.
Plant-derived humectant complexes are electrifying formulation architecture as manufacturers replace petroleum-based glycols with hyaluronic acid from fermented wheat and tremella mushroom polysaccharides. European pharmacy channels are adopting these materials fastest, with dermatological testing protocols sustaining premium pricing tiers. The technology is electrifying competitive positioning by forcing legacy brands into accelerated R&D cycles or partnership-dependent supply arrangements.
REACH enforcement on fragrance allergens is tightening disclosure requirements for pre-shave oils and balms distributed across EU member states. Manufacturers must now label 26 specific allergenic compounds above threshold concentrations, increasing packaging complexity and reformulation costs. Small-batch artisanal producers in Provence and Tuscany face disproportionate compliance burdens relative to scaled competitors with dedicated regulatory affairs functions.
Barbers and grooming professionals are consolidating purchasing through specialized supply cooperatives that negotiate direct manufacturer relationships, bypassing traditional distribution intermediaries. This procurement consolidation concentrates volume with fewer suppliers while demanding customized bulk formats and private-label capabilities. The shift is most visible in London and Berlin, where independent barbershop collectives now command terms previously reserved for national retail chains.
Pre-Shave Care Market Segmentation
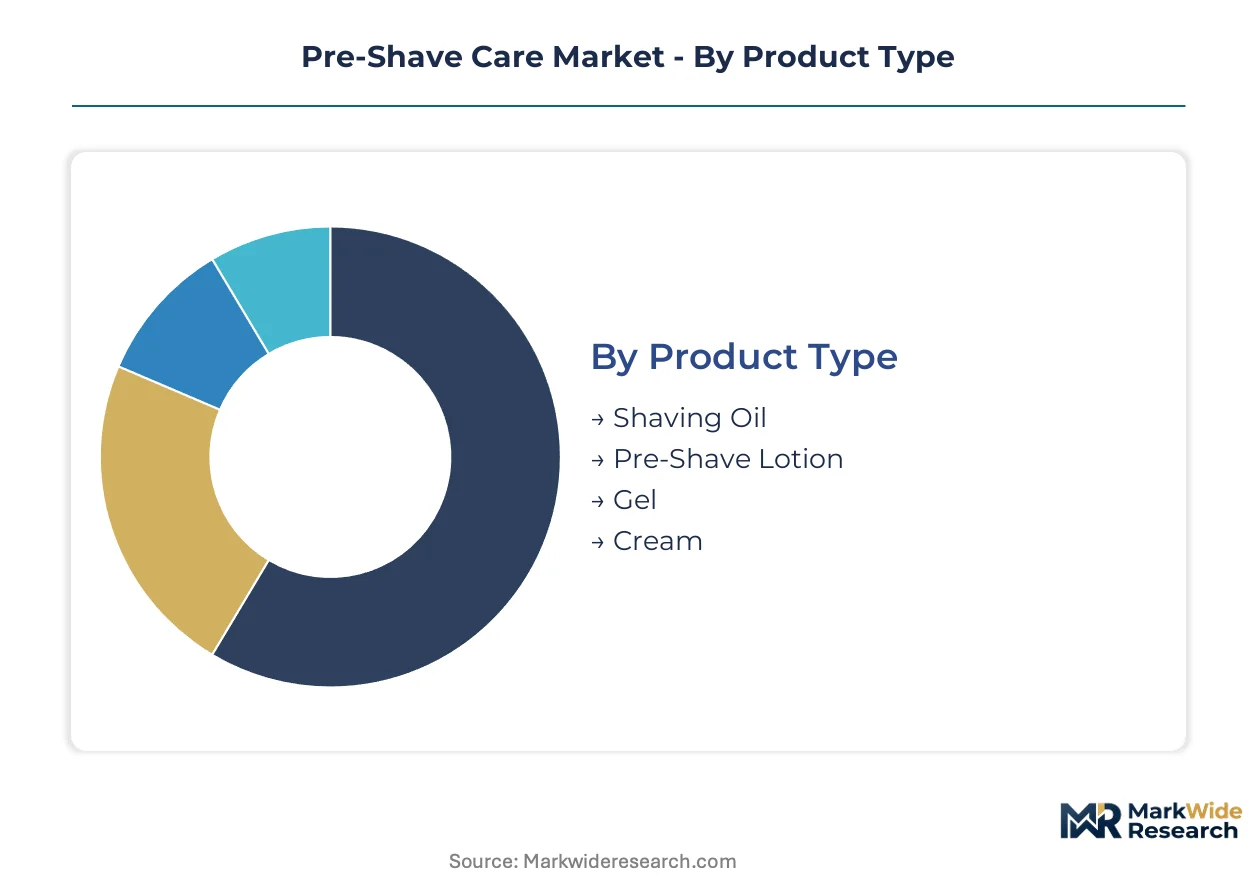
Pre-shave care segmentation reveals divergent margin structures across formulation chemistry and procurement context. Product type and application channel together determine whether brands capture premium pricing or compete on volume efficiency.
Product Type:
Oil-based formulations command the steepest premium tiers due to concentrated active content and minimal water dilution, while water-in-oil emulsions serve mass-market efficiency plays.
- Shaving Oil:Anhydrous or low-water formulations blending jojoba, argan, and essential oil actives without emulsifying agents. German barber-supply wholesalers and artisanal apothecaries in Hamburg concentrate demand here, driven by straight-razor certification expansion and ritual-commerce positioning. REACH compliance on fragrance allergens elevates clean-label specialists who transparently disclose all 26 regulated compounds.
- Pre-Shave Lotion:Lightweight oil-in-water emulsions with humectant complexes and rapid absorption profiles. Personal care consumers in California and New York favor these for daily-use convenience under tightening state-level clean beauty disclosure mandates.
- Gel:Water-dominant formulations with polymer thickeners and cooling agents. Legacy brands face reformulation pressure as California's Proposition 65 and EU Cosmetics Regulation restrict formaldehyde-releasing preservatives.
- Cream:Rich emulsions with higher lipid content for sensitive-skin positioning. Beiersdorf's Hamburg R&D hub concentrates formulation expertise here for pharmacy-channel distribution.
Today's leader: Shaving Oil. Tomorrow's challenger: Pre-Shave Lotion.
Application:
Professional versus personal use contexts split procurement logic between bulk reliability and subscription convenience.
- Personal Care:Individual consumers purchasing through retail or direct-to-consumer channels. Subscription-based replenishment services are decoupling purchases from traditional retail cycles, shifting lock-in toward recurring delivery models anchored by Gillette shave club infrastructure and similar platforms.
- Professional Salons:Institutional buyers prioritizing consistent supply reliability over formulation novelty. Barbers in London and Berlin now consolidate purchasing through specialized supply cooperatives that negotiate direct manufacturer relationships.
- Barbershops:Traditional wet-shaving venues driving demand for professional-grade formulations. North American and Western European barbering academies scaling straight-razor certification programs create institutional pull for heritage apothecary brands.
- E-commerce:Direct-to-consumer brands bypassing wholesale markups to capture margin previously accruing to multi-brand retailers. This channel is expanding most quickly as digital-native labels leverage transparent supply chains for clean beauty positioning.
Professional Salons anchor current volume. E-commerce claims the steepest expansion trajectory.
End User:
Gendered versus unisex positioning determines marketing expenditure allocation and retail placement strategy.
- Men:Core demographic with established grooming rituals and higher category penetration. German men's grooming channels command premium positioning through heritage apothecary brands.
- Women:Growing segment as leg and body shaving protocols extend pre-shave care beyond facial applications. European pharmacy channels adopt botanical formulations fastest here.
- Unisex:Neutral positioning capturing household consolidation and shared-bathroom convenience. Clean-label transparency supports premium pricing across this segment.
- Professionals:Barbers and grooming specialists with institutional purchasing power and formulation expertise demands. London and Berlin barbershop collectives command terms previously reserved for national retail chains.
Men dominate present revenue. Unisex formulations are gaining share fastest as household purchasing consolidates.
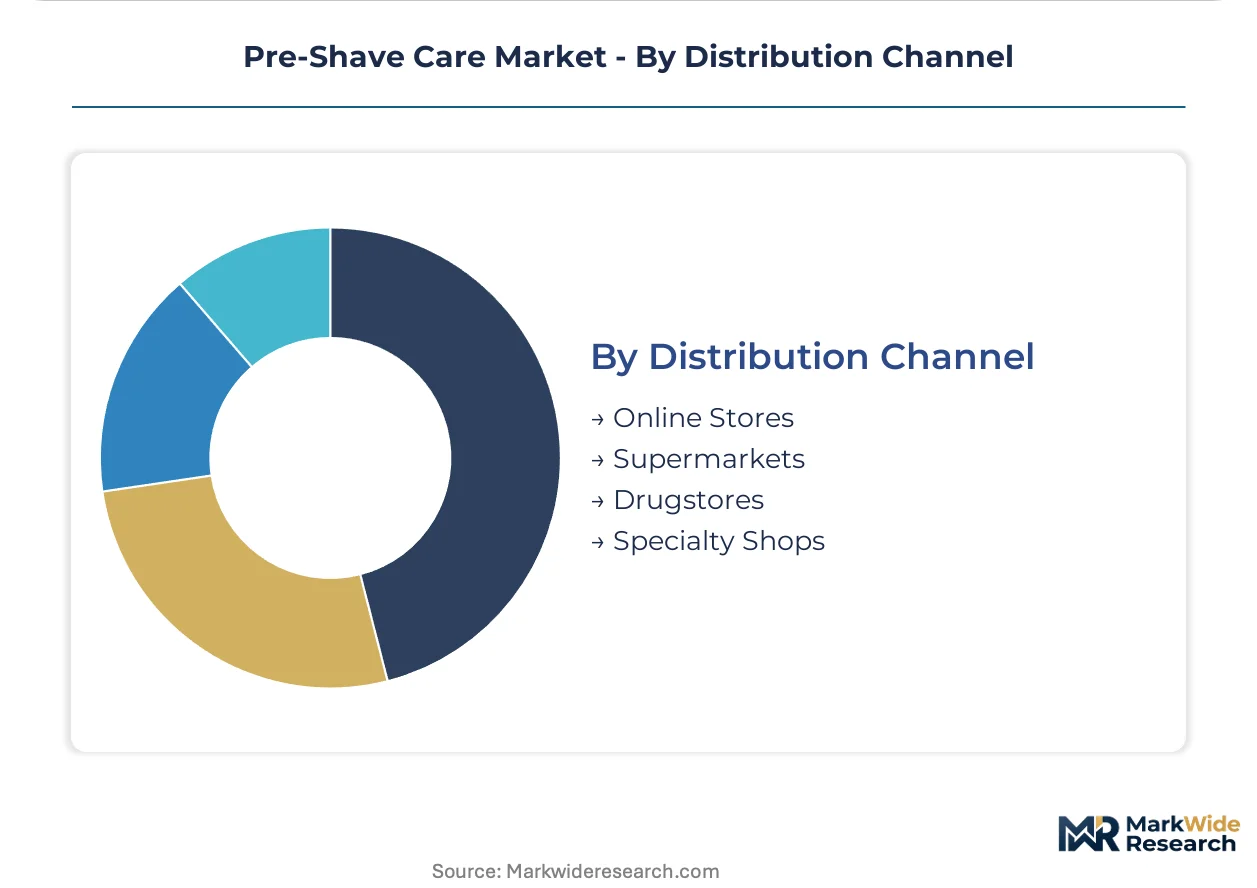
Distribution Channel:
Channel selection determines margin retention and consumer relationship depth.
- Online Stores:Direct-to-consumer infrastructure enabling subscription lock-in and ingredient transparency storytelling. E-commerce bypass captures margin from traditional wholesale markups.
- Supermarkets:Mass-market volume plays with compressed margins and placement fee burdens. L'Oréal sustains premium positioning here through dermatological testing protocols.
- Drugstores:Pharmacy-channel authority with sensitive-skin credibility and pharmacist recommendation leverage. European markets favor this channel for premium botanical formulations.
- Specialty Shops:Barber-supply wholesalers and artisanal apothecaries in Germany, Provence, and Tuscany. Small-batch producers face disproportionate REACH compliance burdens relative to scaled competitors.
Specialty Shops defend premium positioning. Online Stores are climbing the fastest as subscription models reshape purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium positioning through heritage apothecary channels, while the United States drives mass-market volume through subscription infrastructure. Divergent regulatory frameworks across these markets fragment compliance protocols for multi-territory brands.
Germany
Straight-razor certification expansion and artisanal apothecary commerce concentrate demand in Hamburg and Berlin. ECHA's REACH enforcement on fragrance allergens compels transparent ingredient labeling for 26 regulated compounds. Barber-supply wholesalers in Hamburg anchor professional-grade distribution networks serving Western European grooming professionals.
United States
Subscription-based replenishment services and direct-to-consumer brands reshape purchasing patterns away from traditional retail cycles. FDA cosmetic labeling requirements intersect with California's Proposition 65 to restrict formaldehyde-releasing preservatives in legacy gel formulations. Greater Los Angeles and New York Metro clusters concentrate clean-beauty formulation startups targeting state-level disclosure mandates.
United Kingdom
Barbershop collectives in London consolidate procurement through specialized supply cooperatives, bypassing traditional distribution intermediaries. UK cosmetics regulation maintains alignment with EU REACH standards post-Brexit, preserving allergen disclosure requirements. Independent barbershop networks in London and Manchester command purchasing terms previously reserved for national retail chains.
France
Small-batch artisanal producers in Provence face disproportionate compliance burdens under ECHA fragrance allergen enforcement. ANSM pharmaceutical oversight extends to dermocosmetic positioning in pharmacy channels. The Provence-Alpes-Côte d'Azur cluster sustains heritage production of botanical pre-shave formulations despite regulatory cost pressures.
Italy
Tuscan artisanal manufacturers navigate REACH reformulation costs for traditional oil-based pre-shave preparations. Italian cosmetics regulation enforces EU Cosmetics Regulation transparency standards through the Ministry of Health. The Florence-Tuscany corridor maintains small-batch production expertise concentrated in family-owned apothecary operations.
Pre-Shave Care Market Competitive Landscape
Top-tier vendors anchor mass-market scale, while mid-tier specialists defend premium positioning through dermatological credentials and clean-label transparency. The vendor base stratifies across three competitive tiers: multinational consumer goods conglomerates with subscription infrastructure, European pharmacy-channel specialists with R&D concentration, and regional artisanal producers with heritage positioning. Consolidation pressure concentrates volume with scaled players possessing dedicated regulatory affairs functions, while fragmentation persists among small-batch producers facing compliance cost disadvantages. Dominant competitive moves include portfolio diversification into sensitive-skin segments and geographic expansion through direct-to-consumer e-commerce bypass.
Within the mass-market infrastructure tier, The Procter & Gamble Company and Unilever PLC represent subscription-anchored volume plays. L'Oréal S.A. occupies a position exemplifying dermatological testing protocols that sustain premium pharmacy-channel pricing. Beiersdorf AG anchors the sensitive-skin specialization vector through its Hamburg-based R&D concentration. These three corporate structures collectively illustrate how regulatory compliance scale, subscription platform ownership, and regional R&D clustering determine competitive positioning across divergent price tiers.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| L'Oréal S.A. |
| Unilever PLC |
| Beiersdorf AG |
| Edgewell Personal Care Company |
| Johnson & Johnson |
| Energizer Holdings, Inc. |
| Malhotra Shaving Products Ltd. |
| Claus Porto |
| Others |
Value Network & Pricing Analysis
Barbershop collectives in London and Berlin now command purchasing terms previously reserved for national retail chains, anchoring contract-based procurement that compresses margin pools for artisanal suppliers while elevating subscription-anchored volume plays.
Pricing Analysis
Capacity additions in Hamburg and Provence are reshaping price floors for oil-based formulations as German barber-supply wholesalers consolidate volume with heritage apothecary brands. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant clean-label specialists from legacy gel manufacturers facing reformulation costs. Price differentiation hinges on dermatological certification tier and subscription lock-in depth. Pricing pressure stems from shea butter and jojoba oil input volatility, with mass-market gel segments proving most price-sensitive while artisanal oil formulations retain inelastic demand among straight-razor certified professionals.
Supply Chain Analysis
Direct-to-consumer channels handle hyperscale subscription demand while specialty barber-supply cooperatives manage professional bulk procurement. Manufacturing concentrates in Germany, France, and Italy, with Hamburg anchoring sensitive-skin R&D and Provence sustaining small-batch botanical extraction. Raw material flows draw from Moroccan argan cooperatives, Indian jojoba cultivation, and West African shea butter networks. Single-source vulnerability in fermented wheat-derived hyaluronic acid creates chokepoint exposure. Distribution runs through e-commerce platforms, pharmacy-channel wholesalers, and independent barbershop purchasing collectives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-shave care offers margin expansion through clean-label premiumization as regulatory disclosure mandates elevate transparent supply chains above commodity gel competitors.
For Market Incumbents: Hedge against REACH compliance cost inflation by consolidating regulatory affairs functions in Hamburg or Basel while accelerating sensitive-skin formulation R&D. Secure backward integration into jojoba and shea butter sourcing to buffer input volatility. Anchor subscription infrastructure against direct-to-consumer entrants bypassing wholesale markups. For New Entrants and Emerging Players: Capture white space in professional salon bulk formats where barbers prioritize supply reliability over brand novelty. Target German artisanal apothecary channels with transparent 26-allergen disclosure positioning. Leverage e-commerce bypass to undercut traditional retail markups while building clean-beauty credibility ahead of New York state mandate expansion. For Investors and Strategic Acquirers: European consumer goods conglomerates with pharmacy-channel infrastructure represent the most active acquirer category in this space. Long-term viability favors targets with REACH-prepositioned supply chains and Hamburg or Basel R&D clustering. Watch for inflection in state-level clean beauty statute adoption beyond California and New York as signal for premium-tier acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | REACH compliance on fragrance allergens elevates transparent ingredient specialists above legacy competitors in EU pharmacy channels. |
| Subscription Platform Launch | Direct-to-consumer infrastructure captures recurring revenue previously accruing to multi-brand retailers through Gillette-style lock-in mechanics. |
| Professional Bulk Format Expansion | Barbershop collectives in London and Berlin consolidate procurement, opening white space for private-label contract manufacturing. |
| Sensitive-Skin R&D Concentration | Hamburg-based formulation hubs like Beiersdorf's anchor pharmacy-channel credibility through dermatological testing protocols. |
| Botanical Supply Integration | Backward integration into Moroccan argan and Provence botanical networks buffers margin compression from commodity input volatility. |
Research Methodology
Coverage spans Germany, the United States, the United Kingdom, France, and Italy, with primary inputs from each market's grooming professionals and regulatory environment. The analysis combines structured interviews with barbershop owners, formulation chemists at Hamburg and Basel R&D hubs, pharmacy-channel buyers, and contract manufacturing executives with secondary validation through ECHA REACH filings, FDA cosmetic labeling databases, California Proposition 65 enforcement records, and EU Cosmetics Regulation transparency standards. Bottom-up demand modeling from subscription platform disclosures and top-down market sizing from customs trade data were triangulated to establish volume baselines.
Rate-of-change decomposition across the projection horizon segments growth by product type (shaving oil, pre-shave lotion, gel, cream), application channel (personal care, professional salons, barbershops, e-commerce), and end-user demographic (men, women, unisex, professionals). CAGRs were derived from trend extrapolation of straight-razor certification enrollment, clean beauty statute adoption curves, and e-commerce penetration rates in men's grooming. Industry-specific forecast inputs include shea butter and jojoba oil price elasticity models and REACH reformulation cost schedules for small-batch producers.
Underlying measurement precision varies by segment; e-commerce channel data and subscription platform disclosures carry tighter precision than artisanal apothecary sales estimates. Forecasts reflect assumptions regarding regulatory harmonization between FDA oversight and emerging state-level mandates, continued straight-razor certification expansion, and stable botanical input supply chains. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Zero-Waste Shampoo Market
Beauty & Personal Care
Hair Styling Equipment Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Deodorant Products Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Personal Care Shower and Bath Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market