
 Asia Pacific Beauty Fridges Market | 2026-2036
Asia Pacific Beauty Fridges Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Beauty Fridges Market Insights
Premium thermoelectric cooling specifications is unwinding legacy compressor-based designs across the Asia Pacific Beauty Fridges landscape. COOSEON leverages proprietary semiconductor cooling modules to dominate the compact vanity segment. LG anchors its position through backward integration into compressor technology, while Samsung competes via smart-home connectivity features that extend its appliance ecosystem into beauty storage.
Asia Pacific beauty fridges denote thermoelectric or compressor-based refrigerated enclosures engineered to maintain cosmetic formulations between 4°C and 12°C, preserving active ingredients in vitamin C serums, retinols, and probiotic skincare through controlled thermal stability. Mini fridges lead unit shipments due to their dorm-friendly footprint and impulse-purchase price positioning, yet cosmetic coolers capture disproportionate margin pools through mirrored interiors and LED vanity integration. Online retail channels accelerate fastest, though specialty stores sustain higher conversion rates through tactile product demonstration.
China's SAMR enforces GB standards for small appliance energy labeling, while South Korea's K-beauty export framework mandates temperature-stability documentation for cross-border cosmetic logistics. Japan's METI electrical appliance safety regulations further shape product certification requirements for entrants targeting premium household segments. Stakeholders must monitor evolving energy-efficiency thresholds and cross-border e-commerce duty structures as these regulatory layers compound compliance complexity across national boundaries.
Market Dynamics
Thermoelectric semiconductor cooling is displacing compressor architectures across the Asia Pacific Beauty Fridges landscape, compressing unit costs while enabling vanity-integrated form factors that reshape where cosmetic refrigeration sits within household spaces.
Growth Catalysts
- China's GB energy-efficiency standards:Mandatory labeling requirements under SAMR accelerate replacement cycles for legacy compressor units, pulling thermoelectric alternatives into premium urban households.
- K-beauty export logistics:South Korea's temperature-stability documentation mandates for cross-border cosmetic shipments create institutional demand for certified cooling infrastructure among export-oriented brands.
- Urban household density:Compact living in Shanghai, Seoul, and Tokyo drives uptake of dorm-footprint mini fridges that integrate with vanity workflows.
Market Restraints
- Thermoelectric efficiency ceiling:Peltier module performance degrades above 35°C ambient, limiting deployment in non-air-conditioned Southeast Asian climates without supplemental thermal management.
- Semiconductor supply concentration:Bismuth telluride substrate production clusters in Chinese and Korean foundries, exposing module assemblers to input price volatility and allocation constraints.
- Compressor incumbent lock-in:LG's backward integration into compressor technology creates cost barriers for thermoelectric entrants targeting volume appliance retail channels.
Strategic Opportunities
- India's tier-two urbanization:Cooling appliance penetration in Bengaluru, Hyderabad, and Pune remains below saturation, opening whitespace for vanity-integrated cosmetic storage among emerging affluent households.
- Smart-home convergence:Integration of beauty fridges with IoT-enabled skincare routines—temperature logging, product expiry tracking—creates subscription service potential around consumable replenishment.
- Australia's TGA cosmetic stability guidelines:Emerging regulatory attention to active ingredient preservation creates compliance-driven demand for documented thermal control in professional salon and clinic settings.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous pursuit of China's CCC mark, Japan's PSE certification, and South Korea's KC approval extends product launch windows by 8-14 months for regional rollouts.
- Skill scarcity in thermoelectric system design:Engineering talent capable of optimizing COP (coefficient of performance) in compact Peltier assemblies concentrates in Korean and Taiwanese component houses, constraining in-house R&D buildout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Beauty Fridges Market |
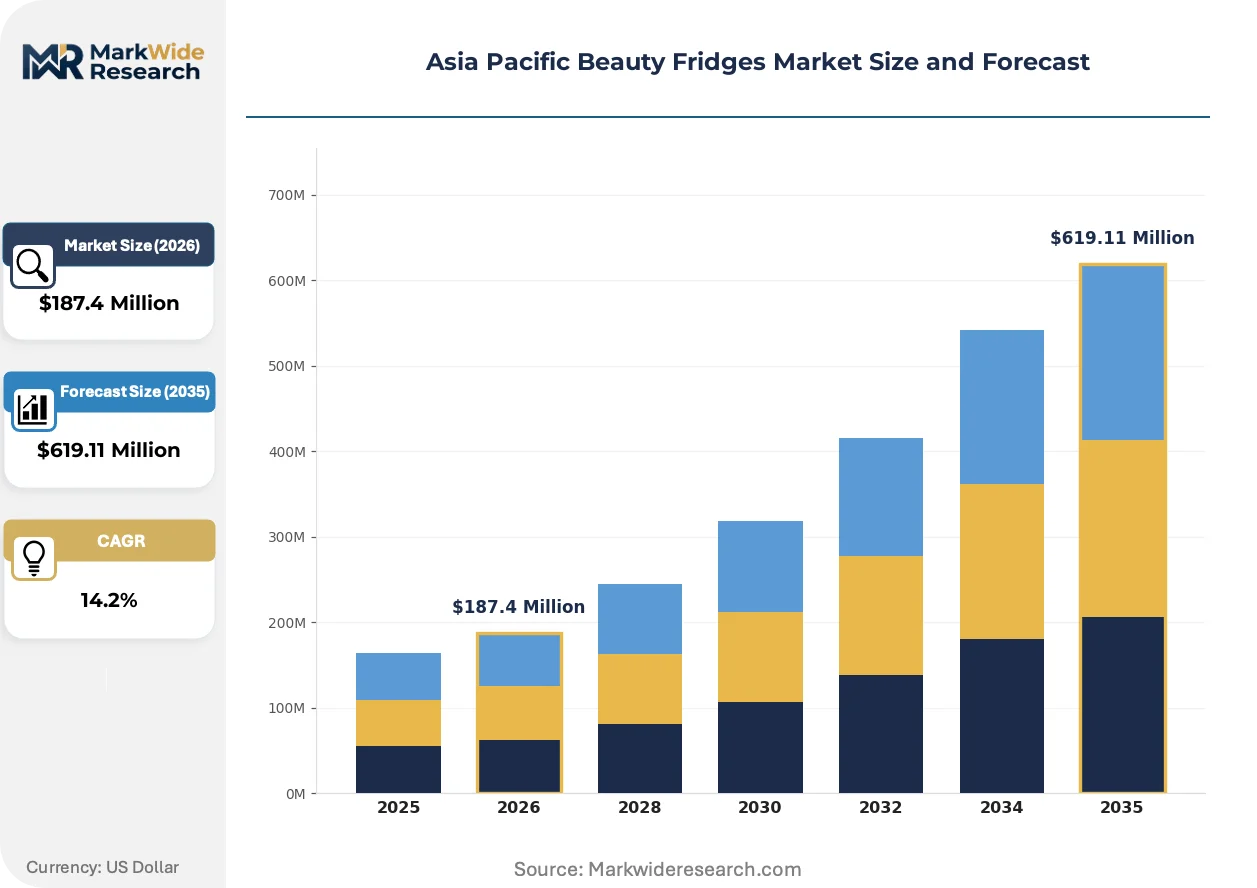
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Fridges, Cosmetic Coolers, Makeup Refrigerators, Skincare Chillers Distribution Channel: Online Retail, Specialty Stores, Department Stores, E-commerce Platforms End User: Individual Consumers, Salons, Spas, Beauty Clinics Capacity: 5L, 10L, 15L, 20L |
| Companies Covered | COOSEON, LG, HCK Refrigeration, Samsung, Hisense, Cooluli, Teami LLC, FaceTory, Inc., Chefman, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Beauty Fridges Market Trends and Innovations
Active ingredient preservation science is redefining cosmetic storage specifications, pulling refrigeration from luxury accessory toward functional skincare infrastructure. Three intersecting developments are compressing product development cycles and reshaping competitive entry points.
Solid-state thermoelectric cooling is miniaturizing vanity-integrated enclosures below 4-liter capacity while maintaining 4-12°C setpoint stability. Millennial consumers in China's tier-one cities are adopting these units at pace sufficient to outship traditional compressor alternatives in online channels. The technology is miniaturizing cosmetic refrigeration into mirror-embedded and drawer-integrated form factors that disappear within existing vanity furniture.
South Korea's K-beauty export framework now mandates temperature excursion documentation for vitamin C and retinol formulations crossing customs thresholds. This regulatory layer forces domestic brands to specify certified cooling infrastructure within their logistics specifications, elevating refrigeration from operational cost to compliance necessity. Cross-border e-commerce fulfillment centers in Incheon and Busan are responding by installing modular cooling banks to maintain chain-of-custody records.
Skincare enthusiasts are compressing purchase cycles through algorithmic replenishment triggered by connected device data. Specialty retail channels with tactile demonstration capacity sustain higher conversion rates, yet online platforms capture volume through subscription bundling of fridges with serum assortments. This behavioral shift concentrates in Seoul and Tokyo, where connected beauty ecosystems from Samsung and local IoT startups embed refrigeration within broader vanity automation workflows.
Asia Pacific Beauty Fridges Market Segmentation
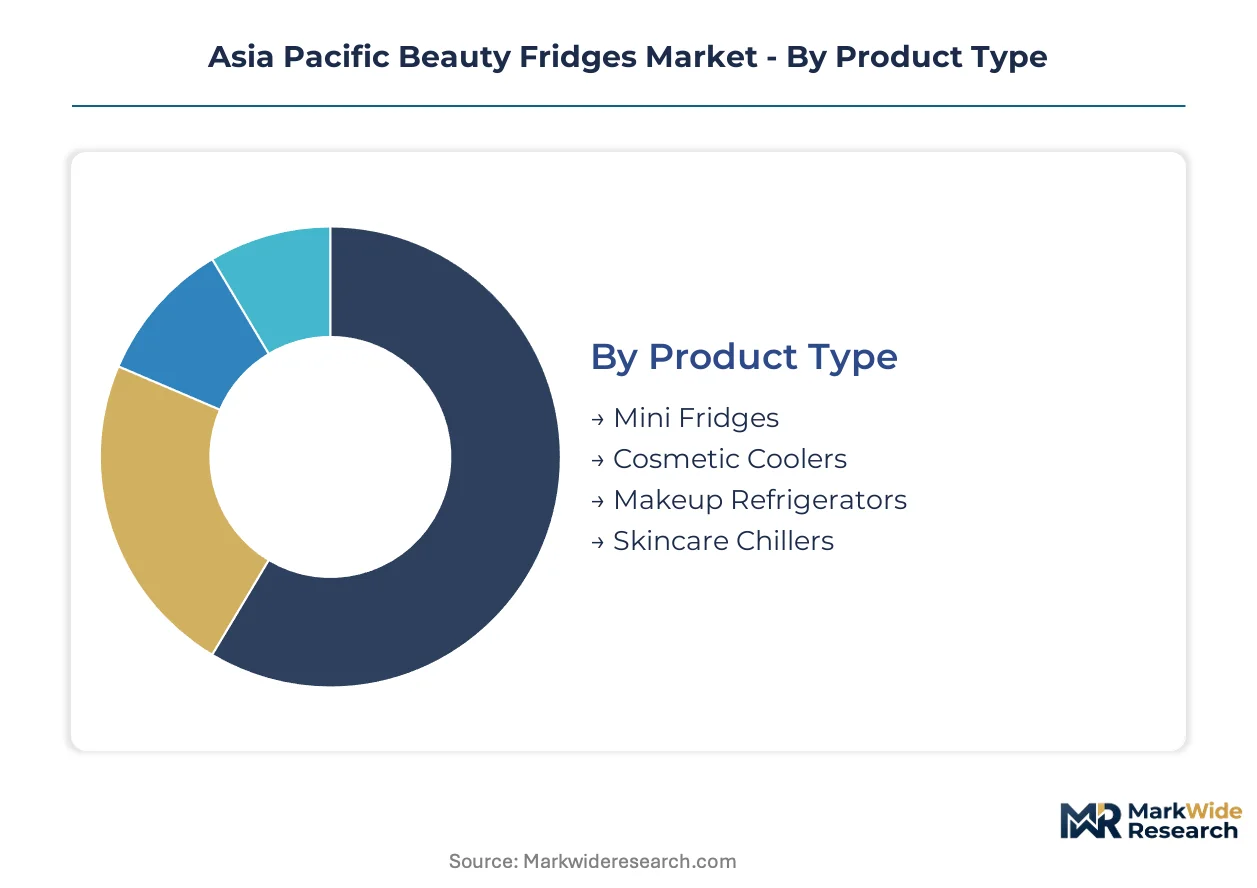
Segmentation in Asia Pacific beauty fridges reveals how cooling technology fragments across consumer workflows, distribution economics, and professional compliance requirements. Understanding these divides exposes where margin pools concentrate versus where volume scales.
Product Type:
Channel mix varies sharply by form factor: mini fridges dominate mass e-commerce through impulse pricing, while cosmetic coolers command specialty store premiums through tactile demonstration.
- Mini Fridges:Thermoelectric units under 10 liters with dorm-friendly footprints. Demand clusters in China's tier-one cities among millennial renters in Shanghai and Beijing, where compact living constraints override cooling performance preferences.
- Cosmetic Coolers:Vanity-integrated enclosures featuring mirrored interiors, LED lighting, and 4-12°C precision control. Seoul and Tokyo households drive uptake as K-beauty routines professionalize home skincare infrastructure.
- Makeup Refrigerators:Hybrid designs blending refrigeration with brush storage and palette organization.
- Skincare Chillers:Single-purpose units optimized for serum and ampoule preservation.
By volume, mini fridges lead. By growth pace, cosmetic coolers are expanding most quickly through premium channel expansion.
Distribution Channel:
Cost tiers separate channels: online retail captures economy and standard segments through price transparency, while department stores anchor premium positioning through service bundling.
- Online Retail:Direct-to-consumer platforms and brand-owned storefronts with algorithmic replenishment integration. Conversion rates lag specialty stores but subscription bundling with skincare assortments drives lifetime value in South Korea's digitally native consumer base.
- Specialty Stores:Beauty-focused retail with tactile demonstration capacity and trained staff. China's tier-one cities sustain higher margins here as consumers validate thermoelectric performance before purchase.
- Department Stores:Premium positioning through gift-with-purchase programs and loyalty tier access.
- E-commerce Platforms:Marketplace aggregators with cross-border logistics for K-beauty export channels.
Specialty stores dominate value per transaction. E-commerce platforms are gaining share fastest through cross-border fulfillment scale.
End User:
Application requirements dictate specification divergence: individual consumers prioritize vanity integration and noise levels, while professional settings demand temperature logging and compliance documentation.
- Individual Consumers:Household purchasers seeking personal skincare preservation with aesthetic integration. Urban density in Tokyo, Seoul, and Shanghai shapes preference for sub-10L footprints that disappear within existing vanity furniture.
- Salons:High-throughput professional settings requiring batch storage for treatment products. Australia's emerging TGA attention to cosmetic stability is pulling documented thermal control into compliance specifications.
- Spas:Wellness-oriented environments emphasizing ambient design and quiet operation.
- Beauty Clinics:Medical-aesthetic hybrid settings with the strictest chain-of-custody requirements.
Individual consumers anchor unit volume. Beauty clinics are climbing the fastest as regulatory documentation requirements spread.
Capacity:
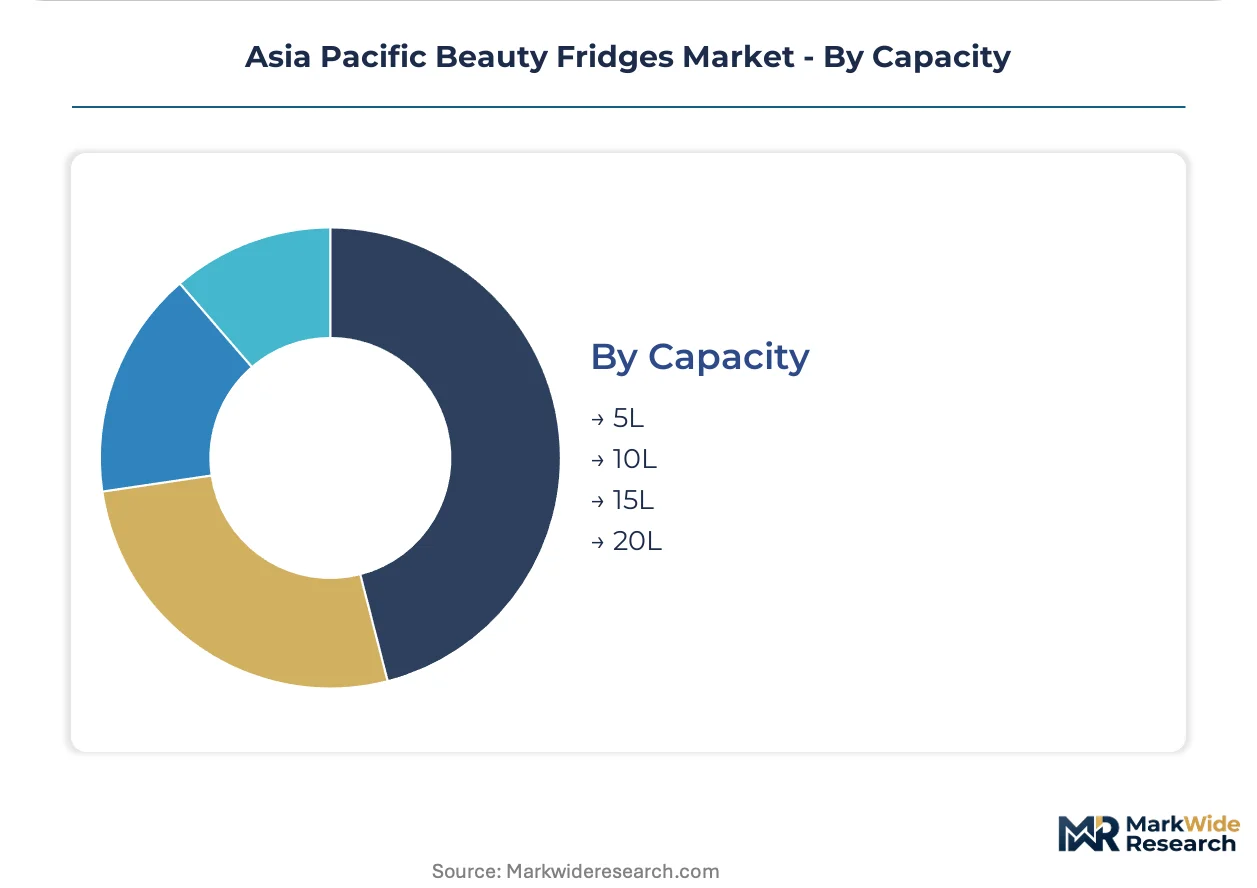
Volume economics concentrate at the extremes: 5L units scale through component standardization, while 20L professional units capture service-contract attach rates.
- 5L:Single-user vanity units with semiconductor cooling modules. China's GB energy-efficiency labeling accelerates replacement of legacy compressor alternatives in this segment.
- 10L:Dual-zone designs separating skincare from makeup storage.
- 15L:Small salon configurations with basic inventory management.
- 20L:Professional-grade enclosures with data logging and multi-user access controls. South Korea's K-beauty export temperature-stability mandates elevate this capacity tier into logistics infrastructure.
5L units dominate shipment volume. 20L configurations are gaining share fastest through professional compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across the Asia Pacific Beauty Fridges Market reveal concentrated production in China and South Korea against rising domestic absorption in tier-one cities. Trade flows increasingly favor intra-regional fulfillment over external markets as K-beauty logistics specifications tighten.
China
Shanghai and Beijing households drive premium thermoelectric uptake through vanity-integrated cosmetic coolers. SAMR's GB energy-efficiency labeling mandates accelerate replacement of legacy compressor units in 5L segments. The Yangtze River Delta manufacturing cluster supplies semiconductor cooling modules to domestic brands and Korean assemblers alike.
South Korea
Seoul's digitally native consumer base compresses purchase cycles through subscription bundling of fridges with serum assortments. K-beauty export regulations mandate temperature-stability documentation for vitamin C and retinol formulations crossing customs thresholds. Incheon and Busan fulfillment centers install modular cooling banks to maintain chain-of-custody records for cross-border shipments.
Japan
Tokyo households prioritize sub-10L footprints that disappear within existing vanity furniture amid compact living constraints. METI electrical appliance safety regulations shape PSE certification requirements for premium household segments. The Kansai region around Osaka hosts specialty retail channels with tactile demonstration capacity sustaining higher conversion rates.
Australia
Sydney and Melbourne clinics pull documented thermal control into compliance specifications as TGA attention to cosmetic stability emerges. Professional salon settings drive 20L capacity uptake with data logging requirements. Queensland's wellness-oriented spa environments emphasize ambient design and quiet operation in cosmetic refrigeration procurement.
India
Bengaluru, Hyderabad, and Pune present whitespace for vanity-integrated cosmetic storage among emerging affluent households. Cooling appliance penetration remains below saturation in tier-two urbanization corridors. Local assembly operations face multi-jurisdiction certification timelines extending product launch windows for regional rollouts.
Asia Pacific Beauty Fridges Market Competitive Landscape
Listed leaders compete with private specialists across cooling technology architectures and distribution channel depth. The vendor base spans Korean conglomerates with backward integration into compressor technology, Chinese fabricators with captive semiconductor module supply, and Western specialists targeting vanity-integrated form factors. Three archetypes dominate: scale-driven appliance conglomerates, thermoelectric technology specialists, and digitally native direct-to-consumer brands. Competitive moves concentrate on smart-home ecosystem integration and cross-border e-commerce fulfillment partnerships.
Within the technology-specialist tier, COOSEON leverages proprietary semiconductor cooling modules to anchor the compact vanity segment, while HCK Refrigeration exemplifies Chinese fabrication capacity serving both domestic and export demand. Among conglomerate players, LG and Samsung occupy positions defined by backward integration into compressor technology and smart-home connectivity features respectively, extending appliance ecosystems into beauty storage workflows.
| Leading Market Players |
|---|
| COOSEON |
| LG |
| HCK Refrigeration |
| Samsung |
| Hisense |
| Cooluli |
| Teami LLC |
| FaceTory, Inc. |
| Chefman |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with semiconductor foundries lock in bismuth telluride substrate access while capping module cost volatility for thermoelectric assemblers serving China's GB-compliant premium tier. This contract structure simultaneously secures supply continuity and price visibility across the 8-14 month multi-jurisdiction certification timelines that delay product launches.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Asia Pacific Beauty Fridges landscape. Price differentiation rests on certification grade—CCC, PSE, and KC marks—and volume scale commitments from export-oriented K-beauty brands. Cost compression in the standard tier is intensifying because LG's backward integration into compressor technology forces thermoelectric specialists to absorb margin pressure. Individual consumers in China's tier-one cities show least price sensitivity for vanity-integrated cosmetic coolers, while mass e-commerce channels for mini fridges face acute price transparency.
Supply Chain Analysis
China and South Korea anchor bismuth telluride substrate production for thermoelectric modules, with Taiwan supplying precision controllers and thermal interface materials. Raw material dependencies center on semiconductor-grade bismuth telluride, aluminum heat sinks, and mirrored glass components for vanity integration. Single-source vulnerability concentrates in Chinese foundries controlling 70% of global Peltier substrate output, exposing assemblers to allocation constraints during demand surges. Distribution runs through Yangtze River Delta manufacturing clusters into Incheon and Busan fulfillment centers for K-beauty export logistics.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoelectric semiconductor cooling is disrupting compressor architectures across beauty refrigeration, with South Korea's K-beauty export regulations mandating temperature-stability documentation as the regulatory inflection accelerating compliance-driven demand.
For Market Incumbents: Shield market position by deepening backward integration into compressor technology to maintain cost barriers against thermoelectric entrants, while accelerating PSE and KC certification investments to compress the 8-14 month multi-jurisdiction approval timelines that delay competitive response. LG and Samsung must leverage existing appliance ecosystem relationships to embed beauty fridges within smart-home connectivity workflows before digitally native brands capture subscription bundling economics. For New Entrants and Emerging Players: Certification fast-track through Australia's emerging TGA cosmetic stability guidelines opens whitespace for documented thermal control in professional salon and clinic settings where compliance requirements are climbing fastest. Target India's tier-two urbanization corridors—Bengaluru, Hyderabad, Pune—where cooling appliance penetration remains below saturation and vanity-integrated cosmetic storage lacks established incumbents. Deploy direct-to-consumer online retail with algorithmic replenishment integration to mirror Seoul's digitally native subscription bundling model. For Investors and Strategic Acquirers: Capital is best deployed toward thermoelectric technology specialists with proprietary semiconductor cooling modules and captive bismuth telluride substrate relationships, positioned to capture margin pools as GB energy-efficiency labeling accelerates replacement cycles. Long-term viability hinges on smart-home ecosystem integration capabilities and cross-border e-commerce fulfillment partnerships. The signal to watch is SAMR enforcement actions on legacy compressor unit energy labeling, which would steepen replacement demand curves.| Strategic Initiative | Industry Significance |
|---|---|
| Smart-Home Ecosystem Integration | Samsung's connectivity features extend appliance ecosystems into beauty storage workflows across Seoul and Tokyo households. |
| Multi-Jurisdiction Certification Investment | Parallel pursuit of CCC, PSE, and KC marks compresses 8-14 month launch windows for regional rollouts. |
| Backward Integration into Compressor Technology | LG's upstream control over compressor manufacturing creates cost barriers for thermoelectric entrants in volume retail channels. |
| Direct-to-Consumer Subscription Bundling | Online platforms in South Korea capture lifetime value through algorithmic replenishment of fridges with serum assortments. |
| Professional Compliance Documentation | Australia's TGA attention to cosmetic stability pulls data-logging 20L units into clinic procurement specifications. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with product managers at thermoelectric specialists, procurement leads at K-beauty export brands, and regulatory affairs officers navigating SAMR GB standards, alongside secondary validation through customs records, SAMR energy-labeling databases, and METI electrical appliance safety filings. Bottom-up shipment data from Yangtze River Delta manufacturing clusters was triangulated against top-down demand estimates from China's tier-one city household penetration surveys and Seoul's digitally native consumer panel data.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning cooling technology architecture, capacity tier, distribution channel economics, and end-user compliance requirements. CAGRs were derived from installed base replacement cycles under China's GB labeling mandates and K-beauty export logistics growth trajectories. Industry-specific inputs included bismuth telluride substrate pricing volatility indices and cross-border e-commerce duty structure evolution in Incheon and Busan fulfillment zones.
Decision-makers should treat outputs as directional under assumptions of continued SAMR enforcement on energy-efficiency thresholds and stable semiconductor substrate allocation from Chinese and Korean foundries; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in K-beauty export regulation stringency and thermoelectric module COP performance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
South America Deodorants Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Artificial Nails Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Middle East Herbal Shampoo Market