
 US Cosmetics Market | 2026-2036
US Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
US Cosmetics Market Insights
Professional salon and spa channels are hardening as a priority distribution tier for premium color cosmetics and hair treatment lines. L'Oréal leverages its professional division to control salon-exclusive formulations and education infrastructure. The Estée Lauder Companies anchors prestige skincare through dermatology clinic partnerships and medical spa channels. Procter & Gamble competes in mass-market haircare with scaled manufacturing and retail shelf dominance.
Cosmetics encompass chemically formulated preparations applied to the human body for cleansing, beautifying, or altering appearance, typically containing emulsifiers, active ingredients, and preservation systems at pH ranges between 4.5 and 7.0. These products serve commercial purposes across personal grooming, professional beauty services, and therapeutic skin management. Skincare and anti-aging applications command the deepest margin pools due to clinical positioning and repeat purchase loyalty. Hair treatment and color cosmetics segments sustain volume leadership through salon professional channels and direct-to-consumer digital platforms. Fragrance and personal hygiene categories occupy mature growth trajectories with consolidation pressure on mid-tier brands.
FDA oversight of cosmetic safety and labeling under the Modernization of Cosmetics Regulation Act interacts with California's Proposition 65 chemical disclosure requirements and state-level bans on per- and polyfluoroalkyl substances. The FTC monitors advertising claims for anti-aging and sun protection efficacy, creating compliance costs that favor larger R&D budgets. Stakeholders must monitor evolving state patchworks of ingredient restrictions and the shifting balance between clinical validation and clean-beauty marketing positioning.
Market Dynamics
Clean-beauty ingredient mandates and state-level chemical disclosure laws are fragmenting formulation standards across the US, forcing brands to maintain multiple product variants and accelerating R&D cycle compression.
Growth Catalysts
- FDA Modernization Act 2.0:Animal testing alternatives now satisfy federal safety requirements, reducing pre-market validation timelines for novel active ingredients and accelerating botanical extract adoption.
- California Proposition 65 enforcement:Heightened litigation risk around chemical exposure warnings is pressuring reformulation toward exempt ingredient classes, creating first-mover advantages for compliant brands.
- Professional salon channel expansion:Medical spa and dermatology clinic partnerships are anchoring prestige skincare distribution in Texas and Florida metropolitan corridors.
Market Restraints
- Per- and polyfluoroalkyl substance phase-outs:Washington and Maine state bans on PFAS in cosmetics are forcing waterproof mascara and long-wear foundation reformulations with inferior performance profiles.
- Fragrance allergen disclosure mandates:California's SB 312 requires granular ingredient reporting that exposes proprietary formulations to competitive intelligence harvesting.
- Biopolymer packaging cost premiums:Sugarcane-derived polyethylene and mycelium-based containers command 40-60% unit cost premiums versus conventional petroleum plastics, compressing mass-market margins.
Strategic Opportunities
- Men's grooming underpenetration:Male-specific skincare and color cosmetics remain underdeveloped in the US Southeast and Mountain West, offering whitespace for gender-positioned brand extensions.
- Microbiome-friendly certification:EWG Verified and NSF/ANSI 305 standards are creating premium pricing tiers for preservative-free and prebiotic formulations in prestige channels.
- AI-driven personalization:Skin diagnostic tools and algorithmic shade-matching are converging with telemedicine platforms to enable subscription-based custom formulation services.
Industry Challenges
- Toxicology expertise scarcity:Cosmetic chemists with dual competency in natural extract stability and regulatory submission navigation command premium compensation that mid-tier brands cannot absorb.
- Legacy ERP integration:Batch record systems designed for conventional manufacturing require costly reconfiguration to track ingredient provenance for state-level disclosure compliance.
- Cross-state labeling complexity:Divergent banned substance lists between California, New York, and Washington force SKU proliferation that strains inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cosmetics Market |
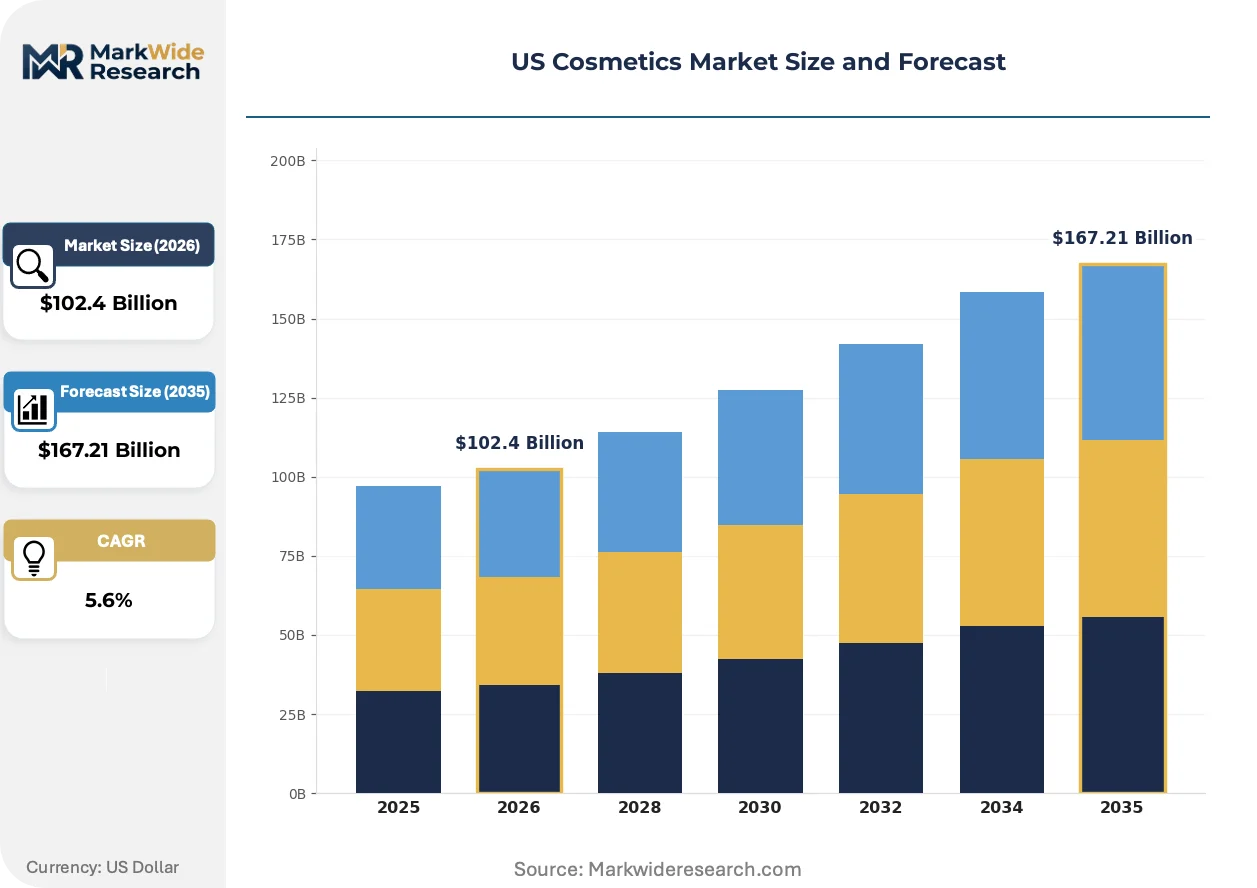
| Market Size in 2026 | $102.4 Billion |
| Market Size in 2035 | $167.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrances, Personal Hygiene Formulation: Creams, Lotions, Serums, Powders, Gels, Sprays Application: Anti-Aging, Sun Protection, Moisturizing, Cleansing, Color Cosmetics, Hair Treatment End User: Salons, Spas, Dermatology Clinics, Beauty Retailers, Direct Consumers |
| Companies Covered | L'Oréal, The Estée Lauder Companies, Procter & Gamble, Unilever, Coty, Shiseido, Johnson & Johnson, Beiersdorf, Kao Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cosmetics Market Trends and Innovations
Bioengineered actives and fermentation-derived ingredients are displacing conventional botanical extracts, while regulatory disclosure mandates and direct-to-consumer channel evolution are compressing traditional wholesale relationships.
Biotechnology platforms utilizing yeast fermentation and plant cell culture are integrating recombinant collagen, squalane, and ceramide production into industrial-scale supply chains. Prestige skincare brands are adopting these inputs to circumvent agricultural volatility and achieve batch-to-batch consistency. This molecular manufacturing approach is integrating vertically into brand-owned production facilities, reducing dependency on commodity ingredient traders.
The Modernization of Cosmetics Regulation Act (MoCRA) mandates facility registration, adverse event reporting, and good manufacturing practice compliance for all US market participants. The FDA's expanded inspection authority is elevating documentation burdens that favor enterprises with dedicated regulatory affairs departments. Small-batch indie brands are responding by consolidating manufacturing partnerships with established contract manufacturers possessing existing quality management certifications.
Subscription-based replenishment models are displacing traditional retail replenishment cycles in color cosmetics and skincare, with consumers accepting algorithmic curation in exchange for unit discounts. Direct-to-consumer platforms are capturing loyalty data that enables predictive inventory positioning and limited-edition drop strategies. This channel migration is most visible in California and New York, where digitally native brands have achieved sufficient scale to bypass Sephora and Ulta shelf negotiations.
US Cosmetics Market Segmentation
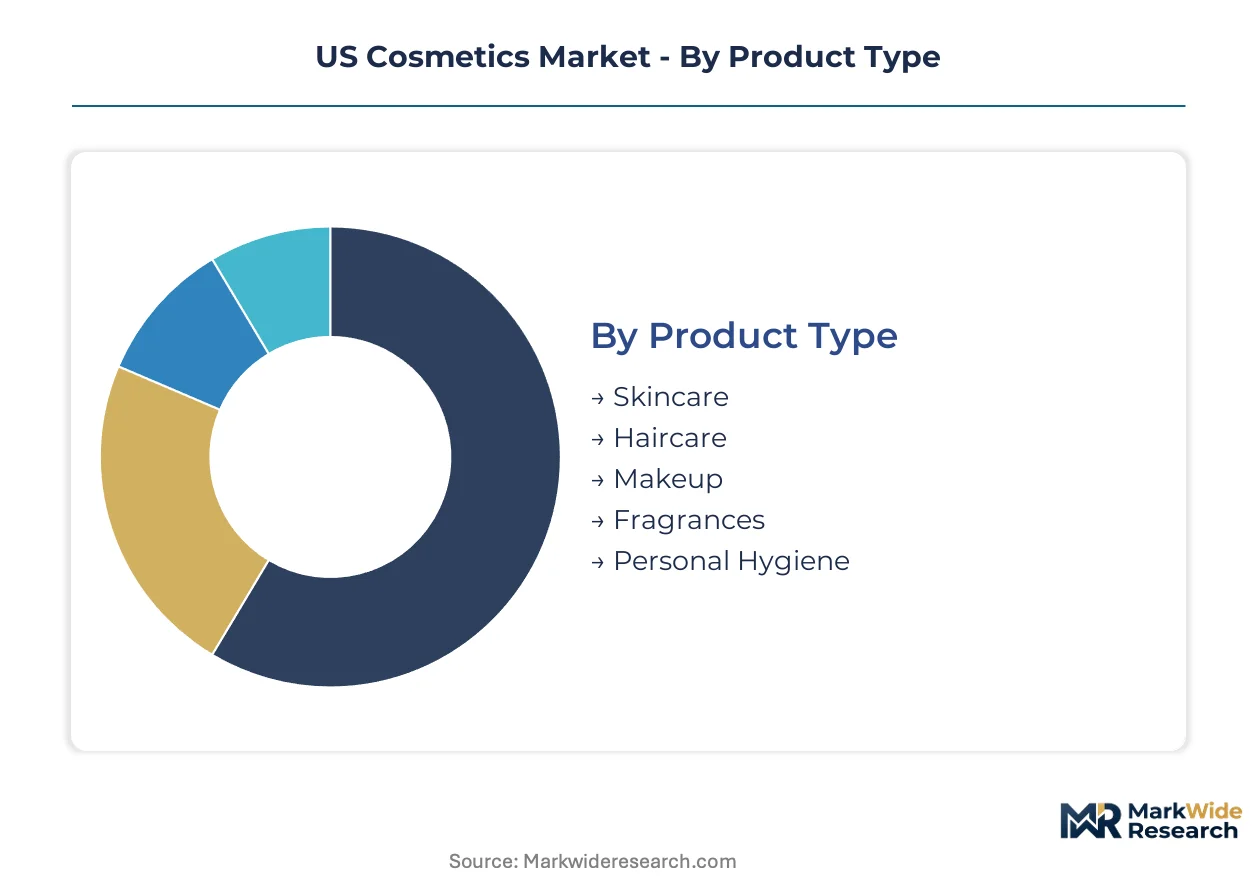
US cosmetics manufacturers configure production lines around formulation chemistry and channel certification requirements rather than consumer demographics alone. Segment boundaries increasingly blur as prestige skincare brands enter dermatology clinics while mass-market haircare lines develop salon-exclusive professional tiers.
Product Type:
Supply concentration clusters around skincare and haircare manufacturing corridors in New Jersey, California, and Illinois, where contract manufacturers maintain FDA-registered facilities for multiple brand portfolios.
- Skincare:Emulsion-based formulations with active concentrations between 0.5% and 2% dominate prestige manufacturing. Demand concentrates in dermatology clinics across California and New York metropolitan areas, where medical spa channel expansion requires clinical validation documentation.
- Haircare:Anionic and cationic surfactant systems at pH 4.5-6.0 constitute the bulk of professional salon production. Texas and Florida absorb the highest volume through independent salon distribution networks, though PFAS-free waterproofing reformulations are compressing styling product performance claims.
- Makeup:Pigment dispersion technology and film-forming polymers define formulation complexity.
- Fragrances:Alcohol-based compositions with 15-20% perfume oil concentration face California SB 312 allergen disclosure mandates.
- Personal Hygiene:Antiperspirant actives and surfactant systems operate on mature cost-competitive manufacturing platforms.
Skincare absorbs the bulk of installed capacity; haircare is expanding most quickly through professional channel verticalization.
Formulation:
Cost tier differentiation separates premium biotech-derived formats from commodity petroleum-based vehicles, with preservative-free and microbiome-friendly variants commanding manufacturing line upgrades.
- Creams:Oil-in-water emulsions with 15-30% lipid phase dominate facial moisturizing manufacturing. Prestige brands in California are retrofitting facilities for fermentation-derived ceramide incorporation, bypassing agricultural supply volatility.
- Serums:Hydrogel and anhydrous bases enable high-actives penetration at low viscosity. New York and Texas dermatology clinics are driving demand for peptide and retinoid concentrates requiring cold-chain stability protocols.
- Lotions:Lower viscosity emulsions with higher water content serve mass-market volume production.
- Powders:Talc-free and mica-based mineral formulations face Washington state mining disclosure requirements.
- Gels:Carbomer-thickened aqueous systems support alcohol-free sanitization and styling applications.
- Sprays:Aerosol and pump-dispensed formats confront propellant regulation under EPA volatile organic compound standards.
Creams and serums together anchor manufacturing margin pools; serums are climbing the fastest on biotechnology ingredient adoption.
Application:
Volume concentration in cleansing and moisturizing applications funds R&D investment for clinical-positioned segments requiring FDA substantiation documentation.
- Anti-Aging:Retinoid, peptide, and antioxidant formulations require photostability testing and dermal tolerance documentation. Florida medical spas and California dermatology partnerships are absorbing inventory for in-office dispensing programs.
- Sun Protection:Mineral and chemical UV filter blends at SPF 30-50 face FDA monograph compliance and Hawaii coral reef-safe prohibitions on oxybenzone and octinoxate.
- Moisturizing:Humectant and occlusive combinations serve baseline daily use across all price tiers.
- Cleansing:Surfactant selection balances efficacy with microbiome-friendly positioning for premium differentiation.
- Color Cosmetics:Pigment load and wear-time claims drive waterproof reformulation away from PFAS-dependent technologies.
- Hair Treatment:Bond-building and keratin-smoothing chemistries concentrate in professional salon channels.
Moisturizing and cleansing absorb the bulk of unit volume; anti-aging is gaining share fastest on clinical channel expansion.
End User:
Customer type determines packaging specification, batch size flexibility, and regulatory documentation depth, with professional channels requiring adverse event reporting infrastructure that direct-to-consumer brands often outsource.
- Salons:Professional-only formulations with elevated developer concentrations and oxidative dyes require state cosmetology board compliance. Texas and California metropolitan corridors concentrate independent salon distribution, with L'Oréal and Kérastase anchoring education-dependent loyalty programs.
- Dermatology Clinics:Medical-grade skincare with clinical trial backing requires FDA facility registration and GMP documentation. Prestige brands are securing exclusive dispensing partnerships in Florida and New York aesthetic medicine practices.
- Spas:Treatment-room protocols and retail resale combinations demand dual-use formulation stability.
- Beauty Retailers:Sephora and Ulta shelf placement requires MOCRA-compliant labeling and supply chain transparency.
- Direct Consumers:Subscription models and algorithmic curation are displacing traditional replenishment cycles in digitally native brand portfolios.
Beauty retailers absorb the bulk of wholesale volume; dermatology clinics are expanding most quickly on medical spa convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US cosmetics manufacturing concentrates in coastal states with FDA-registered infrastructure, while consumption gravitates toward metropolitan corridors with dense professional salon and medical spa networks. California and New Jersey anchor production capacity; Texas and Florida absorb disproportionate volume through dermatology clinic and independent salon channels.
California
Los Angeles and Orange County host the nation's densest cluster of contract manufacturers serving prestige skincare brands. The state's Proposition 65 enforcement creates reformulation pressure toward exempt ingredient classes. Bay Area biotechnology firms supply fermentation-derived actives to local formulators, reducing agricultural supply dependency.
New York Metro
Manhattan and Brooklyn concentrate headquarters operations for digitally native direct-to-consumer brands. New York State's pending PFAS restrictions in personal care products accelerate waterproof mascara reformulation timelines. Long Island manufacturing corridors maintain FDA-registered facilities for fragrance and color cosmetics production.
Texas
Houston and Dallas-Fort Worth absorb the highest per-capita volume of professional salon haircare through independent distributor networks. The state cosmetology board maintains strict licensing requirements for professional-only oxidative dye formulations. Medical spa channel expansion in Austin and San Antonio drives prestige skincare dispensing partnerships.
New Jersey
The Garden State corridor between Newark and Edison hosts legacy contract manufacturing infrastructure for mass-market personal care. EPA volatile organic compound standards for aerosol propellants elevate compliance costs for spray-format production. Proximity to Port Newark facilitates imported active ingredient receipt from European suppliers.
Florida
Miami and Tampa Bay aesthetic medicine practices anchor medical-grade skincare dispensing programs. The state's humidity-driven demand for long-wear makeup confronts PFAS phase-out challenges in waterproof formulations. Orlando-area distribution centers serve southeastern beauty retailer replenishment cycles.
US Cosmetics Market Competitive Landscape
Top-tier vendors anchor prestige and mass-market tiers simultaneously, while mid-cap specialists occupy clean-beauty and professional salon niches. The vendor base stratifies across multinational conglomerates with diversified personal care portfolios, regional contract manufacturers with FDA-registered infrastructure, and digitally native brands with direct-to-consumer distribution. Dominant competitive moves include M&A for biotechnology ingredient capabilities and exclusive salon channel partnerships with education-dependent loyalty programs.
Within the multinational conglomerate tier, L'Oréal and The Estée Lauder Companies exemplify divergent channel strategies. L'Oréal occupies a position spanning mass-market retail through professional salon exclusives. The Estée Lauder Companies anchors prestige skincare through dermatology clinic dispensing relationships. Procter & Gamble sits within the scale-driven mass-market tier with manufacturing efficiencies that support retail shelf dominance.
| Leading Market Players |
|---|
| L'Oréal |
| The Estée Lauder Companies |
| Procter & Gamble |
| Unilever |
| Coty |
| Shiseido |
| Johnson & Johnson |
| Beiersdorf |
| Kao Corporation |
| Others |
Pricing and Supply Chain Analysis
Squalane commodity price volatility cascades through fermentation-derived active supply chains, compressing margin pools at prestige tiers while forcing mass-market brands toward petroleum-based substitutes. California's Proposition 65 litigation exposure and biopolymer packaging premiums amplify cost divergence between compliant and conventional formulations.
Pricing Analysis
Margin tightening in mass-market haircare reflects biopolymer packaging cost premiums and PFAS reformulation expenses. Three-tier pricing structure across prestige dermatology-dispensed, professional salon-exclusive, and mass retail tiers separates clinical validation documentation from commodity surfactant systems. Cost-down pressure on standard-tier color cosmetics accelerates as Washington and Maine PFAS bans force waterproof mascara reformulations with inferior wear claims. Direct-to-consumer subscription buyers exhibit lowest price sensitivity; mass-market retail shoppers face highest elasticity.
Supply Chain Analysis
Fermentation-derived ceramide supply rests on Bay Area biotechnology firms and New Jersey contract manufacturing corridors. Squalane and recombinant collagen inputs draw from California plant-cell culture facilities and European specialty chemical importers through Port Newark. Single-source vulnerability concentrates in FDA-registered contract manufacturers serving multiple brand portfolios. Distribution runs through Sephora and Ulta wholesale replenishment, dermatology clinic direct dispensing, and algorithmic subscription fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as MoCRA facility registration requirements and toxicology expertise scarcity force mid-tier brands toward acquisition or contract manufacturing dependence.
For Market Incumbents: Deepen dermatology clinic dispensing partnerships in Florida and Texas to anchor prestige skincare loyalty against direct-to-consumer algorithmic curation. Secure captive supply of fermentation-derived actives through backward integration into Bay Area biotechnology partnerships. Control salon-exclusive oxidative dye formulations through state cosmetology board compliance infrastructure. For New Entrants and Emerging Players: Male-specific skincare buyers in the US Southeast and Mountain West remain underserved by gender-positioned brand architectures. Microbiome-friendly certification whitespace in prestige channels offers EWG Verified premium pricing entry. Target medical spa channel expansion in Austin and San Antonio through clinical validation documentation partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap clean-beauty brands with California Proposition 65 compliance infrastructure and existing FDA facility registrations. Long-term viability hinges on regulatory affairs depth rather than formulation novelty alone. Watch FDA adverse event reporting enforcement intensity as inflection signal for compliance-cost barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Backward Integration | Captive fermentation-derived squalane supply insulates against agricultural commodity volatility. |
| Dermatology Clinic Dispensing Partnership | Medical spa channel expansion in Texas and Florida anchors prestige skincare loyalty. |
| Clean-Beauty Certification Investment | EWG Verified and NSF/ANSI 305 standards unlock premium pricing tiers in Sephora. |
| PFAS-Free Formulation Platform | Washington and Maine state bans force waterproof color cosmetics reformulation leadership. |
| Direct-to-Consumer Subscription Launch | Algorithmic curation and loyalty data capture bypass traditional wholesale margin compression. |
Research Methodology
Multi-period observation of FDA facility registration filings, state-level ingredient ban implementations, and professional salon channel expansion anchored the trend analysis, supplemented by interviews with cosmetic chemists, regulatory affairs directors at prestige brands, contract manufacturing operations heads, and Sephora category buyers. Secondary validation drew from FDA MoCRA facility databases, California Proposition 65 enforcement records, customs import data for fermentation-derived actives, and SEC 10-K personal care segment disclosures. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Input-output matrices mapped formulation chemistry costs through channel certification requirements across product type, formulation vehicle, application purpose, and end-user channel dimensions. CAGRs derived from regression analysis of historical prestige and mass-market tier trajectories, adjusted for regulatory compliance cost step-changes. Forecast inputs incorporated PFAS phase-out timelines, biopolymer packaging adoption curves, and medical spa channel penetration rates.
Revisions become necessary when FDA adverse event reporting enforcement intensifies, state patchwork ingredient restrictions diverge further, or biotechnology input costs spike. Forecasts reflect documented assumptions on regulatory stability and channel migration velocity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Organic Personal Care Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Bio-Based Cosmetics Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
Intimate Hygiene Products Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
India Antibacterial Soap Market
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market