
 Hair and Nail Accessories Market | 2026-2036
Hair and Nail Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Hair and Nail Accessories Market Foresight
Digital print-on-demand tooling is fragmenting how hair accessories move from design to shelf, collapsing traditional seasonal forecasting cycles. KISS leverages its mass-market distribution network to sustain shelf presence across drugstore chains. Glamnetic anchors the magnetic lash sub-category through technology leadership in reusable adhesion systems. Dashing Diva differentiates via specialized press-on nail formats that bypass salon dependency.
Hair and nail accessories encompass functional and decorative items manufactured from plastics, metals, ceramics, and synthetic fabrics, with specifications ranging from tensile-strength-tested elastic polymers to hypoallergenic ceramic coatings rated for thermal styling tools. These products serve commercial purposes across personal grooming, professional beauty services, and event-based aesthetics. The material dimension shows plastic dominating unit volumes due to cost scalability, while ceramic commands margin pools in heat-styling tools where thermal conductivity specifications matter. End user segmentation reveals professional salons as the quality-certification gatekeeper segment, whereas retail consumers now drive growth through social-commerce discovery channels.
The FDA oversees cosmetic safety labeling for nail products in the United States, while REACH governs chemical substance restrictions across European formulations, and China's GB standards regulate heavy-metal content in metal-alloy hair accessories. These frameworks collectively shape product development cycles, import documentation requirements, and reformulation costs that manufacturers must embed into pricing models. Stakeholders must monitor how evolving chemical disclosure mandates intersect with influencer-driven ingredient transparency expectations to determine compliance investment priorities.
Market Dynamics
Professional salons now function as quality-certification gatekeepers, filtering which ceramic heat-styling tools and reusable lash systems reach retail consumers through their procurement standards and training protocols.
Growth Catalysts
- REACH compliance cycles:European chemical disclosure mandates force nail polish manufacturers into accelerated reformulation pipelines. This regulatory pressure creates competitive moats for laboratories with in-house toxicology capabilities.
- Ceramic thermal conductivity specifications:Professional salons demand heat-styling tools rated for precise temperature control. This specification pull concentrates margin pools in coated-barrel manufacturing.
- Social-commerce discovery channels:Direct-to-consumer brands bypass traditional retail gatekeepers through algorithmic content distribution. Platform-native purchasing infrastructure compresses the path from product demonstration to transaction.
Market Restraints
- Petrochemical input volatility:Acrylates and polymer feedstocks for synthetic lash fibers and nail coatings track crude oil indices. Formulators absorb margin compression or pass through pricing that dampens retail volume elasticity.
- Supply concentration in East Asian molding capacity:Plastic hair accessory production clusters in Guangdong and Zhejiang provinces. Geopolitical friction or shipping corridor disruption threatens just-in-time replenishment for Western seasonal cycles.
- Biodegradability performance gaps:Cellulose-based alternatives to conventional plastics fail tensile-strength benchmarks for claw clips and elastic polymers. Performance compromises limit substitution velocity in functional accessories.
Strategic Opportunities
- Underpenetrated professional salon networks in India:Organized salon chains in Mumbai and Bangalore represent nascent demand for premium ceramic tool certification. Early entrants capture training-protocol influence before category standardization.
- Convergence of magnetic adhesion with AR try-on:Virtual fitting technology reduces return rates for reusable lash systems. Technology bundling creates subscription attach opportunities for consumable adhesives.
- EU Green Deal chemical substitution incentives:Biobased solvent formulations for nail polish removal qualify for green procurement preferences in institutional beauty service contracts. Regulatory tailwind accelerates R&D amortization.
Industry Challenges
- Certification timeline compression:FDA cosmetic safety labeling and REACH substance restriction updates arrive on overlapping cycles. Compliance teams face parallel documentation demands with divergent evidentiary standards.
- Legacy ERP integration with direct-to-consumer fulfillment:Wholesale-oriented manufacturers retrofit inventory systems for unit-level traceability. Implementation friction delays channel diversification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hair and Nail Accessories Market |
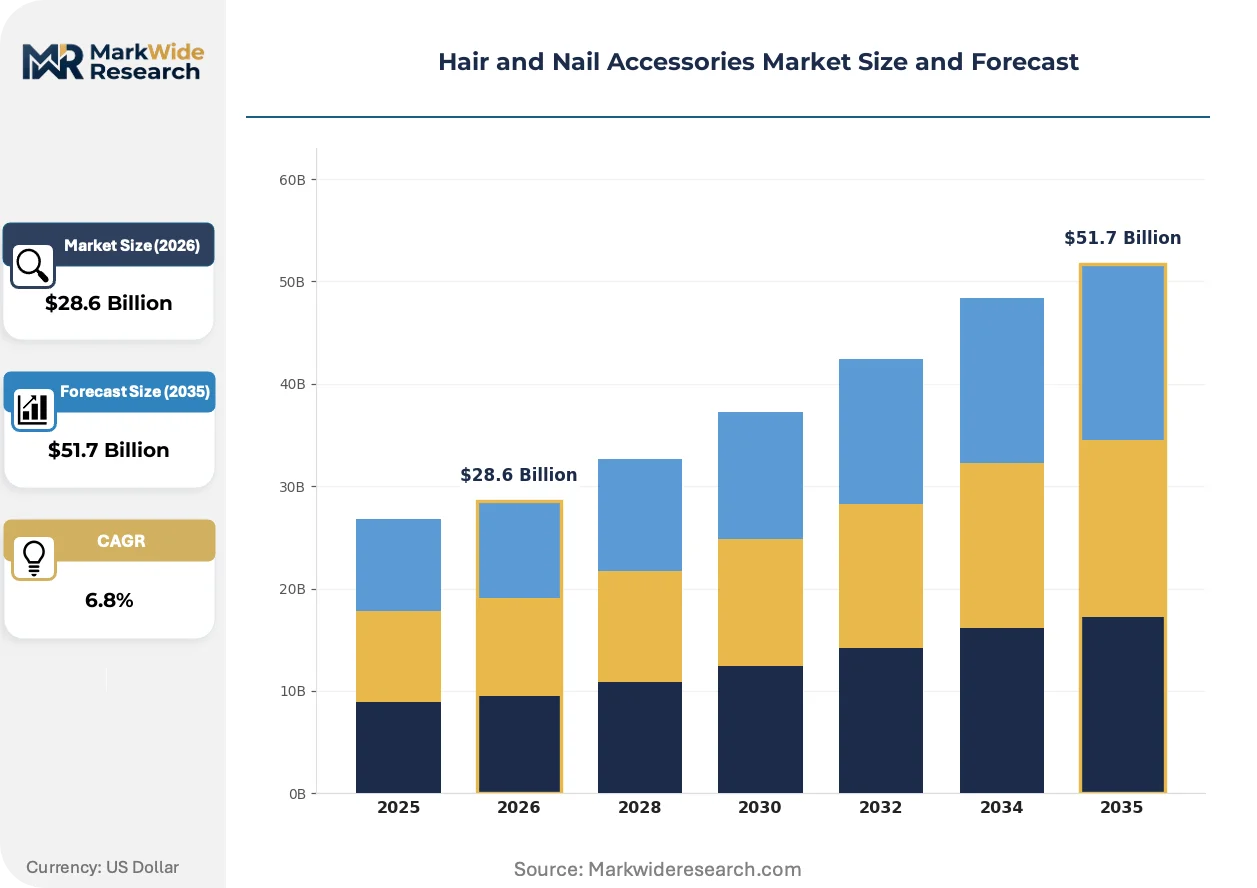
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hair Clips, Hair Ties, Nail Polish, Nail Files Material: Plastic, Metal, Ceramic, Fabric End User: Professional Salons, Retail Consumers, Beauty Schools, Event Planners Retail Channel: Online Stores, Specialty Shops, Department Stores, Drugstores |
| Companies Covered | Vickkybeauty, Dashing Diva, Junyi Beauty, Impress, KISS, Pollux Enterprise, Ecorivta, Glamnetic, Urrykid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hair and Nail Accessories Market Shifts & Advancements
Digital fabrication workflows are fragmenting how accessories move from design to shelf, compressing traditional seasonal forecasting cycles and enabling micro-batch responsiveness to platform-native demand signals.
Ceramic coating deposition technology is collapsing the barrier between professional-grade heat conductivity and mass-market price points. Independent stylists and salon chains adopt these tools at replacement-cycle velocity previously reserved for premium equipment. The compression of performance-tier pricing is forcing legacy manufacturers to recertify supply relationships or surrender margin.
REACH substance restriction expansions now cover microplastic additives in glitter formulations and certain photoinitiators in gel nail systems. European formulators face forced ingredient substitution with twelve-to-eighteen-month validation windows. Nail polish manufacturers serving the EU market are consolidating reformulation investments to amortize compliance costs across larger SKU portfolios.
Salon procurement departments now unbundle after-sales service from equipment purchases, treating ceramic tool maintenance as a separate vendor category. This purchasing pattern shift fragments supplier relationships and compresses contract values for bundled service offerings. The unbundling is most visible in United States metropolitan markets where salon chain consolidation creates centralized procurement leverage.
Hair and Nail Accessories Market Segmentation
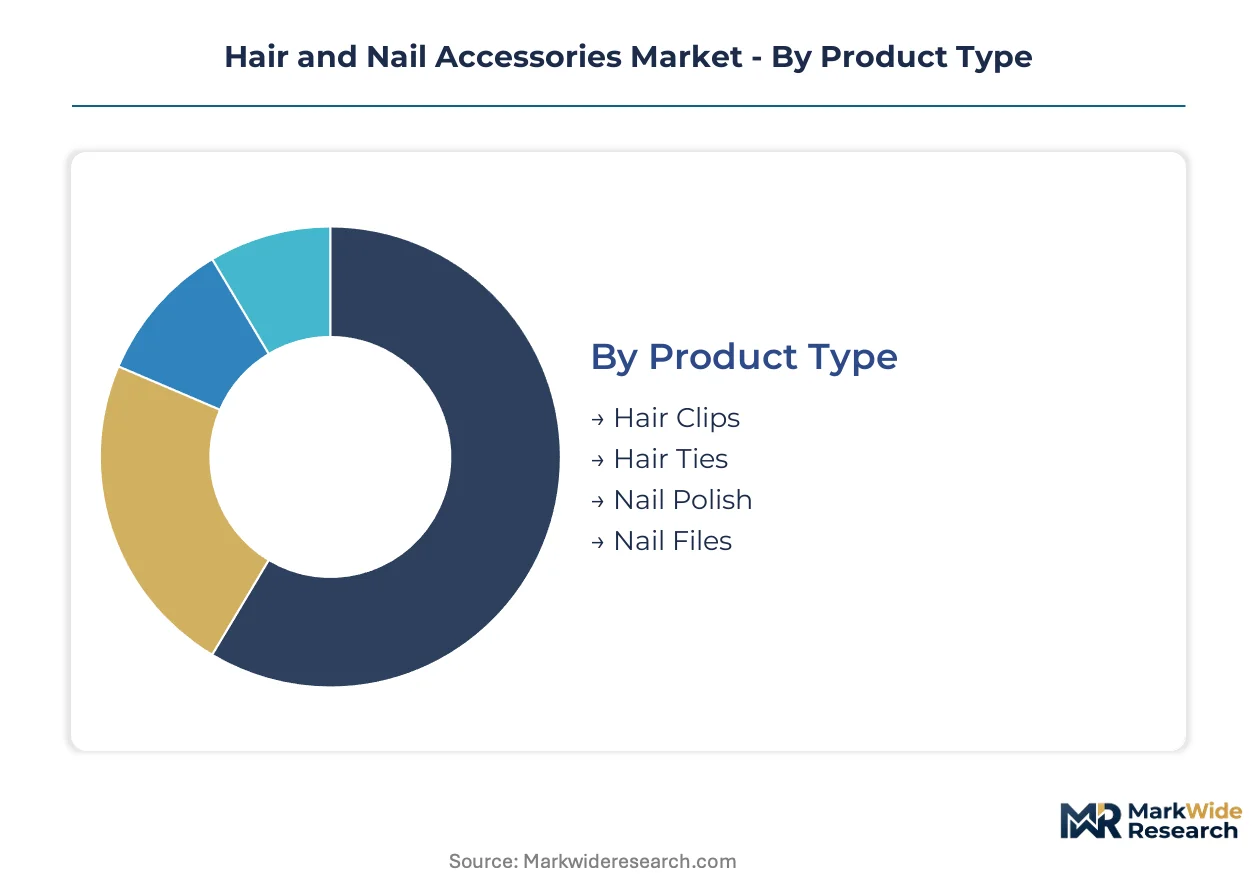
Segmentation in hair and nail accessories reveals divergent margin structures and inventory velocity patterns. Product type determines replacement frequency, while material selection locks in supply chain exposure and regulatory compliance burden.
Product Type:
Hair clips and nail polish operate on opposite ends of the consumption cycle spectrum. Clips and ties turn over through loss-driven repurchase, whereas polish and files deplete through planned consumption.
- Hair Clips:Injection-molded acrylonitrile butadiene styrene and cellulose acetate form the bulk of unit production. Demand concentrates in United States drugstore chains where seasonal colorways drive impulse placement at checkout proximity.
- Hair Ties:Elastic polymers undergo tensile-strength testing to 15-pound pull ratings for salon-grade certification. Professional stylists in Mumbai and Bangalore specify these ratings for heat-tool compatibility, creating a quality-tier price spread against mass-market variants.
- Nail Polish:Solvent-based lacquers face REACH-mandated reformulation cycles for photoinitiator and microplastic additive restrictions.
- Nail Files:Emery boards and glass-crystal abrasives span disposable to multi-year lifespans.
Hair clips dominate installed base. Nail polish is where expansion concentrates.
Material:
Material selection maps directly to thermal performance requirements and chemical disclosure obligations. Ceramic commands certification premiums, while plastic scales through Guangdong molding capacity.
- Plastic:Polypropylene and ABS dominate unit economics through high-cavity injection tooling. Zhejiang province clusters supply 70-plus percent of Western seasonal replenishment, concentrating geopolitical risk in single-corridor shipping lanes.
- Metal:Nickel-free alloys satisfy EU nickel release directives for prolonged skin contact. German salon chains specify these grades for claw clips and barrettes, filtering supply through centralized procurement protocols.
- Ceramic:Aluminum oxide coatings rated to 450°F thermal conductivity specifications separate professional from consumer-grade heat tools.
- Fabric:Silk and satin scrunchies target friction-reduction claims for sleep-wear applications.
Plastic dominates installed base. Ceramic is where margin expansion concentrates.
End User:
End user segmentation splits between quality-certification gatekeepers and volume-driven discovery channels. Salons validate specifications that later diffuse to retail consumers.
- Professional Salons:Organized chains in United States metropolitan markets unbundle equipment purchases from maintenance contracts. Centralized procurement departments negotiate ceramic tool specifications separately from consumable adhesives.
- Retail Consumers:Algorithmic content distribution on platform-native commerce drives discovery. Direct-to-consumer brands bypass traditional retail gatekeepers through demonstration-to-transaction compression.
- Beauty Schools:Training-kit standardization creates bulk purchase agreements with predictable replacement cycles.
- Event Planners:Wedding and editorial stylists demand single-use disposability for hygiene protocols.
Professional salons dominate specification authority. Retail consumers are where volume expansion concentrates.
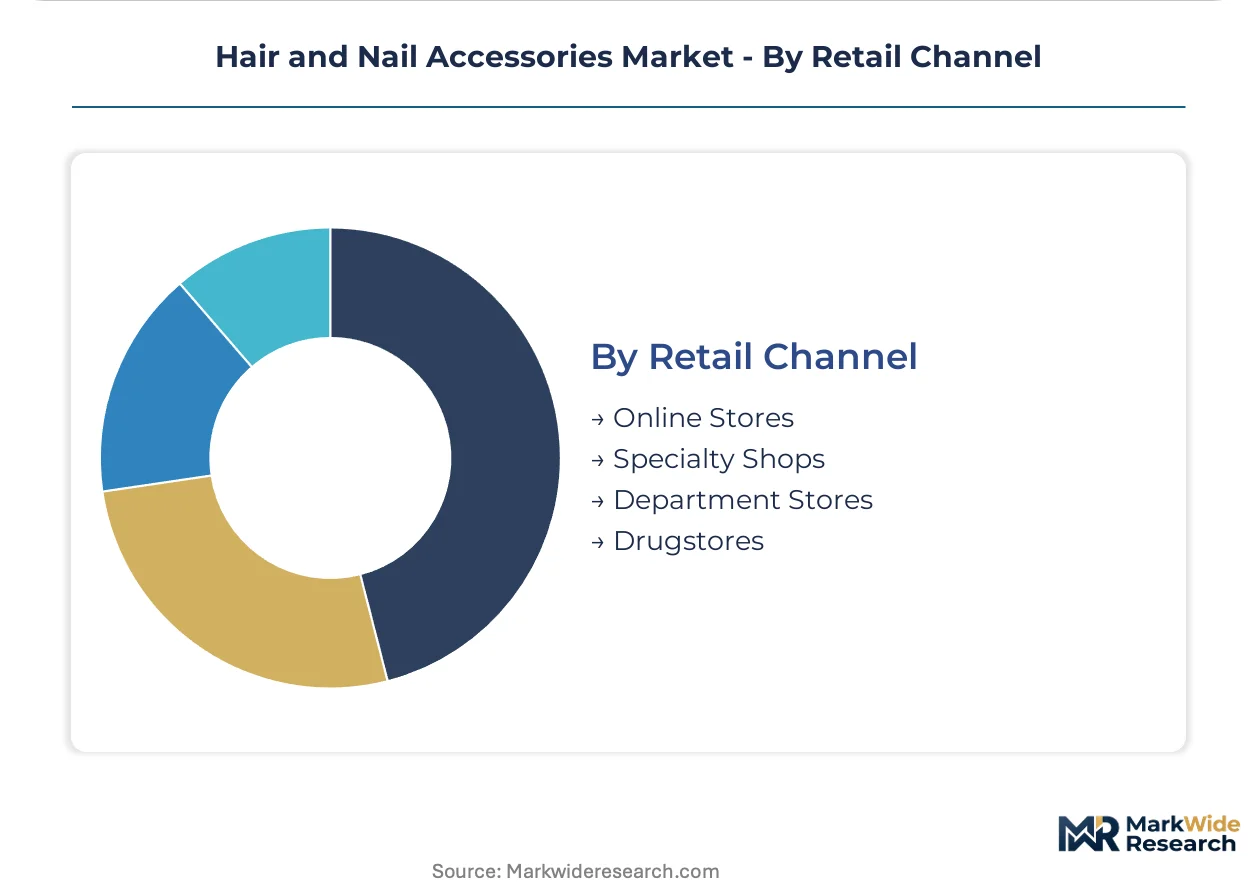
Retail Channel:
Channel structure determines margin capture and inventory risk allocation. Online infrastructure shifts working capital burden from retailer to brand.
- Online Stores:Direct-to-consumer fulfillment requires unit-level traceability retrofitting from wholesale-oriented ERP systems. Implementation friction delays channel diversification for legacy manufacturers.
- Specialty Shops:Curated assortments in Sephora and Ulta Beauty locations anchor premium ceramic tool placement. Staff training protocols influence consumer specification adoption.
- Department Stores:Seasonal buy commitments with return privileges concentrate inventory risk on suppliers.
- Drugstores:KISS and mass-market brands sustain shelf presence through high-velocity replenishment and promotional calendar alignment.
Drugstores dominate unit volume throughput. Online stores are where customer acquisition expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional salons in the United States anchor premium ceramic tool procurement, while direct-to-consumer brands compress purchase cycles through platform-native discovery. Regulatory divergence between FDA cosmetic labeling and REACH chemical restrictions fragments formulation strategies across Atlantic markets. Manufacturing gravity concentrates in East Asian molding clusters that feed Western seasonal replenishment.
United States
Specialty beauty retailers in Sephora and Ulta Beauty locations anchor premium ceramic tool placement through staff training protocols. FDA cosmetic safety labeling mandates shape nail product import documentation and reformulation timelines. Los Angeles and New York metropolitan areas concentrate salon chain consolidation that centralizes procurement leverage for heat-styling equipment specifications.
Germany
Organized salon chains in Berlin and Munich unbundle equipment purchases from maintenance contracts, fragmenting supplier relationships. REACH substance restrictions on microplastic additives and photoinitiators force twelve-to-eighteen-month nail polish reformulation cycles. The Rhine-Ruhr industrial corridor hosts toxicology laboratories that build competitive moats through in-house compliance capabilities.
China
Guangdong and Zhejiang province clusters supply seventy-plus percent of Western plastic hair accessory seasonal replenishment. GB standards regulate heavy-metal content in metal-alloy accessories, shaping export documentation requirements. Shenzhen manufacturers retrofit wholesale-oriented ERP systems for direct-to-consumer unit-level traceability, facing implementation friction that delays channel diversification.
India
Organized salon chains in Mumbai and Bangalore represent nascent demand for premium ceramic tool certification and training-protocol influence. BIS quality standards filter import specifications for heat-styling equipment entering professional channels. The Maharashtra-Gujarat industrial belt concentrates injection-molding capacity that serves domestic mass-market hair clip demand through drugstore distribution.
United Kingdom
London-based direct-to-consumer brands leverage algorithmic content distribution to bypass traditional retail gatekeepers. ECHA chemical disclosure mandates intersect with influencer-driven ingredient transparency expectations, determining compliance investment priorities. The Midlands manufacturing region hosts specialty polymer compounders serving tensile-strength-tested elastic polymer specifications for salon-grade hair ties.
Hair and Nail Accessories Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. Mass-market distribution networks sustain shelf presence through high-velocity replenishment and promotional calendar alignment, while technology-led specialists capture margin pools in reusable adhesion and ceramic thermal conductivity. Three archetypes dominate: scale-driven mass-market suppliers, technology-specialist premium players, and platform-native direct-to-consumer brands. Competitive moves concentrate on M&A for distribution footprint expansion and strategic partnerships for regulatory compliance capabilities.
Among technology-specialist players, Glamnetic anchors the magnetic lash sub-category through reusable adhesion system leadership, while Dashing Diva occupies a position exemplifying press-on nail format specialization that bypasses salon dependency. KISS represents the scale-driven mass-market archetype with sustained drugstore chain presence. These three companies illustrate how competitive positioning fragments between premium technology credentials and high-velocity volume throughput.
| Leading Market Players |
|---|
| Vickkybeauty |
| Dashing Diva |
| Junyi Beauty |
| Impress |
| KISS |
| Pollux Enterprise |
| Ecorivta |
| Glamnetic |
| Urrykid |
| Others |
Supply & Pricing Matrix
The Shanghai-Los Angeles maritime corridor anchors freight cost dynamics for plastic hair accessory replenishment, concentrating supply-side pricing power in Guangdong molding clusters while forcing downstream differentiation between mass-market drugstore tiers and premium ceramic tool certification grades.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate acrylate and polymer feedstock procurement, embedding petrochemical volatility directly into nail coating and synthetic lash fiber pricing. Three-tier pricing structure across premium, standard, and economy levels separates salon-grade ceramic tools with 450°F thermal conductivity ratings from mass-market variants lacking certification documentation. Price erosion runs through the plastic clip segment as Zhejiang capacity expansion outpaces Western seasonal demand absorption. Professional salon chains exhibit lowest price sensitivity due to unbundled equipment procurement protocols, while drugstore retail consumers drive volume through promotional calendar responsiveness.
Supply Chain Analysis
Contract manufacturers in Guangdong and Zhejiang provinces hold seventy-plus percent of Western plastic hair accessory molding capacity, with Shenzhen-based CMs retrofitting wholesale-oriented ERP systems for direct-to-consumer traceability. Raw material dependencies center on polypropylene resin, ABS pellets, and aluminum oxide ceramic coating precursors sourced from domestic Chinese petrochemical complexes and Australian bauxite refinement. Single-source vulnerability concentrates in the Yangtze River Delta shipping corridor where geopolitical friction threatens just-in-time replenishment cycles. Distribution runs through drugstore chain centralized procurement for mass-market volume, specialty beauty retailers for premium placement, and platform-native fulfillment for direct-to-consumer discovery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated salon chain procurement departments in United States metropolitan markets, fragmenting supplier relationships as centralized specifications unbundle equipment from maintenance contracts.
For Market Incumbents: Insulate margin pools in ceramic thermal conductivity certification by deepening toxicology laboratory capabilities for REACH-compliant reformulation cycles. Counter platform-native brand erosion through exclusive staff training protocols at Sephora and Ulta Beauty locations that lock in specification influence before consumer adoption diffuses. For New Entrants and Emerging Players: Pursue underpenetrated organized salon networks in Mumbai and Bangalore where premium ceramic tool certification standards remain nascent and training-protocol influence is contestable. Capture early-mover advantage through demonstration partnerships with beauty schools that create predictable replacement cycle visibility before category standardization solidifies. For Investors and Strategic Acquirers: Technology-specialist premium players with reusable adhesion IP or ceramic coating deposition capabilities offer acquisition exposure to margin expansion segments where performance-tier pricing compression creates consolidation pressure. Long-term viability hinges on regulatory compliance amortization across larger SKU portfolios rather than single-product differentiation. Watch REACH substance restriction expansion timelines as inflection signals for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Launch | Algorithmic content distribution on platform-native commerce compresses demonstration-to-transaction paths for magnetic lash systems. |
| Premium Tier Introduction | Ceramic coating deposition technology collapses professional-grade heat conductivity barriers into mass-market price accessibility. |
| Backward Integration | In-house toxicology capabilities for REACH compliance build competitive moats against reformulation cycle acceleration. |
| Distribution Channel Expansion | Specialty beauty retailer staff training protocols anchor consumer specification adoption for heat-styling equipment. |
| Sustainability Repositioning | EU Green Deal chemical substitution incentives qualify biobased solvent formulations for institutional green procurement preferences. |
Research Methodology
The analysis maps ceramic heat-styling tools, reusable magnetic lash systems, press-on nail formats, and injection-molded plastic accessories, each validated through interviews with salon chain procurement directors, professional stylist trainers, direct-to-consumer brand operations leads, and toxicology laboratory compliance officers. Secondary sources include FDA cosmetic safety labeling filings, ECHA REACH substance restriction updates, Chinese GB standards documentation, and customs records for Guangdong-Zhejiang export volumes. Bottom-up SKU-level demand modeling triangulates against top-down sector aggregation.
Assumptions held fixed include current REACH substance restriction scope and existing FDA cosmetic labeling timelines, while petrochemical input volatility and shipping corridor disruption probability were varied across sensitivity scenarios. Segmentation dimensions modeled span product type, material grade, end user archetype, and retail channel structure across the projection horizon. CAGRs derive from replacement cycle velocity analysis for consumables versus durable goods, with ceramic tool adoption curves and social-commerce penetration rates as category-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil indices, container freight rates, or yuan-dollar exchange volatility would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and platform algorithm changes. Quarterly review of REACH amendment proposals, salon chain M&A activity, and Guangdong province energy policy is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Skin Care Luxury Cosmetic Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
Beard Oil Market
Beauty & Personal Care
Intimate Wash Care Products Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
United States Bath Soap Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
Male Grooming Products Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market