
 Herbal Haircare Products Market | 2026-2036
Herbal Haircare Products Market Size, Share, and Industry Trends Forecast 2026-2036
Herbal Haircare Products Market Foresight
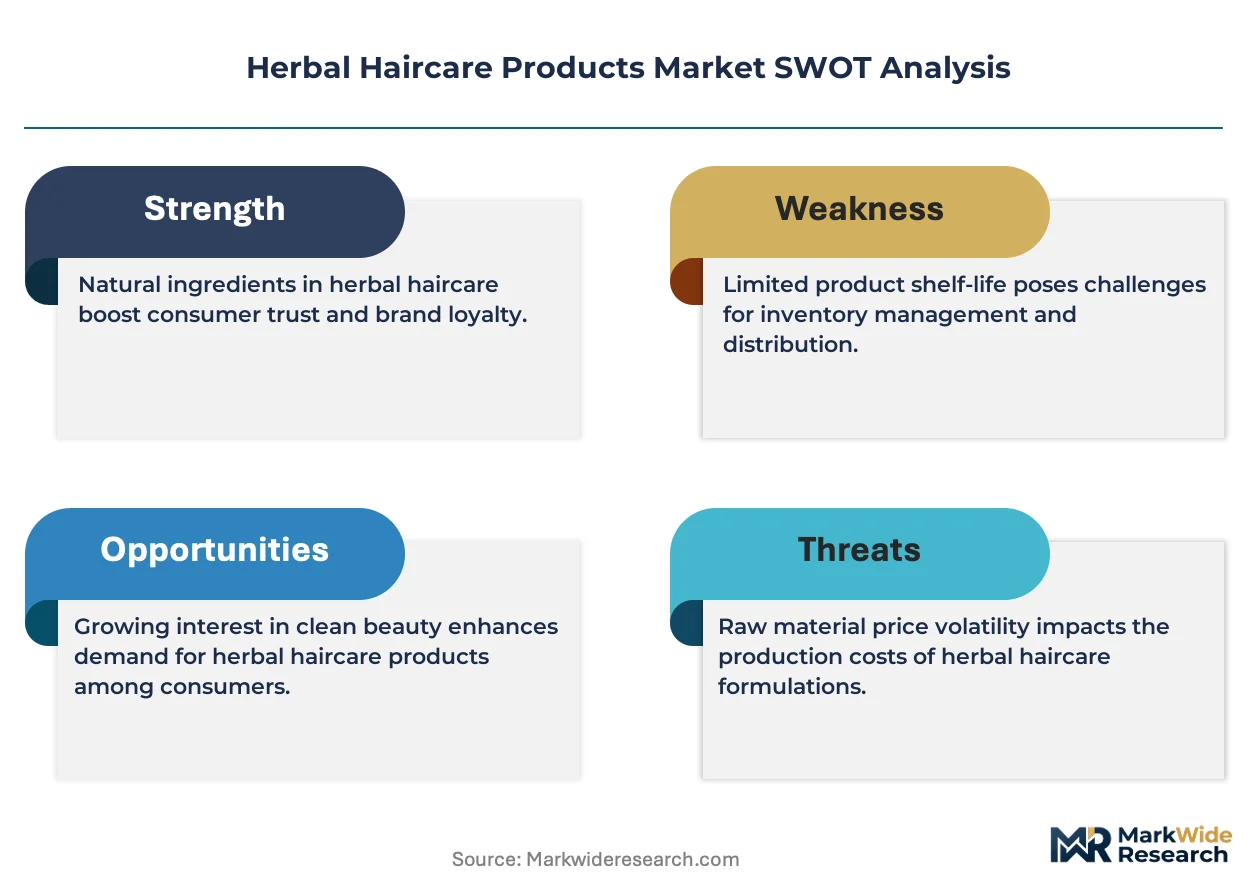
Specialty store distribution is tilting toward digital-first discovery as consumers research ingredient provenance before purchase. Dabur Limited leverages its Ayurvedic heritage to sustain shelf dominance in traditional trade formats across South Asia. The Himalaya Wellness Company anchors its position through pharmacy channel partnerships that emphasize clinical validation of botanical extracts. Aveda Corporation differentiates through salon-exclusive positioning that commands premium pricing in professional haircare channels.
Herbal haircare products comprise formulations derived from plant-based actives such as bhringraj, amla, henna, and argan oil, typically processed through cold-press extraction or aqueous infusion to preserve bioactive compounds, and function primarily to cleanse, condition, or treat hair without synthetic chemical intervention. Shampoo remains the volume leader due to habitual purchase frequency, though hair oil retains outsized margin contribution in South Asian markets where weekly oiling rituals persist. Organic formulation standards are tightening fastest as certification bodies raise bar thresholds for synthetic adjuvant content, squeezing mid-tier natural claims that lack third-party verification.
FDA cosmetic labeling requirements and REACH substance restrictions collectively elevate compliance costs for cross-border formulation standardization. India's BIS and CDSCO frameworks impose additional ayurvedic-specific quality benchmarks that export-oriented manufacturers must satisfy for domestic market access. Stakeholders should monitor evolving certification harmonization between Ayurvedic pharmacopeia standards and international organic cosmetics protocols to anticipate which ingredient sourcing investments will yield durable competitive protection.
Market Dynamics
Millennial and Gen Z consumers are pulling formulation science toward traceable botanical sourcing, forcing manufacturers to rebuild supply chains around cold-press extraction and aqueous infusion methods that preserve bioactive integrity rather than cost-optimized solvent processing.
Growth Catalysts
- REACH substance restrictions:European chemical disclosure mandates are accelerating ingredient transparency investments, pushing brands to document full supply chain provenance and capture premium positioning in pharmacy channels.
- Professional salon channel expansion:Plant-based actives formulated for stylist-grade performance are displacing conventional chemical treatments in premium service menus across urban India and Southeast Asia.
- Ayurvedic pharmacopeia standardization:India's BIS and CDSCO frameworks are creating exportable quality benchmarks that heritage brands leverage for cross-border market entry.
Market Restraints
- Raw material concentration risk:Bhringraj and amla sourcing clusters in Madhya Pradesh and Rajasthan face climate volatility that compresses harvest yields and destabilizes contract pricing.
- Cold-press extraction capex barriers:Small-batch mechanical pressing equipment requires 40-60% higher capital deployment than solvent-based alternatives, excluding regional formulators from organic certification tiers.
- Synthetic adjuvant substitution threat:Low-cost surfactant blends from petrochemical feedstocks undercut botanical emulsifiers on unit economics in mass-market shampoo segments.
Strategic Opportunities
- Sub-Saharan Africa underpenetration:Weekly hair oiling rituals in Nigeria and Kenya mirror South Asian consumption patterns, creating white space for Ayurvedic heritage brands with established tropical botanical expertise.
- EU Green Deal regulatory tailwind:Biobased content mandates in personal care are redirecting R&D budgets toward fully renewable formulation platforms that qualify for green public procurement preferences.
- Direct-to-consumer subscription channel:Digital-first discovery platforms enable personalized regimen curation based on scalp microbiome diagnostics, bypassing traditional retail margin structures.
Industry Challenges
- Phytochemistry talent scarcity:Formulation chemists with dual expertise in traditional Ayurvedic texts and modern analytical validation are concentrated in Kerala and Karnataka, constraining R&D scaling for northern manufacturers.
- Multi-certification timeline compression:Simultaneous pursuit of USDA Organic, COSMOS, and India Organic marks extends product development cycles by 14-18 months, delaying revenue recognition.
- Legacy ERP integration friction:Batch-level traceability requirements for botanical provenance conflict with installed manufacturing execution systems designed for synthetic chemical inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Herbal Haircare Products Market |
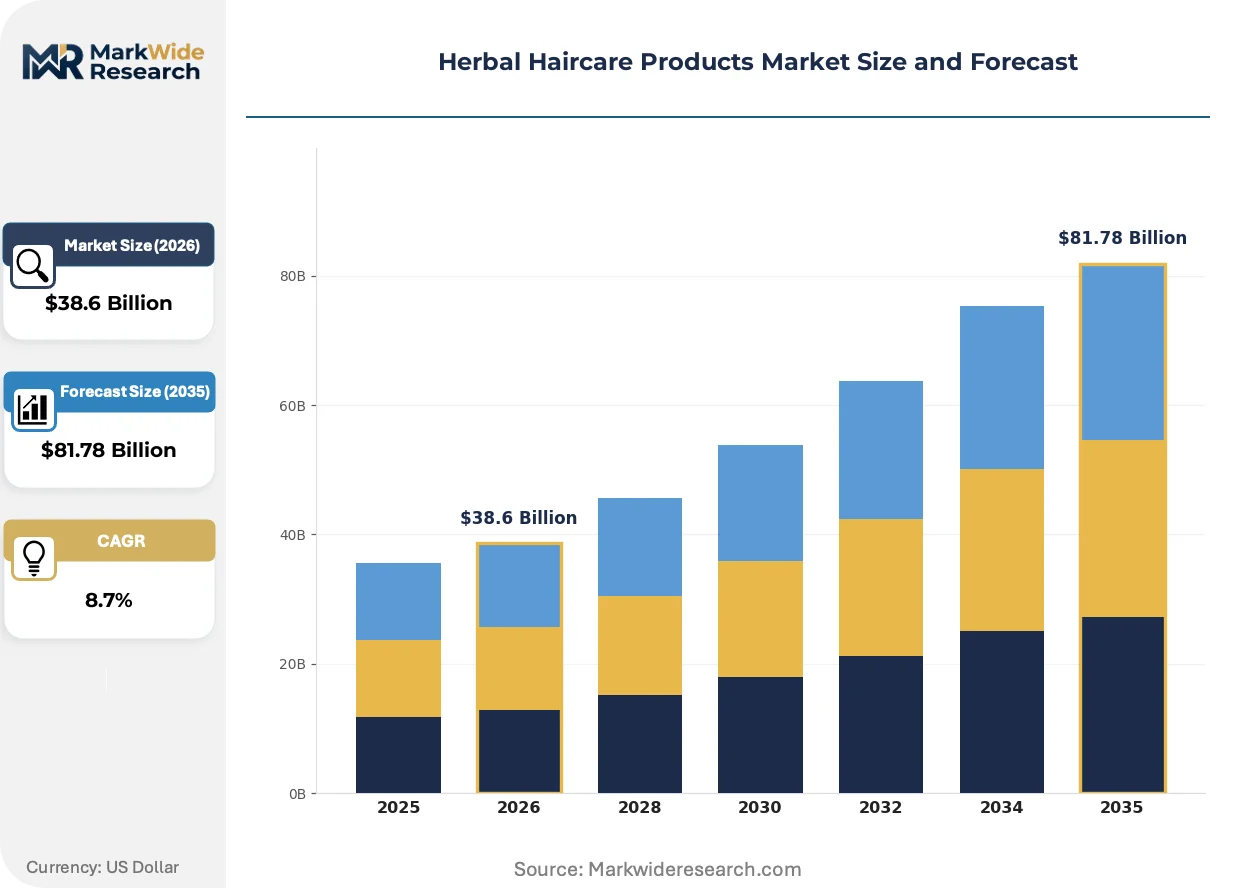
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $81.78 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Conditioner, Hair Oil, Hair Mask Formulation: Organic, Natural, Paraben-Free, Sulfate-Free End User: Women, Men, Children, Salons Distribution Channel: Online, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Dabur Limited, The Himalaya Wellness Company, Cavinkare Pvt. Ltd., Procter & Gamble Company, Aveda Corporation, Biotique, Lotus Herbals, Patanjali Ayurved Ltd., Amway Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Herbal Haircare Products Market Shifts & Advancements
Formulation science is converging with digital traceability infrastructure, creating new competitive axes around verified bioactive potency rather than marketing claims alone.
Supercritical CO2 extraction technology is hybridizing with traditional aqueous infusion methods to capture heat-sensitive terpenes from argan and henna matrices. Premium salon brands in Mumbai and Bangalore are adopting these hybrid systems to deliver standardized active concentrations that command service-menu premiums. The technology is compressing quality variance between artisanal small-batch and industrial-scale production, eroding the historical trade-off between authenticity and consistency.
FDA cosmetic labeling rules are tightening ingredient disclosure granularity, requiring quantitative enumeration of botanical extracts rather than aggregate "fragrance" or "natural flavor" designations. This policy shift is elevating compliance costs for cross-border formulation standardization, particularly for brands sourcing identical actives from multiple origin countries. Professional channel distributors in the United States are responding by consolidating supplier relationships to reduce documentation burden.
Ingredient provenance research is displacing impulse purchase behavior in specialty retail, with consumers scanning QR-linked batch records before committing to cart. Digital discovery platforms are capturing this behavioral shift through algorithmic matching of scalp condition profiles to specific harvest-lot chemistry. Urban middle-class households in Delhi and Hyderabad exhibit the highest engagement intensity with traceability infrastructure.
Herbal Haircare Products Market Segmentation
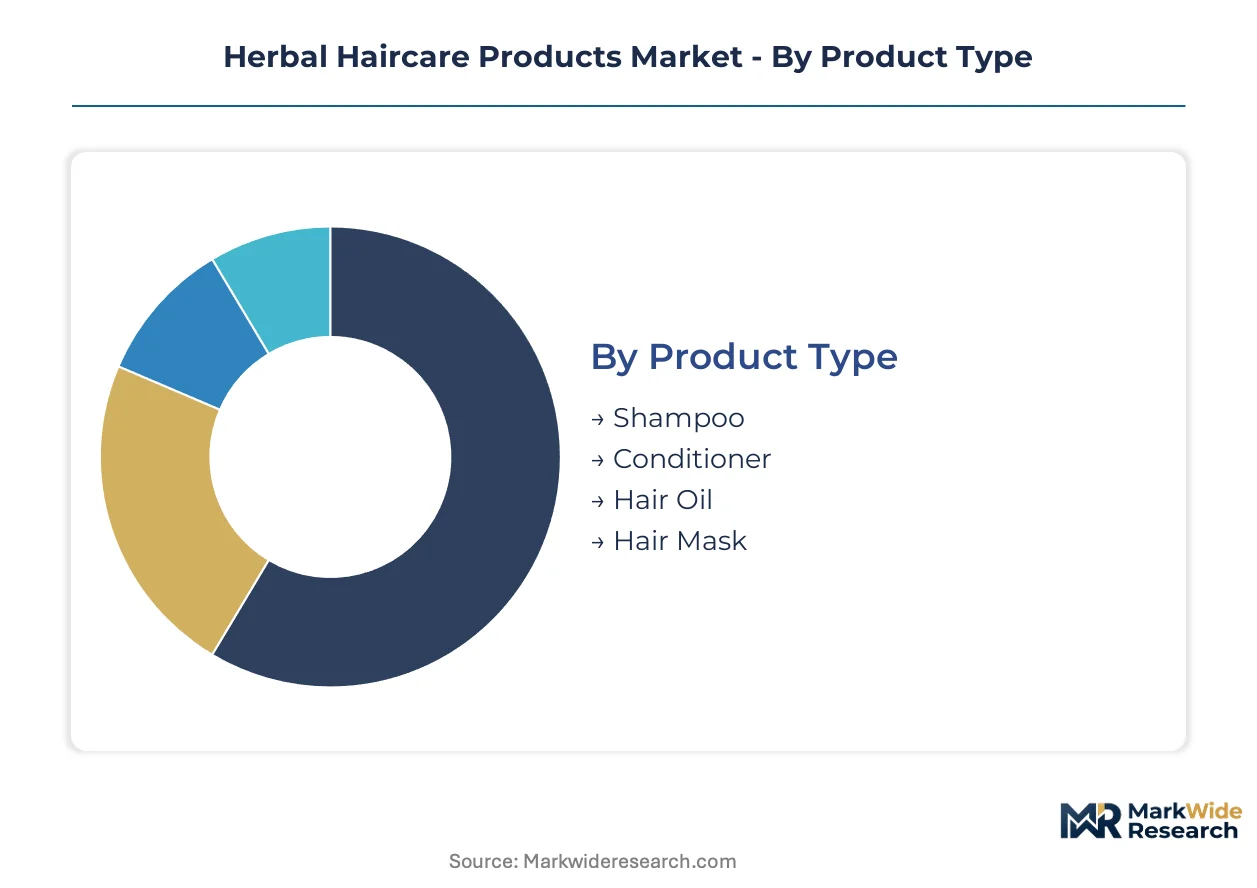
Herbal haircare segmentation reveals how formulation standards, channel economics, and ritual-based consumption patterns fragment addressable demand. Distinct margin structures attach to each category, with certification tiers and distribution format determining viable price positioning.
Product Type:
Volume concentration across product formats reflects purchase frequency and ritual embedding in daily grooming routines.
- Shampoo:Cold-press and aqueous infusion formulations dominate this segment, with habitual weekly replenishment driving volume. Urban Indian households and Southeast Asian salon channels concentrate demand as consumers shift from synthetic surfactant bases to plant-derived cleansers that preserve scalp microbiome balance.
- Hair Oil:Weekly oiling rituals in South Asian markets sustain premium margin structures despite lower purchase frequency. Madhya Pradesh and Rajasthan sourcing clusters supply bhringraj and amla actives that heritage brands process through traditional infusion methods for export positioning.
- Conditioner:Salon-grade botanical conditioners incorporate argan and henna matrices processed through hybrid supercritical CO2 systems for standardized terpene retention.
- Hair Mask:Treatment-grade masks target professional service menus in Mumbai and Bangalore with concentrated botanical actives requiring extended application protocols.
Shampoo holds installed capacity. Hair oil is rotating up the share rankings.
Formulation:
Certification thresholds determine which manufacturers can access pharmacy and premium salon channels versus mass-market retail.
- Organic:USDA Organic, COSMOS, and India Organic marks require synthetic adjuvant content below strict thresholds, compressing mid-tier natural claims. Cold-press extraction equipment demands 40-60% higher capital deployment than solvent alternatives, excluding regional formulators from this tier.
- Natural:Broader formulation latitude permits limited synthetic preservation while maintaining plant-derived active dominance. Mass-market shampoo segments in India and Nigeria concentrate demand where unit economics undercut pure organic positioning.
- Paraben-Free:Preservative system reformulation around phenoxyethanol or sodium benzoate alternatives addresses EU REACH substance restrictions and FDA disclosure tightening.
- Sulfate-Free:Botanical surfactant replacements—cocamidopropyl betaine, decyl glucoside—serve consumers with sensitive scalp profiles in pharmacy channels.
Organic claims command shelf positioning. Natural formulations are climbing the fastest on volume contribution.
End User:
Customer archetypes segment by purchase decision autonomy, ritual participation, and professional service integration.
- Women:Primary household purchasers across all distribution channels, with urban middle-class segments in Delhi and Hyderabad exhibiting highest engagement with QR-linked batch traceability infrastructure.
- Men:Grooming routine simplification favors multi-functional shampoo-conditioner hybrids with visible botanical branding.
- Children:Mild formulation requirements drive tear-free, low-foam specifications with reduced essential oil concentrations.
- Salons:Stylist-grade performance standards require standardized active concentrations that hybrid extraction systems deliver for service-menu premium capture in professional channels.
Women anchor household purchasing. Salon channels are expanding most quickly as professional service integration deepens.
Distribution Channel:
Channel economics determine margin capture, certification documentation burden, and consumer education intensity.
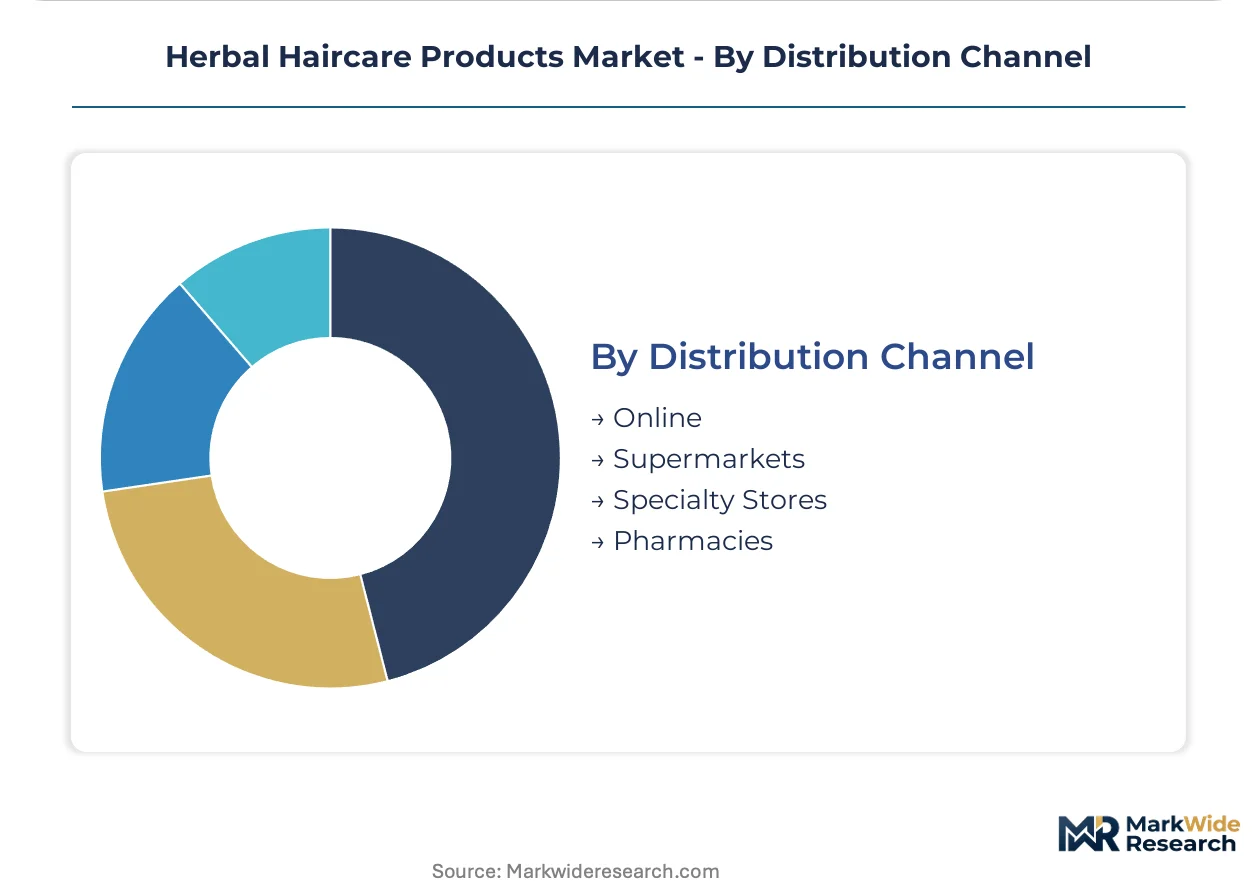
- Online:Digital-first discovery platforms enable personalized regimen curation through scalp microbiome diagnostics, bypassing traditional retail margin structures. Subscription models concentrate in urban Indian and Kenyan markets.
- Supermarkets:Mass-market shampoo and conditioner volume flows through modern trade formats where heritage Ayurvedic brands compete on shelf visibility with synthetic alternatives.
- Specialty Stores:Ingredient provenance research displaces impulse purchase behavior as consumers scan QR-linked batch records before committing to cart.
- Pharmacies:Clinical validation requirements favor Himalaya Wellness Company partnerships and CDSCO-compliant documentation for botanical extract efficacy claims.
Supermarkets maintain volume throughput. Online channels are gaining share fastest on customer acquisition efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali port complex underwrites the UAE's position as a re-export gateway for Ayurvedic formulations entering African and Middle Eastern markets. Container throughput at Mumbai's Jawaharlal Nehru Port Trust anchors India's outbound shipments of cold-pressed hair oils to Southeast Asian pharmacy channels.
United States
Millennial consumers in California and New York drive pharmacy channel demand for sulfate-free botanical shampoos with QR-linked ingredient provenance. FDA cosmetic labeling rules now require quantitative disclosure of botanical extracts rather than aggregate designations. Brooklyn-based formulation labs are piloting scalp microbiome diagnostic platforms that match consumer profiles to specific harvest-lot chemistry.
India
Weekly oiling rituals among urban middle-class households in Delhi and Hyderabad sustain premium margin structures for heritage Ayurvedic brands. BIS and CDSCO frameworks impose ayurvedic-specific quality benchmarks that export-oriented manufacturers must satisfy for domestic market access. Madhya Pradesh and Rajasthan sourcing clusters supply bhringraj and amla actives processed through traditional infusion methods for cross-border positioning.
Germany
REACH substance restrictions accelerate ingredient transparency investments as brands document full supply chain provenance for pharmacy channel placement. ECHA disclosure mandates push manufacturers toward cold-press extraction methods that preserve bioactive integrity. Hamburg-based distributors are consolidating supplier relationships to reduce documentation burden under tightening EU Green Deal biobased content requirements.
Brazil
ANVISA regulatory alignment with international organic cosmetics protocols creates entry pathways for Ayurvedic heritage brands targeting weekly hair oiling rituals in São Paulo and Rio de Janeiro. Tropical botanical expertise from Indian suppliers matches local argan and henna sourcing patterns. Port of Santos infrastructure supports re-export positioning into Mercosur markets with shared cosmetic registration standards.
Nigeria
Weekly hair oiling consumption patterns in Lagos and Abuja mirror South Asian ritual behaviors, creating white space for heritage brands with established tropical botanical expertise. The country's national pharmaceutical regulator is harmonizing import documentation with COSMOS certification benchmarks. Kano-based distribution networks are expanding pharmacy channel penetration for clinically validated botanical extracts.
Herbal Haircare Products Market Competitive Landscape
On the supply side, the industry is consolidating around heritage Ayurvedic specialists, multinational consumer goods platforms, and salon-exclusive premium positioning. Cold-press extraction equipment demands 40-60% higher capital deployment than solvent alternatives, excluding regional formulators from organic certification tiers. Three strategic archetypes dominate: legacy pharmacopeia brands leveraging BIS compliance for cross-border entry, mass-market synthetic incumbents reformulating around botanical surfactant replacements, and professional channel specialists commanding service-menu premiums through standardized active concentrations. Dominant competitive moves include backward integration into Madhya Pradesh and Rajasthan sourcing clusters, plus strategic partnerships with pharmacy distributors for CDSCO-compliant documentation.
Among heritage Ayurvedic specialists, Dabur Limited and The Himalaya Wellness Company exemplify the archetype of pharmacopeia-rooted brands leveraging domestic regulatory compliance for export positioning. Aveda Corporation occupies a distinct tier within salon-exclusive channels where stylist-grade performance standards command premium pricing. These three entities represent the competitive spectrum from traditional trade dominance through clinical validation partnerships to professional service integration.
| Leading Market Players |
|---|
| Dabur Limited |
| The Himalaya Wellness Company |
| Cavinkare Pvt. Ltd. |
| Procter & Gamble Company |
| Aveda Corporation |
| Biotique |
| Lotus Herbals |
| Patanjali Ayurved Ltd. |
| Amway Corporation |
| Others |
Supply & Pricing Matrix
Climate volatility in Madhya Pradesh and Rajasthan sourcing clusters compresses bhringraj and amla harvest yields, forcing contract pricing instability that widens spreads between artisanal small-batch and industrial-scale tiers while reshaping procurement toward backward integration.
Pricing Analysis
Volume-discount tiering separates salon-exclusive professional channels from mass-market retail, with certification grade and cold-press extraction capital intensity driving premium-mid-economy pricing differentiation. Organic formulation tiers command service-menu premiums in Mumbai and Bangalore professional channels, while natural formulations face price erosion in Indian supermarket segments due to synthetic surfactant substitution. Pharmacy channel buyers in Delhi and Hyderabad exhibit lowest price sensitivity, prioritizing QR-linked batch traceability over unit economics.
Supply Chain Analysis
REACH substance restrictions and FDA cosmetic labeling rules limit cross-border formulation standardization, concentrating upstream supply in India, Morocco, and Argentina for argan and henna matrices. Cold-press extraction equipment and supercritical CO2 hybrid systems draw from petrochemical feedstock alternatives for botanical emulsifiers. Single-source vulnerability clusters around Rajasthan bhringraj monsoons. Distribution runs through Jebel Ali re-export gateways and Mumbai port complexes into Southeast Asian pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Herbal haircare operates as a regulatory-entrenchment defensive moat, where BIS and CDSCO compliance investments create switching costs that lock out unqualified entrants from premium channel access.
For Market Incumbents: Harden supply chain resilience through backward integration into Madhya Pradesh and Rajasthan sourcing clusters, capturing climate-hedged raw material positions against harvest volatility. Deepen pharmacy channel control via CDSCO-compliant documentation partnerships that emerging players cannot replicate without 14-18 month certification timelines. For New Entrants and Emerging Players: Build out direct-to-consumer subscription platforms in Nigerian and Kenyan markets, where weekly hair oiling rituals mirror South Asian consumption patterns but heritage Ayurvedic brands lack established presence. Prioritize scalp microbiome diagnostic personalization as the go-to-market wedge, bypassing retail margin structures entirely. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors heritage pharmacopeia brands with export-ready regulatory dossiers. Long-term viability centers on acquisition targets possessing BIS-compliant quality benchmarks and established cold-press extraction infrastructure. Watch COSMOS-EU Green Deal harmonization progress as the inflection signal for biobased content mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sourcing Clusters | Madhya Pradesh and Rajasthan captive supply secures climate-hedged bhringraj and amla positions against harvest volatility. |
| Pharmacy Channel Partnership Expansion | CDSCO-compliant documentation unlocks clinical validation positioning in Delhi and Hyderabad urban middle-class households. |
| Direct-to-Consumer Subscription Launch | Scalp microbiome diagnostics enable personalized regimen curation, bypassing traditional retail margin compression in Indian supermarkets. |
| Hybrid Extraction Technology Adoption | Supercritical CO2-aqueous infusion systems standardize terpene retention for Mumbai and Bangalore salon service-menu premiums. |
| Multi-Certification Investment Program | USDA Organic, COSMOS, and India Organic marks defend shelf positioning as synthetic adjuvant thresholds tighten. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with Ayurvedic formulation chemists, pharmacy channel distributors, salon service directors, and heritage brand supply chain managers; and secondary validation through BIS regulatory filings, CDSCO quality benchmarks, customs export records from Jawaharlal Nehru Port Trust, and ECHA REACH substance restriction databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs spanned product type segmentation by shampoo, hair oil, conditioner, and hair mask; formulation tiers across organic, natural, paraben-free, and sulfate-free; end-user archetypes including women, men, children, and salon professionals; and distribution channels from online platforms through supermarkets, specialty stores, and pharmacies. CAGRs derived from regression analysis against cold-press extraction capacity expansion, professional salon channel penetration rates, and QR-linked traceability infrastructure adoption curves.
Stress conditions across monsoon harvest variability, REACH substance restriction expansion scope, and FDA labeling disclosure granularity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions around certification harmonization timelines and professional channel expansion trajectories. Material shifts in EU Green Deal biobased content mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Face Makeup Market
Beauty & Personal Care
Skincare Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
India Antibacterial Soap Market
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Dry Shampoo Market