
 Stretch Mark Removal Products Market | 2026-2036
Stretch Mark Removal Products Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Mark Removal Products Market Analytics
The price-performance gap between clinic-administered laser systems and over-the-counter topical formulations is hardening as consumers sort into distinct value tiers. Clarins Group leverages its prestige retail footprint to sustain premium positioning across European department stores. Cynosure anchors the professional device segment through installed-base relationships with dermatology practices. Union-Swiss Ltd competes in the masstige bracket with specialized cocoa butter formulations distributed through pharmacy chains.
Stretch mark removal products encompass topical preparations and energy-based devices designed to improve the appearance of dermal striae through collagen remodeling, epidermal hydration, or fractional ablation. Creams and oils typically incorporate centella asiatica, hyaluronic acid, or retinoid compounds to enhance dermal elasticity and reduce erythema in early-stage striae. The creams segment leads absolute volume due to low unit cost and broad retail availability, while the treatments category captures disproportionate value through professional service bundling. Natural and herbal formulations are gaining shelf space in specialty stores as clean-label preferences reshape pharmacy assortment decisions.
FDA device classification rules constrain marketing claims for at-home laser and micro-needling systems, channeling clinical-grade demand toward supervised settings. The EU MDR and REACH frameworks govern ingredient safety disclosures and dermal sensitization testing for topical products sold across European member states. Stakeholders must monitor evolving classification boundaries between cosmetic and medical devices as regulators reassess energy-based home-use technologies.
Market Dynamics
The professional-clinic channel is capturing margin from at-home device manufacturers as FDA enforcement actions narrow permissible marketing claims for unsupervised energy-based systems. This regulatory compression redirects consumer spend toward supervised fractional laser and radiofrequency protocols administered in dermatology settings.
Growth Catalysts
- Postpartum care expansion:Specialized clinics across the United States are adding striae-specific treatment protocols to maternal recovery service menus, creating institutional demand for professional-grade resurfacing equipment.
- REACH compliance differentiation:European formulators investing in dermal sensitization documentation are securing preferred shelf placement in pharmacy chains as clean-label scrutiny intensifies.
- Fractional laser protocol refinement:Shorter recovery windows from non-ablative 1540nm systems are converting trial users into repeat clinic visitors for maintenance sessions.
Market Restraints
- Shea butter price volatility:West African supply disruptions are compressing margins for natural-formulation specialists dependent on cocoa butter and shea derivatives as primary emollients.
- Device classification uncertainty:FDA 510(k) pathway ambiguity for home-use microneedling pens is freezing R&D budgets at consumer electronics manufacturers.
- Topical efficacy ceiling:Dermatological consensus limits marketing claims for over-the-counter retinoid and centella asiatica preparations to hydration and texture improvement rather than structural repair.
Strategic Opportunities
- Men's grooming channel penetration:Specialty retailers in Germany are expanding male-focused skin texture correction assortments beyond traditional female-targeted merchandising.
- Telemedicine prescription integration:Brazilian dermatology platforms are bundling tretinoin formulations with virtual consultation follow-ups for post-surgical striae management.
- EU MDR certification leverage:Device manufacturers obtaining Class IIa designation for radiofrequency systems are accessing reimbursement-adjacent positioning in French aesthetic medicine networks.
Industry Challenges
- Clinical technician certification bottlenecks:Laser safety training program capacity constraints in the United Kingdom are limiting clinic expansion velocity for fractional resurfacing services.
- Legacy ERP integration friction:European pharmacy distributors are struggling to synchronize batch-level traceability data with existing inventory management infrastructure under evolving REACH documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Mark Removal Products Market |
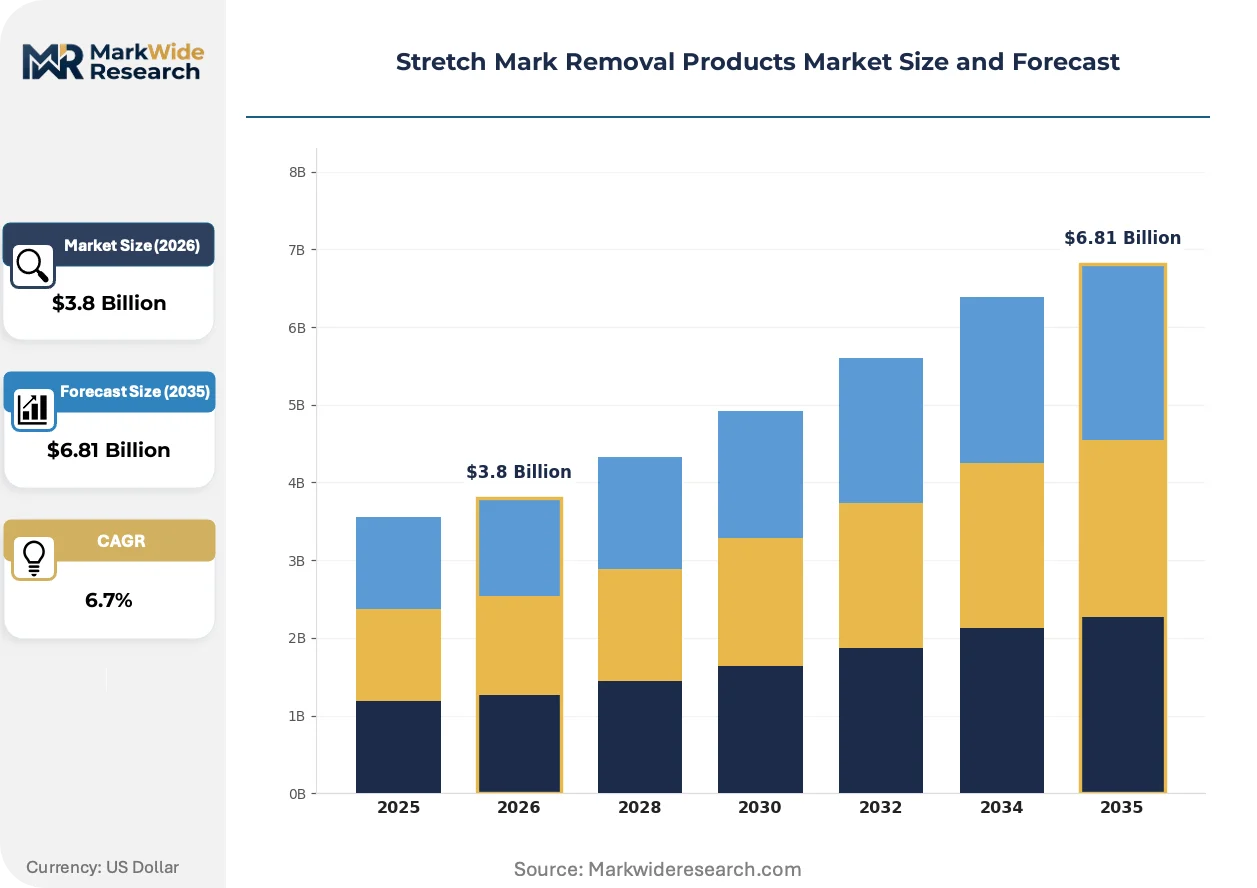
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Oils, Gels, Treatments Formulation: Organic, Chemical, Natural, Herbal Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores Target Audience: Pregnant Women, Athletes, Bodybuilders, General Consumers |
| Companies Covered | Union-Swiss Ltd, Weleda, Clarins Group, Cynosure, Laboratoires Expanscience, Merz Pharma, Basq Skincare, Vichy Laboratories, E.T. Browne Drug, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Mark Removal Products Market Evolving Landscape
Algorithmic treatment planning is compressing consultation-to-procedure timelines in professional settings while reshaping consumer expectations for personalized at-home regimens. These shifts are redrawing competitive boundaries between device manufacturers, formulation houses, and service providers.
AI-powered skin imaging is automating striae severity assessment and treatment parameter selection in high-volume dermatology practices. Clinics in South Korea are deploying convolutional neural networks to predict individual collagen response patterns before laser session scheduling. This capability is automating the customization previously requiring extended physician consultation time, compressing per-patient labor allocation by half.
EU MDR technical documentation requirements are forcing device manufacturers to consolidate quality management systems across multiple product lines. Smaller energy-based system producers are exiting the European market rather than absorbing notified body audit costs. Professional-grade radiofrequency manufacturers with existing ISO 13485 infrastructure are capturing abandoned market share through accelerated CE marking timelines.
Subscription-based topical replenishment is displacing traditional retail purchasing for maintenance-phase consumers. Direct-to-consumer platforms in the United States are bundling hyaluronic acid serums with automated reorder algorithms triggered by usage telemetry. Postpartum demographic cohorts exhibit highest conversion rates to this model, prioritizing convenience over pharmacy browsing.
Stretch Mark Removal Products Market Segmentation
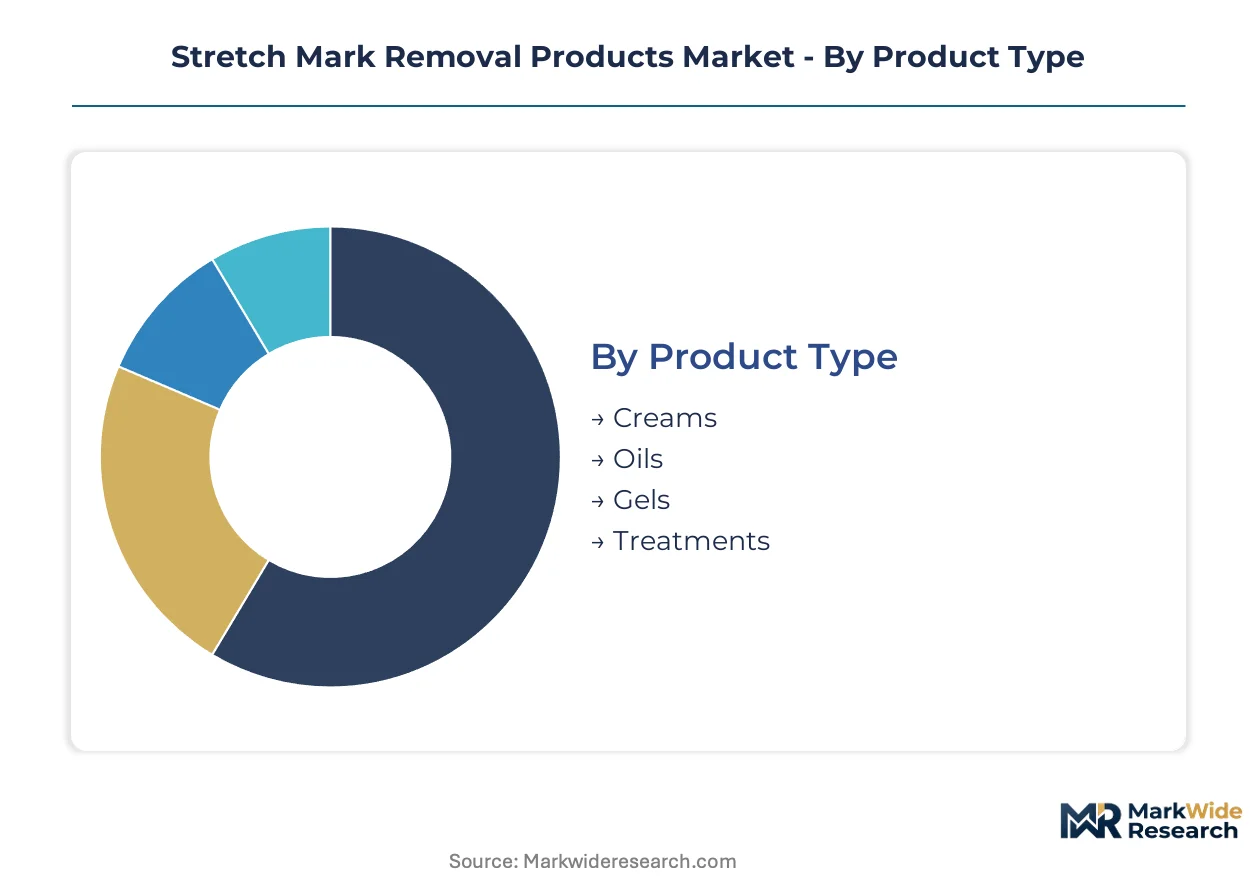
Stretch mark removal products serve divergent consumer needs across prevention, early intervention, and established striae remodeling. Segmentation reveals how formulation chemistry, channel access, and user physiology determine purchasing patterns and margin structures.
Product Type:
Standalone topical formats dominate at-home regimens, while embedded professional protocols integrate multiple modalities into supervised treatment courses.
- Creams:Emulsion-based vehicles incorporating centella asiatica or retinoid compounds for epidermal hydration and early-stage erythema reduction. Postpartum consumers in the United States drive repeat purchases through pharmacy and online channels, constrained by dermatological consensus limiting structural repair claims to hydration benefits.
- Treatments:Energy-based systems and microneedling protocols administered in clinical settings for dermal collagen remodeling. Brazilian dermatology networks anchor demand for fractional laser and radiofrequency platforms, with FDA device classification rules channeling clinical-grade spend toward supervised settings.
- Oils:Lipid-rich formulations emphasizing scar tissue pliability and massage-mediated absorption. Shea butter supply volatility from West African sources compresses margins for natural-formulation specialists.
- Gels:Hydrogel and silicone-based preparations targeting hypertrophic striae texture modification. Athletes recovering from rapid muscle mass fluctuations represent a concentrated user cohort.
Creams lead volumes today; Treatments is gaining share fastest.
Formulation:
Cost tier stratification separates premium-positioned clean-label offerings from mass-market synthetic alternatives, with certification documentation becoming a shelf-placement determinant.
- Natural:Centella asiatica and hyaluronic acid formulations meeting EU REACH dermal sensitization documentation requirements. European pharmacy chains prioritize these SKUs as clean-label scrutiny intensifies.
- Herbal:Botanical extracts including gotu kola and onion extract preparations. Specialty stores in Germany expand male-focused skin texture correction assortments beyond traditional female-targeted merchandising.
- Organic:Certified-emollient systems dependent on cocoa butter and shea derivatives. West African supply disruptions constrain availability for price-sensitive segments.
- Chemical:Synthetic retinoid and peptide compounds requiring prescription pathways in regulated markets. Brazilian telemedicine platforms bundle tretinoin with virtual consultation follow-ups.
Natural formulations lead volumes today; Herbal is climbing the fastest.
Distribution Channel:
Channel selection reflects purchase urgency, with subscription models displacing traditional retail for maintenance-phase consumers seeking replenishment automation.
- Online Retail:Direct-to-consumer platforms deploying usage-telemetry algorithms for automated reorder triggering. United States postpartum demographics exhibit highest conversion to subscription-based topical replenishment.
- Pharmacies:Brick-and-mortar networks struggling to synchronize batch-level traceability data with legacy ERP infrastructure under evolving REACH documentation requirements.
- Specialty Stores:Curated assortments emphasizing clean-label credentials and ingredient transparency. Natural and herbal formulations gain shelf space as assortment decisions reshape.
- Supermarkets:Mass-market cocoa butter and basic emollient offerings competing on unit economics. Union-Swiss Ltd distributes through this channel in pharmacy-chain-adjacent retail formats.
Pharmacies lead volumes today; Online Retail shows steepest expansion trajectory.
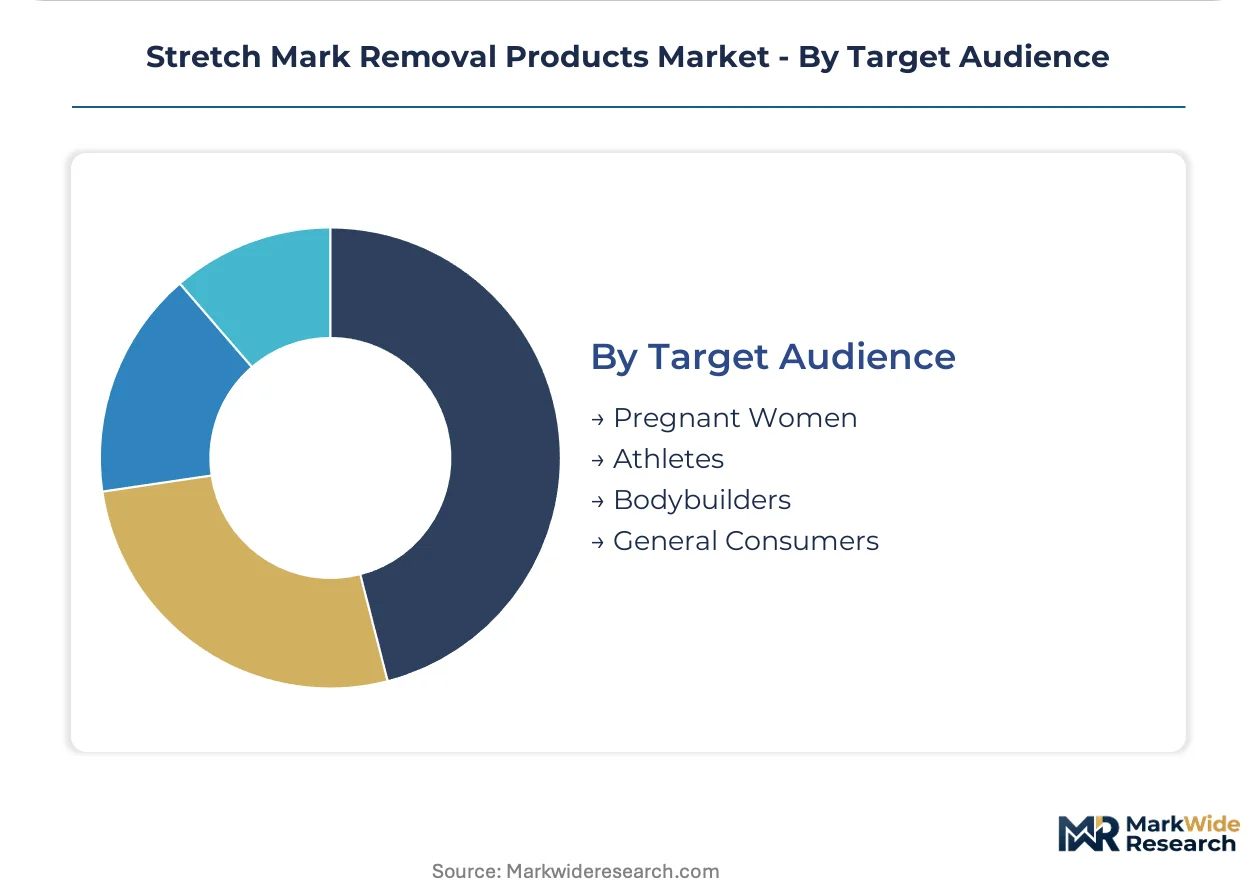
Target Audience:
Physiological stress patterns determine striae formation mechanisms, with pregnancy-related dermal stretching representing the largest addressable population.
- Pregnant Women:Prevention-focused consumers prioritizing third-trimester and postpartum intervention. United States postpartum care clinics are expanding striae-specific treatment protocols to maternal recovery service menus.
- Bodybuilders:Rapid muscle hypertrophy creating thigh and shoulder striae requiring texture correction. Male grooming channel penetration expands beyond traditional female-targeted merchandising in German specialty retail.
- Athletes:Adolescent growth spurts and weight-class fluctuations generating breast and hip striae. Convenience prioritization drives subscription model adoption.
- General Consumers:Adolescent growth-related striae and weight fluctuation patterns. OTC efficacy ceilings limit marketing claims to hydration and texture improvement.
Pregnant Women lead volumes today; Bodybuilders is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dermatology-trained practitioners concentrate in metropolitan corridors across the United States, Germany, Brazil, South Korea, and the United Kingdom, anchoring professional service availability and shaping regional demand patterns for clinic-administered stretch mark protocols.
United States
Postpartum care clinics in Los Angeles and New York are expanding striae-specific treatment menus to maternal recovery services. FDA oversight of cosmetic device claims tightens marketing parameters for at-home energy-based systems. Specialized dermatology networks in Miami and Dallas are converting fractional laser protocols into standardized service bundles.
Germany
Specialty retailers in Berlin and Munich are expanding male-focused skin texture correction assortments beyond traditional female-targeted merchandising. EU REACH dermal sensitization documentation requirements govern ingredient safety disclosures for topical formulations. Clean-label formulators in Hamburg are securing preferred pharmacy shelf placement through compliance differentiation.
Brazil
Dermatology service networks in São Paulo and Rio de Janeiro concentrate demand for professional-grade fractional laser and radiofrequency platforms. ANVISA, the country's national pharmaceutical regulator, supervises prescription pathways for tretinoin formulations. Telemedicine platforms in Belo Horizonte are bundling virtual consultation follow-ups with post-surgical striae management protocols.
South Korea
High-volume dermatology practices in Seoul are deploying AI-powered skin imaging to automate striae severity assessment and treatment parameter selection. The MFDS regulates medical device classification for energy-based systems entering the aesthetic medicine channel. Clinics in Gangnam are compressing consultation-to-procedure timelines through algorithmic treatment planning.
United Kingdom
Laser safety training program capacity constraints in London and Manchester are limiting clinic expansion velocity for fractional resurfacing services. The MHRA oversees evolving classification boundaries between cosmetic and medical devices for home-use technologies. Quality management consolidation among notified body-audited manufacturers in Birmingham is capturing abandoned market share from smaller producers exiting under EU MDR technical documentation requirements.
Stretch Mark Removal Products Market Competitive Landscape
Top-tier vendors anchor the professional device and prestige retail segments, while masstige and mass-market specialists populate lower tiers with pharmacy-chain and direct-to-consumer distribution. The vendor base stratifies across three functional layers: energy-based system manufacturers with installed-base relationships, prestige skincare houses leveraging department store footprints, and natural-formulation specialists dependent on commodity emollient supply chains. Consolidation pressure concentrates among radiofrequency device producers absorbing CE marking timelines, while portfolio diversification drives topical houses toward subscription-based replenishment models.
Within the prestige retail archetype, Clarins Group exemplifies European department store positioning through specialized maternal skincare lines. Cynosure occupies a position among professional device manufacturers with dermatology practice relationships. Union-Swiss Ltd represents the masstige bracket with pharmacy-chain distribution formats. These three anchors illustrate how channel access and formulation chemistry determine margin capture across divergent consumer value tiers.
| Leading Market Players |
|---|
| Union-Swiss Ltd |
| Weleda |
| Clarins Group |
| Cynosure |
| Laboratoires Expanscience |
| Merz Pharma |
| Basq Skincare |
| Vichy Laboratories |
| E.T. Browne Drug |
| Others |
Value Network & Pricing Analysis
Shea butter spot prices from West African cooperatives cascade through three downstream pricing tiers as formulators absorb commodity volatility into margin structures. Clinic-administered fractional laser protocols command bundled service premiums while pharmacy-chain topicals compete on unit economics, with supply concentration in Ghana and Burkina Faso determining input cost trajectories for natural-formulation specialists.
Pricing Analysis
Bundled professional service packages separate from unbundled retail product purchases across the stretch mark removal market. Three-tier pricing structure across premium clinic protocols, masstige pharmacy formulations, and economy mass-market emollients reflects certification grade and channel control differentiation. Pricing pressure stems from FDA device classification tightening that redirects consumer spend toward supervised settings with higher per-session costs. Postpartum consumers in subscription-based replenishment models exhibit lowest price sensitivity, while supermarket shoppers purchasing basic cocoa butter preparations represent the most elastic demand segment.
Supply Chain Analysis
Dual-sourcing requirements for shea butter and cocoa butter derivatives mandate multi-supplier qualification across Ghana, Burkina Faso, and Côte d'Ivoire for European REACH-compliant formulators. Professional device manufacturers draw from German laser component suppliers, South Korean RF module producers, and Chinese electronic assembly operations. Single-source vulnerability concentrates in West African shea nut harvesting cooperatives exposed to climate disruption and export logistics chokepoints. Distribution runs through pharmacy chain consolidation in Europe, dermatology service networks in Brazil, and direct-to-consumer platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in subscription-based replenishment models and professional service bundling as cost compression in digital customer acquisition meets premium-tier consumer willingness to pay for convenience.
For Market Incumbents: Anchor installed-base relationships with dermatology practices through fractional laser maintenance contracts and technician certification programs. Deepen backward integration into shea butter cooperative partnerships to defend input cost positions against West African supply volatility. Prioritize EU MDR Class IIa certification investment for radiofrequency systems to capture abandoned market share from smaller producers exiting under notified body audit requirements. For New Entrants and Emerging Players: Direct-to-consumer telemedicine platforms offer the most penetrable route for tretinoin prescription bundling with virtual consultation follow-ups in Brazilian and United States markets. Target male grooming channel white space in German specialty retail where skin texture correction assortments remain underdeveloped beyond female-targeted merchandising. Pursue clean-label certification differentiation as the primary go-to-market angle for natural formulation launches in European pharmacy chains. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR technical documentation requirements exceed smaller device manufacturer quality management capabilities. Long-term viability favors professional-grade radiofrequency and laser system producers with existing ISO 13485 infrastructure and accelerated CE marking timelines. Acquisition target archetypes include notified body-audited manufacturers capturing abandoned European market share and subscription-platform operators with postpartum demographic concentration. Watch AI-powered skin imaging adoption rates in South Korean dermatology practices as the signal for algorithmic treatment planning inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class IIa Certification Pathway | Device manufacturers accessing French aesthetic medicine networks gain reimbursement-adjacent positioning. |
| Subscription-Based Replenishment Launch | Direct-to-consumer platforms with usage-telemetry algorithms capture highest postpartum demographic conversion rates. |
| Telemedicine Prescription Integration | Brazilian dermatology platforms bundling tretinoin with virtual follow-ups expand post-surgical striae management access. |
| Backward Integration into Shea Cooperatives | Natural-formulation specialists securing Ghana and Burkina Faso supply relationships defend margin against commodity volatility. |
| AI-Powered Skin Imaging Deployment | Seoul dermatology practices automating striae severity assessment compress consultation-to-procedure timelines by half. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade data reconciliation, and stakeholder interviews — were reconciled to construct market estimates for stretch mark removal products. Primary interviews with dermatology clinic operators, pharmacy chain category managers, device manufacturer regulatory affairs leads, and formulation house R&D directors were cross-validated against secondary sources including FDA 510(k) filings, EU MDR notified body registration databases, and REACH dermal sensitization documentation. Customs records from West African shea butter export authorities and Brazilian ANVISA prescription pathway disclosures provided bottom-up volume anchors, while top-down triangulation against dermatology service network expansion data verified market sizing.
Data-stream reconciliation across product type, formulation chemistry, distribution channel, and target audience segmentation dimensions supported analytical framework construction throughout the projection horizon. CAGRs were derived from fitted growth curves against historical volume trajectories and regulatory event impacts. Forecast inputs incorporated professional device installed-base expansion rates, subscription platform customer acquisition cost trends, and shea butter commodity price elasticity assumptions for natural-formulation margin modeling.
FDA enforcement action timing, West African supply disruption severity, and EU MDR audit backlog duration are the dominant revision risks to modeled outcomes. Deviation in FDA device classification boundary determinations for home-use microneedling systems would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Face Oil Market
Beauty & Personal Care
US Skincare Market
Beauty & Personal Care
Aftershave Market
Beauty & Personal Care
North America Beauty and Personal Care Products Market
Beauty & Personal Care
Argentina Beauty and Personal Care Products Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
Women Intimate Care Products Market