
 Personal Care Products Market | 2026-2036
Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care Products Market Outlook
Clean-label and dermatologist-tested tier upgrades is rotating the competitive axis toward ingredient transparency and clinical validation. L'Oréal S.A. leverages its dermatological science heritage to anchor premium positioning across European and Asian markets. Procter & Gamble Company sustains mass-market dominance through manufacturing scale and shelf-space control in North American retail. Shiseido Co., Ltd. differentiates via biotech-driven skin research and precision formulations targeting East Asian skin biology.
Personal care products encompass chemically formulated or naturally derived substances applied to skin, hair, teeth, or facial features, typically containing active concentrations between 0.5% and 15% depending on therapeutic or cosmetic intent, manufactured through emulsification, fermentation, or extraction processes for hygiene, appearance enhancement, or dermatological maintenance. Skin Care commands the largest absolute revenue pool as anti-aging serums and barrier-repair moisturizers attract repeat purchases at premium price points, while E-commerce distribution is expanding fastest as algorithmic personalization and subscription models reduce customer acquisition costs relative to physical retail. Hair Care remains structurally mature with consolidation around professional salon channels and medicated scalp treatments, whereas Specialty Stores capture disproportionate margin through experiential testing and consultant-guided selection.
The FDA oversees cosmetic safety through the Federal Food, Drug, and Cosmetic Act, while the EPA regulates antimicrobial claims and environmental release of rinse-off ingredients; in parallel, the EU enforces REACH substance restrictions and the MDR where products cross into medical-device territory, forcing reformulation cycles and documentation investments. China's SAMR and NMPA administer registration requirements for imported cosmetics and new ingredient filings, creating compliance thresholds that favor established multinationals with regulatory affairs infrastructure. Stakeholders must monitor divergence between U.S. fragrance allergen disclosure proposals and EU microplastic ban implementation timelines to anticipate supply chain reconfiguration needs.
Market Dynamics
The Personal Care Products Market is being fundamentally restructured by the EU Green Deal's chemical safety mandates, which are forcing wholesale reformulation of preservative systems and surfactant bases across multinational portfolios.
Growth Catalysts
- REACH substance restrictions:European regulatory pressure on parabens and microplastics is accelerating biotech-derived preservative adoption, creating first-mover advantages for clean-label formulators.
- Male grooming diversification:Men in South Korea and China are expanding routines beyond basic hygiene into specialized scalp treatments and barrier-repair moisturizers, opening premium price tiers.
- Fermentation-derived actives:Biotech platforms producing ceramides and peptides through microbial synthesis are reducing reliance on petrochemical feedstocks while improving batch consistency.
Market Restraints
- Palm oil supply concentration:Indonesia and Malaysia control over 85% of global sustainable palm kernel oil certification, exposing surfactant supply chains to El Niño-driven harvest volatility.
- SAMR registration timelines:China's National Medical Products Administration requires 12-18 month safety dossier reviews for new cosmetic ingredients, delaying product launches versus domestic competitors.
- Silicone substitution limits:Water-soluble alternatives to dimethicone in hair conditioning lack equivalent thermal protection performance, constraining clean-label claims in heat-styling segments.
Strategic Opportunities
- Rural India penetration:Tier-3 and Tier-4 cities remain underserved by dermatologist-tested skin care, with sachet-format distribution offering unit economics that match mass-market price elasticity.
- EU AI Act alignment:Automated skin diagnostic tools integrated with e-commerce platforms qualify for regulatory fast-tracking, enabling personalized serum formulation at scale.
- Subscription algorithmic personalization:Direct-to-consumer models using microbiome test kits to customize cleanser pH and active concentrations are compressing customer acquisition costs versus physical retail.
Industry Challenges
- Formulation chemist scarcity:Expertise in natural emulsification systems and cold-process manufacturing is concentrated among senior professionals in Basel and Osaka, constraining R&D expansion.
- Legacy ERP integration:Batch-level ingredient traceability required by EU Digital Product Passports conflicts with decades-old manufacturing execution systems at established facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care Products Market |
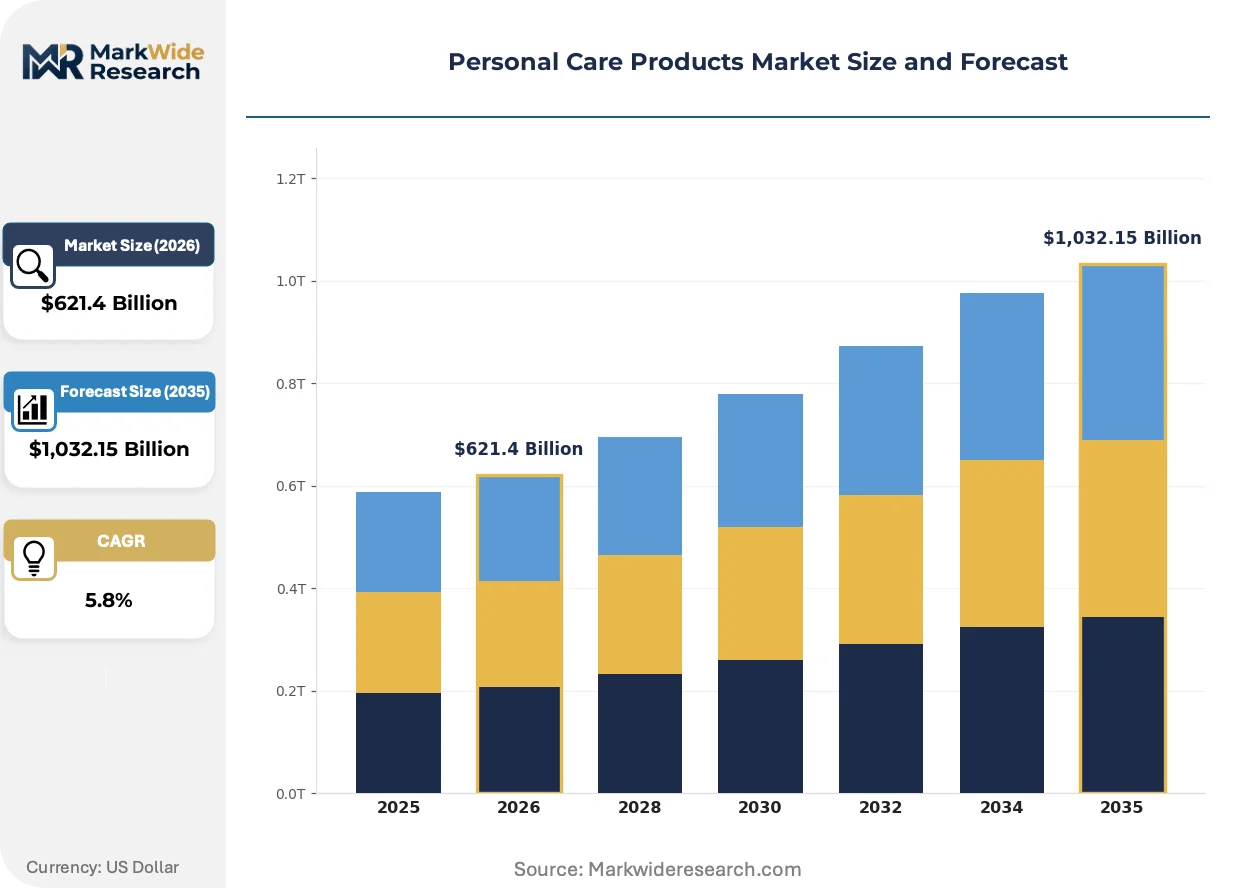
| Market Size in 2026 | $621.4 Billion |
| Market Size in 2035 | $1,032.15 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Care, Hair Care, Oral Care, Makeup Distribution Channel: Offline Stores, E-commerce, Supermarkets, Specialty Stores End User: Women, Men, Children, Seniors Packaging Type: Tube, Pump, Jar, Spray |
| Companies Covered | L'Oréal S.A., Procter & Gamble Company, Unilever PLC, The Estée Lauder Companies, Johnson & Johnson, Beiersdorf AG, Colgate-Palmolive Company, Kao Corporation, Shiseido Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care Products Market Strategic Shifts
Biotechnology is dissolving the boundary between cosmetic and pharmaceutical efficacy claims, as precision fermentation yields active concentrations that challenge traditional extraction economics.
Biotech-derived ceramides produced through microbial fermentation are decomposing the cost structure of premium barrier-repair moisturizers. Korean beauty brands and dermatology clinics in Seoul are adopting these actives at 3x the pace of North American mass-market lines. The technology is decomposing the historical price premium associated with plant-derived identical molecules, forcing extraction-based suppliers to reposition on provenance narratives rather than performance parity.
REACH microplastic restrictions scheduled for enforcement across EU member states are eliminating polyethylene microbeads and acrylate copolymers from rinse-off formulations. Manufacturers serving the German and French markets are accelerating investment in biodegradable cellulose and mineral alternatives, with professional exfoliation products facing the most acute reformulation timelines. The regulation is compressing SKU portfolios as brands consolidate around compliant base formulations rather than maintaining parallel product architectures.
Algorithmic skin assessment tools embedded in mobile commerce platforms are redirecting purchase decisions from brand loyalty toward diagnostic-driven matching. Chinese consumers on domestic super-apps are accepting camera-based moisture and sebum analysis as gatekeepers to product recommendation, displacing influencer-driven discovery. The behavioral shift is most pronounced among consumers aged 25-34 in Shanghai and Shenzhen, where dermatological credibility now outweighs heritage brand equity in serum and essence categories.
Personal Care Products Market Segmentation
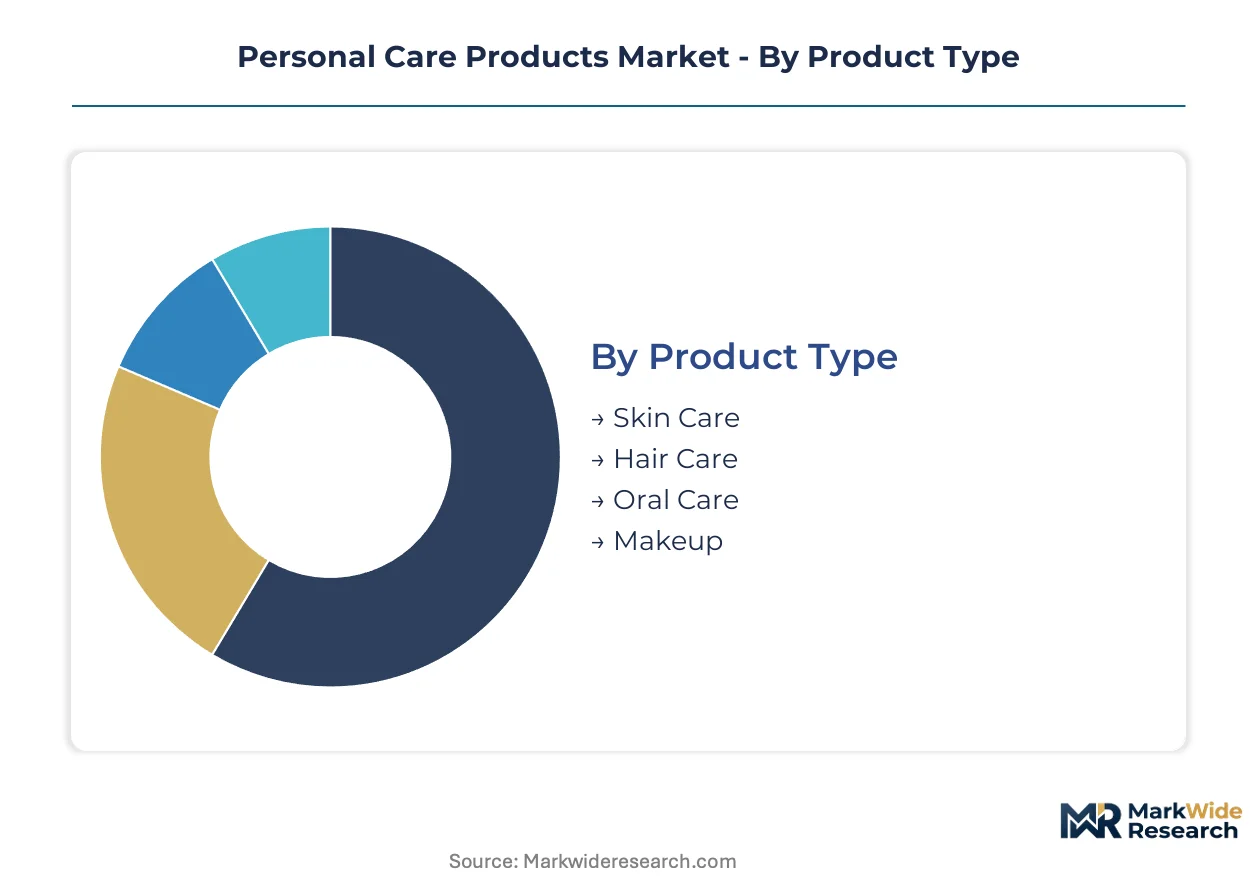
Personal care manufacturers configure their portfolios around four intersecting dimensions that determine pricing power and channel access. Product chemistry and distribution format together shape margin capture, while end-user targeting and packaging engineering influence repeat purchase frequency and brand loyalty economics.
Product Type:
Margin pools concentrate in formulations requiring clinical validation and repeat application cycles, with barrier-repair and anti-aging chemistry commanding sustained premium pricing.
- Skin Care:Emulsions and serums containing ceramides, peptides, and fermentation-derived actives at 0.5-15% concentrations target barrier repair and photodamage reversal. Demand clusters in China's tier-1 cities where dermatologist endorsement outweighs heritage brand equity, and in Seoul's clinic-adjacent retail channels where precision formulations for East Asian skin biology attract premium pricing.
- Hair Care:Shampoos, conditioners, and scalp treatments incorporate surfactant bases and silicone alternatives for thermal protection. Procurement is shifting toward professional salon channels in Germany and medicated scalp solutions in South Korea, where male grooming diversification into specialized treatments is opening new price tiers.
- Oral Care:Dentifrices and mouth rinses with antimicrobial claims fall under EPA environmental release regulations and FDA safety oversight. Mass-market penetration remains highest in India's rural distribution networks through sachet formats.
- Makeup:Color cosmetics with skincare hybrid positioning leverage biotech-derived pigments and clean-label preservative systems. EU REACH microplastic restrictions are forcing reformulation of long-wear foundations and exfoliating primers.
The dominant share belongs to Skin Care, while Hair Care is closing the gap fastest through professional channel premiumization and male-specific line extensions.
Distribution Channel:
Customer acquisition cost structures diverge sharply between physical and digital touchpoints, with algorithmic personalization compressing online spend efficiency relative to shelf-space rental economics.
- Offline Stores:Department store beauty halls and drugstore chains rely on consultant-guided selection and experiential testing to justify premium positioning. L'Oréal S.A. and Shiseido Co., Ltd. anchor European and Asian flagship locations with dermatological credibility displays.
- E-commerce:Direct-to-consumer platforms deploy subscription models and microbiome test kits for customized cleanser pH and active concentration matching. Chinese super-apps integrate camera-based moisture analysis, displacing influencer-driven discovery among Shanghai consumers aged 25-34.
- Supermarkets:Mass-market velocity depends on manufacturing scale and slotting fee negotiations. Procter & Gamble Company sustains dominance through North American retail shelf-space control.
- Specialty Stores:Sephora and Ulta Beauty capture disproportionate margin through exclusive launches and loyalty program data harvesting. Korean beauty retailers in Seoul adopt fermentation-derived ceramides at triple the pace of mass-market lines.
Offline Stores retain the largest transaction volume, yet E-commerce is expanding most quickly as regulatory fast-tracking under the EU AI Act rewards automated skin diagnostic integration.
End User:
Demographic targeting determines formulation complexity and marketing spend allocation, with gender-specific line extensions multiplying SKU counts while improving price elasticity management.
- Women:Multi-step routines spanning 5-12 products per regimen drive the highest absolute revenue and repeat purchase frequency. Anti-aging serums and barrier-repair moisturizers attract premium pricing in Japan and France.
- Men:Grooming diversification beyond basic hygiene into specialized scalp treatments and barrier-repair moisturizers is accelerating fastest in South Korea and China, where domestic brands capture share through localized innovation.
- Children:Hypoallergenic formulations with minimal preservative loads target parental safety concerns. EU Green Deal chemical safety mandates tighten ingredient disclosure requirements for pediatric claims.
- Seniors:Thinning skin and reduced barrier function drive demand for lipid-rich emollients and gentle cleansing systems. Japan's aging population supports sustained R&D investment from Shiseido's biotech platforms.
Women command the dominant revenue share, while Men represent the steepest expansion trajectory as grooming ritual complexity converges with female-category sophistication.
Packaging Type:
Engineering choices affect formulation stability, dosing precision, and sustainability credentials, with airless systems and mono-material designs commanding engineering premiums.
- Tube:Laminated or mono-material squeeze formats dominate mass-market hair care and oral care, with aluminum-barrier laminates preserving oxidative-sensitive actives in retinol creams.
- Pump:Airless dispensing systems protect biotech-derived peptides and fermentation ceramides from degradation, justifying premium positioning in German and French dermocosmetic lines.
- Jar:Wide-mouth glass and post-consumer recycled plastic containers signal luxury positioning for rich balms and sleeping masks, though finger-dip contamination risks require robust preservative systems.
- Spray:Fine-mist and continuous-spray formats serve thermal protection and setting products, with compressed-air alternatives to hydrocarbon propellants advancing under EPA volatile organic compound regulations.
Pump formats claim the highest value-per-unit, while Tube packaging maintains volume leadership through emerging market affordability requirements and sachet-to-tube upgrade paths.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished personal care formulations to Southeast Asian markets while Germany ships specialty surfactants and preservative systems to European Union member states. Trade corridors concentrate active ingredient flows from Swiss and French biotech clusters toward Asian manufacturing hubs.
China
Domestic brands capture share through localized innovation and digital-first distribution models targeting tier-1 cities. SAMR and NMPA administer 12-18 month registration timelines for imported cosmetics, favoring established multinationals with regulatory infrastructure. Shanghai and Shenzhen host algorithmic skin diagnostic platforms that displace influencer-driven discovery among consumers aged 25-34.
United States
Mass-market velocity depends on manufacturing scale and shelf-space control across North American retail channels. FDA oversees cosmetic safety through the Federal Food, Drug, and Cosmetic Act while EPA regulates antimicrobial claims and environmental release of rinse-off ingredients. Greater Boston and New Jersey corridor concentrate formulation chemistry expertise serving dermatologist-tested tier upgrades.
Germany
Professional salon channels and medicated scalp treatments drive procurement shifts toward premium hair care segments. REACH substance restrictions on parabens and microplastics accelerate biotech-derived preservative adoption, creating first-mover advantages for clean-label formulators. BASF and Evonik clusters in Ludwigshafen supply fermentation-derived ceramides to European dermocosmetic lines.
South Korea
Male grooming diversification beyond basic hygiene into specialized scalp treatments and barrier-repair moisturizers accelerates fastest in Seoul. MFDS regulates cosmetic safety while clinic-adjacent retail channels adopt fermentation-derived ceramides at triple the pace of North American mass-market lines. Gangnam district anchors dermatology clinic retail integration.
India
Tier-3 and Tier-4 cities remain underserved by dermatologist-tested skin care, with sachet-format distribution offering unit economics matching mass-market price elasticity. FSSAI and BIS administer safety standards while CDSCO oversees cosmetic ingredient notifications. Maharashtra and Gujarat manufacturing clusters supply affordable tube and sachet packaging formats.
Personal Care Products Market Competitive Environment
Listed leaders compete with private specialists across formulation complexity and channel access dimensions. The market exhibits tiered concentration with multinational conglomerates anchoring mass-market shelf space while regional specialists capture premium positioning through clinical validation. Three archetypes dominate: dermatology-heritage science brands, scale-driven FMCG conglomerates, and biotech-enabled precision formulators. Competitive moves concentrate on M&A for ingredient technology access and strategic partnerships for microbiome testing platform integration.
Within the dermatology-heritage tier, L'Oréal S.A. and Shiseido Co., Ltd. exemplify positioning anchored in scientific credibility across European and Asian markets. Procter & Gamble Company occupies the scale-driven archetype with manufacturing execution systems supporting North American retail dominance. These three entities represent the competitive spectrum from clinical validation premium capture to mass-market velocity optimization.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Procter & Gamble Company |
| Unilever PLC |
| The Estée Lauder Companies |
| Johnson & Johnson |
| Beiersdorf AG |
| Colgate-Palmolive Company |
| Kao Corporation |
| Shiseido Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
EU REACH substance restrictions gate both raw material qualification and price differentiation simultaneously, forcing manufacturers to absorb compliance costs into premium tier positioning while mass-market lines face margin compression from reformulation investments.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for surfactant and preservative base chemicals, with pricing stratifies across premium, standard, and economy tiers driven by certification level (REACH-compliant vs. legacy formulations) and volume scale. Cost compression in mass-market hair care intensifies because Indonesian and Malaysian palm kernel oil suppliers command harvest volatility premiums during El Niño cycles. Professional salon channels exhibit least price sensitivity due to patient reimbursement adjacency and clinician endorsement value.
Supply Chain Analysis
Just-in-time inventory preferences dominate fermentation-derived active ingredient procurement from Swiss and French biotech clusters, while strategic stockpiling characterizes surfactant bases ahead of EU microplastic enforcement timelines. Supply concentrates in Indonesia and Malaysia for palm derivatives, China for packaging components, and Germany for specialty surfactants. Raw material dependencies span palm kernel oil, fermentation feedstocks, and aluminum-barrier laminates. Single-source vulnerability runs through Indonesian sustainable certification bodies. Distribution runs through professional salon channels in Seoul and Gangnam clinic-adjacent retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal chemical safety mandates constitute a regulatory inflection that accelerates biotech-derived ingredient substitution and compresses legacy formulation margins across the analysis window.
For Market Incumbents: Compound dermatological science credibility through backward integration into fermentation-derived ceramide production, securing supply certainty as REACH restrictions tighten. Expand airless pump manufacturing capacity in Ludwigshafen to capture premium positioning in German and French dermocosmetic lines. Channel control through exclusive clinic-retail partnerships in Seoul defends against domestic Chinese brands capturing algorithmic personalization share. For New Entrants and Emerging Players: Anchor in tier-3 and tier-4 Indian cities where dermatologist-tested skin care penetration remains minimal and sachet-format unit economics match mass-market price elasticity. Target male grooming diversification in South Korea through specialized scalp treatment formulations. Deploy microbiome test kit integration for direct-to-consumer subscription models, compressing customer acquisition costs versus physical retail shelf-space negotiations. For Investors and Strategic Acquirers: EU AI Act alignment for automated skin diagnostic tools reshapes the acquisition landscape toward platforms qualifying for regulatory fast-tracking. Five-to-ten year viability favors precision formulators with captive biotech fermentation capacity over extraction-dependent suppliers repositioning on provenance narratives. Monitor NMPA registration timeline compression as signal for Chinese domestic brand valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive ceramide production insulates margin from REACH-driven petrochemical substitution costs. |
| EU AI Act Diagnostic Platform Certification | Automated skin assessment tools unlock algorithmic personalization at scale in Shanghai and Shenzhen. |
| Sachet-to-Tube Packaging Upgrade Path | Unit economics in rural India match mass-market elasticity while building brand loyalty. |
| Clinic-Adjacent Retail Channel Expansion | Gangnam dermatology integration commands triple the adoption pace of mass-market lines. |
| Microbiome Test Kit Subscription Integration | Direct-to-consumer models reduce acquisition costs versus Sephora and Ulta shelf-space rental. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and retail audit data, combining interviews with formulation chemists, regulatory affairs leads at multinationals, professional salon procurement managers, and biotech platform R&D directors. Secondary sources span ECHA REACH substance databases, SAMR cosmetic registration records, NMPA ingredient filing disclosures, and Nielsen retail velocity data. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates across the analysis window.
Segmentation dimensions modeled include product chemistry tier, distribution channel format, end-user demographic, and packaging engineering specification across the projection horizon. CAGRs derive from regression against historical volume trajectories, regulatory implementation timelines, and channel shift elasticity parameters. Industry-specific forecast inputs incorporate fermentation capacity expansion schedules and clinic-retail channel penetration curves in Seoul and Shanghai.
Decision-makers should treat outputs as directional under base assumptions of sustained REACH enforcement and stable palm oil harvest yields; material deviation in El Niño intensity or NMPA registration acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as EU microplastic ban implementation timelines and Chinese domestic brand capture rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Intensive Conditioner Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Brazil Dermocosmetics Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Makeup Brush and Tool Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Asia-Pacific Beauty and Personal Care Products Market
Beauty & Personal Care
Hair Straightener Market
Beauty & Personal Care
Makeup Setting Spray Market